

A strategic technology, infrastructure, cybersecurity, defence and societal assessment
Geographic and analytical scope: Global telecommunications transformation, with particular attention to the United States, China, the European Union, Italy, France, Germany and the United Kingdom; the transition from advanced 5G to AI-native 6G; and the industrial, military, medical, economic and societal consequences through 2031.
Executive Summary — Bottom Line Up Front
The strategic significance of AI-RAN extends beyond accelerating mobile networks. It concerns the potential transformation of telecommunications infrastructure into a geographically distributed computing system capable of supporting connectivity, artificial intelligence, real-time sensing and automated decision-making within a common infrastructure.
On 21 October 2026, NVIDIA, Nokia and T-Mobile announced the completion of an AI-RAN call on T-Mobile’s operational 5G network in Bellevue, Washington. Conventional commercial user equipment, Nokia Massive MIMO radios, Nokia’s CUDA-accelerated anyRAN software and NVIDIA Aerial RAN Computer infrastructure were used with the existing 5G Standalone core. The achievement establishes an important commercial-network integration milestone, but does not yet demonstrate production-scale economic superiority, sustained multi-workload performance or autonomous 6G functionality.
The industrial consequences could be substantial. Telecommunications operators possess distributed sites, fibre connections, radio spectrum, operational infrastructure and established customer relationships. Accelerated computing could allow selected parts of those networks to become edge-computing platforms rather than remaining exclusively connectivity assets.
Three dimensions will determine the success or failure of this transition:
- Technological viability: whether AI acceleration improves radio efficiency, reliability and service performance without compromising deterministic telecommunications workloads.
- Economic sustainability: whether the additional revenue and operational benefits justify GPU investments, electricity consumption, cooling, fibre upgrades and system complexity.
- Strategic sovereignty: whether countries and operators retain effective control over the hardware, software, AI models, orchestration systems and data that underpin essential communications.
The geopolitical consequences are equally important. The competitive boundaries between semiconductor manufacturers, telecommunications equipment vendors, cloud providers, AI developers and network operators are beginning to converge. The strategic dependence previously concentrated in mobile radio equipment could extend into GPU ecosystems, AI toolchains, model governance and accelerator supply chains.
The next decisive phase is expected during 2027–2029, when field trials, performance measurement, commercial economics and early 6G standardisation should provide stronger evidence of which architectures are viable. For governments, the immediate priority is not premature deployment of autonomous infrastructure but the creation of systems that can be independently secured, audited, recovered and governed.
AI-RAN and the Battle for 6G: Who Will Own the Intelligence Behind the Network?
The convergence of telecommunications and artificial intelligence threatens to shift industrial power from mobile operators to semiconductor and software platforms. Europe has the radio expertise to compete, but its investment constraints and dependence on external computing technology could leave it financing infrastructure whose most valuable functions it does not control.
The decisive question raised by the AI-RAN breakthrough of 21 October 2026 is not whether artificial intelligence can operate inside a commercial mobile network, but who will control the computing infrastructure on which future communications depend. NVIDIA, Nokia and T-Mobile have demonstrated that radio processing can run on AI-accelerated servers within an operational 5G network. The result opens a new contest over semiconductor supply, software ownership, network investment and national security. For Europe, the contradiction is immediate: its telecommunications manufacturers retain world-class radio engineering capabilities, while much of the advanced computing ecosystem needed to exploit them is controlled elsewhere. Unless operators can convert this technological transition into sustainable revenues and enforceable control over critical systems, the evolution towards 6G risks transferring industrial value away from the companies and countries financing the networks.
The Bellevue call changes the industrial equation, not the economics of 5G
The 21 October 2026 demonstration in Bellevue, Washington, established a specific engineering result: Nokia’s 5G anyRAN software, Massive MIMO radio equipment and NVIDIA Aerial RAN Computer infrastructure operated with T-Mobile’s existing 5G Standalone core and commercial user equipment. The achievement matters because it moved accelerated radio processing into an operational network environment rather than confining it to an isolated laboratory. It did not establish that an entire national network can operate more cheaply on GPUs, that AI has doubled spectral efficiency or that telecommunications-grade reliability can be maintained indefinitely while radio and commercial inference applications compete for computing resources. Nokia identified further field validation as the next stage. The distinction between a successful technical integration and an economically sustainable deployment is precisely where the next contest begins.
The architectural change is substantial. In conventional telecommunications procurement, mobile operators acquire radio equipment, baseband processing and network software through relationships dominated by specialised infrastructure suppliers. Under AI-RAN, selected radio functions can execute on accelerated computing platforms that may also support artificial intelligence services. This introduces semiconductor designers, accelerator software environments and server manufacturers into decisions previously governed principally by radio engineering. NVIDIA’s October 2026 announcement identified MGX 2U and MGX 4U Aerial RAN Computer configurations using RTX PRO 6000 Blackwell Server Edition accelerators, with Dell Technologies, Quanta Cloud Technology and Supermicro participating in the server ecosystem. Nokia remains responsible for critical radio capabilities, but a greater share of the system’s performance and commercial value may depend on the computing platform beneath them.
The result could redistribute bargaining power. Telecommunications operators possess spectrum rights, network sites and established customer relationships, but NVIDIA’s CUDA ecosystem may influence how software is developed and optimised. A network function that technically supports multiple computing architectures is not necessarily economical to migrate between them. Portability depends on the cost of rewriting or adapting software, preserving performance and maintaining uninterrupted service. If those costs become prohibitive, ownership of physical telecommunications infrastructure will provide less commercial independence than it appears to. The emerging question for operators is whether AI-RAN creates a new source of revenue or a new category of supplier dependence.
The numbers expose the distance between technological ambition and financial capacity
The economic evidence remains narrower than the industrial announcements suggest. Nokia and Deutsche Telekom reported typical 10–15% uplink throughput improvements in laboratory work involving AI-based channel estimation, with stronger results under selected difficult radio conditions. Nokia also presented an ambition in July 2026 to achieve more than 100% spectral-efficiency gains by 2028 through its AI-native radio platform. These figures measure different things. The first is a reported result for a specific technique under laboratory conditions; the second is a forward-looking vendor objective. Neither establishes a doubling of commercial network capacity, a proportional reduction in capital expenditure or a verified improvement in the financial performance of a mobile operator.
France illustrates the investment problem. ARCEP reported 28.1 million fibre subscriptions at the end of June 2026, representing approximately 85% of fixed internet subscriptions, alongside 37.5 million SIM cards active on 5G networks. Average mobile data consumption reached 19.3 GB per customer per month in the second quarter. Yet telecommunications retail revenue stood at approximately €9.1 billion excluding tax in that quarter, declining 1.3% year on year. Operator and mobile-infrastructure investment amounted to approximately €10.3 billion in 2025, excluding spectrum expenditure, a reduction of about 15% from the previous year. Network usage and technological sophistication are advancing while the sector’s financial capacity remains under pressure. AI-RAN cannot resolve that imbalance merely by adding more powerful equipment to the balance sheet.
The discrepancy between technological demand and investment capacity is not confined to France. The European Commission announced €116 million for 20 additional 6G research projects in March 2026, within a Smart Networks and Services Joint Undertaking research portfolio associated with approximately €630 million in EU funding. The wider undertaking envisages at least €1.8 billion over 2021–2027, combining a €900 million EU contribution with industry participation. Separately, the Commission’s July 2026 AI Gigafactories initiative envisaged up to €10 billion in public support and at least €20 billion in expected private investment. These are materially different financial categories: research allocations, programme commitments, announced computing initiatives and commercial telecommunications expenditure. Treating them as one European 6G investment envelope would conceal the central problem. Public funding can support research and computing capacity without guaranteeing that European operators possess the capital or customer demand to deploy profitable AI-native networks.
Europe risks supplying the radio expertise while importing the computing architecture
The United States has begun treating AI-native telecommunications as an industrial-policy issue. On 10 March 2026, the National Telecommunications and Information Administration announced a proposed redirection of the Public Wireless Supply Chain Innovation Fund towards AI-native radio access technologies. Its stated objectives linked wireless innovation with American AI leadership and supply-chain resilience. The announcement did not establish completed funding awards under the revised approach, but it identified the strategic interest: telecommunications infrastructure represents another potential market for American computing platforms and software.
China has organised its response through a different mechanism. In June 2026, the Ministry of Industry and Information Technology launched a central-provincial programme coordinating telecommunications operators, equipment manufacturers, regional authorities and research institutions around 6G technologies, with objectives extending to 2029. China had reported more than 4.8 million 5G base stations and over 1.2 billion 5G users in January 2026. In May, the ministry authorised experimental use of the 6 GHz band for selected 6G research activities. These figures do not establish Chinese leadership in commercial 6G, but they indicate the scale of the domestic infrastructure and administrative coordination available to support research, experimentation and industrial development.
Europe’s position is more fragmented. Nokia and Ericsson provide major telecommunications engineering capabilities, while European operators control commercially important infrastructure. Yet the transition towards accelerated radio processing introduces dependence on computing hardware, software libraries and semiconductor supply chains beyond the traditional telecommunications equipment market. European sovereignty cannot therefore be measured only by the nationality of the company supplying a radio unit. It depends on who controls the computing execution environment, security updates, model management and practical replacement options when technologies or commercial relationships change.
Italy, France, Germany and the United Kingdom demonstrate why a uniform European response would be insufficient. NVIDIA identified TIM and Fastweb + Vodafone among participants in its wider accelerated-infrastructure ecosystem, but that does not establish nationwide Italian AI-RAN deployment. Orange is testing accelerated radio and distributed AI applications. Deutsche Telekom and Nokia have reported laboratory results and planned further field activity in 2027. BT has announced an operational-network trial in Birmingham for 2027. These initiatives occupy different stages of maturity, and none proves that accelerated infrastructure already delivers a superior national investment model. The common requirement is not identical deployment schedules, but interoperable procurement and the ability to retain meaningful operational control.
Germany’s industrial base may provide a particularly demanding market for integrated communications and computation, where machine vision, robotics and production monitoring require predictable services. France possesses extensive fibre infrastructure but faces shrinking telecommunications investment. Italy must reconcile industrial applications with operator financing constraints and existing spectrum obligations. The United Kingdom can exploit cloud-native experimentation while addressing its own resilience and supplier-governance requirements. These differences are commercially material: infrastructure that earns a return in a densely connected industrial installation may be uneconomic at a rural mobile site with limited computing demand. European coordination can reduce fragmentation in standards and security, but it cannot abolish national differences in infrastructure cost or customer demand.
Regulation can protect the network without restoring Europe’s industrial position
The European Union’s regulatory framework addresses important parts of the emerging risk but does not constitute an industrial strategy by itself. Directive (EU) 2022/2555, the NIS2 Directive, establishes cybersecurity risk-management and significant-incident reporting obligations for covered entities, including relevant electronic communications providers. Regulation (EU) 2024/1689, the AI Act, establishes requirements for AI systems according to their intended purpose and classification. An AI-assisted radio optimisation function does not automatically become a high-risk AI system simply because it operates inside a critical network. The classification depends on the specific function and applicable provisions. The distinction matters because telecommunications cybersecurity, medical-device safety, industrial automation and AI governance impose different obligations on systems that may eventually share the same computing infrastructure.
The attack surface is expanding faster than any single regulatory category can describe. ENISA’s February 2022 assessment of network-function virtualisation identified 60 security challenges across seven categories and proposed 55 best practices. AI-native infrastructure adds accelerator firmware, privileged software environments, model provenance and autonomous management agents to this earlier virtualisation problem. A compromised commercial inference application should not be able to interfere with time-critical radio processing; an automated management agent should not be able to modify protected configurations without defined authority. The financial advantage of resource sharing must therefore be tested against the cost of isolation, redundancy, monitoring and recovery. A system that saves server capacity while increasing the probability or consequences of a regional outage has not demonstrated an economic advantage for essential infrastructure.
The European Commission’s Digital Networks Act proposal of January 2026 addresses the fragmentation and investment conditions of European connectivity markets. Its eventual relevance will depend on the legislative process and implementation, not on the proposal’s announcement alone. The underlying conflict is difficult to avoid: operators seek scale and lower regulatory costs, public authorities must preserve competition and service obligations, and national governments require control over critical communications. At the same time, the commercial value of AI-native infrastructure may increasingly accumulate in software and semiconductor ecosystems outside the traditional jurisdiction of telecommunications regulators. Regulation can reduce vulnerability and improve market conditions, but it cannot independently create a competitive European accelerator platform or guarantee that new infrastructure produces profitable services.
NATO’s digital ambitions increase the importance of civilian infrastructure resilience
The security implications extend beyond commercial cybersecurity. NATO’s Alliance Digital Strategy of January 2026 and Digital Transformation Implementation Strategy 2.0 of May 2026 identify secure data exchange, distributed computing, interoperability and digital resilience among the Alliance’s priorities. The proposed Digital Backbone and Alliance Data Sharing Ecosystem reflect the growing importance of connecting information, computing and operational systems across national boundaries. Commercial AI-RAN could provide useful technologies for selected applications, but a successful call on T-Mobile’s network does not demonstrate performance under electronic warfare, infrastructure attack, classified-data requirements or deliberate communications disruption.
The strategic danger is to confuse distributed computational capacity with protected military capability. Commercial networks may support logistics, emergency coordination and selected forms of information processing, but military systems must retain appropriate independence under hostile conditions. Dependence on external software support, inaccessible accelerator components or shared computing facilities could become significant during a geopolitical crisis. The same concern applies to hospitals, electricity networks and emergency services relying on nearby AI processing. Their essential functions must remain available when the computing environment fails or when lower-priority commercial workloads are suspended. For NATO members, national resilience increasingly depends on understanding these civilian technological dependencies before they become embedded in operational plans.
The next two years will determine who absorbs the cost of delayed decisions
Between October 2026 and October 2028, the decisive evidence should come from operator field trials, production-scale performance measurements, procurement decisions and the continuing ITU IMT-2030 and 3GPP standardisation processes. BT’s planned Birmingham trial and Deutsche Telekom’s expected 2027 field activity will be relevant not because additional demonstrations settle the investment case, but because they can expose the operating costs, workload conflicts and recovery requirements obscured by laboratory performance claims. Governments and operators should demand comparable evidence of total cost of ownership, energy consumption, supplier portability and service continuity before treating accelerated computing as the default architecture for national mobile networks.
The cost of inaction will not fall equally. European operators risk investing in computing systems whose commercial returns are captured elsewhere; equipment manufacturers risk retaining radio expertise while losing influence over the software platforms governing future networks; and governments risk allowing supplier dependence to become entrenched before procurement safeguards are established. Industrial customers and public services may ultimately pay through higher infrastructure charges, restricted supplier choice or less resilient connectivity. Conversely, premature nationwide deployment could leave shareholders and consumers financing expensive accelerators without sufficient demand for the services they are intended to provide.
The choice facing European governments over the next 12–24 months is therefore narrower and more demanding than the rhetoric surrounding 6G suggests. They must decide how research funding, telecommunications regulation and public procurement can preserve industrial participation without underwriting unproven business models. Operators must decide where accelerated processing delivers a measurable return and where specialised infrastructure remains preferable. Suppliers must demonstrate interoperability beyond contractual promises. By October 2028, the relevant measure of progress will not be how many companies have announced AI-RAN partnerships, but how many deployments can show reliable communications, sustainable economics and practical independence from non-substitutable computing platforms. The financial cost of failing that test will remain with the operators, industries and public authorities responsible for keeping the network operational.
Navigational Index
Pillar I — The Technological and Infrastructural Transformation
Chapter 1 — From Conventional 5G to AI-RAN: The New Architecture of Telecommunications
The development of centralised and virtualised radio networks; GPU-accelerated baseband processing; Nokia anyRAN; NVIDIA Aerial RAN Computer; Massive MIMO; fronthaul and transport networks; orchestration; edge-cloud integration; and the technical meaning of the Bellevue commercial-network milestone.
Chapter 2 — The Engineering Economics of Intelligent Connectivity
AI-for-RAN, AI-and-RAN and AI-on-RAN; dynamic spectrum management; uplink channel estimation; signal processing; resource allocation; latency; computing density; shared workloads; electricity; cooling; capital investment; site engineering; and the conditions determining commercial scalability.
Chapter 3 — From AI-RAN to 6G: Standards, Physical AI and the Network of 2030
3GPP Releases 20 and 21; ITU IMT-2030; integrated sensing and communications; native AI; terrestrial and non-terrestrial connectivity; programmable radio functions; interoperability; and the progression from experimental architectures to globally standardised systems.
Pillar II — Cybersecurity, National Security and Societal Transformation
Chapter 4 — Cybersecurity and the New Attack Surface of AI-Native Infrastructure
GPU and hypervisor vulnerabilities; shared-compute isolation; adversarial machine learning; model poisoning; data exfiltration; software supply-chain compromise; autonomous-agent security; zero-trust operations; network segmentation; resilience; and incident containment.
Chapter 5 — Defence, Intelligence and Geopolitical Power
Military communications; distributed intelligence processing; autonomous systems; electronic warfare; protected national infrastructure; operational resilience; foreign technology dependence; dual-use controls; NATO interoperability; and the relationship between commercial AI-RAN infrastructure and national defence capabilities.
Chapter 6 — Healthcare, Industry, Transport, Energy and the Connected Society
Telemedicine, clinical AI, industrial robotics, intelligent manufacturing, automated transport, critical utilities, agricultural systems, emergency services, urban infrastructure, education, labour-market transformation, civil rights and the social risks of pervasive network intelligence.
Pillar III — Global Competition, European Sovereignty and the 2031 Outlook
Chapter 7 — The Global Strategic Competition for AI-Native Telecommunications
The United States, China, Japan, South Korea and Europe; semiconductor ecosystems; industrial policy; infrastructure financing; spectrum governance; cloud competition; standards diplomacy; technological concentration; and international dependencies.
Chapter 8 — Italy, France, Germany and the United Kingdom: Four Different Paths to Network Sovereignty
National operator strategies, industrial capabilities, regulatory institutions, energy constraints, digital infrastructure, cybersecurity priorities, military implications, research institutions and national competitiveness within the European framework.
Chapter 9 — The Economics and Governance of 6G, 2027–2031
Investment scenarios, procurement strategies, industrial bottlenecks, technological risks, regulatory choices, sustainability, skills, competition and the evolving distribution of value between operators, semiconductor companies and software platforms.
Chapter 10 — Strategic Scenarios, Early-Warning Indicators and Government Policy Options
Alternative adoption pathways; measures of technical and commercial readiness; sovereignty requirements; security conditions for critical deployment; European industrial coordination; public-private infrastructure strategies; and a final assessment of the future global telecommunications order.
Master Abstract
The emergence of a new infrastructure paradigm
The telecommunications industry is approaching a structural transition in which the boundaries separating radio communications, high-performance computing and artificial intelligence are becoming less rigid. The traditional mobile network was engineered primarily to transmit information with predictable performance over licensed radio spectrum. The emerging AI-RAN model introduces a different proposition: parts of the same distributed infrastructure that process radio signals could also execute AI workloads, allowing a mobile network to function simultaneously as a communications system and a geographically distributed computing platform.
The Bellevue trial represents the first important commercial-network evidence for this particular implementation. It did not replace the entire mobile system with artificial intelligence. The antennas, radio functions, transport connectivity and existing 5G core retained essential roles. What changed was the computing architecture used to execute radio-access software. This distinction is central to understanding both the achievement and its limitations. A programmable GPU platform may be able to support AI algorithms for radio optimisation and, where capacity permits, inference workloads serving nearby devices. Yet demonstrating these possibilities in an operationally sustainable network requires significantly more evidence than establishing a successful call.
The strategic question is therefore not whether AI-RAN can process a radio call. The commercial-network experiment has provided evidence that it can. The harder question is whether shared accelerated computing can operate under telecommunications-grade reliability requirements while offering a convincing improvement in total economic value. Network processing involves deadlines that cannot simply be postponed when an AI application consumes additional resources. Priority enforcement, accelerator partitioning, predictable processing latency, capacity reservation and rapid fault recovery become central engineering requirements.
Artificial intelligence becomes part of infrastructure, not merely an application
This transformation has three distinct technological dimensions. Artificial intelligence can optimise the radio network, improving decisions concerning channel estimation, resource allocation, interference management and network configuration. The network and AI applications can share computing infrastructure, potentially increasing the utilisation of expensive hardware. Finally, operators can provide distributed AI services through facilities already connected to their communications networks.
The economic implications differ substantially across these three categories. Better radio efficiency may increase the useful capacity of existing spectrum. Shared computing may reduce duplicate infrastructure in selected operating environments, but only if real workload utilisation exceeds the overhead associated with coordination and resource reservation. Edge AI services may generate new revenues, although those revenues depend on applications for which proximity, data locality, responsiveness or service continuity create measurable value. None of these benefits should be treated as automatically established by the Bellevue demonstration.
There is early quantitative evidence for some narrower improvements. Nokia reported that laboratory work with Deutsche Telekom on AI-based uplink channel estimation produced typical throughput improvements of 10–15%, with larger gains under more complex radio conditions. This is an attributed laboratory result for a specific technique, not a commercial-network-wide efficiency improvement, and it cannot be translated directly into equivalent financial savings or user-experienced performance.
The transition to 6G is already influencing industrial architecture
AI-RAN should also be understood within the international evolution towards sixth-generation mobile communications. ITU’s IMT-2030 framework identifies six principal usage scenarios: immersive communications, hyper-reliable low-latency communications, massive communications, ubiquitous connectivity, artificial intelligence and communications, and integrated sensing and communications. In 2026, ITU working groups advanced technical requirements and evaluation methods for candidate 6G radio technologies. These remain part of an ongoing standards-development process rather than evidence that commercial 6G systems are already available.
The inclusion of sensing and artificial intelligence matters because it changes what policymakers may eventually expect from a network. Telecommunications infrastructure could become a platform for interpreting environmental information, coordinating robotic equipment, supporting industrial automation and delivering AI inference closer to the point where data is generated. Such capabilities could be valuable for manufacturing, healthcare, transport and emergency response, but their practical implementation will depend on application-specific safety engineering, spectrum conditions, compute availability and governance.
This new architecture is also a potential instrument of geopolitical power. If national communications capacity becomes increasingly dependent on specialised accelerators, proprietary software environments and globally concentrated semiconductor production, communications sovereignty will no longer be determined primarily by who owns antennas and licences. It will also depend on who controls the computing environment, software updates, AI models, cryptographic credentials, operational telemetry and infrastructure-management systems.
Security and sovereignty become inseparable from engineering design
The introduction of shared computing expands the number of technical components and institutional actors upon which a communications network depends. An AI inference process and a time-critical radio function may execute on hardware belonging to the same infrastructure, while relying on different software components, operational teams and potentially customers. This creates additional security boundaries between critical communications, commercial services and automated management systems.
The European Union Agency for Cybersecurity has already identified extensive security issues associated with virtualised 5G infrastructure. In its 2022 assessment, ENISA examined 60 security challenges across seven categories and identified 55 technical, policy and organisational best practices. That analysis concerned network-function virtualisation rather than the complete AI-RAN architecture now emerging, but it provides an important foundation for assessing the security consequences of shared computing in telecommunications.
Future security controls must address not only familiar risks such as unauthorised access and software compromise, but also corrupted AI models, malicious training data, unsafe orchestration commands, compromised accelerator firmware and the consequences of contention between critical radio workloads and lower-priority applications.
The stakes are particularly high for infrastructure supporting hospitals, defence organisations, transport systems, financial services and emergency communications. These sectors will require evidence of fault isolation, service continuity, data protection and recoverability before shared AI-RAN platforms can be considered appropriate for safety-critical deployments.
Europe faces an industrial opportunity and a sovereignty dilemma
For Europe, AI-RAN presents an unusual combination of industrial opportunity and potential technological dependence. Nokia offers an important European foundation in radio equipment and network software. European operators can provide deployment environments, spectrum access, infrastructure and operational expertise. Yet leading accelerator technologies and associated software ecosystems remain closely linked to non-European industrial suppliers.
The European Union has established a €900 million EU funding contribution for its Smart Networks and Services Joint Undertaking over 2021–2027, intended to be at least matched by industry, bringing the planned combined envelope to at least €1.8 billion. In March 2026, the European Commission announced €116 million for 20 additional 6G research and innovation projects, within a broader programme described as having reached 100 projects. These are research and industrial-policy commitments, not measurements of commercial AI-RAN deployment.
European strategic success will depend on the degree to which these investments produce competitive intellectual property, interoperable architectures, deployable products, secure operations and commercially sustainable infrastructure. Simply installing advanced foreign-designed accelerators in European telecommunications facilities would not, on its own, establish technological sovereignty.
The emerging network must therefore be judged against two simultaneous tests: whether it improves the productivity of communications infrastructure, and whether the public authorities and companies responsible for essential services retain effective control over the systems upon which those services depend.
Key Evidence Table — Verified Technology and Institutional Baseline
The following indicators distinguish operational demonstrations, vendor-reported measurements, announced initiatives and standards-development activities. They should not be interpreted as directly comparable measures of commercial readiness.
| Indicator | Value or current status | Reference date | Definition and scope | Issuer and exact source |
|---|---|---|---|---|
| Commercial AI-RAN call | Completed at Bellevue, Washington | 21 October 2026 | AI-RAN processing in an operating 5G commercial network | NVIDIA, NVIDIA, Nokia and Leading Telecom Operators Turn Networks Into Distributed Intelligence Platforms. |
| European concurrent-workload trial | Voice, mobile data and video analytics on shared accelerated infrastructure | October 2026 | Elisa field environment using live 5G spectrum | Nokia, Nokia advances AI-RAN toward commercial deployment and physical AI. |
| AI-based uplink improvement | 10–15% typical measured throughput gain | October 2026 disclosure | Deutsche Telekom–Nokia laboratory channel-estimation trials | Nokia, same October 2026 release. |
| AI-RAN operator ecosystem | Nearly 20 publicly announced collaborations | 21 October 2026 | Collaboration count, not operational deployment count | NVIDIA, October 2026 announcement. NVIDIA Newsroom |
| New accelerated computing platforms | MGX 2U and MGX 4U | October 2026 | NVIDIA ARC configurations using RTX PRO 6000 Blackwell Server Edition GPUs | NVIDIA Newsroom |
| UK network trial | Birmingham deployment trial planned for 2027 | October 2026 | BT, Nokia and NVIDIA programme | Nokia and NVIDIA, October 2026 announcements. |
| German field validation | Planned for 2027 | October 2026 | Deutsche Telekom, following Bonn and Oulu laboratory work | NVIDIA and Nokia, October 2026 announcements. |
| IMT-2030 use cases | Six defined scenarios | 2023 framework; 2026 development | International 6G framework, not achieved network performance | ITU-R, IMT towards 2030 and beyond. |
| EU research funding framework | €900 million EU contribution, intended to be matched by industry | 2021–2027 | SNS JU planned programme funding | European Commission, The Smart Networks and Services Joint Undertaking. |
| EU 6G project announcement | €116 million for 20 projects | March 2026 | Research and innovation funding announcement | European Commission, Europe to advance 6G innovation. |
| Virtualised-network security baseline | 60 security challenges, 55 best practices | February 2022 | ENISA assessment of 5G network-function virtualisation | ENISA, NFV Security in 5G – Challenges and Best Practices. |
The Sectoral Impact of AI-RAN: Strategic Opportunities and Exposure
AI-RAN’s long-term importance depends on what it enables beyond conventional mobile connectivity. Each sector faces different constraints, and a technologically possible application should not be confused with a clinically validated, safety-certified or commercially viable deployment.
Cybersecurity and Critical Infrastructure
Shared acceleration could support local threat detection, anomaly analysis and more responsive network-defence systems. At the same time, it introduces potential attack paths through AI models, container orchestration, accelerator firmware and cross-tenant resource sharing. The central requirement is enforceable separation between critical communications and less trusted AI workloads, supported by independently verifiable recovery procedures.
Defence, Intelligence and National Security
Distributed compute close to operational environments could support rapid sensor-data processing, situational awareness and coordination of autonomous systems. But commercial AI-RAN platforms cannot be assumed to meet military requirements for contested-spectrum operation, electromagnetic resilience, protected communications or mission assurance. Defence applications require separate qualification and sovereignty assessments.
Healthcare, Clinical AI and Emergency Medicine
Potential applications include nearby inference for medical imaging, remote patient monitoring, connected ambulances and clinical decision-support systems. Local processing may reduce the need to transport sensitive data to distant computing centres. It does not, however, automatically establish medical-device safety, clinical accuracy or end-to-end service reliability. Patient safety, data protection and clinical validation remain independent requirements.
Manufacturing, Robotics and Industrial Automation
AI-RAN could integrate industrial communications with local machine-vision inference, predictive maintenance and coordination of robotic fleets. The greatest value may arise in environments where local data processing reduces dependence on distant facilities. Industrial safety functions must nevertheless preserve deterministic execution and fail-safe behaviour when AI compute resources become unavailable.
Transport, Ports and Autonomous Mobility
Future infrastructure could support traffic analytics, roadside perception, logistics automation and coordination between vehicles and infrastructure. Network-assisted intelligence may supplement onboard systems but should not become a single point of failure for safety-critical vehicle decisions. The EU’s February 2026 ICT supply-chain work specifically identified connected and automated vehicles as a sector requiring coordinated security assessment.
Energy, Utilities and Environmental Infrastructure
Distributed AI could improve local monitoring and predictive analysis for power distribution, renewable-energy assets, water systems and environmental sensors. The trade-off is the additional electricity, cooling and backup-power demand introduced by accelerated computing. Deployment economics must assess both infrastructure energy consumption and any verified efficiency gains.
Society, Labour, Privacy and Democratic Governance
More local AI processing could improve accessibility, translation, public services and digital inclusion. Conversely, the combination of communications data, positioning, sensing and AI inference creates risks of disproportionate surveillance, opaque automated decisions and unequal access. The governance challenge is to prevent the network’s enhanced ability to interpret the physical environment from becoming unrestricted authority to monitor it.
These possibilities are consistent with the direction of the ITU IMT-2030 framework, but the Bellevue trial itself did not validate the sector-specific applications described above.
The European Strategic Position: Four National Models
Europe’s exposure cannot be understood through a single industrial or regulatory profile. Italy, France, Germany and the United Kingdom occupy different positions within the telecommunications value chain and bring different institutional capabilities to the emerging AI-RAN ecosystem.
| Country | Verified 2026 development | Strategic implication | Principal question |
|---|---|---|---|
| Italy | NVIDIA identifies TIM among operators building NVIDIA-powered infrastructure and Fastweb + Vodafone among those expanding it. | Potential convergence of operator networks, distributed AI services and domestic digital infrastructure | Can investment in accelerated computing translate into Italian industrial capability and retain meaningful operational control? |
| France | Orange is testing Nokia software on NVIDIA ARC and developing distributed voice-intelligence applications. | Opportunity to link telecom infrastructure, enterprise AI and trusted national services | Can French operators integrate edge intelligence without creating disproportionate platform dependencies? |
| Germany | Deutsche Telekom and Nokia report laboratory uplink-performance results and plans for 2027 field validation. | Connection between AI-RAN, industrial robotics and Germany’s wider industrial AI ambitions | Can Germany demonstrate reliable, economically defensible integration between industrial AI and commercial radio infrastructure? |
| United Kingdom | BT plans AI-RAN trials in Birmingham in 2027 and is pursuing AI-based network-operations applications. | Potential alignment of cloud-native telecommunications, enterprise services and network automation | Can the UK translate trial success into resilient infrastructure and independently governed commercial deployment? |
The distinction between Italy’s disclosed accelerated-computing infrastructure initiatives and the more specific AI-RAN trials announced for other European operators is important. Participation in the wider NVIDIA telecommunications ecosystem is not proof of a commercial AI-RAN installation.
At European level, regulatory responsibility is also distributed. Telecommunications operators fall within the scope of NIS2 cybersecurity obligations where the directive’s conditions apply. AI systems must be assessed under the EU AI Act according to their actual intended purpose and classification; the presence of AI within network infrastructure does not automatically make every radio optimisation system a high-risk AI system. The February 2026 EU ICT Supply Chain Security Toolbox adds a voluntary, supplier-agnostic framework for managing critical technology dependencies.
Competing Strategic Pathways, 2027–2031
Three overlapping future pathways can be distinguished. They are not mutually exclusive: different operators and national markets may follow different models, depending on capital expenditure, deployment density, electricity costs, technology regulation and the availability of commercially valuable edge services.
| Strategic pathway | Supporting evidence | Evidence against premature adoption | Decisive indicator | Current assessment |
|---|---|---|---|---|
| AI-RAN becomes a mainstream commercial architecture | Commercial-network call, Elisa shared-workload trial, operator partnerships | Limited published large-scale cost and resilience evidence | Multi-site deployments with audited reliability and total-cost comparisons | Technically plausible; commercial validation incomplete |
| Selective adoption in high-value environments | Demonstrated concurrent workloads and specialised industrial use cases | Variable utilisation, site constraints and uneven customer demand | Profitable deployments in industrial and high-density locations | A credible nearer-term pathway |
| AI-RAN remains complementary to specialised radio infrastructure | Existing network architectures remain operational; time-critical radio processing imposes strict constraints | Software evolution may reduce the need for specialised deployment | Comparative performance of accelerated and specialised systems under identical conditions | A credible alternative, particularly where economics or resilience favour separation |
The strongest current evidence supports the prospect of selective commercial adoption before universal architectural replacement. This judgment does not imply a quantified adoption probability. It reflects the difference between demonstrated technical interoperability and the broader reliability, cost and governance evidence that a network-wide migration would require.
Principal Gaps and Watch Indicators
The decisive unanswered questions concern sustained operational performance, not whether the underlying concept is technically possible.
Radio and AI workload coexistence
Required evidence: production-network measurements of tail latency, scheduling deadline misses, jitter, radio-block errors, service availability and performance when accelerator utilisation increases.
Commercial economics
Required evidence: independently comparable capital and operating expenditure, useful accelerator utilisation, workload revenue, licence costs and five-year total cost of ownership against conventional and alternative virtualised RAN systems.
Cybersecurity and operational assurance
Required evidence: third-party testing of workload isolation, hypervisor and firmware security, model integrity, privileged orchestration, update mechanisms and failure containment.
Interoperability and strategic autonomy
Required evidence: documented migration paths between compute suppliers, portable radio software, standards-conformant interfaces and recovery procedures that do not depend entirely on one proprietary ecosystem.
Energy and environmental sustainability
Required evidence: measured energy per delivered traffic unit and per useful AI inference, including cooling, idle capacity, network transport and embodied hardware costs.
No decision-useful quantitative visualisation is supportable from the verified record for a direct comparison of AI-RAN commercial cost, energy efficiency or reliability against conventional RAN systems.
Strategic Net Assessment
The present stage of AI-RAN development is best understood as the opening of a new infrastructure competition rather than the arrival of a mature telecommunications generation.
NVIDIA’s October 2026 announcement identifies a hardware and software ecosystem that includes RTX PRO 6000 Blackwell Server Edition accelerators, MGX-based Aerial RAN Computer configurations, Nokia’s CUDA-accelerated software and commercial servers from Dell Technologies, Quanta Cloud Technology and Supermicro. It also describes the use of Nemotron models in network-management products from Nokia and Cisco. The industrial significance is the convergence of several previously more separate value chains: telecommunications infrastructure, accelerated computing, cloud software and AI model operations.
This convergence could redistribute strategic influence. Semiconductor platforms may become more important to telecommunications procurement. Operators may acquire new opportunities to provide AI services through distributed facilities. Cloud and software companies may gain influence over network operations, while traditional network-equipment suppliers must compete on the integration of radio engineering, software programmability and AI performance.
The transition also presents a critical policy distinction. The ability to deploy AI computing on national territory is not equivalent to sovereign control over AI infrastructure. Effective sovereignty requires enforceable control over operations, access, data, security updates, service recovery and strategic dependencies. Domestic infrastructure ownership may be necessary, but it is not sufficient.
For governments, the immediate strategic opportunity is to shape procurement, cybersecurity requirements, research priorities and future standards while the architecture is still developing. The principal danger is allowing early commercial partnerships to become irreversible infrastructure dependencies before the reliability, economics and security of the underlying platforms have been adequately demonstrated.
The coming five years will establish whether AI-RAN becomes a central architectural component of 6G, a valuable but selective edge-computing model, or one of several competing approaches to intelligent telecommunications.
What is already becoming clear is that the future of mobile connectivity will be determined by more than spectrum efficiency and radio coverage. It will increasingly involve computational power, industrial supply chains, AI governance, cybersecurity resilience and the capacity of national institutions to retain control over the infrastructures on which their societies depend.
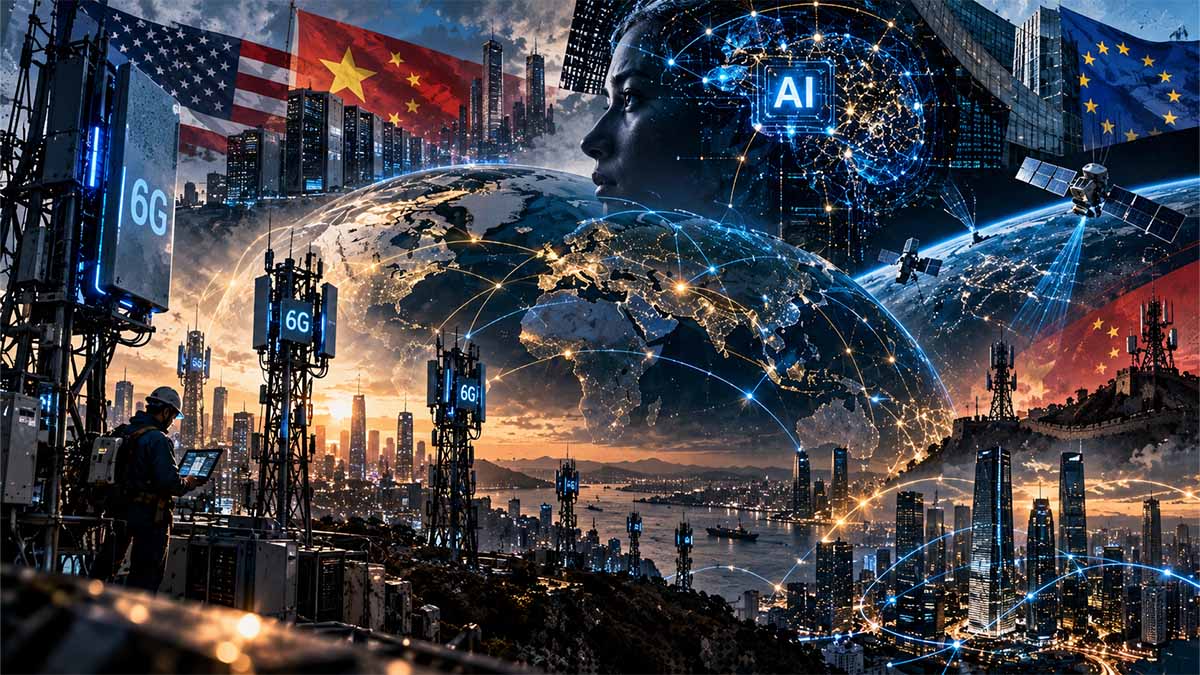
AI-RAN & 6G
THE NEW GEOPOLITICS OF INTELLIGENT CONNECTIVITY
From a commercial 5G call on AI-accelerated infrastructure to the prospect of distributed intelligence networks: the changing architecture of cyber power, critical infrastructure, industrial competition and digital sovereignty.
TECHNOLOGY CYBERSECURITY DEFENCE HEALTHCARE GEOPOLITICS 6G 2030+The October 2026 AI-RAN Breakthrough
On 21 October 2026, NVIDIA, Nokia and T-Mobile announced an AI-RAN call over an operational commercial 5G network in Bellevue, Washington. The demonstration used Nokia’s radio technology and accelerated software running on NVIDIA computing infrastructure, connected to T-Mobile’s existing 5G Standalone core.
2026
Public announcement of the commercial-network AI-RAN call.
Existing core
Commercial user equipment and radio infrastructure integrated with a pre-existing Standalone network core.
Collaborating operators
NVIDIA’s reported count of publicly announced operator collaborations, not production deployments.
The call demonstrates architectural integration, not commercial superiority, production-scale reliability or measured network-wide spectral-efficiency gains.
The 3D Architecture of the AI-RAN Network
A conceptual representation of four interdependent infrastructure layers. The 3D geometry shows functional relationships, not a literal equipment installation or proven allocation of computing resources.
Functional Integration
From Conventional 5G to AI-Native 6G
The following 3D blocks distinguish the established telecommunications architecture, the emerging AI-RAN model and the proposed capabilities of future IMT-2030 systems.
5G / 5G Advanced
Mobile connectivity supported by specialised, virtualised or cloud-native radio functions.
Core objective: efficient, reliable mobile communications.
AI-RAN
AI-assisted radio functions and potentially shared acceleration for communications and AI inference.
Core question: measurable operational and economic value.
6G
Advanced communications, AI integration, ubiquitous connectivity and integrated sensing.
Core objective: standardised, trusted next-generation capabilities.
AI-RAN is not itself synonymous with 6G. Its architectures and techniques may contribute to future 6G implementations, subject to standardisation, interoperability and verified performance.
What Has Actually Been Demonstrated?
Typical uplink throughput improvement
Nokia-reported results from laboratory work with Deutsche Telekom using AI-based uplink channel estimation.
Concurrent workload categories
Elisa’s reported field test combined voice, mobile data and video analytics on accelerated infrastructure using live 5G radio conditions.
| Capability | Evidence available | What remains to establish |
|---|---|---|
| AI-RAN radio processing | Commercial-network call completed | Reliability and performance at production scale |
| AI-supported channel estimation | Vendor-reported laboratory gains | Generalisability across sites, devices and traffic profiles |
| Shared RAN and AI compute | Concurrent-workload field demonstration | Tail latency, resource isolation and workload economics |
| Reduced infrastructure costs | Potential benefit | Auditable five-year total-cost comparisons |
| Autonomous network management | Developing AI-agent capabilities | Safe operation, oversight, recovery and security assurance |
Eight Domains That Could Be Transformed
These are prospective application pathways and their principal engineering or governance constraints; they are not outcomes proven by the Bellevue test.
Cybersecurity
Local threat analysis, traffic anomaly detection, more responsive protection of critical services.
Military and Intelligence
Distributed sensor analysis, protected communications support and potentially faster operational intelligence.
Healthcare and Medicine
Edge-based diagnostic support, patient monitoring, connected ambulances and clinical data processing.
Manufacturing and Robotics
Machine vision, predictive maintenance, automated inspection and connected industrial equipment.
Transport and Logistics
Roadside intelligence, port automation, intelligent transport analytics and vehicle coordination.
Energy and Utilities
Infrastructure monitoring, distributed sensing, grid analytics and predictive asset maintenance.
Public Services and Society
Local language AI, accessible digital services, emergency support and urban infrastructure analytics.
Satellite and Ubiquitous Connectivity
Potential integration with non-terrestrial networks, intelligent routing and remote-area services.
The New Cybersecurity Dependency Chain
Shared computing introduces additional trust boundaries. The following conceptual chain shows where a technology dependency may become an operational security exposure. It does not describe a documented cyberattack.
Principal technical risks
Compromised accelerators or firmware; malicious updates; unsafe AI-generated control actions; cross-tenant data leakage; resource exhaustion; orchestrator compromise; and cascading service failures.
Essential controls
Hardware-backed attestation, least-privilege access, separated management domains, resource reservation, cryptographically protected updates, model provenance, independent monitoring and tested fallback mechanisms.
The Four Strategic European Positions
The four 3D columns represent distinct national strategic roles, not quantitative rankings. Their relative heights are decorative and must not be read as measurements of leadership, investment or technological readiness.
Equal illustrative column heights indicate that no comparable quantitative national AI-RAN adoption dataset is presented.
| Country | 2026 documented activity | Strategic opportunity | Critical dependency or policy issue |
|---|---|---|---|
| Italy | TIM and Fastweb + Vodafone identified in NVIDIA-related infrastructure initiatives. | Distributed AI services, industrial applications and network-cloud integration. | Supplier independence, network economics and sovereign operational control. |
| France | Orange testing accelerated Nokia software and distributed AI applications. | Edge intelligence, operator services and enterprise-oriented innovation. | Platform concentration, security and durable industrial value. |
| Germany | Deutsche Telekom and Nokia laboratory demonstrations; field work planned for 2027. | Industrial automation and AI-supported radio optimisation. | Field reproducibility and production-grade deterministic performance. |
| United Kingdom | BT planning AI-RAN field trials in Birmingham during 2027. | Cloud-native operations, service automation and network experimentation. | Critical network assurance, supplier risks and scale economics. |
Who Controls the Intelligent Network?
Accelerated Compute
Strong position in GPU platforms, AI software ecosystems and cloud infrastructure. Central strategic issue: platform concentration and export-control exposure.
Telecom Industrial Base
Radio systems expertise, network operators, research institutions and regulatory capacity. Central issue: converting infrastructure and research into sovereign industrial value.
Alternative Technology Ecosystems
Large telecommunications and electronics industrial capabilities create scope for competing network-computing architectures. Central issue: standards competition, supply chains and market fragmentation.
AI-RAN and 6G: Roadmap to 2031
A conditional analytical roadmap. Dates after October 2026 indicate anticipated decision periods, not guaranteed commercial milestones.
2026
Commercial-network technical demonstrations; shared accelerated-compute validation.
2027
Announced operator field trials; broader operational testing and integration.
2028
Potential procurement decisions, workload economics and security qualification.
2029
Further 6G standards development, architecture convergence or fragmentation.
2030–31
Potential early 6G commercialisation and selective intelligent-network scaling.
Three Possible Commercial Pathways
Shared AI-RAN platforms expand as operators demonstrate favourable economics, predictable performance and robust security.
AI-RAN concentrates in industrial campuses, dense urban sites and locations with measurable demand for nearby AI services.
Specialised radio infrastructure remains attractive where capital requirements, energy efficiency, operating complexity or reliability favour separation.
The three pathways are analytical possibilities, not probability-weighted forecasts. Different operators may adopt different models simultaneously.
Government and Operator Priorities
| Strategic priority | Practical action | Evidence required | Risk to manage |
|---|---|---|---|
| Cyber resilience | Require independently evaluated isolation, update security and recovery. | Penetration testing and service-continuity records. | Cross-workload compromise. |
| Industrial sovereignty | Promote interoperable procurement and documented exit strategies. | Portability and supplier substitution tests. | Irreversible vendor dependence. |
| Critical-service assurance | Separate safety-critical processing from nonessential AI applications. | Fault injection, fallback and deterministic scheduling results. | Communications degradation. |
| Economic efficiency | Conduct like-for-like deployment cost comparisons. | Audited energy, infrastructure cost and workload utilisation. | Unproductive capital investment. |
| 6G standardisation | Support international technical interoperability. | Standards-conformance and multi-vendor integration evidence. | Ecosystem fragmentation. |
| Societal governance | Establish clear data-purpose, privacy and AI accountability rules. | Impact assessments and independent governance audits. | Excessive surveillance and exclusion. |
The Infrastructure Question of the Next Decade
AI-RAN marks an important stage in the convergence of telecommunications, accelerated computing and distributed artificial intelligence. The October 2026 commercial-network demonstration establishes a technological milestone, while the next phase must determine whether the architecture can meet the economic, resilience and security requirements of large-scale telecommunications infrastructure.
The principal geopolitical question is no longer limited to which countries control spectrum, mobile towers or network vendors. It increasingly concerns who controls semiconductor platforms, computing resources, software ecosystems, automated management, AI models and the data generated through intelligent communications networks.
PILLAR I — THE TECHNOLOGICAL AND INFRASTRUCTURAL TRANSFORMATION
AI-RAN, Accelerated Telecommunications Infrastructure and the Engineering Foundations of Sixth-Generation Networks
Institutional Technology and Strategic Infrastructure Assessment | 23 October 2026
Chapter 1 — From Conventional 5G to AI-RAN: The New Architecture of Telecommunications
The transformation of radio access networks from dedicated telecommunications equipment into programmable computing infrastructure
The emergence of Artificial Intelligence Radio Access Networks represents a significant change in the engineering foundations of mobile telecommunications, but its importance cannot be understood simply as the replacement of conventional network equipment with graphics processors. The deeper transformation concerns the separation of radio functions from the physical computing systems on which those functions execute, followed by their potential integration with artificial intelligence workloads operating within a common technological environment. This development challenges an industrial architecture that has historically relied on tightly integrated relationships between specialised signal-processing hardware, telecommunications software, radio equipment and the operating procedures needed to maintain continuous mobile connectivity. It also changes the distribution of technical responsibilities within telecommunications networks, bringing semiconductor architecture, general-purpose computing, cloud orchestration, software acceleration and artificial intelligence increasingly into decisions that were previously dominated by radio engineering and telecommunications equipment design.
Conventional mobile networks already contain substantial software-defined functionality. Modern 5G systems should not be characterised as entirely hardware-bound infrastructures being transformed for the first time into programmable networks. Centralisation, network-function virtualisation, software-defined networking, cloud-native core systems and disaggregated radio architectures have been developing for years. AI-RAN builds on these earlier transformations by introducing accelerated computing as a potential execution environment for demanding radio workloads and, importantly, by proposing that the same infrastructure might support radio communications and artificial intelligence services with different processing requirements. The distinction is fundamental: virtualisation changes where network software runs, while AI-RAN seeks to change both the computational methods used within the radio network and the economic purpose of the infrastructure itself.
Nokia’s description of its anyRAN architecture illustrates this evolution. The company distinguishes Cloud RAN, where virtualised radio functions operate on cloud infrastructure, from Open RAN, where standardised interfaces seek to facilitate interoperability between network components supplied by different manufacturers. Nokia’s approach combines purpose-built, cloud-based and open architectures rather than assuming that every network element must immediately migrate to general-purpose computing. This distinction matters because the future telecommunications system is unlikely to develop through one universal architectural replacement. Dense urban networks, rural coverage installations, industrial private networks, national emergency communications and military installations operate under different combinations of processing demand, economic constraints, resilience requirements and infrastructure availability. An architecture commercially attractive in a metropolitan aggregation facility may offer little advantage at an isolated radio site where power, cooling, fibre connectivity or technical maintenance are expensive.
A conventional 5G network consists of several interacting systems whose functions must remain conceptually distinct. The radio unit converts digitally processed signals into radio-frequency transmissions and receives signals from connected devices through an antenna system. Baseband processing implements demanding physical-layer functions, including modulation, coding, channel estimation, signal detection and other operations necessary for reliable communication over an imperfect radio channel. Higher protocol layers coordinate scheduling, mobility, bearer handling and user-plane transport. The 5G core provides functions associated with authentication, mobility management, session control, policy enforcement and connectivity to external data networks. Transport infrastructure interconnects these elements through fronthaul, midhaul and backhaul arrangements, while management systems supervise configuration, security and service continuity.
The separation between these functions explains why an apparently simple voice call provides meaningful evidence about a new network architecture. A functioning call requires more than successful arithmetic on an accelerator. Radio-processing tasks must execute within the required scheduling windows; packets must traverse the interfaces linking network components; the user device must exchange control information with the network; and the existing core must maintain the services necessary to establish and sustain communication. Failure in one of these relationships can interrupt the entire service even if the accelerator itself is performing correctly.
The commercial-network test reported on 21 October 2026 by NVIDIA, Nokia and T-Mobile therefore matters because it demonstrated interoperability across several operational layers rather than merely confirming that radio-processing software could execute on a graphics processor. According to Nokia’s technical account of the Bellevue AI-RAN call, the demonstration connected Nokia Massive MIMO radio equipment, Nokia 5G anyRAN software and server infrastructure built around NVIDIA Aerial RAN Computer to a commercial 5G core, using commercial user equipment. The test took place at a commercial cell site on T-Mobile’s operational network. The companies described it as the first call of its type, a claim that should be attributed to the participating vendors because the breadth of any historical first depends on the exact definition of AI-RAN and the technologies included in the comparison.
The important achievement was the successful execution of a functional radio-access processing chain within a commercial telecommunications environment. The announcement did not establish that the entire access network had become autonomous, that every radio-processing operation was performed by artificial intelligence, or that commercial operation across thousands of sites had already been economically justified. Nokia explicitly identified subsequent field trials involving AI-for-RAN algorithms and AI workloads operating alongside radio functions as the next phase. The distinction between demonstrated radio-processing capability and still-pending operational validation is essential for investment decisions, regulatory assessments and government procurement.
The evolution of centralised, virtualised and distributed radio access networks
The architecture of contemporary radio access networks reflects a series of engineering trade-offs between processing centralisation, transport availability, fault containment and deployment cost. Distributed RAN places substantial baseband processing close to the radio site, reducing dependence on high-capacity transport to a central processing facility but requiring processing resources across a larger number of locations. Centralised RAN aggregates selected baseband functions into shared facilities serving multiple radio sites, potentially improving operational efficiency and enabling coordination across cells. Cloud RAN introduces software workloads running on virtualised or containerised computing platforms, allowing operators to separate network functions from particular equipment configurations. Open RAN adds an interoperability dimension through defined interfaces, although the presence of an open interface does not automatically guarantee that any two suppliers’ implementations will operate together without integration work.
These distinctions have major consequences for AI-RAN because accelerated computing is not economically or technically appropriate in every physical location. A centralised processing facility may contain enough radio traffic to justify expensive accelerator hardware and may also have sufficient power, cooling, fibre infrastructure and operations support to accommodate additional artificial intelligence workloads. A smaller rural installation may have low average traffic and limited commercial demand for edge inference, making the same investment difficult to recover. The ability to pool workloads across multiple cells becomes economically attractive only if the transport network can carry the necessary information without violating radio-processing deadlines.
A crucial architectural distinction exists between the radio unit, distributed unit and central unit. In a disaggregated 5G radio access network, the distributed unit normally performs functions with relatively demanding real-time requirements, while the central unit carries out higher-layer activities that may tolerate greater geographical separation. The precise functional allocation depends on the selected split architecture. A lower-layer functional split can place time-sensitive processing in a centralised computing system while keeping radio-frequency functions at the antenna location, but this arrangement places demanding requirements on the transport connection between the radio unit and distributed unit.
The O-RAN Alliance’s Open Fronthaul Working Group is responsible for specifications addressing the interface between radio units and distributed units, including control, user, synchronisation and management requirements. These are not secondary engineering details. Synchronisation errors can degrade coordinated radio transmission, while insufficient transport capacity or excessive variation in packet delivery can undermine the timing assumptions on which radio processing depends. The cost of fibre installation, optical transport equipment, resilient timing sources and network monitoring must therefore be included in any economic comparison between accelerated centralised processing and a conventional distributed architecture.
The move towards accelerated Cloud RAN must also preserve the difference between telecommunications-grade reliability and ordinary cloud-computing availability. An enterprise application may tolerate a temporary processing slowdown, a delayed response or a retry after a software service becomes unavailable. A radio-processing function may have to complete a scheduled operation within a defined transmission interval. Missing that deadline can cause a radio transmission opportunity to be lost, increase retransmissions, reduce throughput or interfere with service continuity. Telecommunications workloads consequently require predictable execution latency, controlled resource contention and mechanisms ensuring that lower-priority computing jobs cannot unexpectedly consume resources reserved for essential radio functions.
For national infrastructure planners, this creates a more complex optimisation problem than selecting the server offering the highest theoretical processing capacity. The relevant unit of analysis becomes the complete operating system of radio hardware, transport connections, processing resources, software orchestration, operational support and energy infrastructure. AI-RAN may improve one element while increasing the cost or vulnerability of another. A reduction in dedicated baseband hardware may be offset by additional accelerator equipment, while improved compute utilisation may require more elaborate orchestration and failure-management systems.
GPU-accelerated baseband processing and the changing role of telecommunications semiconductors
The technical case for accelerated radio processing originates in the substantial mathematical workload associated with modern cellular systems. Massive MIMO processing involves operations on signals transmitted and received through multiple antenna elements. Channel estimation attempts to characterise the changing radio environment between transmitting and receiving antennas. Equalisation and detection seek to recover transmitted information from signals affected by noise, interference and propagation conditions. Channel coding introduces redundancy that allows receivers to reconstruct information despite errors, while decoding attempts to recover the original bits within computational and timing constraints. These tasks involve extensive parallel computation, but they do not all have identical execution characteristics.
Graphics processing units are attractive for selected radio functions because their architecture is designed to execute many mathematical operations concurrently. Matrix and vector operations are particularly relevant to signal processing and machine learning, creating an opportunity to use accelerated computing platforms for both conventional radio algorithms and neural-network inference. The presence of parallel arithmetic capacity, however, is not sufficient. Data must reach the accelerator in time, processing must complete predictably, and the resulting information must return to the radio-processing chain without violating the network’s timing requirements.
The performance of an accelerated RAN therefore depends on more than the nominal capabilities of a GPU. CPU scheduling, memory transfer, direct-memory-access mechanisms, accelerator queue management, networking interfaces, device drivers and application software all affect the time required to complete a processing operation. A theoretically faster mathematical kernel may produce little system-level benefit if its inputs spend excessive time moving between computing components. Conversely, an accelerator with lower theoretical peak throughput may be more suitable for a telecommunications workload if its integrated execution environment produces more predictable processing latency and lower operational overhead.
NVIDIA’s October 2026 telecommunications announcement introduced additional Aerial RAN Computer configurations, including MGX 2U and MGX 4U server designs using RTX PRO 6000 Blackwell Server Edition accelerators. The company identified x86 and NVIDIA Vera processor options and named Dell Technologies, Quanta Cloud Technology and Supermicro as suppliers of compatible systems. The announcements indicate an industrial strategy extending beyond a single experimental configuration towards a supply chain of servers, processors, accelerators and software designed for high-capacity telecommunications workloads.
These hardware characteristics should nevertheless be distinguished from verified deployment economics. A compact server chassis does not establish the complete electrical or thermal requirements of an operational AI-RAN site. Power consumption depends on accelerator configuration, CPU utilisation, memory, storage, network interfaces and the actual workload. Thermal requirements are affected by equipment density, airflow, ambient temperature and the surrounding infrastructure. Reliability depends on redundant power, replaceable components, failure detection and the network’s ability to continue operating when an accelerator or server becomes unavailable.
The semiconductor implications extend to industrial policy. A traditional telecommunications supplier could exercise substantial control over a network through its integrated baseband architecture. Under accelerated architectures, control becomes more distributed across the radio-system supplier, server manufacturer, processor supplier, accelerator provider, operating-system environment, container infrastructure and software toolchain. In the NVIDIA model, CUDA is an important part of the software development and acceleration environment. This can create substantial engineering advantages through established libraries and optimisation tools, but it also makes software portability and the possibility of moving workloads between different accelerator architectures economically significant.
Nokia’s Cloud AI-RAN architecture presents its anyRAN software as supporting GPU, Arm and x86 execution environments. This flexibility is strategically relevant, but a claim of cross-platform software support should not be treated as evidence that all supported processors provide identical throughput, energy efficiency, functionality or deployment cost. Hardware independence is a spectrum rather than a binary characteristic. Source-code portability, functional interoperability, equivalent service performance and commercially practical supplier substitution are different achievements.
An operator seeking genuine negotiating power must therefore examine whether it can migrate between processing platforms without redesigning essential radio functions, rewriting substantial software components or accepting unacceptable service degradation. The answer will depend on how much of the implementation relies on standard interfaces, proprietary acceleration libraries, specialised optimisation techniques and vendor-specific orchestration. The future distribution of market power may be determined as much by these software dependencies as by physical semiconductor supply.
Massive MIMO, channel estimation and the physical limits of network intelligence
The transition to AI-RAN does not abolish the physical constraints of wireless communications. Radio waves remain subject to propagation loss, interference, reflections, obstruction, fading and variations in the movement and distribution of connected devices. The capacity of a radio system depends on the relationship between bandwidth, signal quality, interference conditions, spatial reuse and the effectiveness of modulation and coding. Artificial intelligence can assist in estimating and responding to these conditions, but it cannot eliminate the underlying physical limitations.
Massive MIMO illustrates both the opportunity and the difficulty. By using multiple antenna elements and carefully controlled transmission characteristics, a network can direct energy spatially and support communications with multiple users across available radio resources. The quality of those decisions depends on knowledge of the channel conditions between antennas and connected devices. In practice, that knowledge is imperfect, changes over time and must be inferred from reference signals and other observations. Processing complexity increases as systems attempt to exploit additional antennas, users and spatial dimensions.
AI-based channel estimation introduces the possibility of learning statistical relationships that conventional estimation algorithms may not fully capture under particular propagation conditions. A trained model may improve the interpretation of noisy channel measurements, potentially allowing more effective signal recovery or better-informed transmission decisions. Such an improvement can produce higher useful throughput without requiring additional radio spectrum, although the magnitude of the benefit depends heavily on the operating environment.
On 21 October 2026, Nokia reported that its laboratory work with Deutsche Telekom had demonstrated typical uplink throughput gains of 10–15% using AI-based channel estimation, with larger improvements under more difficult radio conditions. The company’s official AI-RAN announcement described these as initial laboratory measurements. They do not establish an equivalent improvement across all 5G traffic, all users, downlink performance or an entire commercial network.
The distinction is important because spectral-efficiency improvement has several possible meanings. An operator may measure increased bits transmitted per second per hertz under a defined laboratory configuration, improved cell-edge performance, better average user throughput or increased aggregate cell capacity. These indicators are related but not interchangeable. A stronger uplink result under difficult channel conditions may be particularly valuable for industrial devices, connected cameras or uplink-intensive applications, yet it cannot automatically be extrapolated to the economics of every mobile subscriber.
In July 2026, Nokia presented an ambition to achieve more than 100% spectral-efficiency gains by 2028 through its AI-native radio platform. The July 2026 Nokia platform announcement must be read as a forward-looking vendor objective, not as a gain already measured across operational commercial networks. The more modest laboratory results disclosed in October provide evidence that particular techniques may yield practical improvements, but they do not independently validate the company’s broader target.
The engineering question is whether gains observed in carefully controlled trials persist when models encounter different frequencies, antenna geometries, subscriber mobility patterns, seasonal propagation changes, device capabilities and interference distributions. AI models can perform well on familiar conditions and less predictably outside their training distribution. Operators must therefore consider model monitoring, the detection of performance deterioration and the ability to revert to conventional signal-processing methods when learned techniques fail to deliver the expected result.
The strategic benefit of such reversibility is substantial. Telecommunications infrastructure is too important to depend on an optimisation method whose failure cannot be identified or corrected. The strongest AI-RAN designs may ultimately be those that combine conventional, mathematically characterised algorithms with adaptable machine-learning components while retaining deterministic control over essential operating conditions.
Fronthaul, timing and transport infrastructure as the hidden constraints on accelerated radio networks
Much of the commercial debate surrounding AI-RAN concentrates on semiconductor acceleration and potential new AI revenues. Yet the economic feasibility of the architecture may depend equally on transport networks that receive much less public attention. Moving radio-processing functions away from a traditional base station requires the transport of information between radio equipment and the facility where processing occurs. Depending on the selected functional split, the volume and timing sensitivity of this information can be very demanding.
For lower-layer splits, fronthaul capacity is influenced by the number of antenna ports, sampling requirements, signal representation, bandwidth, compression and system implementation. Increasing radio bandwidth or antenna count can materially increase the transport burden. Operators may use compression or different functional allocations to reduce the burden, but these choices introduce trade-offs involving processing complexity, radio performance, latency and interoperability.
The relationship between transport distance and timing is particularly important. Propagation through optical fibre is fast, but it is not instantaneous. Processing delays, switching equipment, buffering, synchronisation and congestion management add further components to the end-to-end timing budget. A centralised accelerated-computing facility located far from a radio site cannot be assumed to meet the same deadlines as processing hardware installed locally. Geographic centralisation consequently has an engineering limit determined by the functional split, transport implementation and service requirements rather than by the availability of computing power alone.
Operators planning extensive AI-RAN deployments must also consider the physical redundancy of transport routes. A centralised facility may efficiently serve many radio sites, but the failure of an optical connection or aggregation node could interrupt a much larger area than the failure of one self-contained distributed base station. Resilience planning must therefore evaluate not only component reliability but also the geographical consequences of shared infrastructure failures.
The deployment of accelerated processing can amplify this issue because centralised facilities may simultaneously serve multiple radio cells and commercial AI applications. Concentrating resources increases the potential efficiency of shared computing, but it also concentrates dependencies. Redundant computing nodes are useful only if the transport infrastructure, power systems, synchronisation architecture and operational processes allow services to recover within acceptable limits.
The required topology may therefore differ significantly between countries and regions. Dense European metropolitan areas with established fibre infrastructure and concentrated business demand may support centralised accelerated facilities more readily than mountainous, sparsely populated or geographically isolated areas. Industrial zones may justify dedicated local processing because of strong operational demand, while remote rural coverage sites may remain better served by simpler and more energy-efficient installations.
The emergence of AI-RAN reinforces the strategic importance of optical transport infrastructure. Investments in high-capacity fibre, resilient timing, network monitoring and energy supply are not peripheral to the development of intelligent wireless networks; they are among its prerequisites. A national programme focused only on accelerator procurement would consequently address only one component of the transformation.
The orchestration problem: governing software workloads with fundamentally different operational priorities
The integration of radio processing and AI applications creates a difficult orchestration challenge because different workloads have different definitions of acceptable performance. A telecommunications workload is often governed by specific deadlines and service-availability requirements. An AI inference workload may be governed by response-time objectives, throughput commitments, model accuracy and computational efficiency. Both may benefit from accelerators, but allowing them to compete for resources without enforceable priorities could undermine the central purpose of the radio network.
A shared computing platform requires mechanisms capable of reserving accelerator resources for time-critical processing, controlling memory consumption, limiting competing workloads and preventing lower-priority operations from disrupting scheduled radio functions. These mechanisms must operate across several layers, from hardware scheduling and device drivers to container orchestration and higher-level service management. The addition of AI models introduces further requirements concerning model loading, memory allocation, version management and the handling of variable inference demand.
The problem becomes more complex under mobile traffic fluctuations. Radio workload demand is affected by subscriber activity, network configuration, the number of connected devices and the radio conditions experienced by users. AI demand may follow entirely different patterns, driven by enterprise applications, video analytics, industrial automation or changes in customer activity. A resource-sharing strategy that appears efficient under average utilisation may fail precisely when radio demand and AI demand peak simultaneously.
From an engineering perspective, the most important issue is not maximising average accelerator utilisation but preserving telecommunications service quality under credible peak and failure conditions. A system operating with high average utilisation may appear financially attractive while leaving insufficient reserve capacity for unexpected demand. Conversely, substantial reserved capacity can protect service quality but weaken the economic argument for sharing hardware.
The O-RAN Software Community architecture documentation, which follows the O-RAN Alliance architecture, distinguishes near-real-time and non-real-time RAN Intelligent Controller functions. The near-real-time controller supports relatively fast optimisation and control activities through defined interfaces, while the non-real-time controller supports policy guidance, longer-term optimisation and AI/ML workflows. These components illustrate the importance of separating different control timescales. They should not be confused with the extremely time-sensitive signal-processing operations performed within the radio physical layer, nor do they imply that every AI-RAN implementation must adopt an identical controller arrangement.
This separation has institutional consequences. Network management increasingly involves decisions taken by automated systems that may change radio parameters, allocate resources or respond to changing conditions. As AI agents become capable of proposing or executing operational actions, operators will need explicit authority boundaries identifying which decisions can be automated, which require human approval and which must remain governed by conventional deterministic mechanisms.
The future AI-native telecommunications system will therefore require a combination of software engineering, control theory, radio expertise and operational governance. The most successful architecture will not necessarily be the one with the greatest number of AI components, but the one that can establish which component is authorised to act, when it may act, how its performance is verified and what happens when it behaves incorrectly.
The real significance of Bellevue: a transition in engineering credibility rather than a completed industrial revolution
The Bellevue demonstration should be interpreted as an important reduction in integration uncertainty. Before a new processing architecture can become commercially relevant, it must demonstrate that essential telecommunications functions can operate together under realistic conditions. A successful call involving commercial radio equipment, commercial user equipment, an operational network core and accelerated processing infrastructure is stronger evidence than an isolated software benchmark because it tests a more extensive chain of technical dependencies.
Nevertheless, a single successfully executed telecommunications service does not disclose the sustained behaviour of an entire network. It does not reveal how performance changes during peak-hour demand, whether accelerator sharing can be maintained without deadline failures, how rapidly the system recovers from hardware faults, or whether the architecture remains economical after the costs of power, cooling, transport and software operations are included. The remaining engineering uncertainties are precisely those that determine whether operators can deploy the technology at national scale.
The principal distinction for government and industrial decision-makers is between technological feasibility and deployable infrastructure maturity. Bellevue provides evidence for the former. Broad commercial maturity will require substantially more operational evidence, ideally including measurements taken across multiple sites, traffic distributions, radio environments and equipment configurations, as well as direct comparisons against alternative network architectures.
The emerging infrastructure model will also influence the structure of telecommunications procurement. Rather than purchasing a largely integrated baseband system, operators may increasingly negotiate across multiple technology layers: radio equipment, accelerated servers, cloud software, transport systems, service-management platforms and AI models. Such modularity could increase procurement flexibility, but only where interoperability is enforceable and where replacing one supplier does not require redesigning the entire system.
The most consequential result of this first chapter is therefore architectural rather than promotional. AI-RAN creates the possibility of treating radio processing as one category of workload within a larger distributed computing environment, but the essential physics, timing obligations and resilience requirements of telecommunications remain. The future network may become more programmable and more capable of supporting intelligent applications, yet its reliability will continue to depend on engineering disciplines that artificial intelligence cannot replace.
Chapter 1 — Technical architecture and critical dependencies
| Infrastructure component | Conventional or established role | AI-RAN architectural change | Primary engineering constraint | Strategic consequence |
|---|---|---|---|---|
| Radio unit | Radio-frequency conversion and antenna connectivity | Potential integration with more programmable and intelligent processing arrangements | Radio performance, timing, power and interoperability | Continued reliance on specialised radio equipment |
| Massive MIMO antenna system | Spatial transmission and reception | More advanced signal estimation and beam-related optimisation | Channel knowledge, interference and calibration | Potential improvement in spectrum productivity |
| Distributed unit | Time-sensitive baseband and lower-layer functions | Execution on accelerated virtualised platforms | Deterministic timing and predictable processing | Greater role for computing-platform suppliers |
| Central unit | Higher-layer radio functions | Flexible software placement and orchestration | Transport latency, security and service continuity | More freedom in geographical deployment |
| GPU accelerator | Not necessarily present in traditional baseband platforms | Parallel radio computation and potential AI inference | Scheduling, memory movement and workload isolation | New semiconductor and software dependencies |
| CPU and host system | Processing and system control | Coordination of accelerated functions and software services | Host latency, resource allocation and availability | Greater importance of server integration |
| Fronthaul | Radio-to-baseband transport | May connect radios to accelerated processing facilities | Capacity, timing, synchronisation and distance | Fibre becomes central to economic feasibility |
| Backhaul and midhaul | Transport between RAN and core functions | Support more distributed service and compute placement | Capacity, route diversity and operational resilience | Increased importance of optical infrastructure |
| Orchestration | Configuration and management | Coordinated management of radio and AI workloads | Policy enforcement, fault isolation and scheduling | Expanded operational and cyber governance |
| Edge AI environment | Usually separate from radio-processing hardware | Potential coexistence with RAN workloads | Commercial demand and resource availability | Opportunity for new services, with uncertain revenue |
| 5G core | Subscriber sessions, mobility and policy | Can remain in place during AI-RAN access migration | Interoperability, security and continuity | Incremental adoption without immediate core replacement |
Key judgment: The architecture is technically credible because it builds on established virtualisation and accelerated-computing principles and has now been demonstrated in an operational commercial-network setting. Its eventual scale will depend less on whether a GPU can execute baseband software than on whether the entire system can meet telecommunications-grade timing, resilience, energy and cost requirements.
What would change the assessment: Sustained multi-site field measurements showing predictable radio performance under concurrent AI demand, documented fault recovery, comparative energy efficiency and independently reproducible system economics would materially strengthen the case for large-scale deployment. Conversely, persistent scheduling conflicts, infrastructure cost overruns or difficult supplier portability would favour more selective adoption.
Chapter 2 — The Engineering Economics of Intelligent Connectivity
From telecommunications capital expenditure to the economics of shared computational infrastructure
The central economic proposition behind AI-RAN is not that graphics processors are intrinsically cheaper than specialised telecommunications hardware. In many configurations, high-performance accelerators are expensive, electrically demanding and operationally complex. The proposition is instead that the economic value of a telecommunications processing platform may increase if the same infrastructure can perform multiple useful functions, particularly when conventional radio-processing resources are underutilised or when demand for local artificial intelligence services can be served without building an entirely separate computing facility. Whether this proposition holds depends on the interaction between hardware cost, resource utilisation, radio performance, electricity consumption, transport architecture, software licensing, equipment life and the revenue attributable to new services.
This requires a change in the economic unit used to evaluate network infrastructure. Conventional radio-network investment is often assessed through coverage, capacity, traffic growth, operating cost and quality-of-service requirements. Shared accelerated infrastructure adds compute utilisation, inference demand, service-level agreements, tenant isolation and additional commercial revenues to the assessment. The operator is no longer evaluating only the cost of delivering mobile traffic; it may also be evaluating whether distributed computing capacity can provide a financially sustainable service to enterprise customers, application developers, hospitals, industrial facilities or other organisations.
The three complementary categories identified in NVIDIA’s technical explanation of AI-RAN help separate the economic mechanisms. AI-for-RAN applies artificial intelligence to improve radio functions. AI-and-RAN allows AI and radio workloads to use common computing infrastructure. AI-on-RAN concerns AI services delivered through compute resources located within or close to the radio-access network. These concepts are related but should not be merged into a single financial claim. Each has different requirements for profitability, different infrastructure implications and a different degree of dependence on the successful commercialisation of edge computing.
The first can generate value even without selling AI services to third parties. If AI improves the efficiency with which existing radio spectrum is used, an operator may defer additional network investment, support more traffic within a given configuration or improve service quality in difficult coverage conditions. The second seeks value through improved utilisation of computing assets, but it must overcome the cost of protecting real-time radio workloads against resource contention. The third requires actual demand for local inference services, commercially viable pricing and an effective route to market. An operator could succeed with the first, fail with the second and find limited commercial demand for the third. Alternatively, a specialised industrial deployment could derive most of its value from edge applications while obtaining only modest improvements in radio processing.
This differentiation is essential because the business case for a national telecommunications network cannot be built by adding together hypothetical benefits as though they were independent and automatically realisable. More efficient radio processing may reduce the amount of infrastructure required to serve a given traffic load, leaving different quantities of accelerator capacity available for external applications. However, reductions in infrastructure can also eliminate spare computing capacity that would otherwise have supported those applications. Likewise, dedicating accelerator resources to commercial inference can increase equipment utilisation while increasing the redundancy required to protect telecommunications service continuity. These effects must be modelled together rather than counted as separate gross benefits.
AI-for-RAN: the economics of spectrum efficiency, channel estimation and radio optimisation
Radio spectrum is a finite and institutionally controlled resource. Operators incur substantial costs to obtain or retain access to licensed frequency bands, deploy networks capable of using those frequencies and maintain service quality as demand develops. The ability to deliver more useful traffic through existing spectrum can therefore create economic value even when the operator does not receive additional direct revenue from the optimisation technique itself.
Yet spectrum efficiency is not a single universal indicator. It can refer to throughput achieved per unit of bandwidth, average spectral efficiency over a cell, performance at the cell edge, aggregate efficiency across multiple cells or improvements under particular interference conditions. A gain measured under one definition should not be generalised to every other definition. The value of a 10% improvement in throughput may be substantial in a congested urban cell but negligible in a lightly utilised rural network where traffic demand is already well below available capacity.
AI-based channel estimation can improve decisions about the radio environment when the selected model captures useful statistical relationships that conventional techniques do not exploit as effectively. In uplink communications, the network must reconstruct signals received from devices whose transmission power, antenna characteristics, movement and surrounding propagation conditions vary. More accurate channel estimates may reduce the errors introduced during signal recovery and improve effective throughput. Where this translates into fewer retransmissions or more efficient allocation of transmission resources, the network may use its existing capacity more productively.
The 10–15% typical uplink throughput improvement reported by Nokia and Deutsche Telekom in laboratory conditions is a meaningful engineering observation precisely because it concerns a defined technique rather than an undefined promise of network-wide acceleration. However, the measurement does not establish how the gains vary across radio bands, equipment configurations, subscriber mobility, interference levels or traffic profiles. Nor does it directly demonstrate a proportional improvement in spectral efficiency, energy consumption or financial return. Those relationships require separate measurement.
The economic significance of AI-assisted signal processing also depends on its computational cost. A neural-network model may improve signal interpretation but consume additional processing resources. The relevant measure is not simply additional radio throughput; it is the amount of useful radio capacity gained relative to the incremental compute, energy, memory and infrastructure costs required to achieve it. A technique that improves throughput under demanding conditions but requires substantially more accelerator capacity could be attractive in high-value congested cells and uneconomic elsewhere.
There is also an opportunity cost. Accelerator resources committed to AI-assisted radio processing cannot simultaneously be allocated without restriction to third-party inference workloads. Consequently, operators must compare the marginal value of an accelerator used to increase radio efficiency with the marginal value of the same resources used to deliver other AI services. This is not a conventional telecommunications procurement question: it combines radio engineering, computing economics and service-market demand.
Nokia’s July 2026 objective of more than doubling spectral efficiency by 2028 is relevant as an indicator of the company’s intended technological direction, but investment models should not treat the objective as achieved performance. An operator preparing a deployment decision would need representative field measurements demonstrating the realised gain under its own spectrum holdings, antenna configurations, traffic distributions and equipment constraints. The financial value would then depend on whether the improvement allows a specific investment to be avoided or deferred, reduces service degradation or supports commercially valuable additional traffic. An improvement in a technical benchmark has little direct financial value unless it changes an operational or commercial outcome.
Dynamic spectrum management and the limitations of intelligent optimisation
AI-assisted spectrum management could eventually encompass a much broader range of functions than channel estimation. Predictive models may help estimate future traffic demand, identify changes in interference, recommend resource allocation or adjust energy-consuming radio configurations in response to observed conditions. More sophisticated systems might coordinate decisions across adjacent cells, select radio parameters based on changing network conditions and identify situations where conventional planning assumptions no longer accurately describe actual usage.
The potential benefit arises from the fact that mobile networks operate in environments that change continuously. Subscriber concentration varies by location and time of day. Industrial installations may produce highly structured traffic patterns. Transport corridors experience changing mobility and handover requirements. Sporting events, emergencies and infrastructure disruptions can produce temporary demand concentrations that differ sharply from historical averages. Static configurations are rarely optimal under every condition, creating an opportunity for adaptive control.
However, the usefulness of an AI model depends on what it is permitted to observe and control. Predictions based on delayed or incomplete telemetry can produce poor decisions. Incorrect model assumptions can cause oscillation between configurations, degrade neighbouring cells or allocate resources inefficiently. A network that optimises one cell without considering interference effects on adjacent cells may improve a local metric while reducing system-wide performance. The objective function governing an AI optimisation system is therefore strategically important: maximising average throughput, protecting disadvantaged users, minimising energy consumption and preserving low latency can require different choices.
Some of these objectives conflict. Reducing transmission power may save electricity but reduce coverage or signal quality. Concentrating users on fewer active cells may allow other equipment to enter an energy-saving state, but it can also increase congestion and vulnerability to the failure of a remaining active cell. Prioritising premium service traffic may improve performance for certain customers while worsening experience elsewhere. AI can calculate and implement a policy more rapidly, but it cannot determine the legitimacy of that policy without an external governance framework.
For regulators, the growing autonomy of radio optimisation raises questions about compliance with licence conditions, interference obligations, lawful operating parameters and emergency communications requirements. A learning system should not be given unrestricted authority to alter transmission behaviour simply because a statistical model predicts improved efficiency. Its decisions must remain within technically and legally defined boundaries, and network operators must be able to identify the software version and control process responsible for material operating changes.
The commercial value of dynamic optimisation should therefore be evaluated through controlled comparisons that preserve service-quality constraints. It is insufficient to demonstrate an energy reduction if that saving results from degraded coverage or lower network availability. Similarly, higher aggregate throughput is not necessarily a desirable outcome if latency, reliability or access for vulnerable users deteriorates. The relevant economic gain must be measured after the service requirements that the operator is obliged to maintain have been satisfied.
AI-and-RAN: computational multiplexing and the problem of stranded capacity
The economic rationale for sharing accelerated computing resources rests on the possibility that workloads with different demand patterns can use the same physical infrastructure more efficiently than separate dedicated systems. A conventional network may reserve processing capacity for peak traffic even when actual demand is much lower during substantial parts of the day. If unused capacity can serve additional applications without affecting radio performance, the operator may obtain greater value from equipment already installed.
This resembles the economic logic of resource pooling in cloud infrastructure, but telecommunications introduces constraints that make the comparison imperfect. Ordinary cloud services often tolerate workload queuing, temporary performance variation or application-level scaling mechanisms. Radio processing must satisfy deadlines associated with the communications system’s timing structure. Therefore, spare capacity cannot be identified simply by observing that average GPU utilisation is low. Some resources must remain available to respond to sudden radio demand, hardware failures and variations in processing complexity.
The central economic variable is usable, contractually available accelerator capacity, not theoretical idle compute. A GPU that appears lightly loaded may still have insufficient predictable capacity for an inference service requiring a strict response-time commitment. Likewise, an AI inference application with unpredictable memory and processing requirements may consume resources in ways that interfere with radio functions unless the infrastructure provides robust partitioning.
The interaction between memory availability and computing utilisation is particularly important. Modern inference systems may require substantial memory capacity to hold model parameters and intermediate data. Even when the accelerator’s mathematical processing units are not fully utilised, its memory may already be committed. A second application may consequently require a separate accelerator or the costly loading and unloading of models. This limits the circumstances in which theoretical resource-sharing gains translate into real consolidation benefits.
Operators must also account for different workload priorities. Radio processing will generally require stronger protection because its interruption can affect many subscribers simultaneously. AI applications may be paused, throttled or migrated when radio demand rises, but such behaviour can compromise the commercial service-level agreements promised to AI customers. If an operator compensates for this by reserving additional accelerator capacity, some of the anticipated consolidation savings disappear.
A further issue concerns the geographical relationship between demand and computing resources. AI inference may need to run close to a particular hospital, factory or transport facility, while radio-processing resources may be centralised at a location selected primarily for network-engineering reasons. The most efficient position for the radio network is not necessarily the most valuable location for AI services. Combining both functions on shared hardware is therefore most attractive when their geographic, latency and infrastructure requirements align.
AI-on-RAN: the commercial challenge of turning network locations into AI service markets
The third economic dimension involves the possibility that telecommunications operators can provide distributed AI services through computing infrastructure located within their networks. Such services may include enterprise analytics, industrial computer vision, local language processing, machine-generated content analysis, intelligent traffic management and other inference tasks where processing near the source of data has measurable advantages.
The commercial logic is strongest when local execution changes the quality, cost or regulatory characteristics of a service. A manufacturing facility may prefer local AI inference because transmitting continuous high-resolution video to a distant cloud facility is expensive or operationally undesirable. A healthcare organisation may require stronger data-locality protections. A logistics centre may need sufficiently predictable response times for time-sensitive operational decisions. In these cases, the telecommunications operator may already control or have access to useful infrastructure such as fibre connectivity, secure facilities and local networking expertise.
However, proximity does not automatically create a market. Many AI applications can tolerate execution in centralised data centres, which often benefit from greater economies of scale and more extensive computing infrastructure. Local AI services must therefore justify any additional cost arising from distributed hardware, maintenance, capacity reservation and fragmented resource utilisation. The operator must also compete against hyperscale cloud providers, specialist edge-computing companies, enterprise-owned servers and increasingly capable local devices.
One significant economic risk is that the computing environment may be installed before demand becomes sufficiently predictable. If an operator purchases accelerators based on anticipated inference revenues but customers do not commit to long-term service agreements, it may hold expensive and depreciating infrastructure with limited productive use. This risk is amplified by rapid changes in AI hardware performance and software efficiency, which may reduce the commercial value of a particular accelerator generation before the end of its physical operating life.
The most defensible commercial strategy is therefore likely to begin with identifiable demand rather than speculative universal edge deployment. Industrial campuses, transport hubs, large hospitals and dense commercial areas may provide more credible early markets than geographically uniform installation across an entire national radio network. This does not mean that other deployments will fail; it means that their profitability must be established through location-specific evidence.
Electricity consumption, cooling and the infrastructure cost of accelerated radio processing
Electricity is one of the most important determinants of accelerated infrastructure economics. The introduction of GPUs into telecommunications facilities changes both processing power demand and the thermal environment in which network equipment operates. Radio installations already consume electricity for transmission equipment, baseband processing, transport interfaces, control systems and environmental management. Accelerated computing adds hardware whose electricity consumption depends on its configuration, utilisation and software behaviour.
The cost of operation must include more than the electrical demand of the accelerator itself. CPUs, memory, storage, networking equipment and power-conversion systems contribute to the total load. Cooling systems consume additional electricity, and their effectiveness depends on the building design, climate, airflow and equipment density. Facilities engineered for conventional telecommunications workloads may require electrical distribution upgrades, more advanced cooling arrangements or additional backup-power capacity before they can safely accommodate dense accelerator configurations.
A meaningful energy-efficiency comparison must use a clearly defined output. Measuring energy per radio traffic unit can reveal whether a new architecture delivers connectivity more efficiently. Measuring energy per AI inference can indicate the cost of local computing services. Measuring the combined output of both services requires a carefully specified accounting convention, because data transmission and AI inference are different products. Aggregating them into an undefined notion of computational efficiency would obscure rather than clarify the investment decision.
Idle consumption also matters. A high-performance accelerator may remain powered during periods when neither radio processing nor inference demand approaches its capacity. Consolidation can be attractive if the operator can place unnecessary resources into low-power states without compromising radio readiness. But powering down equipment too aggressively can introduce unacceptable service recovery delays, particularly when future traffic demand is difficult to predict.
The design of redundant systems creates another trade-off. Telecommunications operators cannot evaluate infrastructure solely under normal operating conditions. Additional resources may be required to maintain service when a server fails, a software update is unsuccessful or electrical equipment becomes unavailable. These resources may be economically unproductive during ordinary operation but essential to meeting service obligations.
The site-level economic comparison should therefore include the energy consumed by all equipment necessary to deliver a defined telecommunications service under the required resilience standard. A demonstration of lower accelerator energy per computation does not prove lower network energy consumption if the deployment also requires additional servers, networking equipment, cooling, transport capacity or standby resources.
The financial model: total cost of ownership rather than component-level savings
AI-RAN procurement must be assessed across the entire useful operating period of the infrastructure. The relevant capital expenditure includes accelerated servers, host processors, memory, network interfaces, switching equipment, fibre upgrades, power distribution, cooling systems, redundancy, integration and site modification. Operating expenditure includes electricity, facility maintenance, software support, security monitoring, equipment replacement, network operations and the personnel required to maintain a more complex computing environment.
To assess the investment defensibly, these costs must be compared against an alternative architecture delivering equivalent coverage, quality of service, resilience and useful capacity. A comparison that assumes superior performance for the new system without holding service conditions constant cannot establish economic superiority. Similarly, comparing the cost of an accelerated server with the purchase price of a conventional baseband unit ignores the transport, operating and maintenance consequences of architectural change.
The calculation must also consider the remaining value of existing infrastructure. Operators have already invested in radios, baseband equipment, fibre, site facilities and software systems. Replacing equipment before the end of its economically useful life can create stranded capital, even when a new system offers lower operating expenditure. A gradual migration may be financially preferable to an immediate national replacement because it allows new infrastructure to be introduced at sites where traffic growth, equipment renewal or new customer demand already justify investment.
A critical distinction concerns the treatment of anticipated AI revenue. Revenue that has not yet been supported by contracts, demonstrated customer demand or measurable willingness to pay should not be used as though it were an established offset against infrastructure cost. The financial model can include scenarios for future services, but its base case should remain defensible without assuming that every deployed accelerator will become a profitable inference platform.
The following assessment framework separates the principal cost and revenue variables without creating artificial market forecasts.
Chapter 2 — Infrastructure economics and investment assessment
| Economic variable | Required measurement | Principal value mechanism | Main downside exposure |
|---|---|---|---|
| Radio spectral efficiency | Delivered traffic per unit spectrum under defined conditions | More productive use of licensed frequencies | Gains may be limited to specific environments |
| Uplink processing performance | Throughput, errors and processing cost under matched tests | Better utilisation of existing network capacity | Additional inference overhead |
| Accelerator utilisation | Useful compute occupancy over time, including peak reserves | Improved hardware productivity | Idle capacity and scheduling conflicts |
| RAN processing cost | Full cost per supported capacity under equivalent service conditions | Potential consolidation of processing infrastructure | Expensive accelerators and system integration |
| Fronthaul investment | Transport capacity, latency, synchronisation and route redundancy | Enables functional centralisation | Fibre costs and shared failure exposure |
| Energy efficiency | Total system energy per comparable service output | Potential operational savings | Higher server and cooling demand |
| Edge inference revenue | Contracted usage, utilisation, service pricing and customer retention | New commercial income | Insufficient demand and rapid hardware depreciation |
| Network reliability | Availability and recovery under specified fault scenarios | Reduced outage exposure and stronger service quality | Concentrated infrastructure dependencies |
| Software and support | Licence fees, updates, engineering effort and maintenance | Operational automation and programmability | Vendor lock-in and continuing software costs |
| Equipment lifecycle | Depreciation, replacement, remaining asset value and upgrade frequency | Optimised investment timing | Premature replacement and stranded assets |
| Security expenditure | Assurance, monitoring, segmentation and incident-recovery costs | Lower cyber and operational risk | Added complexity and supplier dependencies |
| National deployment economics | Geographic variation in costs, usage and demand | Selective investment where value is highest | Uneconomic uniform deployment |
Why location will determine the profitability of AI-RAN
The economics of AI-RAN will differ sharply between geographic markets because the value of radio capacity and local compute is not uniform. In a dense metropolitan network, operators may face sustained spectrum congestion, relatively strong demand for enterprise computing and existing fibre infrastructure capable of supporting centralised processing. These conditions can favour accelerated infrastructure, although the high price of electricity, facility space and resilient cooling may offset part of the benefit.
In industrial areas, the most important economic driver may be the value of applications rather than the volume of consumer mobile traffic. Industrial computer vision, local monitoring and operational analytics can justify investment in computing capacity even where ordinary subscriber demand would not. However, the facility owner may prefer to operate its own private computing infrastructure, and telecommunications operators must demonstrate why an integrated network-compute service offers better value than a separate local server.
Rural environments present a different challenge. Lower population density can reduce demand for both radio capacity and commercial edge inference. Facilities may have limited fibre connectivity, insufficient electrical infrastructure or higher maintenance costs. The economic advantage of sharing accelerated resources becomes less certain when the hardware cannot be sufficiently utilised. In such cases, purpose-built equipment or a hybrid architecture may remain preferable.
National governments should be particularly attentive to this geographic variation because public-service objectives do not always coincide with private-sector investment incentives. A commercially optimised deployment strategy could concentrate advanced intelligent infrastructure in economically attractive regions while providing fewer benefits to remote communities. Universal connectivity obligations, public procurement, infrastructure-sharing arrangements and targeted support may therefore remain necessary to prevent a new divide between regions with local AI computing capacity and regions dependent on distant services.
The limits of the commercial evidence available in October 2026
The public record establishes that important technical demonstrations have occurred and that several operators have announced further field activity. It does not provide a sufficiently standardised set of commercially audited operating figures to calculate a defensible global payback period, average national deployment cost or universal energy-efficiency advantage for AI-RAN.
This absence matters because technical trials and investment announcements often measure different things. A laboratory throughput improvement cannot be directly compared with a network operator’s annual electricity bill. A successful shared-workload test does not disclose the long-term utilisation profile of an accelerator installation. A vendor’s announced spectral-efficiency target does not establish the amount of future capital expenditure an operator can avoid.
The evidence that would most materially improve the economic assessment consists of multi-quarter operational data comparing AI-RAN with alternative architectures under equivalent traffic loads, radio conditions, quality-of-service obligations and resilience requirements. Such data would need to include capital expenditure, software costs, power and cooling consumption, accelerator utilisation, hardware failure rates and the realised revenue associated with AI services.
Until those comparisons become available, the most defensible economic judgment is that AI-RAN offers several credible but conditional value mechanisms. Radio optimisation may deliver measurable benefits in selected circumstances; accelerated computing may improve infrastructure utilisation where workloads complement one another; and distributed inference may create new markets where local processing offers a demonstrable advantage. The commercial success of the architecture will depend on whether these benefits exceed the full costs of deployment and operation, rather than on the technical novelty of executing radio functions on AI-capable servers.
Key judgment: The economic case for AI-RAN is strongest when operators can combine verified radio improvements with predictable demand for computational services, sufficient accelerator utilisation and infrastructure already capable of supporting high-density computing. It is weakest where radio traffic is modest, edge AI demand is uncertain, transport upgrades are expensive or resilient operation requires substantial additional standby capacity.
What would change the assessment: Audited evidence of lower total cost of ownership, economically significant contractual demand for local AI inference, high utilisation without radio-performance degradation and lower total system energy consumption would support faster commercial adoption. Persistently high infrastructure costs, uncertain application revenue or rapid accelerator obsolescence would strengthen the case for hybrid architectures and selective investment.
Chapter 3 — From AI-RAN to 6G: Standards, Physical AI and the Network of 2030
The transition from artificial intelligence as a network enhancement to artificial intelligence as a network-design principle
The transition towards sixth-generation telecommunications introduces a more consequential architectural question than whether existing 5G infrastructure can execute artificial intelligence algorithms. The issue is whether future communications systems should be designed from the outset to coordinate radio transmission, distributed computing, intelligent decision-making and environmental sensing as interdependent capabilities. This constitutes a departure from the historical model in which each mobile generation was primarily distinguished by improvements in radio access performance, greater capacity, new frequency arrangements and expanded communications functionality. Although these characteristics remain essential, the emerging 6G framework also addresses the possibility that the network itself may become an active participant in processing and interpreting information.
The conceptual distinction between AI-enabled and AI-native telecommunications is important. An AI-enabled system introduces machine-learning algorithms into an architecture whose fundamental operating principles were established independently of those algorithms. An AI-native architecture, by contrast, is designed to accommodate artificial intelligence across relevant functional layers, including model execution, data collection, lifecycle management, resource coordination and operational control. This does not require every protocol or signal-processing operation to be performed by a neural network. It requires the architecture to recognise AI as a significant operational capability while retaining appropriate conventional control mechanisms.
The distinction also has implications for standards development. Commercial vendors may introduce proprietary AI-assisted features into existing 5G systems, but the long-term benefits of internationally interoperable 6G require common technical rules governing radio operation and the exchange of essential information between network components. The standardisation challenge is therefore to accommodate innovation without making interoperability dependent on one hardware supplier, software platform or machine-learning framework.
This is particularly difficult because artificial intelligence systems can evolve more rapidly than conventional telecommunications specifications. A radio protocol must retain compatibility with equipment operating across multiple manufacturers and national markets. AI models may be retrained, modified or replaced as conditions change. A standards architecture that requires one fixed model implementation could rapidly become obsolete, whereas an architecture permitting completely unconstrained model substitution may undermine interoperability and operational assurance. Future 6G specifications will have to address this tension through a combination of defined interfaces, functional requirements, lifecycle management and performance evaluation.
The ITU IMT-2030 framework and the technical meaning of sixth-generation connectivity
The International Telecommunication Union has established the principal international framework for future sixth-generation radio systems through Recommendation ITU-R M.2160-0, Framework and Overall Objectives of the Future Development of IMT for 2030 and Beyond, approved in November 2023. The recommendation identifies six usage scenarios encompassing immersive communication, hyper-reliable and low-latency communication, massive communication, ubiquitous connectivity, artificial intelligence and communication, and integrated sensing and communication.
The inclusion of artificial intelligence and integrated sensing as explicit usage scenarios is particularly important. These capabilities broaden the possible purpose of telecommunications infrastructure beyond providing a communications channel between a device and a network. AI and communications integration concerns systems in which computational intelligence and connectivity support one another. Integrated sensing and communication concerns the potential use of radio infrastructure to support environmental sensing capabilities alongside communications. Both introduce new opportunities but also expand the technical, institutional and security requirements that must be addressed before deployment.
The ITU process has advanced considerably during 2026. In February, Working Party 5D completed draft technical-performance requirements containing 20 requirements for the evaluation of future IMT-2030 radio interfaces. In June, it completed draft evaluation guidelines defining simulation, analytical assessment and inspection as methods for examining candidate technologies. The evaluation framework identifies seven test environments, including new scenarios addressing industrial hyper-reliable low-latency communications and integrated sensing in industrial and urban settings. These documents had been submitted for consideration by the parent ITU-R Study Group 5, with approval anticipated in December 2026. Their development constitutes progress towards international evaluation, not evidence that commercial networks already satisfy the proposed performance levels. The relevant institutional account is provided in the ITU IMT-2030 programme documentation.
The differences between performance aspirations and deployable capabilities require particular attention. The ITU framework discusses peak data rates potentially reaching 50–200 Gbit/s under applicable scenarios, user-experienced data rates in the hundreds of megabits per second, spectral-efficiency improvements relative to IMT-2020, improved positioning accuracy and very low radio-network latency. These values are technical objectives and evaluation references associated with the future system. They do not establish the minimum experience every user will receive, nor should they be confused with end-to-end latency between an application and a distant computing facility.
Chapter 3 — IMT-2030 technical reference values and their interpretation
| Technical dimension | IMT-2030 framework reference | Relevant engineering question | Interpretation for AI-RAN and 6G |
|---|---|---|---|
| Peak data rate | 50–200 Gbit/s, scenario-dependent | Can the radio interface support substantially greater transmission capacity? | Future radio ambition; not a demonstrated AI-RAN throughput result |
| User-experienced data rate | 300–500 Mbit/s or higher in identified framework ranges | Can the system improve practical user performance? | Depends on coverage, spectrum, network load and device capabilities |
| Spectrum efficiency | 1.5–3 times the IMT-2020 reference range | Can more useful traffic be delivered using available spectrum? | AI-assisted processing is one possible contribution, not the sole mechanism |
| Area traffic capacity | 30–50 Mbit/s/m² or higher in relevant scenarios | Can dense environments support more simultaneous traffic? | Requires radio densification, transport and sufficient processing |
| Connection density | 10⁶–10⁸ devices/km² in framework ranges | Can very large numbers of devices be supported? | Application-specific; not equivalent to simultaneous maximum-rate connections |
| Mobility | Up to 500–1,000 km/h in framework ranges | Can connectivity be sustained under extreme movement? | Requires robust radio procedures and mobility management |
| Radio-network latency | 0.1–1 ms in stated framework ranges | Can selected radio operations meet extremely tight timing requirements? | Does not represent complete application-to-application latency |
| Radio transmission reliability | Reference success probabilities approaching 1 − 10⁻⁵ to 1 − 10⁻⁷ | Can radio delivery satisfy demanding service classes? | Requires defined traffic conditions and measurement methods |
| Positioning | Approximately 1–10 cm in relevant framework aspirations | Can radio infrastructure support more precise location services? | Environment-dependent and subject to technical and privacy constraints |
| Integrated sensing | Detection, localisation, mapping and related functions | Can communication infrastructure support environmental sensing? | Research and standards-development domain |
| AI integration | Model execution, distributed learning and intelligent operation | How should AI interact with network resources? | Requires interoperable architecture and trustworthy governance |
These values are drawn from the ITU’s IMT-2030 programme framework and describe prospective capabilities across different scenarios. They are not simultaneous guarantees for one device or deployment. The ITU’s 17 March 2026 technical requirements update separately records progress on the requirements that will be used to evaluate candidate radio technologies. Framework ranges, draft evaluation requirements and achieved commercial performance must remain distinct.
3GPP Releases 20 and 21: from exploratory research to international technical specifications
The 3rd Generation Partnership Project occupies a central position in translating future mobile-network concepts into detailed telecommunications specifications. The 3GPP process involves extensive technical work across radio interfaces, network architecture, protocols, security, management and interoperability. Its contribution is essential because a commercially interoperable mobile generation requires more than a high-performance radio demonstration. Devices, radio equipment, network software and core systems must implement sufficiently consistent procedures to operate across suppliers and markets.
The transition towards 6G is proceeding through Release 20 study activities and the development of subsequent normative specifications. Release 20 includes both continued 5G-Advanced work and studies addressing future 6G capabilities. Release 21 forms part of the progression towards normative sixth-generation specifications, although its precise content and completion sequence remain dependent on continuing technical decisions.
As of October 2026, the official 3GPP release register records Release 19 as frozen and Releases 20 and 21 as open. The distinction is important: a release being open does not mean that all its technical features are complete, nor that commercial equipment implementing those features is already available.
More specific evidence of the scope of the work appears in individual technical studies. The 3GPP TR 29.832 study on the protocol for artificial intelligence in 6G is identified as a draft Release 20 technical report. Similarly, work on the 6G non-access-stratum protocol and network-selection aspects of the 6G system demonstrates that the transition concerns the wider system rather than only its physical radio interface.
These records provide a more precise basis for analysing 6G progress than generic announcements of forthcoming commercial deployment. A draft study can establish that a technical issue is under formal consideration, but it cannot be represented as an approved interoperable protocol. The industry must move from identifying candidate capabilities to agreeing on specific interfaces and procedures, validating their performance and implementing them in commercial equipment.
The interaction between Release 20 and Release 21 also has important procurement consequences. Operators investing in AI-RAN during 2026 or 2027 cannot assume that today’s proprietary implementation will automatically satisfy the final requirements of future 6G specifications. Procurement agreements should therefore account for standards evolution, software upgrades, backward compatibility and the practical cost of modifying equipment or interfaces as normative specifications mature.
The long-term industrial opportunity lies in influencing the standards themselves. Companies participating in technical working groups can contribute technologies, intellectual property and implementation experience. Governments can support research and standards participation, but commercially sustainable influence requires technical contributions that other participants regard as useful and sufficiently interoperable. National preference alone cannot substitute for credible engineering.
AI-native radio functions: the limits of intelligent signal processing
Artificial intelligence may be incorporated into future radio systems through several distinct technical methods. Machine-learning models can support channel estimation, interference prediction, resource allocation or adaptation to changing propagation conditions. AI may also assist higher-level network control, mobility management and the identification of unusual operating patterns. These applications differ fundamentally in timing, data requirements and the consequences of incorrect decisions.
At the physical layer, a model may have to operate within extremely constrained processing intervals. It must therefore offer predictable inference latency and an acceptable relationship between performance gains and computational cost. Models deployed at higher control layers may operate over longer timescales and can incorporate a broader range of telemetry, historical observations and system-wide objectives. The practical architecture may consequently employ several forms of intelligence rather than one universal network AI.
This fragmentation is not necessarily a weakness. Different functions require different degrees of explainability, adaptation and deterministic behaviour. A signal-processing model performing a narrowly specified mathematical task can be assessed differently from an autonomous operational agent authorised to modify network parameters across thousands of sites. Treating both as identical artificial intelligence systems would produce an inadequate governance framework.
Future standardisation may also have to determine how models are updated and evaluated. Changes in model weights or training data can alter system behaviour even when the surrounding telecommunications software remains unchanged. This introduces a new type of configuration change: the operational characteristics of the network may change without modifications to conventional protocol code.
A trustworthy system should therefore maintain reliable records of model versions, training and validation procedures, deployment authorisations and observed performance. Operators need mechanisms capable of identifying deteriorating models and returning to established configurations when performance no longer meets service requirements. The ability to reverse an unsuccessful model deployment is particularly important when radio functions support hospitals, emergency services or industrial control environments.
Integrated sensing and communication: the expansion of the radio network’s purpose
Integrated sensing and communication is among the most strategically consequential concepts in the IMT-2030 framework because it broadens the possible role of radio infrastructure. Conventional cellular networks transmit signals designed to support communication between network equipment and connected devices. Future systems may investigate whether aspects of the transmitted and received signals can also provide information about the surrounding physical environment.
Depending on the implementation, sensing functions could potentially support object detection, movement estimation, localisation or environmental mapping. The relevant techniques may use properties of radio propagation, reflected signals and spatially distributed observations. The concept is particularly attractive because communications infrastructure already possesses access to radio spectrum, antenna systems, processing facilities and geographically distributed installations.
Nevertheless, the technical and institutional obstacles are substantial. Sensing accuracy depends on radio frequency, bandwidth, antenna geometry, surrounding materials, propagation conditions and the availability of appropriate signal-processing methods. A system optimised primarily for communications may not provide the sensing performance achievable with a specialised radar or other dedicated sensor. The coexistence of sensing and communications must also be evaluated for interference, resource allocation and operational reliability.
The June 2026 ITU evaluation framework includes specific industrial and urban sensing test environments, confirming that the issue has progressed beyond a purely conceptual discussion. The ITU IMT-2030 evaluation programme identifies extended channel models, including near-field and spatially non-stationary propagation considerations, as relevant to future evaluation. Such models are necessary because systems attempting to infer information about the physical environment require an understanding of radio propagation that may be more detailed than that used for ordinary coverage planning.
From an infrastructure perspective, integrated sensing may create demand for additional processing close to the radio network. Environmental observations may produce substantial volumes of data, and local analysis could reduce the need to transport all raw information to distant data centres. AI-RAN therefore offers one possible computing architecture for future sensing applications.
This connection does not mean that current AI-RAN demonstrations establish operational 6G sensing capability. It means that accelerated distributed computing could become relevant to the implementation of such capabilities if future radio systems and standards support them.
Physical AI and the convergence of wireless communication, sensors and automated machines
Physical AI refers broadly to artificial intelligence systems interacting with the physical world through sensing, decision-making and, in some implementations, control of machines or other actuators. Its relevance to 6G lies in the possibility that future connected systems will require more than rapid delivery of information to a human user. They may need to coordinate industrial robots, moving vehicles, logistics equipment, infrastructure sensors and intelligent machines operating within shared physical environments.
This introduces a different relationship between telecommunications and computing. In an ordinary mobile application, network delay may primarily affect convenience or responsiveness. In a robotic system, delay or communication failure can influence the behaviour of a machine interacting with people, equipment or valuable infrastructure. Network performance becomes one component of a larger control and safety problem.
The combination of distributed computing and advanced radio systems could support architectures in which machines retain local safety-critical control while obtaining additional intelligence from nearby network resources. A robotic device might execute essential motion control locally while using external inference to interpret complex images, coordinate tasks or receive noncritical environmental information. Such an arrangement could benefit from proximity-based computing without requiring the telecommunications network to become the sole controller of a safety-critical process.
This distinction is essential. A network promising very low radio latency does not automatically guarantee that an AI model can produce a safe decision within the same interval. Total response time includes sensor acquisition, data preparation, transmission, network processing, inference, decision validation and any subsequent actuation. Some of these operations may dominate the timing budget even when radio transmission is extremely fast.
The safety challenge is similarly broader than connectivity. A model may return an incorrect result while the network is functioning perfectly. A robot may act on outdated information despite low average latency. A communications link may be interrupted at an unexpected moment. Engineering systems therefore require local fail-safe behaviour, bounded dependence on remote processing and explicit methods for handling uncertainty.
For industrial and defence applications, the strategic significance of AI-RAN will depend on whether accelerated communications infrastructure improves the performance of these distributed systems without creating unacceptable dependencies. The potential is considerable, but its practical value must be established at the complete system level.
Terrestrial and non-terrestrial integration: intelligent connectivity beyond conventional cellular coverage
The future 6G framework also addresses ubiquitous connectivity, which raises questions about the integration of terrestrial networks with satellites and other non-terrestrial platforms. Such systems may improve connectivity in remote areas, maritime environments, transport corridors and locations where terrestrial infrastructure has been damaged or is economically difficult to deploy.
Non-terrestrial connectivity introduces conditions that differ substantially from conventional terrestrial radio links. Depending on satellite altitude, orbit and system architecture, propagation delays, Doppler effects, coverage geometry and mobility management may differ from those encountered in ordinary cellular networks. Satellite capacity and spectrum coordination also impose limitations that cannot be overcome simply by introducing artificial intelligence.
AI may assist with predicting changing link conditions, allocating resources or coordinating traffic across different network environments. Distributed processing may support local decisions, particularly where transport to distant central facilities is unreliable or costly. However, deploying intelligence across terrestrial and non-terrestrial networks requires interoperability among different suppliers, network domains, security frameworks and operating jurisdictions.
The wider geopolitical implications are material. Satellite systems and terrestrial telecommunications networks are governed by overlapping but distinct national and international arrangements. Infrastructure operators may need to coordinate spectrum rights, service authorisations, data protection and national-security requirements across multiple jurisdictions. The addition of AI-driven network management increases the importance of identifying which organisation is authorised to make operational decisions when a service moves between terrestrial and non-terrestrial domains.
The ITU’s IMT-2030 framework makes ubiquitous connectivity part of the future system’s objectives. It does not establish that all terrestrial and satellite systems will operate through a single AI-RAN architecture, nor that a future mobile generation will remove the physical and economic limitations of satellite communications.
Interoperability, intellectual property and the risk of competing 6G technology ecosystems
The international success of mobile telecommunications has depended heavily on the ability of equipment and devices from different manufacturers to operate within common technical frameworks. Interoperability allows operators to purchase equipment from multiple suppliers, enables device manufacturers to address international markets and reduces the economic fragmentation that would result from incompatible national mobile systems.
AI-native architectures create new interoperability challenges because intelligence may reside in different parts of the network and may depend on different software environments. Two systems can implement the same telecommunications protocol while relying on distinct model structures, accelerator libraries and operational-management procedures. Their conventional radio interfaces may interoperate while their AI-related functionality remains proprietary.
Several layers of interoperability consequently need to be considered. Radio-interface interoperability concerns communication between devices and networks. Network-function interoperability concerns the exchange of information between components supplied by different manufacturers. Computing portability concerns the ability to execute software across alternative hardware platforms. AI interoperability concerns the exchange of model-related information, control instructions and lifecycle data where required. Operational interoperability concerns whether different suppliers’ systems can be integrated, monitored, upgraded and recovered within a common network-management framework.
These characteristics should not be treated as equivalent. A system may support an open fronthaul interface while remaining heavily dependent on proprietary acceleration software. Another system may execute portable software but use AI models whose operational behaviour differs across implementations. Genuine industrial flexibility requires evidence covering the particular layers that an operator may need to replace or combine.
This creates strategic consequences for the global telecommunications industry. Semiconductor suppliers may seek to establish broadly adopted computing platforms. Telecommunications vendors may compete through radio algorithms, software integration and standards contributions. Cloud providers may attempt to extend their operational platforms into distributed network facilities. Mobile operators may seek to preserve negotiating power by demanding interoperability and avoiding unnecessary dependence on a single computing ecosystem.
The eventual structure of 6G competition may therefore be influenced by decisions taken before final standards are agreed. Early investments in proprietary infrastructure can establish expertise and accelerate deployment, but they can also increase migration costs if later interoperability requirements differ. Public procurement and national research programmes should accordingly distinguish between financing technological innovation and creating dependencies that would be costly to reverse.
Sustainability as an engineering requirement rather than an assumed outcome of AI optimisation
Environmental sustainability appears among the guiding principles of IMT-2030, but the relationship between advanced computing and network energy efficiency requires careful analysis. AI-assisted radio optimisation may reduce unnecessary transmissions, improve resource allocation or allow selected equipment to operate in lower-power states. At the same time, more advanced processing, additional sensors and distributed inference infrastructure may increase total electricity demand.
The correct assessment must consider the system as a whole. A reduction in energy per transmitted data unit is valuable, but absolute network energy consumption may still rise if traffic volumes and computing workloads increase substantially. Similarly, moving an AI service from a distant cloud facility to a local telecommunications site may reduce transport requirements while increasing electricity and cooling demand at that site.
Lifecycle effects are also important. Manufacturing high-performance semiconductors, servers and associated equipment consumes materials and energy. Accelerated hardware may become commercially obsolete faster than traditional telecommunications infrastructure if software requirements or competitive processing capabilities evolve rapidly. The resulting replacement cycle affects the environmental and financial consequences of deployment.
A sustainable 6G architecture must therefore be evaluated through transparent measurements of operational energy, equipment utilisation, service output, replacement requirements and the relevant lifecycle boundaries. Claims of energy efficiency should distinguish reductions in energy per unit of work from reductions in total consumption. They should also disclose whether comparisons include the full supporting infrastructure.
For public authorities, sustainability should become a measurable procurement criterion rather than a general description of technological progress. The most efficient architecture may differ by site density, electricity conditions, climate, network topology and application demand. A flexible mix of specialised and accelerated processing may consequently produce better outcomes than uniform deployment of a single platform.
The 2027–2031 transition: what must occur before AI-RAN becomes an established component of 6G
The period between 2027 and 2031 will be decisive because it brings together two separate processes: the commercial validation of accelerated AI-RAN architectures and the continuing development of international 6G specifications. These processes influence one another but do not share an identical timeline. Operators can introduce AI-RAN features into existing 5G networks before 6G standards are finalised, while future 6G equipment may use a combination of technologies developed through several competing research and industrial programmes.
The first requirement is sustained operational evidence. Field deployments must demonstrate that accelerated radio processing can preserve network quality under realistic traffic demand, concurrent AI workloads, hardware failures and software updates. The second requirement is economic validation. Operators need credible measurements showing whether increased computational flexibility generates sufficient operational savings or new revenue to justify additional investment. The third requirement is interoperability. The architecture must accommodate standards evolution and avoid commercially prohibitive dependence on proprietary components.
The fourth requirement concerns governance and security. AI-native systems introduce more complex software supply chains, additional management interfaces and new model-related vulnerabilities. Their integration into critical infrastructure will require procedures for independent security assessment, configuration management, fault isolation and reliable recovery. The fifth requirement is international technical coordination. Standards bodies, manufacturers and operators must resolve how emerging capabilities can be implemented consistently across different national and industrial ecosystems.
These requirements are not sequential stages in which one can be ignored until the preceding stage is complete. Commercial trials may inform standardisation, while standardisation may reveal limitations in current hardware or software implementations. Security evaluation may identify architectural changes that affect economics. Industrial procurement may create early demand but also expose gaps in interoperability. The transition will therefore involve repeated interaction between technical experimentation, commercial deployment and international governance.
The following table distinguishes the major institutional and industrial milestones without presenting forecasts as established results.
Chapter 3 — Standards and technology maturity, October 2026 to 2031
| Period | Documented position or prospective development | Institution or principal actors | Technical significance | Decision relevance |
|---|---|---|---|---|
| November 2023 | IMT-2030 framework approved | ITU-R | Establishes the international vision and usage scenarios | Provides a common framework for research and policy |
| February 2026 | Draft IMT-2030 performance requirements completed at working-party level | ITU-R WP 5D | Defines the basis for future technical evaluation | Distinguishes candidate capabilities from unsupported performance claims |
| June 2026 | Draft evaluation guidelines completed | ITU-R WP 5D | Defines evaluation methods and test environments | Supports future comparability across candidate radio technologies |
| October 2026 | Commercial-network AI-RAN call and further European field activity announced | NVIDIA, Nokia and operators | Demonstrates selected accelerated radio-processing and shared-workload capabilities | Supports continued trials, not automatic network-wide investment |
| 2027 | Announced AI-RAN field trials and continued standards work | Participating operators and 3GPP | Opportunity to evaluate operational scale and emerging technical specifications | Establish procurement evidence and technology risks |
| 2028–2029 | Potential maturation of interoperability and commercial deployment evidence | Standards bodies, operators and suppliers | Possible narrowing of architectural alternatives | Influence supplier selection and investment timing |
| 2030–2031 | Prospective early commercial 6G implementations | International telecommunications ecosystem | Possible transition from standards development to initial deployment | Assess network readiness, affordability, security and international compatibility |
The entries from 2028 onward describe conditional developments rather than confirmed implementation schedules. Their achievement depends on technical agreement, commercial investment, equipment availability and successful system validation.
The geopolitical consequence: the future telecommunications system becomes a contest over computing architecture
The technological transformation described in these three chapters alters the relationship between communications infrastructure and economic power. Historically, a country seeking resilient telecommunications capabilities concentrated on access to spectrum, national network coverage, radio-equipment supply, secure core systems and international connectivity. These remain essential, but distributed AI introduces additional dependencies involving accelerator manufacturing, software execution environments, model lifecycle management and the geographical availability of computing capacity.
The ability to operate advanced wireless infrastructure may therefore depend increasingly on access to specialised computing ecosystems. This creates opportunities for semiconductor and software companies to influence telecommunications architecture, procurement and technical innovation. It also creates opportunities for established telecommunications vendors to extend their activities into accelerated software and distributed intelligent services.
For countries seeking greater technological autonomy, the strategic challenge is not simply to establish domestic assembly or ownership of server infrastructure. The deeper requirement is to retain sufficient technical knowledge, operational access, interoperability and recovery capability to operate essential systems even when commercial relationships or international supply conditions change.
The United States, Europe and China enter this competition with different industrial strengths, market structures and technology-policy approaches. The resulting landscape may include interoperable international standards alongside continued competition over accelerators, software platforms and AI implementation methods. Effective participation in standards bodies can reduce fragmentation, but it cannot by itself eliminate dependencies within semiconductor manufacturing or proprietary computing environments.
Europe faces a particularly important architectural choice because its telecommunications equipment suppliers and network operators possess substantial expertise in radio systems, while advanced AI computing introduces additional external technology dependencies. European industrial competitiveness will therefore depend on the ability to combine radio engineering, software portability, semiconductor access, secure infrastructure and commercially relevant AI applications. The outcome cannot be determined solely by the nationality of the supplier providing an accelerator or server. It must be assessed through the distribution of intellectual property, development capabilities, operating authority, financial returns and security control across the complete system.
A network may be geographically located in Europe while depending heavily on external hardware, software updates and proprietary execution environments. Conversely, an international supply chain does not automatically eliminate operational sovereignty if the network operator retains effective technical control, auditable security and workable substitution options. This distinction will become increasingly important for telecommunications policy, defence procurement and critical infrastructure regulation.
Final technical assessment of Pillar I
The development of AI-RAN reveals a structural convergence between three industries that previously operated with more distinct engineering and commercial priorities: telecommunications, accelerated computing and artificial intelligence. The first is concerned with reliable and economically sustainable communication. The second provides programmable computational resources with increasing levels of parallel processing capability. The third introduces methods for extracting information, making predictions and supporting decisions through learned models. Their convergence could change how networks are built, where computing resources are located and which companies capture value from digital infrastructure.
The October 2026 commercial-network milestone establishes that this convergence is technically feasible in a meaningful operational setting. Laboratory results involving AI-assisted channel estimation suggest that selected radio functions can benefit from learned processing methods. Concurrent-workload demonstrations provide early evidence that radio and AI applications can operate on shared accelerated platforms. The ITU and 3GPP processes show that future mobile systems are being developed with greater attention to artificial intelligence, sensing and advanced connectivity.
None of these developments, considered individually or together, establishes that AI-RAN has already demonstrated universal economic superiority, that the entire telecommunications network can be made autonomous without significant new risks, or that existing commercial demonstrations satisfy prospective sixth-generation performance requirements.
The long-term significance instead lies in the possibility of creating a new class of infrastructure in which communications and computing are engineered as closely related services. Such infrastructure could support more adaptable radio processing, distribute selected AI capabilities across geographically dispersed facilities and enable future applications requiring closer coordination between physical systems and digital intelligence.
The determining constraint will be the ability to preserve the characteristics that make telecommunications infrastructure essential: predictable service, interoperability, technical accountability, resilience, security and affordability. A system that provides more computational intelligence but becomes excessively expensive, difficult to recover or dependent on non-substitutable components would represent an ambiguous advance. A system that improves radio productivity, enables commercially valuable services and retains verifiable operational control would constitute a more substantial industrial transformation.
The central judgment of Pillar I is that AI-RAN should be treated as a potentially important architectural foundation for future intelligent networks, not as a completed replacement for conventional radio infrastructure or a finished implementation of 6G. Its strategic value will be determined by whole-system engineering results, commercial economics and interoperability rather than by accelerator performance or artificial intelligence capability considered in isolation.
The decisive transition between 2026 and 2031 will be from technical demonstrations and early deployments towards reproducible operational evidence and internationally compatible systems. Governments, network operators and industrial suppliers that distinguish those stages will be better positioned to make defensible infrastructure decisions. Those that treat announced performance targets or experimental integration milestones as equivalent to mature commercial capability risk allocating capital before the essential engineering, economic and governance questions have been resolved.
Key judgments
The technical record supports the conclusion that accelerated computing is becoming a credible execution environment for selected radio-access workloads. It also supports continued research into AI-assisted channel estimation, shared computing and distributed inference. It does not yet establish a universally superior network architecture.
The commercial case remains conditional on measurable value from spectrum productivity, computing utilisation or application demand after all relevant infrastructure and operational costs have been included.
The transition towards IMT-2030 expands the technical objectives of telecommunications to include closer integration with artificial intelligence and environmental sensing. Achieving these objectives requires standards development, interoperability, deployment engineering and application-specific validation that extend well beyond the successful operation of an AI-RAN call.
The most strategically robust path is likely to preserve architectural flexibility while field evidence accumulates, allowing accelerated systems and specialised telecommunications equipment to coexist where their respective performance, economic and resilience characteristics justify their use.
What would change the assessment
The strongest positive evidence would consist of independently reproducible production-network measurements showing improved total system efficiency, stable telecommunications service under concurrent AI demand, commercially meaningful demand for distributed inference and demonstrable interoperability across different computing suppliers.
The strongest negative evidence would be repeated failure to maintain predictable radio-processing performance under shared workloads, unacceptable operating costs, energy or cooling requirements that limit site deployment, or software dependencies that make practical supplier substitution prohibitively expensive.
A further decisive development would be the emergence of sufficiently mature 6G specifications establishing how AI-enabled radio functions, sensing capabilities, model management and relevant interoperability arrangements should be implemented. Such specifications would not remove the need for commercial validation, but they could reduce uncertainty for equipment manufacturers and operators considering long-term infrastructure commitments.
Open official record
The most consequential information still required consists of representative multi-site AI-RAN performance data, detailed energy and total-cost comparisons, documented workload-isolation mechanisms, independently evaluated recovery procedures, and the progression of 3GPP and ITU technical studies towards stable and interoperable 6G specifications. These records would allow the current assessment to move from identifying credible engineering pathways to judging their operational and economic maturity.
PILLAR II — CYBERSECURITY, NATIONAL SECURITY AND SOCIETAL TRANSFORMATION
AI-Native Telecommunications, Strategic Vulnerability, Defence Transformation and the Future of Critical Civilian Infrastructure
Open-Source Strategic and Institutional Assessment | 23 October 2026 | Analytical Horizon: 2027–2031
Chapter 4 — Cybersecurity and the New Attack Surface of AI-Native Infrastructure
The security paradigm changes when telecommunications networks become shared computational environments
The cybersecurity consequences of AI-native radio access networks extend considerably beyond the introduction of another generation of software vulnerabilities. They concern a structural change in the relationship between trusted telecommunications functions, general-purpose computing infrastructure, artificial intelligence systems and the organisations authorised to operate them. As network operators explore architectures in which radio processing, intelligent optimisation and potentially third-party inference services can execute within shared accelerated-computing environments, they must protect systems whose operational priorities and security characteristics differ fundamentally. The resulting challenge is not simply to defend a new category of server. It is to prevent a compromise originating in one computing workload, software component or management environment from affecting essential communications services upon which governments, industry and citizens depend.
Traditional telecommunications networks have never been immune to cyberattack, nor have they been universally isolated from conventional information technology. Their security has historically depended on a combination of specialised network equipment, controlled management interfaces, protocol protections, operational segregation and tightly governed software configurations. Virtualisation has already weakened some of the assumptions associated with physical separation by allowing multiple network functions to operate on shared computing platforms. AI-RAN extends this evolution into computationally intensive workloads, potentially introducing additional device drivers, accelerator firmware, model-serving systems, container environments, inference frameworks and automated management agents into infrastructure supporting essential mobile communications.
The significance of the transition becomes clearer when examined through the earlier security experience of virtualised 5G networks. In its February 2022 report, NFV Security in 5G — Challenges and Best Practices, the European Union Agency for Cybersecurity identified 60 security challenges distributed across seven categories and proposed 55 technical, organisational and policy best practices. The categories included virtualisation and containerisation, orchestration and management, administrative access, interactions between new and legacy technologies, commercial and open-source software, supply chains and lawful interception. These findings do not constitute a quantitative assessment of AI-RAN security in 2026. They establish, however, that the risks created by shared infrastructure and software-defined network functions were already recognised before the incorporation of more sophisticated AI execution environments.
The fundamental security issue is the expansion of trust relationships. A radio network may trust a virtualisation platform to enforce separation between workloads, an accelerator driver to manage access to hardware, an orchestration system to allocate computing resources and an AI model to produce useful operational recommendations. Each relationship introduces a component whose compromise or malfunction could affect the confidentiality, integrity or availability of the wider system. Security failures may arise through conventional software exploitation, compromised administrative credentials, malicious updates, insufficient isolation or incorrect automated decisions. Some failures require an external attacker; others can result from configuration mistakes, uncontrolled resource contention or software defects.
The consequences are unusually significant because telecommunications networks are enabling infrastructures. A disruption can propagate beyond telephone calls or mobile broadband access into payment systems, emergency communications, logistics, transportation coordination, industrial monitoring and public services. When a common accelerated-computing platform supports radio functionality and commercial AI applications, the security consequences of a computing incident must be evaluated against the essential services that share the underlying resources. This creates a strong argument for treating AI-RAN security as a form of national infrastructure assurance rather than merely as an enterprise cybersecurity problem.
The central institutional distinction is between protecting the confidentiality of information, preserving the integrity of network behaviour and maintaining the availability of essential services. These objectives may require different controls. Strong encryption can protect information in transit without preventing resource exhaustion. Software attestation can help identify authorised components without demonstrating that their operational decisions are correct. Network segmentation can restrict lateral movement without guaranteeing that shared electrical infrastructure or acceleration resources will remain available. A defensible architecture must address all three dimensions through coordinated technical and organisational measures.
GPU security, accelerator firmware and the emergence of shared-hardware trust boundaries
Accelerator-based infrastructure introduces an additional security layer whose significance derives from the relationship between hardware access, device drivers, shared memory and workload execution. A GPU is not simply a mathematical coprocessor detached from the surrounding computing environment. It relies on firmware, a host operating system, drivers, runtime libraries and management interfaces that collectively determine which processes may execute, what memory they can access and how hardware resources are allocated. These components introduce security boundaries between the accelerator and the host, between different applications using the device, and between operational management systems and the workloads being managed.
The risks associated with a compromised accelerator environment can be organised into three broad categories. The first concerns unauthorised access to information. If the isolation mechanisms governing accelerator memory or host-device data transfers fail, information belonging to one workload could potentially become accessible to another. The second concerns execution integrity. A vulnerable driver, runtime component or privileged management service could allow an attacker to interfere with processes executing on the accelerator or with the host operating system. The third concerns availability. A malfunctioning or deliberately abusive workload could monopolise resources, trigger instability or prevent time-critical applications from obtaining the computing capacity they require.
For AI-RAN, these are not equivalent risks. Unauthorised access to commercial inference data may create a confidentiality incident. Unauthorised modification of a network-management process may affect radio configuration. Resource exhaustion affecting a time-sensitive signal-processing function could degrade communications for subscribers who have no relationship with the compromised application. The architecture must therefore avoid assuming that a workload is harmless merely because it does not directly access telecommunications control interfaces.
A shared accelerated-computing environment should be evaluated according to the strength of its actual isolation mechanisms. Process isolation, container isolation, virtual-machine separation, accelerator partitioning and physical hardware separation offer different security properties. They should not be treated as interchangeable. A container generally depends on the host kernel and relevant runtime components; a virtual machine introduces a hypervisor boundary but still relies on shared physical hardware and management mechanisms. Hardware-assisted partitioning may improve separation where properly supported, yet its effectiveness must be established for the specific device, driver, firmware version and workload configuration.
The choice between these mechanisms has consequences for performance. Stronger isolation can consume additional resources or restrict sharing. The greatest theoretical efficiency may be achieved through aggressive resource pooling, while the strongest operational separation may require dedicated accelerators or physically distinct facilities. Telecommunications operators must therefore decide which forms of consolidation are compatible with their critical-service obligations. There is no universal requirement that all AI workloads share the same physical accelerator as radio processing simply because the hardware platform is capable of supporting both functions.
A further complication is the management of firmware and driver updates. Security patches can reduce exposure to known vulnerabilities, but updates to low-level hardware interfaces can also change performance, compatibility or system behaviour. In an ordinary enterprise environment, a problematic update may interrupt a limited number of applications. In a telecommunications aggregation facility, an unsuccessful update could affect multiple network functions simultaneously. Secure update mechanisms consequently require cryptographic integrity verification, controlled deployment, testing against representative radio workloads and reliable rollback procedures.
For infrastructure designated as nationally critical, the operator should retain the ability to identify the exact versions of accelerator firmware, drivers, libraries and management software operating within each production environment. The absence of that visibility makes it difficult to determine exposure when a new vulnerability is disclosed, complicates incident investigation and creates uncertainty over whether a compromised component has actually been removed.
Hypervisors, containers and the risk of crossing virtualisation boundaries
Virtualisation introduces significant operational flexibility because software functions can be deployed, migrated, replicated and managed independently of particular physical appliances. It also creates a security problem associated with the concentration of trust in common infrastructure layers. If a hypervisor or other privileged virtualisation component is compromised, the attacker may be able to affect multiple workloads that were intended to remain isolated. The same principle applies to container-management infrastructure where privileged access or misconfiguration permits interference across application boundaries.
The earlier ENISA assessment explicitly identifies virtualisation and multi-tenancy as major security concerns for 5G networks. This finding becomes more consequential in AI-RAN environments because a shared host may contain applications with different owners, data classifications and operational responsibilities. A commercial edge inference service, for example, should not be able to modify a telecommunications scheduling process, obtain subscriber-related information or interfere with the execution of protected radio functions. Even where the software components are independently secure, weaknesses in common orchestration or management systems can undermine their separation.
The most consequential attack path may involve privileged control rather than direct exploitation of a radio protocol. An attacker gaining administrative access to a container orchestration system could potentially change software images, modify resource allocations, extract secrets or interfere with operational workloads. Similarly, compromised credentials used for infrastructure management can allow malicious activity to appear as authorised configuration changes. The ability to distinguish legitimate administration from malicious use of authorised privileges becomes central to effective defence.
A robust deployment consequently requires separation between infrastructure-management identities, radio-network administration, commercial AI application management and security monitoring. Privileged accounts should be narrowly scoped, strongly authenticated and subject to independently reviewable logging. Sensitive network configurations should not be modifiable through the same operational channels used by lower-trust customer applications. Where shared physical infrastructure remains necessary, administrative segregation becomes an essential compensating measure.
The European experience also illustrates the difficulty of assigning responsibility across suppliers. A software vendor may develop a network function, a server manufacturer may supply the host hardware, a third party may maintain the acceleration environment and the operator may be responsible for service continuity. When an incident spans these layers, contractual ambiguity can delay containment. Security architecture must therefore be accompanied by explicit obligations concerning vulnerability notification, patch availability, forensic assistance, incident reporting and recovery support.
Adversarial machine learning: how malicious data and manipulated models can influence network behaviour
The addition of machine-learning systems introduces security concerns that differ from conventional software exploitation. Traditional attacks frequently seek to exploit programming defects, bypass authentication or obtain unauthorised execution privileges. Adversarial machine-learning attacks may instead target the relationship between the model, the information it receives and the decisions it produces. A model can operate exactly as programmed yet generate incorrect outputs because its inputs have been manipulated or because its training process has been compromised.
The National Institute of Standards and Technology’s March 2025 report, Adversarial Machine Learning: A Taxonomy and Terminology of Attacks and Mitigations, establishes a framework for analysing attacks involving evasion, poisoning, privacy compromise and misuse across different forms of machine learning. Its significance for AI-RAN lies in distinguishing malicious manipulation of model behaviour from attacks against the conventional software platform hosting the model.
Consider a hypothetical network-optimisation system using historical telemetry to estimate future congestion. If an attacker can influence the training data, the model may learn relationships that do not reflect genuine network demand. If the attacker can manipulate operational inputs, the model may produce inaccurate predictions even when its underlying parameters remain unchanged. If the model is authorised to make configuration changes automatically, the consequences of incorrect predictions may extend beyond a misleading analytical dashboard into actual network behaviour.
The precise risks depend on how the model interacts with the infrastructure. A recommendation system whose outputs must be reviewed by a network engineer has a different risk profile from an autonomous controller authorised to change operational parameters. A model assisting with offline capacity planning differs from a real-time optimisation system that directly influences radio scheduling or traffic priorities. Assessing AI security therefore requires an explicit description of the model’s operational authority.
Training-data poisoning is particularly difficult to detect when the resulting changes are small, gradual or statistically plausible. A model may continue to perform acceptably under routine testing while behaving poorly under selected conditions. This creates a need for validation methods that extend beyond average predictive accuracy. Operators should assess performance across unusual traffic patterns, unexpected infrastructure failures and conditions materially different from those represented in the training data.
Evasion attacks create another challenge. A malicious actor may attempt to construct inputs that cause a model to misclassify an event, underestimate a threat or produce an undesirable operational recommendation. Where AI assists security monitoring, this could reduce the effectiveness of anomaly detection. Where AI assists network optimisation, it could cause inefficient resource allocation or unexpected service degradation. The relevant defensive objective is not the impossible elimination of every erroneous prediction, but the prevention of model errors from exercising uncontrolled authority over essential services.
Model theft and privacy attacks also have economic and institutional significance. Proprietary models may contain valuable industrial intellectual property, while training data may reflect sensitive operational information. Telecommunications telemetry can reveal patterns of network utilisation, equipment behaviour and potentially commercially sensitive information. A model trained on such data may expose information through poorly controlled outputs or interfaces even without direct access to the original training records.
The future AI-RAN security architecture must therefore treat data provenance, model validation, deployment authorisation and continuous monitoring as core infrastructure functions. Protecting the model file alone is insufficient if the information entering the model can be manipulated or if its outputs are allowed to trigger unsafe operational actions.
Autonomous network agents and the governance of machine-executed operational authority
Autonomous management agents represent a separate category of cybersecurity risk because they combine language or reasoning models with access to operational tools. A conventional monitoring system may identify a fault and generate an alert. A more capable AI agent may examine logs, query infrastructure inventories, recommend configuration changes, initiate diagnostics or request the execution of corrective commands. Such functions offer the prospect of reducing maintenance burdens and accelerating incident response, but they also introduce new pathways through which incorrect, manipulated or malicious instructions could affect critical infrastructure.
The central security concern is the boundary between information and authority. An AI agent may encounter network logs, incident tickets, vendor documentation, configuration files and externally supplied information. These materials can contain useful operational evidence, but they must not automatically be treated as authorised instructions. A malicious instruction embedded in a log entry or retrieved document could attempt to influence the agent’s subsequent behaviour. This form of prompt-injection risk is particularly consequential when the agent has access to powerful administrative tools.
The danger is not limited to deliberately malicious content. Models can misinterpret ambiguous instructions, construct incorrect explanations or propose inappropriate actions based on incomplete information. If an agent executes those actions without meaningful checks, an ordinary analytical error can become an infrastructure incident.
The appropriate control architecture separates the agent’s analytical capabilities from its authority to change production systems. An agent may be permitted to collect diagnostic information automatically while requiring explicit approval before modifying sensitive configurations. High-impact operations should be subject to deterministic policy checks that do not depend solely on the model’s own assessment of safety. Credentials should grant only the permissions necessary for the agent’s defined task, and those permissions should remain revocable without disabling essential network services.
The 15 April 2024 joint NSA, CISA and international-partner guidance on deploying AI systems securely provides an important institutional basis for these requirements. It addresses the secure deployment and operation of externally developed AI systems, including the protection of confidentiality, integrity and availability and the need for appropriate vulnerability management and monitoring.
For AI-native telecommunications, a further requirement is the ability to reconstruct automated decisions after an incident. Operators should retain records identifying the model and software versions involved, the information available to the agent, the actions proposed or executed, the permissions used and the resulting infrastructure state. Without that evidence, operational accountability becomes difficult, particularly when multiple agents and human administrators interact with the same system.
Software supply chains, vendor dependencies and the limits of conventional procurement security
The software supply chain of an AI-native telecommunications network is substantially more heterogeneous than the supply chain of a single integrated network appliance. It may include host operating systems, container images, infrastructure automation, accelerator drivers, computational libraries, radio-processing software, AI models, monitoring components and commercial or open-source dependencies. Each component can introduce vulnerabilities, licensing obligations and update requirements.
The principal supply-chain risk is not necessarily that an adversary compromises every component. A compromise of one sufficiently privileged dependency may provide access to a much larger environment. Similarly, an unmaintained library or insecure configuration can create a persistent vulnerability despite the presence of strong controls elsewhere in the network.
Software bills of materials can improve visibility into the components incorporated into a system, but they do not independently establish security. They must be connected to vulnerability-management procedures, build provenance, integrity verification and contractual obligations to provide timely updates. Model-related inventories also require information that conventional software inventories may not capture, including model provenance, versioning, deployment restrictions and relevant evaluation records.
The multinational character of the supply chain introduces an additional governance problem. An operator may purchase an integrated solution from a telecommunications supplier while depending indirectly on several semiconductor, software and cloud providers. Contractual responsibility must therefore extend beyond the immediate vendor relationship. Authorities responsible for critical communications need to understand which components are essential, which organisations can modify them and how long the network can continue to operate if access to external support becomes unavailable.
The strongest procurement arrangements should distinguish ordinary vendor support from capabilities required for national resilience. A commercial service agreement may provide acceptable maintenance under normal conditions but prove insufficient during a geopolitical crisis, export restriction or major coordinated cyber incident. Critical infrastructure planning must consider access to security patches, operational documentation, spare components and alternative recovery procedures under adverse conditions.
Zero-trust security, segmentation and the containment of failures across shared infrastructure
Zero-trust architecture is particularly relevant to AI-RAN because shared computing creates environments in which physical location is an inadequate basis for determining trust. A workload executing inside an operator-controlled facility should not automatically be granted access to other workloads or management systems. Access decisions should depend on verified identity, authorised purpose, device and workload integrity, and the specific resources being requested.
For an AI-native radio network, zero trust requires more than strong authentication for human administrators. Machine identities, service-to-service connections, workload credentials and automation agents must also be governed. Applications should receive narrowly scoped permissions, and sensitive management operations should require stronger controls than routine telemetry collection. Network communications should be segmented according to function and trust level, with special protection for management interfaces, subscriber-related information and critical radio processing.
Segmentation is particularly effective when it is designed around operational consequences rather than organisational convenience. Placing two applications into different virtual networks may reduce their direct communication, but it does not eliminate risks arising from shared hypervisors, device drivers or physical accelerators. Similarly, isolating management traffic does not automatically protect the underlying system against power loss or physical failure. Zero trust should therefore be treated as one component of a wider resilience strategy.
A useful operational distinction concerns the division between the service plane, control plane and management plane. Service-plane functions deliver the data traffic used by subscribers and applications. Control-plane functions coordinate network behaviour. Management-plane functions configure, monitor and maintain the infrastructure. Compromise of a management interface may permit changes that affect both service and control functions, making it a particularly sensitive target.
AI management introduces a further distinction between analytical access and execution authority. A model may need access to operational telemetry to identify faults, but that does not justify unrestricted access to configuration systems. Separating observation from action reduces the potential consequences of model compromise, prompt injection and incorrect inference.
Cyber incident response in an AI-native telecommunications environment
Incident response for accelerated telecommunications infrastructure must be designed around service continuity. Conventional enterprise containment procedures, such as disconnecting an affected server, may not be acceptable if the server is responsible for essential radio processing. The incident-response plan must therefore account for the operational importance of affected workloads and the availability of alternate processing resources.
A critical capability is the controlled transfer or restoration of radio functions following a computing-platform incident. Depending on the architecture, recovery may involve switching to redundant servers, restarting known-good software images, isolating commercial AI workloads or reverting to a more conventional processing configuration. These capabilities must be engineered and tested before deployment; they cannot be assumed merely because the software is virtualised.
AI-related incidents require additional investigative procedures. If a network model produces abnormal decisions, the operator must determine whether the cause was malicious input manipulation, compromised model files, defective training data, software failure or legitimate but unfamiliar operating conditions. These possibilities require different responses. Replacing a model may resolve one problem while destroying evidence needed to understand another.
Forensic readiness is therefore important. Logs should preserve relevant model versions, configuration changes, access events and workload interactions. Where privacy or national-security restrictions apply, the collection and retention of evidence must remain proportionate and legally authorised.
The principal objective is to ensure that security containment does not create a more serious communications failure than the original incident. This requires coordination between cybersecurity personnel, radio engineers, infrastructure operators and emergency management teams. A network-security team acting without awareness of telecommunications timing requirements could inadvertently disrupt essential services, while a radio operations team focused exclusively on service restoration could compromise forensic integrity or reintroduce a vulnerable component.
Chapter 4 — Cybersecurity risk and control matrix
| Security domain | Principal failure or attack mechanism | Consequence for AI-native infrastructure | Required control | Evidence of effective implementation |
|---|---|---|---|---|
| GPU and accelerator firmware | Compromised firmware, unsafe privileged interfaces | Unauthorized computation or disruption | Verified firmware, controlled access and patch governance | Firmware inventory, security tests and attestation results |
| Hypervisor | Privilege escalation or isolation failure | Cross-workload compromise | Hardened virtualisation, restricted administration | Independent isolation testing and monitored privileged access |
| Container infrastructure | Compromised images or orchestration credentials | Malicious deployment or resource manipulation | Signed images, admission controls, limited permissions | Deployment records and policy-enforcement tests |
| Shared accelerator resources | Resource exhaustion or interference | Missed radio deadlines and service degradation | Resource reservation, scheduling controls, admission limits | Peak-load and fault-injection results |
| Training data | Data poisoning or manipulated telemetry | Corrupted model behaviour | Provenance, validation, anomaly detection | Data-lineage records and adversarial evaluations |
| AI inference | Crafted inputs causing incorrect predictions | Misallocation or unsafe recommendations | Robustness testing and bounded control authority | Performance under adversarial and out-of-distribution conditions |
| Model supply chain | Malicious or unauthorised model replacement | Persistent manipulation of network decisions | Model signing, version governance, approval workflow | Reproducible model inventory and integrity records |
| Autonomous agents | Prompt injection or excessive privileges | Unauthorised configuration changes | Tool restrictions, human approval and deterministic policy checks | Action logs and prohibited-operation tests |
| Management plane | Credential compromise or abuse | Large-scale infrastructure manipulation | Privileged-access controls and independent monitoring | Access reviews and incident simulations |
| Supplier updates | Malicious or defective software packages | Multi-site operational disruption | Staged updates, integrity checks and rollback | Recovery exercises and deployment audit trails |
| Subscriber and enterprise data | Leakage between tenants or services | Privacy breaches and commercial exposure | Strong separation, encryption and minimisation | Access-control testing and privacy assessments |
| Physical infrastructure | Power, cooling or facility failure | Regional communications disruption | Geographic redundancy and protected backup systems | Recovery-time measurements under realistic faults |
The matrix represents an analytical synthesis of the security mechanisms identified in the ENISA NFV security assessment, the NIST adversarial machine-learning taxonomy and the NSA-led secure AI deployment guidance. It is not a register of confirmed attacks against commercial AI-RAN installations.
European cybersecurity obligations and the governance of intelligent telecommunications
The European regulatory environment provides an important institutional framework for evaluating AI-native infrastructure, although no single European instrument resolves every AI-RAN security question. Directive (EU) 2022/2555, commonly known as NIS2, establishes cybersecurity risk-management and reporting obligations for covered entities across critical sectors. Its scope includes providers of public electronic communications networks and publicly available electronic communications services, alongside sectors such as energy, transportation, healthcare, digital infrastructure and water services.
Under Directive (EU) 2022/2555, Article 21 addresses cybersecurity risk-management measures, including incident handling, business continuity, supply-chain security, secure acquisition and development, vulnerability handling, access controls and relevant technical protections. Article 23 establishes significant-incident reporting requirements, including an early warning generally within 24 hours after becoming aware of a significant incident, an incident notification generally within 72 hours and a final report within one month, subject to the directive’s detailed conditions and any applicable sector-specific provisions.
These obligations matter because AI-RAN increases the number of technical dependencies relevant to the operator’s risk assessment. Supply-chain management must include accelerators and AI software where they form part of essential network functions. Business-continuity planning must consider failures affecting shared computing resources. Incident response must address the possibility that an AI-related failure compromises communications availability without involving a conventional network intrusion.
Regulation (EU) 2024/1689, the AI Act, adds a separate framework for AI systems falling within its scope. Its application depends on the system’s intended purpose, regulatory classification and relevant implementation provisions. A telecommunications optimisation model does not become a high-risk AI system automatically because it operates within a critical network. However, an AI system serving as a safety component in the management and operation of certain critical infrastructure may fall within high-risk classifications, as may qualifying medical-device AI or emergency-response applications. The EU AI Act establishes requirements concerning risk management, technical documentation, data governance, oversight and robustness for relevant high-risk systems, subject to its application timetable and other legal conditions.
The regulatory distinction is significant. NIS2 primarily addresses organisational cybersecurity and resilience obligations for covered entities. The AI Act addresses obligations associated with particular AI systems and uses. Data protection legislation governs personal information. Sector-specific rules may impose additional safety requirements. Operators deploying AI-RAN must evaluate the interaction of these regimes rather than assuming that compliance with one automatically satisfies the others.
For national authorities, the central policy challenge is translating these frameworks into verifiable technical requirements. An operator should be able to demonstrate which computing components are essential to service continuity, what happens when one fails, how AI models are updated and whether third-party workloads can affect protected radio functions. Effective supervision requires evidence of actual system behaviour, not merely a statement that an architecture uses zero-trust principles or secure-by-design practices.
Chapter 4 — Regulatory and institutional requirements
| Instrument or institution | Verified scope | AI-RAN relevance | Governance implication |
|---|---|---|---|
| EU NIS2 Directive | Cybersecurity obligations for covered critical and important entities | Telecommunications and dependent infrastructure resilience | Risk management, reporting, supply-chain governance and continuity |
| EU AI Act | Risk-based obligations for AI systems according to intended use | AI supporting safety-critical infrastructure or regulated applications | System classification, documentation and applicable AI controls |
| ENISA NFV Security Report | 60 security challenges and 55 best practices identified in 2022 | Shared-compute and virtualisation risks | Architecture review, isolation, supplier accountability |
| NIST AI 100-2e2025 | Adversarial machine-learning taxonomy | Poisoning, evasion, privacy and model risks | AI-specific security testing |
| NSA-led Secure AI Deployment Guidance | Security of externally developed AI systems | Agent, model and deployment integrity | Controlled access, monitoring and secure operations |
| National telecom regulators | National communications oversight under applicable law | Availability, continuity and licence obligations | Service assurance and incident coordination |
| National cybersecurity authorities | Supervision and incident response under national mandates | Critical-network cyber resilience | Threat intelligence, reporting and recovery coordination |
Chapter 4 — Final assessment
The introduction of AI-RAN does not create an entirely new category of cyberattack; rather, it combines established infrastructure vulnerabilities with AI-specific risks and potentially increases the consequences of failures through shared resource dependencies. The most significant exposure arises where a compromised component can influence multiple functions, particularly when lower-trust commercial applications, privileged automated management and essential radio workloads share hardware or administrative systems.
The strongest security strategy is therefore based on controlled separation, verifiable software and model integrity, restricted operational authority, independent monitoring and tested recovery. These requirements may limit the maximum efficiency obtainable through aggressive resource sharing, but the resulting reduction in systemic vulnerability is an essential component of the economic value of resilient telecommunications.
The decisive operational question is whether operators can demonstrate that compromise of an AI application, model or management component will remain contained without causing unacceptable degradation of essential communications. Until such evidence becomes available at production scale, critical AI-RAN deployments should retain conservative workload boundaries and independently tested fallback arrangements.
Chapter 5 — Defence, Intelligence and Geopolitical Power
The emergence of a new strategic relationship between civilian communications, distributed computing and military capability
The possible integration of artificial intelligence into commercial radio access infrastructure introduces a consequential question for national defence: whether the computing capacity distributed throughout civilian telecommunications networks could become a supplementary source of military-relevant processing, communications resilience and situational awareness without compromising the security or independence of military systems. The significance of this development lies less in any single AI-RAN demonstration than in the changing relationship between communications infrastructure and the wider defence information environment. Military organisations increasingly depend on the timely acquisition, processing and distribution of information from geographically dispersed sensors, personnel, platforms and command systems. A telecommunications network containing distributed computing resources might support selected functions within that information chain, but its suitability depends on security classification, operating conditions, spectrum access, survivability and the military’s ability to maintain operations when civilian infrastructure becomes unavailable.
The distinction between commercial capability and operational military readiness is essential. A civilian network may deliver satisfactory service under normal conditions while lacking the protection required against deliberate electronic interference, physical attack, infrastructure disruption or the loss of external services. Likewise, a computing platform capable of processing commercial AI workloads may not be authorised to handle classified information or connected to the secure systems used for military command and control. The use of commercially derived technology in defence does not remove these requirements. It creates a potential opportunity to adapt mature industrial components where their characteristics are compatible with military needs.
NATO’s strategic documents provide a useful institutional basis for understanding the direction of this transformation. The Alliance Digital Strategy, published on 13 January 2026, establishes a vision extending towards 2035 in which secure, resilient and interoperable digital capabilities support information superiority, multi-domain operations and human-machine collaboration. The strategy specifically addresses distributed artificial intelligence, tactical-edge inference, federated data environments and the protection of national control over information. These are institutional objectives, not declarations that commercial AI-RAN systems already possess the characteristics required for military deployment.
The connection becomes more explicit in NATO’s Digital Transformation Implementation Strategy 2.0 of 26 May 2026, which identifies the development of a Digital Backbone and an Alliance Data Sharing Ecosystem among its strategic deliverables. The Digital Backbone is conceived as a federation of networks and systems connecting sensors, decision-makers and operational actors across different domains, while allowing secure information exchange and the use of cloud and edge capabilities. This federated approach is relevant to AI-RAN because it suggests that the future defence information environment will depend on coordinated but not necessarily identical communications and computing infrastructures.
The strategic implication is that national defence planners should assess civilian accelerated telecommunications as one possible component of a wider communications and computing ecosystem. The objective should not be to make military operations dependent on ordinary commercial radio networks. It should be to understand where those networks can provide useful capacity, how their capabilities can be accessed under clearly defined conditions and how operational independence can be preserved when they are compromised or unavailable.
Military communications and the enduring requirement for operational independence
Military communications differ from ordinary commercial connectivity because the conditions under which they must function can be deliberately hostile. A commercial telecommunications operator generally designs its network to meet defined coverage, capacity, availability and service-quality obligations under foreseeable operating conditions. Armed forces may require communications despite deliberate interference, destruction of infrastructure, movement into areas without commercial coverage or restrictions on the transmission of sensitive information. These conditions change the value of every proposed architecture.
Distributed computing can support military communications by processing selected information close to the point where it is generated, potentially reducing dependence on distant facilities. This may be valuable for logistics, maintenance, administrative support, disaster response and other functions whose information requirements are compatible with the available network. However, the geographical presence of computing infrastructure does not establish that it can support protected military communications.
Several additional questions must be answered. Can the communications system operate when external network management is unavailable? Does it retain usable functionality if connections to central facilities are interrupted? Can it authenticate authorised users under degraded conditions? Can sensitive information be processed without exposure to unauthorised administrative systems? Are essential functions protected against the failure of commercial applications sharing computing resources? Can the operator continue service during shortages of replacement components or external technical support?
The answers determine whether commercial AI-RAN infrastructure should be treated as a potential operational enabler, a noncritical support system or an unacceptable dependency for a particular mission. In many circumstances, hybrid arrangements may be preferable, with military-controlled systems retaining essential command functions and commercial networks providing supplementary connectivity where conditions permit.
The security boundary should be understood in institutional as well as technical terms. Military authorities may require guaranteed priority, access restrictions and the ability to change operational configurations in response to a crisis. Civilian operators remain responsible for public communications, legal obligations and services supporting essential civilian activities. Establishing military priority without an appropriate legal framework could create conflicts over resource allocation, especially during emergencies when civilian hospitals, authorities and rescue services also require connectivity.
The most defensible arrangements are therefore based on pre-established agreements defining permissible uses, service priorities, information handling and emergency responsibilities. These arrangements should be tested before a crisis rather than improvised when communications infrastructure is already under stress.
Distributed intelligence processing and the changing geography of military information
The integration of AI with distributed communications infrastructure could influence intelligence processing by allowing selected information to be analysed closer to where it is collected. Military intelligence systems frequently involve data from multiple sources, including observation platforms, communications systems, operational reports and other sensors. The volume and timeliness of this information can exceed the capacity of human analysts to examine every item immediately.
Distributed processing may assist by filtering information, identifying patterns or preparing material for further human analysis before it is transmitted to central facilities. This could reduce the volume of data requiring long-distance transport and enable faster recognition of certain events. Yet the quality of intelligence depends on the reliability of the underlying observations, the accuracy of analytical methods and the ability to distinguish genuine information from deception or error.
An AI model operating near a sensor does not automatically provide reliable intelligence. It may misclassify objects, confuse environmental conditions with meaningful events or produce misleading results from incomplete data. In military environments, adversaries may deliberately attempt to manipulate what sensors observe or how observations are interpreted. The analytical process must therefore preserve source provenance, relevant uncertainty and the ability of authorised personnel to challenge machine-generated conclusions.
The NATO Data Strategy for the Alliance, agreed in February 2025 and published in May, places particular emphasis on data quality, governance and interoperability. It envisages the development of an Alliance Data Sharing Ecosystem integrated through NATO’s digital infrastructure while maintaining Allied control over national information. Its target for 2030 concerns the availability of curated, interoperable data and the organisational skills necessary to use that information effectively.
This is directly relevant to distributed AI because computational capacity is useful only when information can be interpreted within a trusted framework. A system may possess substantial processing resources yet remain operationally ineffective if data classification, metadata, provenance and access permissions are inconsistent. Conversely, carefully governed data sharing can improve coordination even without the most advanced computing hardware.
The military significance of AI-RAN therefore lies partly in its compatibility with wider data-governance arrangements. A commercial edge-processing platform may support certain functions, but integrating it into military information systems requires more than a communications interface. It requires clearly defined security domains, data-handling rules and authoritative control over the information lifecycle.
Autonomous systems and the relationship between network intelligence and machine control
Autonomous systems introduce one of the most sensitive potential applications of advanced communications and distributed AI. Robotic platforms, uncrewed vehicles and other automated systems may require access to sensor information, mission updates and coordination services. Network-based computation could supplement onboard processing, particularly when systems need to share situational information or perform computationally demanding tasks.
However, autonomy and network connectivity are not equivalent. A machine capable of acting autonomously must maintain appropriate behaviour under conditions in which external communications are delayed, disrupted or unavailable. Reliance on remote computing can create vulnerabilities if the loss of connectivity prevents a system from executing essential safety functions.
The design implications depend on the system’s intended function. A logistics robot operating in a controlled military facility may benefit from local network inference for route planning or inventory recognition. A vehicle operating in an uncertain or hostile environment may require substantially greater onboard independence. A system whose actions can affect human safety must be evaluated according to the full decision and control chain, not simply the response time of its wireless connection.
This raises a broader issue concerning the relationship between human judgement and machine-executed decisions. Artificial intelligence may assist personnel by analysing information or presenting alternatives, but the authority to initiate consequential actions must remain governed by the applicable legal and operational framework. Machine recommendations should not be treated as inherently reliable merely because they are produced quickly or processed close to the operational environment.
NATO’s Revised Artificial Intelligence Strategy of July 2024 emphasises responsible use, interoperability and protection against adversarial AI. These principles are relevant to future communications-enabled autonomy because the risks involve not only whether the network functions correctly, but also whether the systems using it behave lawfully, predictably and within authorised limits.
A particularly important distinction concerns the role of civilian infrastructure. Commercial network operators should not be assumed to possess the legal authority, security arrangements or operational capabilities required to support autonomous military functions merely because their systems contain AI accelerators. The provision of computing services to defence organisations may require separate contractual, regulatory, security and technical arrangements.
Electronic warfare and the vulnerability of intelligent radio systems under contested conditions
Electronic warfare highlights the limits of transferring commercial AI-RAN results directly into defence applications. A radio system operating successfully under ordinary commercial conditions has not thereby demonstrated resilience against intentional interference, deceptive signals, spectrum denial or the destruction of communications infrastructure.
Artificial intelligence may assist radio systems by identifying changes in the electromagnetic environment or improving certain adaptive functions, but its effectiveness depends on the quality of available observations and the conditions represented during development and testing. An algorithm trained on ordinary interference patterns may respond poorly when exposed to deliberately manipulated or unfamiliar signals. The presence of AI does not remove the need for robust conventional signal-processing, communications-security and operational procedures.
The risk is especially important when network optimisation is highly automated. A system that reacts rapidly to perceived interference may be useful under normal conditions, but it must not be allowed to make unrestricted operating changes based on misleading information. Safe operation requires technical boundaries that prevent unauthorised frequency use, unacceptable service degradation or the disruption of other systems.
A further limitation concerns the physical network itself. AI processing cannot compensate for the destruction of a radio site, the loss of electrical power or the severing of essential transport infrastructure. It may support faster diagnosis or reconfiguration where alternative resources remain available, but the resulting resilience depends on those resources actually existing.
For defence procurement, electromagnetic resilience must therefore be established through controlled testing appropriate to the intended mission. Commercial throughput measurements, standard radio benchmarks and ordinary service-availability statistics are insufficient to demonstrate performance under contested conditions.
The strategic consequence is that intelligent networking can become one element of military communications resilience, but it cannot replace hardened infrastructure, protected communications arrangements, alternative transmission methods and trained operational personnel.
Civilian infrastructure, national mobilisation and the security of communications during crises
Civilian telecommunications networks play a significant role in national resilience even when they are not directly integrated into military systems. They support emergency warning, public administration, transport, financial transactions, healthcare coordination and communication between citizens and public authorities. During a major crisis, disruptions to these services can affect the ability of a country to maintain economic activity and organise a coordinated response.
The incorporation of AI workloads into telecommunications infrastructure could improve certain aspects of crisis management, particularly through automated monitoring, local analytics and faster identification of infrastructure failures. It could also create new dependencies if essential radio functions become reliant on shared computing systems vulnerable to common technical faults or resource contention.
The public-interest question is therefore whether intelligent infrastructure increases the country’s ability to withstand disruption. A system that provides advanced capabilities during normal conditions but becomes difficult to operate under emergency conditions may not represent a net improvement in national resilience. Authorities should assess resilience through credible disruption scenarios involving power loss, transport outages, software compromise and shortages of technical support.
Continuity planning must also consider the allocation of scarce computing and communications resources. During an emergency, telecommunications demand may rise sharply while infrastructure capacity is reduced. Commercial AI services may compete with communications functions for processing resources unless priority arrangements are established in advance. Where essential services share infrastructure, their relative priorities should be determined through transparent governance rather than improvised automated optimisation.
This creates a strong argument for preserving clearly defined protected capacity for emergency communications and other designated essential services. Such capacity may remain unused during ordinary operation, but its existence can be necessary to sustain public safety during exceptional conditions.
Foreign technology dependence and the security implications of concentrated computing ecosystems
The geopolitical consequences of AI-native telecommunications are closely related to the global distribution of semiconductor, software and infrastructure capabilities. Advanced accelerators and their associated software environments may be supplied by companies operating under different legal jurisdictions from the telecommunications operators deploying them. This is not inherently unacceptable, since modern communications infrastructure already depends on international supply chains. The strategic issue is the degree of dependency and whether essential operations can continue under adverse political, commercial or security conditions.
Several forms of dependency must be distinguished. Hardware dependence concerns access to processors, accelerators, memory, networking components and replacement equipment. Software dependence concerns licences, drivers, development tools, security patches and operational support. Intellectual-property dependence concerns the ability to modify, understand or replace essential implementations. Operational dependence concerns the need for external entities to maintain services, verify configurations or authorise certain actions.
These dependencies have different implications for national security. A system may use foreign-designed hardware while remaining under effective national operational control. Conversely, equipment owned by a national operator may be difficult to maintain independently if essential software updates or management functions depend on external suppliers.
Export controls add another dimension. Advanced semiconductors, certain computing technologies and defence-related systems may be subject to national or regional controls depending on their characteristics, destination and intended use. These frameworks evolve and require product-specific legal assessment. It would be incorrect to assume that every AI-RAN server is a controlled military item, just as it would be incorrect to assume that commercial classification eliminates all restrictions. The relevant authorities must examine the actual hardware, software, technology transfers and end uses.
For NATO members and other security-sensitive jurisdictions, the most important procurement requirement is the preservation of practical control over critical services. Operators should understand whether they can continue essential operations without access to a supplier’s remote management systems, whether security updates can be obtained through dependable arrangements and whether a replacement computing platform could be integrated without unacceptable disruption.
NATO interoperability and the emerging requirements of federated digital defence
Interoperability within NATO involves more than the ability to establish a communications link between national systems. It requires agreement on information classification, identity, authentication, data exchange, technical standards, security policies and operational procedures. The increasing use of AI adds questions concerning model trust, data provenance, automated decision-making and the interpretation of machine-generated information.
The Alliance’s 2026 digital documents emphasise federation rather than the universal replacement of national systems with one centrally controlled platform. This is strategically significant because member states retain different industrial capabilities, national regulations, procurement arrangements and security responsibilities. A federated approach can accommodate diverse infrastructures while establishing the standards and trust mechanisms needed for cooperation.
AI-RAN may become relevant to this environment if certain commercial or military-adapted implementations provide useful edge processing or communications functionality. However, compatibility with NATO’s broader digital objectives should not be mistaken for certification or operational integration. The Alliance’s strategy describes the direction of development; it does not confer military readiness upon commercially demonstrated systems.
The important future question is whether distributed intelligent telecommunications can support controlled information exchange across national and security boundaries while preserving the authority of each participating government over its data and operational decisions.
Chapter 5 — Defence and national-security capability assessment
| Capability area | Potential role of AI-native telecommunications | Minimum operational condition | Principal strategic risk | Status of the claim |
|---|---|---|---|---|
| Military logistics | Distributed analytics and connected asset monitoring | Secure connectivity and reliable application data | Dependence on civilian services | Potential application |
| Protected communications | Supplementary network services in authorised environments | Security accreditation and protected operating arrangements | Interception, disruption or loss of control | Requires separate validation |
| Intelligence processing | Local filtering and interpretation of selected sensor data | Trusted models, provenance and information controls | Misclassification or manipulation | Technically plausible |
| Tactical-edge inference | Computing assistance close to operational users | Appropriate ruggedness, security and resilience | Network or computing failure | NATO strategic priority; implementation-specific |
| Autonomous systems | Coordination and noncritical processing support | Local safety controls and defined authority | Unsafe remote dependence | Conditional application |
| Electronic-warfare resilience | Adaptive analysis of radio conditions | Contested-environment testing | Adversarial manipulation and spectrum denial | Not established by commercial AI-RAN tests |
| National crisis response | Infrastructure diagnostics and local service support | Protected emergency capacity and recovery plans | Cascading shared-platform failure | Plausible civil-defence function |
| NATO interoperability | Potential integration with federated digital infrastructure | Agreed identity, data and security standards | Fragmented national implementations | Strategic direction under development |
| Defence industrial capability | Use of commercial semiconductor and software ecosystems | Assured supply and security governance | External supplier concentration | Existing procurement concern |
| Sovereign operations | National control over essential computing and communications | Independent access, monitoring and recovery | Dependency during geopolitical disruption | Strategic procurement requirement |
Chapter 5 — Strategic assessment
The principal military significance of AI-RAN is not that a civilian telecommunications network can immediately be transformed into a secure defence system. It is that accelerated computing and intelligent communications are becoming increasingly interdependent, creating potential opportunities for distributed analysis, crisis response and certain forms of operational support.
NATO’s digital transformation agenda provides an institutional framework in which these capabilities may eventually become relevant, particularly through secure data exchange, tactical-edge computing and federated infrastructure. Yet the requirements of military communications remain substantially more demanding than those demonstrated by a commercial AI-RAN call.
For defence planners, the appropriate strategic objective is selective exploitation of commercially developed capabilities while preserving operational independence, security accreditation and resilience under hostile conditions. Commercial telecommunications should be assessed as a possible supplementary asset rather than an assumed substitute for protected military networks.
The assessment would strengthen if military authorities published evidence of successfully qualified deployments demonstrating secure interoperability, reliable operation under relevant degraded conditions and meaningful improvements in mission performance. It would weaken if the technology introduced dependencies that could not be controlled or recovered during crisis conditions.
Chapter 6 — Healthcare, Industry, Transport, Energy and the Connected Society
When intelligent telecommunications enter the physical economy, the decisive measure becomes the quality of essential services
The most extensive long-term consequences of AI-native telecommunications may emerge outside the telecommunications sector itself. The integration of connectivity, local computational intelligence and automated sensing could alter how hospitals deliver care, how industrial facilities operate, how transport systems coordinate movement and how governments organise essential services. Yet these changes will not occur simply because a mobile operator installs AI accelerators. They require applications whose performance depends materially on the interaction between communication and computation, organisations capable of integrating those applications into established workflows, and governance systems able to prevent technical failures from becoming threats to safety, privacy or economic continuity.
The relevant distinction is between connectivity as a supporting service and connectivity as part of an operational decision system. In conventional telecommunications, the network transmits information between users, devices and applications. In a more deeply integrated environment, nearby computing infrastructure may analyse information and return interpretations or recommendations to connected systems. This can reduce the need to send all information to distant facilities, but it also changes the responsibilities of the organisations operating the infrastructure. They may become participants in data processing and decision-support activities whose consequences are governed by medical, industrial, transport or public-sector standards.
The economic significance of this transition depends on the structure of each industry. Healthcare places exceptional importance on clinical evidence and patient safety. Manufacturing prioritises reliable production, machine safety and continuity. Transport requires operational coordination under strict safety constraints. Energy and water utilities must maintain continuous service despite equipment failures and cyber incidents. Education depends on equitable access, pedagogical quality and the protection of students’ information. Public administration must ensure that automated systems operate within the law and remain accountable to citizens.
AI-RAN may provide useful infrastructure for these sectors, but its contribution must be evaluated against their actual requirements rather than against generic promises of low latency or artificial intelligence. The strongest applications will be those in which the location of computation, the reliability of communications and the availability of local data produce a measurable improvement in service outcomes.
Healthcare: from remote connectivity to clinically governed distributed intelligence
Healthcare illustrates both the potential and the limitations of intelligent telecommunications. Modern medical systems increasingly rely on digital records, connected equipment, imaging, remote consultations and software-supported clinical workflows. The availability of reliable communications is important, particularly where patients and professionals are geographically separated. Distributed AI computing could extend these capabilities by enabling selected analytical functions to operate closer to healthcare facilities, reducing the need to transmit large volumes of information to distant computing centres.
Medical imaging provides one potential application. Hospitals generate substantial quantities of diagnostic information, and AI systems may assist authorised professionals in identifying patterns or prioritising cases for review. Local inference could allow a hospital or regional healthcare network to process information without relying entirely on a remote cloud platform. The potential benefit is especially relevant where connectivity to central facilities is limited, where data-governance requirements constrain information transfers or where applications need to remain available during wider network disruption.
However, clinical usefulness cannot be inferred from computing proximity. An AI model operating within a hospital’s local telecommunications environment may produce results rapidly while remaining clinically inaccurate. Diagnostic sensitivity, specificity, calibration, performance across patient populations and the consequences of erroneous outputs must be evaluated separately from network performance. The existence of local computing resources does not eliminate the need for clinical trials, medical-device assessment or professional oversight where applicable.
The World Health Organization’s Global Strategy on Digital Health 2020–2027, updated following the World Health Assembly’s decision to extend the strategy through 2027, emphasises the need to integrate technological initiatives with financial, organisational and human resources. This is important for AI-RAN because telecommunications investment alone cannot improve healthcare unless hospitals possess interoperable information systems, trained personnel, appropriate clinical procedures and sustainable funding.
The same considerations apply to remote patient monitoring. Connected sensors may collect physiological measurements or information about treatment adherence, while local AI systems may assist in identifying changes warranting professional attention. A nearby inference platform could reduce dependence on distant processing for selected applications, but the reliability of medical monitoring depends on the entire information chain. Sensor accuracy, secure transmission, correct patient identification, model performance, alert prioritisation and clinical response procedures are all essential. Reducing communications latency provides little benefit if the resulting alert is unreliable or if the healthcare organisation lacks the capacity to act upon it.
Connected ambulances and emergency medicine introduce an additional layer of operational complexity. Mobile networks may support the transmission of patient information, medical imagery or consultation requests between emergency vehicles and hospitals. In selected circumstances, local or regional processing could assist with data interpretation. Yet emergency medical systems require continuity during movement, coverage interruptions and periods of network congestion. Applications must therefore retain appropriate fallback procedures and avoid placing life-critical decisions under the exclusive control of an externally hosted AI service.
The US Food and Drug Administration’s February 2026 guidance, Cybersecurity in Medical Devices: Quality Management System Considerations and Content of Premarket Submissions, reinforces the importance of managing cybersecurity throughout relevant medical-device development and regulatory processes. The guidance addresses device design, documentation and the requirements associated with cyber devices under section 524B of the Federal Food, Drug, and Cosmetic Act. It does not establish a general certification procedure for AI-RAN networks, but it illustrates why a telecommunications application connected to regulated medical equipment must be evaluated within the broader medical-device security environment.
A particularly sensitive application concerns robotic and remotely assisted medical procedures. The availability of high-capacity communications and local computing may support certain medical robotics functions, training environments or remote assistance. However, the feasibility and safety of a remote clinical intervention depend on far more than average network latency. End-to-end delay, variation in delay, control stability, equipment reliability, professional responsibility, cybersecurity and the ability to respond to connection failure all matter. AI-RAN should not be represented as making autonomous or remote surgery routinely safe merely by improving the location of computational resources.
For European healthcare systems, the governance environment is especially complex because personal health information receives strong protection under data-protection law, while qualifying AI medical devices may be subject to medical-device legislation and AI Act requirements. The relevant legal treatment depends on the application, its intended purpose and the applicable regulatory provisions. A hospital using local AI inference must still establish the lawful basis for processing information and implement appropriate safeguards. Keeping information geographically close to the hospital may support data-governance objectives, but it does not automatically establish legal compliance.
The most promising near-term healthcare model is therefore likely to involve clinically validated applications operating within controlled healthcare information environments, with telecommunications infrastructure providing connectivity and, where justified, nearby computing services. The operator’s role should remain clearly distinguished from the healthcare provider’s responsibility for clinical decisions.
Healthcare deployment requirements and consequences
| Healthcare application | Potential contribution of distributed AI connectivity | Evidence required before clinical use | Main patient-safety concern | Relevant institutional framework |
|---|---|---|---|---|
| Medical imaging analysis | Local inference and reduced dependence on distant processing | Clinical accuracy, validation across populations, workflow evaluation | Incorrect or delayed diagnosis | Medical-device regulation where applicable |
| Remote patient monitoring | Local analysis of selected sensor information | Sensor reliability, alert accuracy, clinical-response procedures | Missed deterioration or false alarms | Clinical governance and data protection |
| Emergency medical services | Secure transmission and processing of patient information | Connectivity continuity and emergency workflow tests | Delayed or unavailable information | Emergency medical service rules |
| Connected ambulances | Mobile consultation and selected decision-support functions | End-to-end reliability under mobility | Interruption during patient transport | Clinical and communications requirements |
| Clinical robotics | Possible remote assistance and local computational support | System-level safety validation and control stability | Unsafe action following network disruption | Medical-device and clinical safety regimes |
| Hospital operations | Predictive maintenance, scheduling and nonclinical analytics | Operational accuracy and business-continuity tests | Disruption of critical hospital services | Healthcare cybersecurity obligations |
| Medical research | Controlled processing of selected research information | Data governance, research ethics and reproducibility | Privacy or misleading analytical conclusions | Research and data-protection frameworks |
The table identifies prospective applications and their validation requirements. It does not imply that these services have been demonstrated on the Bellevue AI-RAN architecture.
Intelligent manufacturing: telecommunications becomes part of the production infrastructure
Manufacturing presents a different opportunity because industrial facilities often combine demanding communications requirements with substantial local information processing. Automated production lines, machine-vision systems, robotic equipment and connected sensors generate data that can support quality control, maintenance planning and operational coordination. Some applications already use local servers or dedicated industrial computing platforms, making the integration of accelerated telecommunications infrastructure a potential alternative rather than an entirely new capability.
The central industrial question is whether combining connectivity and computing improves the reliability or cost of production. A factory may operate several camera systems inspecting products for defects. Local AI inference can process images without transporting all raw video to a distant facility. A network-compute platform may also support communications between machines and industrial information systems. Yet an integrated solution is economically attractive only if it improves upon the factory’s existing combination of wired networks, private wireless infrastructure and local computing.
Industrial automation places particular importance on the distinction between supervisory intelligence and safety-critical control. AI may help identify equipment deterioration, recommend maintenance or improve production scheduling. These functions can often tolerate some variation in processing time. Machine safety functions, by contrast, may require highly predictable behaviour and independent protection mechanisms. A network-assisted AI system should not be assumed to replace established machinery safeguards merely because it can produce rapid decisions under ordinary conditions.
The operational environment further complicates radio connectivity. Industrial facilities may contain metal structures, moving equipment, electromagnetic interference and changing physical layouts. Wireless performance must therefore be evaluated under realistic production conditions rather than generic coverage assumptions. The presence of AI-optimised radio processing may assist particular communications functions, but it does not eliminate the need for engineering surveys, redundancy and suitable industrial network design.
A valuable use case may involve predictive maintenance. Industrial equipment can generate vibration, temperature and operational telemetry that supports analysis of emerging faults. Processing selected information locally may allow earlier identification of abnormal behaviour while reducing the volume of data transmitted outside the facility. However, the commercial benefit depends on whether the analytical system reduces unplanned downtime, prevents equipment damage or improves maintenance scheduling. A high model-accuracy score is not equivalent to realised production savings if the factory cannot act effectively on the prediction.
Another potential application concerns industrial robotics coordination. Robotic systems may exchange information about their status, movements or assigned tasks, while edge AI supports perception and scheduling. Yet essential collision avoidance and safe-stop functions should remain subject to appropriate safety engineering. Network-assisted coordination can enhance productivity without necessarily becoming the sole means by which machines avoid hazardous behaviour.
Industrial deployment comparison
| Industrial process | Potential application of AI-RAN-connected computing | Principal operational benefit | Required validation | Risk of overdependence |
|---|---|---|---|---|
| Machine-vision inspection | Local AI analysis of production images | Faster or more consistent defect detection | False-positive and false-negative testing | Incorrect acceptance or rejection of products |
| Predictive maintenance | Local processing of equipment telemetry | Reduced unplanned downtime | Comparison with actual failure and maintenance records | Misleading maintenance decisions |
| Industrial robotics | Network-assisted coordination and perception | Improved operational flexibility | Safety and communication-failure testing | Unsafe reliance on external computing |
| Warehouse automation | Connected robotic fleets and inventory analytics | Improved logistics efficiency | Mobility and congestion performance | Disruption of material movement |
| Process industries | Distributed monitoring and anomaly detection | Earlier identification of deviations | Process-specific reliability and safety analysis | Incorrect operational interventions |
| Digital twins | Near-real-time data exchange with simulation models | Better operational planning | Model fidelity and data timeliness | Decisions based on inaccurate virtual representations |
| Industrial cybersecurity | Local anomaly detection across equipment networks | Faster identification of suspicious behaviour | Detection accuracy and incident-response exercises | False alerts or missed intrusions |
Transport and logistics: the difference between infrastructure-assisted intelligence and autonomous control
Transportation systems provide a substantial potential market for distributed intelligence because movement creates continuous demands for information, coordination and situational awareness. Road networks, ports, airports, rail systems and logistics facilities depend on interactions among vehicles, infrastructure and operational authorities. Advanced communications could allow selected analytical functions to operate closer to transport activity, potentially reducing dependence on distant computing systems for time-sensitive operational information.
Road transport illustrates both the opportunity and the limits. Infrastructure-based cameras, sensors and traffic-monitoring systems may generate information about congestion, accidents or changing road conditions. Local AI processing could analyse these observations and provide information to traffic-management centres or authorised connected vehicles. This may improve the speed at which certain events are identified, but its effectiveness depends on sensor quality, system coverage and the reliability of the resulting interpretation.
The distinction between advisory information and vehicle control is essential. A transport authority may use AI-assisted analysis to adjust traffic-management decisions, subject to appropriate safeguards. An automated vehicle, however, must retain sufficient onboard capability to operate safely when network information is delayed, unavailable or incorrect. A telecommunications service cannot be treated as a guaranteed substitute for vehicle perception and control simply because it offers advanced connectivity.
Ports and logistics hubs present different opportunities. Container terminals may already operate private communications networks, automated handling systems and local computing facilities. Shared accelerated infrastructure could support video analysis, equipment monitoring and operational coordination, but the economic advantage over existing infrastructure must be demonstrated. The most valuable contribution may arise from integrating previously separate information systems rather than from increasing raw communication speed.
Rail operations require particular caution because signalling, train protection and safety-critical control are governed by specialised technical requirements. AI-RAN could support passenger services, maintenance analytics and selected operational communications without necessarily becoming part of the safety-critical control infrastructure. Any deeper integration would require sector-specific qualification and demonstration of reliability under foreseeable failure conditions.
The European Union’s AI Act identifies certain AI systems used as safety components in the management and operation of road traffic and other designated critical infrastructure as high-risk under applicable conditions. This reinforces the need to distinguish ordinary analytics from applications whose malfunction could threaten life or physical safety. The relevant classification follows the actual function of the system, not the marketing description of the network supporting it.
Energy systems: intelligent infrastructure creates both an opportunity and a new source of electricity demand
Energy infrastructure occupies a particularly important position because AI-RAN could simultaneously support utilities and increase demand on the electricity system. The potential applications include monitoring distributed electrical assets, analysing equipment conditions, supporting renewable-energy operations and improving the detection of faults. Local processing may be useful where transmitting large quantities of operational data to a central computing facility is unnecessary or where continuity during network disruption is valuable.
Electricity networks are already complex cyber-physical systems. Their stable operation depends on measurement, control, protection equipment and coordination among multiple organisations. AI may assist with forecasting demand, identifying anomalies or scheduling maintenance, but critical control decisions must remain governed by appropriate operational safeguards. An AI system providing a recommendation is not equivalent to a certified protection mechanism authorised to respond to dangerous electrical conditions.
The possible benefits are therefore application-specific. Local analytics may reduce the time required to identify equipment deterioration. Distributed sensing may improve visibility into parts of the system that previously had limited monitoring. Better information may support maintenance planning and investment decisions. Yet these benefits depend on sensor deployment, data quality, integration with utility workflows and the ability to respond effectively to identified problems.
The energy burden of AI infrastructure is substantial at global scale, although it must not be attributed entirely to AI-RAN. The International Energy Agency’s 2026 Key Questions on Energy and AI assessment projects global data-centre electricity consumption rising from approximately 485 TWh in 2025 to 950 TWh in 2030, with AI-focused data centres experiencing substantially faster growth than the wider sector. These figures describe global data-centre demand, not the electricity consumption of telecommunications AI-RAN installations. They nevertheless establish the broader context in which governments must assess new distributed accelerated-computing infrastructure.
The electricity implications of AI-RAN will depend on whether distributed installations supplement or substitute existing computing facilities, how efficiently their hardware is utilised and whether useful applications reduce electricity consumption elsewhere. Installing local accelerators may improve certain operational processes while adding new electricity demand to telecommunications facilities. A credible environmental assessment must account for both effects.
This becomes a matter of public infrastructure planning when multiple operators and AI service providers seek electrical capacity in the same metropolitan regions. Network densification, accelerated servers and cooling systems may compete with other uses of limited distribution capacity. Where infrastructure is located near essential facilities, authorities may also need to evaluate the implications for backup power and emergency operating priorities.
Water, agriculture and environmental infrastructure: extending intelligence beyond urban networks
Water infrastructure offers an important application of distributed sensing because drinking-water distribution, wastewater treatment and hydraulic systems often cover large geographical areas and contain equipment requiring continuous or periodic monitoring. Potential applications include leakage detection, pump maintenance, water-quality monitoring and the analysis of treatment-plant operating conditions.
The value of local processing depends on the structure of the system. A treatment facility may already possess substantial industrial control infrastructure, while geographically dispersed pumping stations may have limited connectivity and computing capacity. AI-RAN could support selected installations where reliable wireless communication and nearby inference provide advantages, but many remote facilities may remain better served by simpler sensing networks or existing wired and wireless technologies.
The principal safety requirement is to prevent analytical systems from interfering with essential hydraulic operations. Water-treatment and distribution facilities must preserve controlled processes even when communications or AI applications are unavailable. A model identifying an abnormal measurement should not automatically be authorised to make consequential changes to treatment or distribution without appropriate safeguards.
Agriculture presents a different economic problem because land areas can be extensive while revenue per connected device or unit of infrastructure may be comparatively modest. Precision agriculture can use sensors, imaging and automation to support irrigation, equipment maintenance and crop monitoring. Advanced network intelligence may benefit particular large-scale or high-value operations, but the cost of connectivity and computing must remain proportionate to the agricultural application.
For environmental monitoring, distributed intelligence may improve the processing of information from air-quality sensors, water-monitoring installations and other observation systems. However, sensing coverage, measurement accuracy and data integrity remain essential. A sophisticated AI model cannot compensate for missing or incorrectly calibrated observations.
The geopolitical importance of these applications is strongest where infrastructure resilience, water security and food production are already national priorities. Distributed AI may improve the management of scarce resources, but it should be treated as a supporting capability within broader engineering and governance systems.
Emergency services and disaster response: network intelligence under conditions of maximum vulnerability
Emergency communications represent a particularly demanding application because infrastructure demand often rises precisely when physical conditions are deteriorating. During natural disasters, major accidents or security incidents, telecommunications systems may experience congestion, power failures, transport disruptions and damage to radio sites. Public authorities depend on communications to coordinate rescue operations, distribute warnings and maintain contact with affected communities.
Distributed computing could support local information processing, damage assessment or analysis of emergency-service data. It may reduce reliance on distant computing facilities for selected functions, especially when communications between regions are degraded. Yet the same incident that creates demand for local intelligence may also damage the infrastructure hosting that intelligence.
This creates a fundamental resilience requirement: emergency applications should not depend exclusively on facilities exposed to the same hazards as the communications systems they support. Geographic diversity, protected power supplies, alternative communications arrangements and operational fallback procedures remain essential.
AI-assisted emergency call handling introduces additional concerns. Systems may help classify information, identify relevant resources or support dispatch personnel, but errors can have direct consequences for human safety. An incorrect prioritisation decision may delay assistance, while biased or poorly calibrated models may treat different communities unequally.
The EU AI Act specifically addresses relevant AI applications used for evaluating and classifying emergency calls, dispatching or prioritising emergency first-response services and emergency healthcare triage. Such applications may fall within high-risk categories because their decisions can materially affect life, health and property.
The correct institutional model is therefore one in which AI supports authorised emergency personnel through validated tools, clear accountability and appropriate human oversight. Network intelligence should enhance situational awareness without creating an opaque system that independently determines access to life-saving services.
Education, public administration and the transformation of access to digital services
The integration of local AI services with telecommunications infrastructure could also affect education and public administration, particularly where institutions lack the resources to operate their own advanced computing systems. Regional computing infrastructure could potentially support language technologies, accessibility tools, administrative information services and selected educational applications.
For education, the availability of AI processing near schools or universities may reduce certain infrastructure barriers, but it does not guarantee improved learning outcomes. The educational value of technology depends on instructional design, teacher competence, content quality and the capacity of students to use systems critically. An AI service that provides rapid responses can still reinforce misunderstandings or generate inaccurate information.
Local processing may offer advantages for privacy and institutional control, particularly when student information is sensitive. However, geographic data locality does not automatically resolve questions of consent, lawful processing, retention and the use of information for model development. Institutions need clear rules concerning what information can be processed, who may access outputs and how errors can be challenged.
Public administration faces similar issues. AI-assisted services may improve access to information or reduce routine administrative burdens. Yet systems influencing access to essential public benefits, employment opportunities or public services require particularly careful governance. Citizens must be able to understand the basis of consequential decisions and obtain appropriate human review where the law requires it.
The broader risk is that infrastructure efficiency becomes confused with institutional legitimacy. A government may be able to automate an administrative process more rapidly without improving its fairness, accuracy or accessibility. AI-native telecommunications could make such services more widely available, but the quality of governance remains an independent requirement.
Labour markets and the redistribution of technical expertise
AI-native telecommunications may influence employment through several channels. Network operators may automate diagnostic and maintenance activities, reducing demand for certain repetitive tasks while increasing demand for specialists in cybersecurity, software integration, accelerated computing and AI assurance. Industrial customers may use distributed inference to automate selected analytical or administrative work. Public institutions may reorganise workflows as AI services become more accessible.
These developments should not be interpreted as evidence that AI-RAN itself will eliminate a quantifiable number of jobs. Its employment effects are embedded within the broader diffusion of artificial intelligence, telecommunications automation and digital transformation. Distinguishing the effects of one infrastructure architecture from those of AI adoption more generally will be difficult.
The International Labour Organization’s 2025 study, Generative AI and Jobs: A Refined Global Index of Occupational Exposure, estimates that approximately one in four workers worldwide are employed in occupations with some exposure to generative AI. The study identifies 3.3% of global employment in its highest exposure category, while emphasising that transformation of work is more likely than wholesale replacement in many occupations. These figures concern generative AI across the labour market and must not be represented as forecasts of employment displacement caused by AI-RAN.
The ILO’s June 2026 review of empirical evidence on jobs, productivity and work organisation further reports that measured productivity benefits remain uneven and that observed time savings have not consistently translated into proportional increases in output, earnings or employment. It identifies concerns relating to inequality, opportunities for younger workers and changes in workplace autonomy.
For the telecommunications workforce, the practical implication is a shift in the mixture of skills required to operate networks. Traditional expertise in radio engineering, fibre infrastructure and field maintenance remains necessary, but operators increasingly require personnel capable of managing cloud-native environments, GPU-based workloads, software supply chains, model governance and complex cyber incidents. The challenge is not simply to recruit more AI specialists. It is to develop teams capable of understanding interactions between computational systems and physical infrastructure.
For governments, education and workforce policy should therefore focus on multidisciplinary technical competence. Engineers must understand both software and physical systems, while managers and regulators need sufficient technical literacy to evaluate the consequences of automated decisions. Training programmes limited to generic AI tools will not meet the requirements of critical infrastructure operations.
Civil liberties, privacy and the risk of pervasive network intelligence
The most sensitive societal consequence of AI-native telecommunications concerns the potential convergence of communications data, environmental sensing, artificial intelligence and geographically distributed processing. Telecommunications infrastructure already supports highly sensitive information about communications and connectivity. More advanced sensing and analytical capabilities could increase the ability of organisations to infer patterns of movement, behaviour and activity in the physical environment.
This creates a distinction between technical capability and legitimate authority. A network operator may possess the technical means to process information, but that does not establish a lawful or socially acceptable purpose for doing so. The deployment of intelligent sensing must therefore be accompanied by clear limitations on data collection, retention, analysis and disclosure.
Integrated sensing may introduce particularly complex privacy questions because some information could concern individuals who are not active subscribers to a specific service. Depending on the technology and implementation, radio-based observations might reveal characteristics of the surrounding environment. The legal and ethical treatment of such observations depends on whether they constitute personal data, the purpose of processing and the applicable national laws.
AI can also increase the inferential value of apparently limited information. Data that do not directly identify a person may become more revealing when combined with other observations or processed by sophisticated models. An effective privacy framework must therefore consider not only the information collected, but also the inferences that organisations can reasonably derive from it.
The possibility of widespread sensing also raises questions about public confidence. Citizens may accept telecommunications infrastructure that provides connectivity while objecting to persistent environmental monitoring undertaken without meaningful safeguards. The legitimacy of future networks could consequently depend on transparent restrictions preventing the conversion of communications infrastructure into systems of indiscriminate surveillance.
These concerns have geopolitical dimensions. Countries differ in their approaches to state access, privacy protections, regulatory oversight and intelligence collection. The export of AI-native telecommunications infrastructure may therefore raise questions extending beyond technical interoperability into the legal and institutional environment in which the systems operate.
Chapter 6 — Sectoral opportunity, maturity and societal exposure
| Sector | Potential AI-native network application | Main source of value | Essential safeguard | Current evidence level |
|---|---|---|---|---|
| Healthcare | Local diagnostic inference and remote monitoring | Data locality and selected workflow improvements | Clinical validation and patient protection | Prospective AI-RAN use; broader digital-health precedent |
| Hospital operations | Connected equipment and predictive maintenance | Service continuity and asset management | Healthcare cybersecurity and fallback | Technically plausible |
| Manufacturing | Machine vision and production analytics | Quality control and productivity | Industrial safety and deterministic controls | Established use of edge AI; AI-RAN integration requires validation |
| Industrial robotics | Network-assisted coordination | Flexibility and information sharing | Independent machine safety | Application-specific research and deployment |
| Road transport | Infrastructure sensing and traffic analytics | Better situational awareness | Road safety and data governance | Potential application |
| Ports and logistics | Local analytics and automation support | Operational efficiency | Resilient operational control | Technically plausible |
| Rail | Maintenance analytics and noncritical services | Improved asset visibility | Separation from safety-critical signalling | Application-specific |
| Electricity | Distributed asset monitoring | Fault detection and maintenance | Grid protection and cyber resilience | Wider utility AI precedent |
| Water infrastructure | Pump and treatment monitoring | Resource management | Safe control and data integrity | Prospective integration |
| Agriculture | Local processing of sensor and imaging data | Resource optimisation | Cost proportionality and reliable measurements | Application-dependent |
| Emergency services | Decision support and local analytics | Faster information interpretation | Human oversight and continuity | High-risk governance concerns |
| Education | Accessibility and local AI learning services | Broader service availability | Pedagogical quality and privacy | Potential service model |
| Public administration | Distributed AI information services | Improved access and processing efficiency | Accountability and lawful decisions | Application-dependent |
| Environmental monitoring | Local sensing analytics | Better observation and response | Measurement validity and proportionality | Prospective integration |
The emerging distributional problem: intelligent infrastructure may reinforce existing inequalities
The diffusion of AI-native telecommunications may create a new dimension of digital inequality. Earlier telecommunications policy concentrated heavily on access to network coverage and adequate broadband capacity. If valuable AI services become increasingly dependent on nearby computing resources, geographical access to computation may become an additional determinant of economic opportunity.
Regions with dense enterprise demand, established fibre infrastructure and reliable electricity may attract more advanced deployments. Rural or economically disadvantaged areas may remain dependent on more distant computing facilities or receive fewer specialised services. This does not imply that every useful AI application requires local processing; many applications can operate effectively through centralised infrastructure. It does mean that certain forms of industrial automation, distributed sensing and time-sensitive analytics may become easier to deploy in regions with suitable computing infrastructure.
The distributional consequences could extend to firms of different sizes. Large corporations may negotiate dedicated infrastructure or build private computing facilities, while smaller enterprises may depend on telecommunications operators or cloud providers. If access prices are high or services are insufficiently interoperable, smaller organisations could face a competitive disadvantage.
Governments should therefore evaluate the social and economic distribution of intelligent infrastructure benefits rather than measuring deployment success solely by the quantity of accelerators installed or the number of partnerships announced. Relevant indicators include the availability of useful services to smaller enterprises, the affordability of access for public institutions, the geographical distribution of computing capacity and the ability of local organisations to retain control over their information.
Cross-sector governance: the problem of shared infrastructure serving different safety regimes
One of the most difficult institutional consequences of AI-RAN arises when a single computing environment supports applications subject to different legal and safety obligations. A telecommunications workload, a hospital information service, an industrial analytics application and a public-sector AI system may share physical infrastructure while operating under different regulatory frameworks.
The operator’s responsibilities cannot be determined solely by the fact that all applications run on the same server. The healthcare provider remains responsible for relevant clinical obligations. The industrial operator retains responsibilities associated with machinery and workplace safety. Public authorities remain accountable for lawful administrative decisions. Telecommunications providers must satisfy applicable communications and cybersecurity duties. The computing supplier may have separate contractual or regulatory obligations associated with its products.
Nevertheless, shared infrastructure creates dependencies that can affect every participant. A cybersecurity failure in the hosting platform may compromise several sectors simultaneously. An unsuccessful software update could disrupt unrelated services. A shortage of computing capacity may create conflicts between contractual customers and essential public functions.
This raises the need for cross-sector assurance arrangements addressing responsibility for incidents that originate in shared infrastructure. Contracts should define service priorities, liability boundaries, data-handling obligations, incident notification and recovery procedures. Regulators may need mechanisms for coordinating oversight where failures cross traditional industry boundaries.
The central challenge is to preserve the special protections required by each sector without making the shared infrastructure operationally unmanageable. Standardised security controls can help, but they cannot replace application-specific safety requirements. The fact that a telecommunications platform has passed a cybersecurity assessment does not establish that a medical diagnostic model is clinically effective or that an industrial control system is safe.
Chapter 6 — Public-interest and regulatory decision matrix
| Public-interest objective | Responsible institutional sphere | Required evidence | Principal policy trade-off | Recommended governance approach |
|---|---|---|---|---|
| Patient safety | Healthcare authorities and regulated providers | Clinical validation and service-continuity testing | Innovation versus clinical risk | Application-specific approval and oversight |
| Industrial productivity | Industrial operators and safety authorities | Measured production outcomes and safety testing | Automation benefits versus operational dependency | Preserve independent safety systems |
| Transport safety | Transport regulators and operators | System-level reliability and failure-mode analysis | Connected intelligence versus autonomous resilience | Require safe operation during network loss |
| Energy security | Energy regulators and infrastructure operators | Reliability and system-energy measurements | Operational efficiency versus additional electricity demand | Integrated energy and cyber assessment |
| Water security | Water authorities and utility operators | Measurement integrity and process-safety testing | Automation versus continuity of essential supply | Maintain protected control functions |
| Emergency protection | Civil protection and emergency authorities | Service continuity and decision-support validation | Faster response versus automated errors | Protected priorities and meaningful oversight |
| Education | Educational institutions and authorities | Learning outcomes, accessibility and data protection | Personalisation versus student privacy | Institutional control and pedagogical evaluation |
| Labour-market inclusion | Employment and education authorities | Task transformation and skills-demand evidence | Efficiency versus unequal adjustment | Technical reskilling and social dialogue |
| Civil liberties | Data-protection and competent public authorities | Lawfulness, necessity and proportionality assessments | Sensing capabilities versus individual rights | Strict purpose limitation and independent oversight |
| Regional equality | Digital infrastructure and regional authorities | Service distribution and affordability | Market-led deployment versus territorial cohesion | Targeted public-interest infrastructure policy |
Chapter 6 — Final societal assessment
The societal significance of AI-RAN will be determined by the degree to which distributed intelligence improves the functioning of essential services without creating unacceptable dependencies or weakening public accountability. Healthcare, manufacturing, transport, energy and public administration possess different priorities, but they share one central requirement: the performance of an AI application must be evaluated within the complete operational system in which it is deployed.
The availability of accelerated computing near a communications network may reduce some technical constraints and enable useful forms of local analysis. It does not establish clinical effectiveness, industrial safety, transport reliability, energy savings or administrative fairness. Each benefit requires evidence specific to the application and the organisation responsible for its operation.
The strongest strategic opportunity lies in combining reliable connectivity with carefully governed local intelligence where this produces measurable improvements in service quality, operational resilience or economic productivity. The greatest risk lies in allowing computing efficiency and automated decision-making to take precedence over the safety, rights and continuity obligations associated with essential infrastructure.
Pillar II — Integrated Strategic Assessment
The analysis of cybersecurity, national defence and civilian infrastructure reveals a common structural issue. AI-native telecommunications introduce new relationships between computing platforms and essential services. These relationships can generate valuable capabilities, but they also distribute operational dependencies across organisations, software systems and physical facilities whose security requirements may differ substantially.
The cybersecurity assessment establishes that the principal exposure arises from the interaction between shared resources, privileged software environments, model-related vulnerabilities and automated operational authority. The defence assessment demonstrates that commercially developed capabilities can be useful without satisfying the more demanding requirements of protected military systems. The civilian-sector assessment shows that the availability of local intelligence creates potential value only when applications are independently validated and integrated into responsible institutional workflows.
The resulting strategic problem is not simply technical. Governments must determine which organisations are authorised to control intelligent infrastructure, which services receive priority during disruption, what evidence demonstrates acceptable safety and how accountability is maintained when failures cross institutional boundaries.
The movement towards 6G may increase the importance of these questions because future networks are being designed to support closer relationships among communications, artificial intelligence and environmental sensing. The expansion of technical capability could improve economic productivity and public-service delivery, but it could also increase the volume of sensitive information processed by network infrastructure and the consequences of unauthorised access or incorrect automated decisions.
The principal judgment is that AI-native telecommunications should be governed as a convergence of critical infrastructure systems, rather than as a conventional telecommunications upgrade. Their successful development requires the simultaneous protection of technical resilience, military operational independence, sector-specific safety and fundamental rights.
For cybersecurity authorities, the immediate priority is verifiable containment across shared computing environments and strict control over autonomous management systems. For defence institutions, it is the selective use of commercial technological capabilities without sacrificing protected communications or national operational authority. For healthcare, industrial and public-service organisations, it is the independent validation of applications and the preservation of essential functions when AI or network services fail.
The international institutional record provides substantive foundations for this approach. ENISA’s analysis of virtualised 5G networks identifies the risks of shared infrastructure. NIST’s adversarial machine-learning framework addresses manipulation of AI systems. The NSA-led guidance establishes practices for secure deployment. NATO’s 2025–2026 strategies place data governance, interoperability and resilient digital systems within the wider defence transformation agenda. WHO, FDA, ILO and EU regulatory instruments demonstrate that the consequences of AI adoption extend beyond computing performance into public health, employment, safety and civil rights.
These institutional foundations do not establish that all future AI-RAN deployments will be secure or socially beneficial. They provide criteria against which governments and operators can evaluate whether proposed deployments deserve to be trusted.
Principal indicators for 2027–2031
| Strategic domain | Observable indicator | Positive development | Adverse development | Primary decision authority |
|---|---|---|---|---|
| Cyber resilience | Independent workload-isolation and recovery tests | Contained failures without essential-service disruption | Cross-workload compromise or cascading outages | Operators and cybersecurity authorities |
| AI management | Auditable authority and model governance | Reversible, independently monitored automation | Uncontrolled configuration actions | Operators and competent regulators |
| Military applications | Mission-specific qualification | Reliable supplementary capabilities under required conditions | Unacceptable reliance on commercial infrastructure | National defence authorities |
| NATO interoperability | Standards-based secure federation | Trusted cross-domain information exchange | Persistent fragmentation or incompatible controls | NATO and Allied authorities |
| Clinical applications | Clinical and medical-device evidence | Validated outcomes with safe fallback | Deployment based solely on infrastructure claims | Healthcare regulators and providers |
| Industrial applications | Productivity with maintained safety | Measured gains without compromising protected controls | Automation failures or unmanageable dependencies | Industrial operators and safety authorities |
| Energy sustainability | Whole-system energy measurements | Demonstrated efficiency under equivalent service obligations | Higher consumption without compensating value | Operators, utilities and energy authorities |
| Societal legitimacy | Rights and impact assessments | Lawful, proportionate and accountable use | Unjustified surveillance or discriminatory decisions | Data-protection and public authorities |
| Regional inclusion | Distribution of useful computing services | Broader access across regions and firm sizes | Concentration of benefits in already advantaged markets | National and regional policymakers |
The decisive evidence will come not from the number of intelligent functions introduced into telecommunications networks, but from the ability to demonstrate that those functions improve service performance while preserving the resilience, legal accountability and human protections required of essential infrastructure.
PILLAR III — GLOBAL COMPETITION, EUROPEAN SOVEREIGNTY AND THE 2031 OUTLOOK
The Political Economy of AI-Native Telecommunications: Industrial Power, Semiconductor Dependencies, European Competitiveness and the Future International Order
Open-Source Strategic Assessment | 23 October 2026 | Forecast Horizon: 2027–2031
Chapter 7 — The Global Strategic Competition for AI-Native Telecommunications
The struggle for control of intelligent telecommunications is becoming a struggle over the international division of technological power
The global competition surrounding sixth-generation telecommunications is developing into a confrontation between different models of industrial organisation, technological sovereignty and control over critical digital infrastructure. It is no longer sufficient to compare countries according to the number of mobile base stations deployed, the geographical extent of fifth-generation coverage or their participation in international radio standards. The emergence of AI-native architectures introduces additional sources of strategic influence, including access to advanced semiconductor manufacturing, ownership of accelerator software ecosystems, control over distributed cloud infrastructure, availability of investment capital and the ability to convert technical research into internationally adopted standards. These factors are not distributed evenly among the world’s principal technological powers. Consequently, the transition towards 6G could alter not only the architecture of mobile networks but also the relationship between telecommunications operators, semiconductor companies, governments and the digital services that increasingly underpin national economic activity.
The competitive structure is particularly important because the economic value of a future intelligent network may be captured by companies that do not own radio spectrum or operate telecommunications services. An accelerator supplier can receive revenue from hardware and software even when the network operator controls the customer relationship. A cloud provider may capture the value of AI applications running near the network. A telecommunications equipment manufacturer may retain the intellectual property associated with radio algorithms and integration. A national operator may own strategically located infrastructure yet receive only a limited proportion of the economic returns generated by applications running over it. The resulting distribution of power will depend on contractual arrangements, industrial concentration, standardisation and the practical ability of operators to substitute technologies.
This transformation is already influencing public policy. On 10 March 2026, the United States National Telecommunications and Information Administration announced a change in direction for the Public Wireless Supply Chain Innovation Fund, shifting its prospective funding emphasis towards AI-native radio access architectures. The NTIA announcement, New Direction for Innovation Fund that Focuses on AI RAN, explicitly connected the initiative to American AI leadership, wireless supply-chain resilience and the development of an American-led technology ecosystem. The agency stated that it would develop a new funding opportunity and would not proceed with awards under the fund’s third previously planned notice. This establishes a concrete industrial-policy change, although it does not establish that the proposed new funding mechanism had already produced commercial AI-RAN deployments.
China is pursuing a different but equally consequential approach. On 4 June 2026, the Ministry of Industry and Information Technology initiated a programme coordinating central government, provincial authorities, telecommunications operators, industrial companies and research institutions around 6G development. The official MIIT notice, 工信厅通信函〔2026〕255号, establishes a framework for research, standards participation, equipment development, industrial applications and regional pilot programmes, with objectives extending to 2029. Its scope includes telecommunications integration with artificial intelligence, satellite communications, wireless sensing, embodied intelligence and specialised equipment manufacturing.
The European Union has adopted a third approach, combining telecommunications research funding, industrial cooperation and prospective regulatory reform. The European Commission’s Smart Networks and Services Joint Undertaking provides an institutional framework for 6G research and international standardisation. The Commission’s January 2026 Digital Networks Act proposal seeks to modernise the economic and regulatory structure of European connectivity markets, addressing fragmentation, investment conditions and security dependencies. These instruments pursue related objectives, but their effectiveness depends on whether Europe can transform research activity and regulatory coordination into internationally competitive products, services and production capacity.
The international competition is therefore taking place simultaneously across research laboratories, commercial telecommunications networks, semiconductor supply chains, public financing programmes, spectrum-allocation decisions and standards organisations. Success in one dimension does not guarantee leadership in the others. A country may possess extensive network infrastructure without controlling the computing platforms required for advanced AI services. Another may produce sophisticated semiconductors while depending on foreign companies for radio access equipment. A third may influence technical standards while lacking the capital necessary to deploy the resulting technology at scale.
The United States: control of accelerated computing as an instrument of telecommunications strategy
The United States enters the emerging competition with a particularly strong position in advanced computing architecture and the commercial development of artificial intelligence platforms. NVIDIA’s role in accelerated computing, the influence of American cloud providers and the depth of the country’s software ecosystem create opportunities to extend American technological influence into telecommunications functions previously dominated by specialised network equipment manufacturers.
This does not imply that American companies control the entire telecommunications supply chain. Advanced semiconductor production is internationally distributed, and major parts of the radio equipment market remain associated with European and Asian manufacturers. The strategic advantage lies instead in the possibility that accelerator platforms and their associated software ecosystems become increasingly important to how telecommunications functions are implemented.
The commercial arrangement between NVIDIA, Nokia and T-Mobile illustrates that possibility. Nokia contributes radio engineering and telecommunications software, NVIDIA supplies accelerated computing technology, and T-Mobile provides the operational telecommunications environment. The 21 October 2026 Nokia announcement documents further activity involving European operators, showing that the architecture is not confined to the United States.
The industrial significance is the potential creation of a broader market for American computing technology within mobile infrastructure. If substantial numbers of radio functions eventually execute on accelerator platforms, semiconductor suppliers may obtain recurring influence over hardware specifications, software development and equipment-upgrade cycles. This could expand their role in telecommunications procurement even where the radio equipment and network operator remain non-American.
The NTIA’s 2026 policy initiative should be understood within this competitive framework. The agency’s focus on AI-native networking suggests that the American government regards the integration of AI and telecommunications as relevant to industrial leadership, not merely as a private-sector optimisation project. The programme’s eventual significance will depend on actual funding awards, beneficiary companies, research outputs, standards contributions and commercial adoption. The March announcement alone cannot establish those outcomes.
The United States also faces strategic limitations. Internationally concentrated semiconductor fabrication and advanced packaging create dependencies that cannot be eliminated through software leadership alone. The rapid development of accelerator technology can increase the cost of telecommunications infrastructure if operators become locked into short equipment-replacement cycles. Dependence on proprietary computing environments may generate resistance from customers and governments seeking greater operational autonomy.
American industrial leadership will therefore depend on whether its technology platforms can provide sustained advantages in performance, cost and developer productivity while remaining acceptable to international operators concerned about supplier concentration. The broader the adoption of a computing ecosystem, the greater its potential commercial returns, but also the greater the scrutiny directed towards its control over critical infrastructure.
China: coordinated industrial development and the ambition to control the complete 6G technology chain
China’s strategy is distinguished by the degree of coordination between national industrial policy, telecommunications operators, equipment manufacturers, research institutions and regional authorities. Its 2026 programme places telecommunications research within a wider industrial framework encompassing chips, operating systems, network equipment, satellite infrastructure, applications and standards participation.
The scale of China’s existing telecommunications infrastructure provides a substantial environment for technical experimentation. In January 2026, the Ministry of Industry and Information Technology reported more than 4.8 million 5G base stations and over 1.2 billion 5G users. These figures were presented in the context of China’s transition to the second phase of its 6G technology trials, following an initial phase that officials said had generated a reserve of more than 300 key technologies. The State Council Information Office’s January 2026 account provides the institutional basis for these statements. They should be treated as official Chinese figures and descriptions of research progress, not as evidence that more than 300 technologies had become commercial or internationally standardised products.
The May 2026 approval of experimental use of the 6 GHz band for 6G research provides a particularly concrete example of China’s approach. The MIIT spectrum authorisation of 8 May 2026 authorised trials by the IMT-2030 Promotion Group in selected regions. This decision creates controlled opportunities to test technologies against prospective 6G requirements. It is not a nationwide commercial allocation and should not be confused with a final international decision concerning future radio spectrum.
The June programme goes further by requiring participating regions to align research and industrial development with national priorities while exploiting local technological specialisations. Its stated objectives include the development of 6G base stations, core networks, transmission infrastructure, measurement equipment, terminals, operating systems and relevant semiconductor capabilities. The programme also addresses industrial applications involving manufacturing, low-altitude economic activity, smart maritime operations and embodied intelligence.
The industrial mechanism is significant. Research and experimentation can be organised around the same operators and equipment ecosystems expected to participate in eventual commercial deployment. This may facilitate the transition from laboratory development to testing and manufacturing. It can also create a sufficiently large domestic market to support particular technology choices before they achieve international adoption.
China’s challenge is that domestic scale does not automatically ensure international acceptance. Global telecommunications markets require interoperability, confidence in infrastructure security, commercially competitive equipment and compatibility with national restrictions imposed by importing countries. The development of separate or partially incompatible technological ecosystems could reduce the economic benefits associated with international standards.
The degree of convergence or separation between Chinese and other international 6G architectures will therefore become a major geopolitical indicator. Cooperation within international standards bodies can preserve technical compatibility even amid political competition. Conversely, persistent disagreements over computing platforms, security requirements, radio interfaces or intellectual property could increase the costs of international telecommunications integration.
Japan: advanced optical infrastructure, telecommunications research and the pursuit of differentiated industrial capabilities
Japan’s strategic position differs from those of the United States and China because its comparative strengths are concentrated in a different combination of advanced electronics, optical technology, telecommunications research and specialised industrial systems. Rather than relying exclusively on competition in accelerator platforms or the scale of domestic mobile networks, Japan has pursued a Beyond 5G research strategy intended to strengthen technologies in which Japanese companies and research institutions can establish internationally competitive positions.
The Beyond 5G R&D Promotion Project administered by Japan’s National Institute of Information and Communications Technology identifies the development of technologies for international competitiveness, commercialisation and incorporation into international standards as principal objectives. The programme includes research addressing specific technical requirements, international collaboration and early-stage innovation.
The importance of this strategy lies in the relationship between next-generation radio networks and optical transport. Increasing the amount of distributed computing within telecommunications networks may increase demand for high-capacity, energy-efficient connections between facilities. Japanese research and industrial capabilities associated with advanced optical communications could therefore remain strategically relevant even if AI accelerator platforms are supplied by foreign companies.
Japan’s wider industrial strategy also involves cooperation between telecommunications operators and equipment manufacturers. A June 2026 Japanese government-supported programme involving NTT DOCOMO, NEC and partners was identified by the European Commission’s 5G Observatory as focusing on research into the use of multiple frequency bands in future 6G systems. This illustrates the continuing importance of radio engineering alongside the expansion of AI computing.
The principal strategic opportunity for Japan is to develop differentiated technologies that remain valuable across alternative global network architectures. Optical transport, advanced radio equipment, devices and specialised industrial electronics can contribute to 6G regardless of whether one particular accelerated-computing ecosystem becomes dominant.
The corresponding risk is that the most profitable software and AI execution layers become concentrated elsewhere. Japanese companies may contribute essential physical and electronic technologies without capturing equivalent value from the applications and computational platforms built upon them. Industrial policy must therefore consider not only technical excellence but also intellectual-property ownership, commercial scalability and participation in international software ecosystems.
South Korea: semiconductor strength, advanced communications and the industrial convergence of AI and electronics
South Korea occupies a strategically important position because of its semiconductor manufacturing capabilities, major electronics companies and experience in commercial mobile telecommunications deployment. These assets provide opportunities to participate across several layers of future intelligent networks, from memory and devices to radio equipment and computing systems.
The country’s research and industrial ambitions are supported by substantial public expenditure. The Ministry of Science and ICT’s confirmed 2026 budget amounted to approximately KRW 23.7 trillion, while the overall Korean government research and development budget was established at KRW 35.5 trillion, an increase of 19.9% over the preceding year. These figures describe broad science and technology expenditure and must not be represented as dedicated 6G investment. They nevertheless indicate the scale of the public research environment supporting strategic areas including artificial intelligence, semiconductors, advanced technologies and defence-related research.
South Korea’s position is particularly relevant to the interaction between computing performance and semiconductor manufacturing. The growth of accelerated computing increases demand for high-performance memory and other advanced components. The strategic economic value of these components may rise even if the final AI-RAN software platforms are developed by companies headquartered elsewhere.
At the same time, South Korea possesses industrial incentives to maintain influence over network equipment and user devices. The commercial significance of 6G will depend partly on whether domestic manufacturers can integrate advances in radio technology, computing systems and devices into products adopted internationally.
The central challenge is to avoid reducing the country’s role to the supply of components while other companies dominate software platforms and service revenues. A competitive national ecosystem requires the ability to convert semiconductor capabilities into differentiated products, international standards contributions and commercially valuable systems.
South Korea’s position may be strengthened by international partnerships, but the most durable value will come from capabilities that remain useful across different hardware and software architectures rather than from dependence on a single commercial platform.
Europe: industrial leadership in telecommunications confronts dependence in accelerated computing
Europe’s strategic position is unusually complex because it possesses globally significant telecommunications engineering capabilities but remains exposed to external suppliers across important areas of advanced computing. Nokia and Ericsson provide an industrial foundation in radio equipment, network software and telecommunications research. European operators possess substantial physical infrastructure and operational expertise. Universities, research institutions and European programmes contribute to advanced communications development.
Yet these strengths do not automatically produce leadership in AI-native networks. If future radio-processing systems depend on accelerator architectures and software environments controlled outside Europe, European companies may retain important radio intellectual property while becoming more dependent on external computing platforms.
The EU’s Smart Networks and Services Joint Undertaking is intended partly to address this challenge. In March 2026, the European Commission announced €116 million for 20 additional 6G research and innovation projects, bringing the reported programme portfolio to 100 projects and placing these awards within approximately €630 million of EU funding under the wider Horizon Europe-supported programme. The Commission also identified a further €270 million of planned investment during 2026–2027. These are programme and financing announcements with different implementation stages, not equivalent amounts of completed infrastructure expenditure. The relevant documentary basis is the European Commission’s announcement of 2 March 2026.
A separate European Commission initiative announced on 30 July 2026 sought to establish up to seven AI Gigafactories, supported by up to €10 billion in EU and national public funding and expected to mobilise at least €20 billion in private investment. The Commission’s AI Gigafactories announcement concerns large-scale AI computing infrastructure, not dedicated AI-RAN deployment. Its relevance is indirect but strategically significant: an expanded European computing ecosystem could improve the availability of infrastructure, expertise and services that complement intelligent telecommunications.
The distinction between research funding, computing investment and commercial telecommunications expenditure is essential. They support different parts of the industrial system and cannot be added together as though they constitute a unified budget for 6G network deployment.
Europe’s institutional challenge is to connect these programmes effectively. Research into advanced radio systems must influence standards and commercial products. AI computing initiatives must provide useful infrastructure and industrial capabilities. Regulatory reform must improve investment conditions without undermining competition, security or public-interest obligations.
The Digital Networks Act proposal of January 2026 addresses several of these issues through proposals intended to simplify the regulatory framework and strengthen the European connectivity market. As of October 2026, it remains a legislative proposal rather than an operative replacement for the existing European Electronic Communications Code.
The strategic question is whether Europe can use its position in radio engineering and telecommunications operations to exercise greater influence over the entire AI-native infrastructure value chain. The answer will depend on industrial coordination, commercial scale, interoperable technology choices and the ability to produce economically competitive systems rather than solely on the number of publicly funded research projects.
Semiconductor manufacturing, advanced packaging and the changing geography of infrastructure dependence
The semiconductor supply chain introduces a crucial distinction between the nationality of a technology company and the geographical location of the manufacturing processes on which it depends. Designing an advanced processor, fabricating it, packaging it and integrating it into a telecommunications server are separate industrial functions. Different companies and jurisdictions can control each stage.
This creates multiple potential points of dependence. Accelerator designers may rely on external semiconductor foundries. Advanced memory production may be concentrated among a limited number of manufacturers. Packaging capacity can constrain the production of completed accelerator systems even when chip designs and fabrication capability are available. Server integration introduces additional suppliers of networking equipment, storage and power systems.
The resulting exposure cannot be adequately assessed by identifying the headquarters of the final hardware vendor. Governments and operators need to understand which components are difficult to substitute, how long replacement equipment would take to obtain and whether alternative products can operate with existing software.
The impact of semiconductor restrictions would also differ between an operator replacing a failed server and a country attempting to develop a fully independent computing platform. The former may require inventories and alternative suppliers. The latter may require extensive semiconductor design, fabrication, packaging and software capabilities developed over many years.
The international structure of advanced semiconductor production consequently makes complete technological self-sufficiency difficult and costly. A more practical objective for many governments is controlled interdependence: preserving access to multiple trusted suppliers, retaining essential operating capabilities and avoiding single points of failure that could interrupt nationally important services.
Spectrum governance as a geopolitical instrument
Radio spectrum remains a strategic resource even as computing becomes more important to network architecture. Governments determine the conditions under which telecommunications operators can use national frequencies, while international coordination helps manage interference and compatibility across borders.
Future 6G development will require decisions concerning how existing and potentially additional frequency bands are used. The choice affects equipment economics, international roaming, industrial applications and the ability of operators to deploy globally compatible systems.
China’s approval of 6 GHz experimental use demonstrates how national administrations can create research opportunities ahead of full international commercial standardisation. Other jurisdictions must balance competing spectrum demands, including established telecommunications services, wireless networking, satellite applications and national-security requirements.
The ITU IMT-2030 programme provides the framework within which future technical candidates will be evaluated, but radio-interface evaluation and national spectrum licensing are distinct processes. A technically successful radio system does not automatically receive spectrum rights in every market.
Spectrum decisions can also influence industrial competition. Greater international alignment creates economies of scale for equipment manufacturers and device suppliers. Divergent national allocations can require additional hardware variants, increase testing costs and weaken interoperability.
For governments, the strategic objective should be to preserve the productive use of existing spectrum while creating credible conditions for experimentation and future standards-based deployment. Speculative allocation policies based on unproven technical benefits risk imposing costs before the commercial value of new systems is established.
Chapter 7 — Global institutional and industrial comparison
| Jurisdiction | Verified policy or industrial initiative | Quantitative baseline or announced commitment | Principal competitive advantage | Strategic exposure |
|---|---|---|---|---|
| United States | NTIA’s March 2026 AI-RAN-oriented Innovation Fund direction | No verified award total attributable to the new AI-RAN funding direction in the cited announcement | Accelerator platforms, software, cloud ecosystems | Semiconductor production dependencies and platform concentration |
| China | MIIT’s June 2026 central-provincial 6G programme | More than 4.8 million 5G base stations and 1.2 billion users reported in January 2026 | Domestic market scale and coordinated industrial policy | Export restrictions, international market acceptance and technology dependencies |
| Japan | NICT Beyond 5G research programmes and government-supported 6G research | No comparable national AI-RAN deployment budget established here | Optical technology, electronics and advanced communications research | Capturing value in software and AI platforms |
| South Korea | MSIT-supported strategic research and industrial development | KRW 23.7 trillion MSIT budget and KRW 35.5 trillion government R&D budget for 2026, across all research areas | Semiconductor memory, devices and electronics manufacturing | Dependence on complementary computing architectures and international software |
| European Union | SNS JU, Digital Networks Act proposal and AI computing initiatives | €116 million for 20 new 6G projects; broader €630 million EU SNS funding; up to €10 billion public support announced for AI Gigafactories | Radio engineering, operators, regulation and research institutions | Fragmented capital markets and external computing dependencies |
The figures concern different financial or operational categories and are not suitable for a numerical ranking of national 6G leadership.
Chapter 7 judgment: The emerging international competition is not a single technological race with one winner. It is a struggle to control complementary components of an increasingly integrated infrastructure economy. American computing platforms, Chinese industrial coordination, Japanese optical and electronics research, South Korean semiconductor capabilities and European radio engineering may all remain essential. Strategic influence will depend on which countries and companies control the interfaces between these capabilities and can convert them into profitable, interoperable and trusted systems.
Chapter 8 — Italy, France, Germany and the United Kingdom: Four Different Paths to Network Sovereignty
The European transition will be determined by four distinct telecommunications economies rather than one unified deployment model
The future of AI-native telecommunications in Europe will depend on the interaction between national market structures, industrial capabilities, infrastructure conditions and public policy. Italy, France, Germany and the United Kingdom possess substantial telecommunications markets, but their starting conditions are materially different. The scale and maturity of fibre infrastructure, the financial position of operators, the structure of industrial demand, national cybersecurity institutions and public attitudes towards technological dependence all influence whether accelerated communications infrastructure becomes commercially attractive.
It would therefore be misleading to treat announced AI-RAN trials as evidence that the participating countries possess equivalent investment capacity or comparable technological maturity. A country may have a highly developed mobile market but limited commercial demand for local AI inference. Another may have advanced industrial automation requirements but face difficulties integrating computing across geographically dispersed facilities. A third may benefit from extensive fibre infrastructure while experiencing declining telecommunications revenue and investment. The final commercial architecture will reflect these differences.
European sovereignty also cannot be reduced to the domestic ownership of telecommunications equipment. A national operator may own radio sites while relying on external suppliers for important software and computing functions. Another may use foreign-designed hardware while retaining substantial operational control and the ability to migrate between suppliers. The relevant policy question is which forms of dependence create unacceptable national risk and which can be managed through contractual, technical and institutional safeguards.
Italy: telecommunications restructuring, spectrum policy and the challenge of converting industrial demand into network investment
Italy approaches the AI-native transition from a telecommunications environment shaped by strong price competition, substantial investment requirements and an ongoing restructuring of fixed and mobile infrastructure. The national market contains major operators, specialised infrastructure companies and industrial customers potentially interested in local computing and advanced wireless services. Yet the commercial attractiveness of AI-RAN depends on whether these conditions translate into investable projects rather than simply creating another layer of capital expenditure.
The most important starting point is the relationship between operators’ existing financial resources and their future investment commitments. The 2026 Annual Report of the Italian communications regulator, AGCOM, covers regulatory activity from May 2025 to April 2026 and provides an institutional assessment of the telecommunications environment. It places the evolution of connectivity infrastructure within the wider transformation of Italy’s digital economy.
Italy’s spectrum position is particularly significant because frequency licensing influences the capital available for network modernisation. The country’s expensive 2018 5G spectrum allocation created obligations that remain relevant to operator financing and the longer-term renewal of usage rights. The strategic issue for AI-RAN is whether spectrum policy enables operators to invest in new infrastructure while preserving competition and the public value of scarce radio resources.
The Italian government and AGCOM must balance several objectives. Operators need sufficiently predictable licence conditions to plan investment over multiple years. The state must preserve fair access to spectrum and competitive market conditions. Industrial customers require reliable connectivity and commercially viable services. Consumers and public institutions need continuity, security and adequate geographical coverage.
A technology transition that requires additional accelerated computing can intensify these competing demands. Operators may wish to invest in selected urban or industrial locations with strong demand, while rural coverage and ordinary network renewal remain essential obligations. Public policy should therefore avoid assuming that investment in AI-enabled infrastructure automatically improves the broader national connectivity environment.
The commercial importance of Italy’s industrial structure is nevertheless considerable. Manufacturing districts, logistics facilities, ports, healthcare organisations and utility systems can create demand for connected computing services. The challenge is to translate this potential into contracts that justify infrastructure investment. A factory already operating local computing systems may have little reason to purchase a telecom-operated alternative unless the new arrangement offers measurable savings, better reliability or additional functionality.
NVIDIA’s October 2026 telecommunications announcement identified TIM and Fastweb + Vodafone among operators involved in NVIDIA-powered infrastructure initiatives. These disclosures are relevant to Italy’s participation in the emerging computing ecosystem, but they must not be interpreted as proof of equivalent commercial AI-RAN deployment across the country. The distinction between participation in accelerated infrastructure and verified operational radio processing remains essential.
Italy’s national strategic opportunity lies in connecting telecommunications investment with its industrial base. Rather than attempting indiscriminate network transformation, the country could prioritise locations where industrial demand, existing fibre and computing requirements justify advanced infrastructure. Such projects would be more persuasive if they involved domestic systems integrators, industrial equipment suppliers, research institutions and cybersecurity capabilities rather than relying exclusively on imported platforms.
From a defence and national-security perspective, Italy also requires clear governance over critical telecommunications suppliers, software dependencies and the interfaces linking civilian infrastructure to strategically important activities. Its role within NATO and European security arrangements reinforces the importance of interoperability and continuity, but there is no basis for assuming that ordinary commercial AI-RAN infrastructure is automatically suitable for classified defence applications.
Italy’s principal policy challenge is consequently one of investment selection and institutional coordination. It must avoid both premature infrastructure expenditure without demonstrable demand and underinvestment that would leave domestic industry dependent on computing services controlled elsewhere.
France: extensive digital infrastructure, industrial ambition and pressure on telecommunications profitability
France enters the AI-native transition with substantial fixed-network infrastructure and an established regulatory framework. Its national position is strengthened by the scale of fibre deployment, the presence of major telecommunications operators and a broader industrial strategy emphasising digital technologies, cybersecurity and national technological capability. At the same time, the financial circumstances of the telecommunications sector place limits on the speed at which operators can finance additional capital-intensive infrastructure.
The latest ARCEP telecommunications market observatory, updated on 8 October 2026, provides an unusually detailed quantitative picture. At the end of June 2026, France had 28.1 million fibre internet subscriptions, representing approximately 85% of fixed internet subscriptions. The regulator reported 43.1 million premises eligible for fibre access, equivalent to more than 95% of the relevant national premises total. Mobile networks recorded 37.5 million SIM cards active on 5G networks, representing approximately 44% of all active SIM cards, while average mobile data consumption reached 19.3 GB per customer per month during the second quarter.
These indicators demonstrate the maturity of France’s connectivity environment, but they do not measure AI-RAN readiness directly. Fibre penetration can facilitate transport and aggregation, while 5G adoption can support a commercial environment for advanced services. Neither guarantees that accelerated computing investments will produce adequate returns.
The financial picture introduces an important constraint. ARCEP reported retail telecommunications revenue of approximately €9.1 billion excluding tax in the second quarter of 2026, down 1.3% year on year. The regulator also recorded a reduction in mobile service revenue. This matters because future investment must be financed in a market where subscriber growth and data consumption do not necessarily generate proportional revenue growth.
The longer-term investment trend is even more consequential. According to ARCEP’s 2025 annual telecommunications market assessment, French telecommunications operators and mobile infrastructure companies invested approximately €10.3 billion in 2025, excluding spectrum purchases. This represented a decline of approximately 15% from the previous year and the fourth consecutive annual decrease. The contraction was associated partly with the progression towards completion of major fibre deployment programmes.
This creates a strategic paradox. France possesses infrastructure that could support advanced computing deployment, but the operators expected to finance that deployment face pressure on revenues and investment. The economic case for AI-RAN must consequently be sufficiently strong to compete against ordinary network renewal, fibre maintenance, cybersecurity obligations and other capital priorities.
Orange’s participation in Nokia and NVIDIA’s AI-RAN activities is relevant because it may connect telecommunications functions with enterprise AI services and operational automation. The operator has announced work on radio processing and local AI applications. These projects should be assessed according to whether they create measurable commercial value and strengthen operational autonomy rather than merely demonstrating compatibility with a particular computing platform.
France also has institutional advantages in cybersecurity, digital regulation and public research. The challenge is to integrate these capabilities into procurement and investment decisions without assuming that national industrial ambition can overcome weak commercial economics. Public support may be justified for research, interoperability and strategically important infrastructure, but long-term deployment must ultimately be supported by sustainable operating models.
From a defence perspective, France’s national-security and strategic-autonomy traditions make supplier governance particularly important. The ability to preserve control over sensitive communications and associated computing infrastructure is likely to remain a central consideration. Commercial AI-RAN systems can contribute to national technological capability without necessarily satisfying the requirements of defence-controlled systems.
France’s most credible pathway is therefore selective expansion where fibre availability, enterprise demand and regulatory governance create a strong investment case, combined with continued participation in European research and standards programmes.
Germany: industrial demand, advanced manufacturing and the challenge of converting laboratory performance into production infrastructure
Germany’s position differs from France’s because its industrial structure may create particularly strong demand for integrated communications and computing within manufacturing, logistics and engineering environments. The country’s economic dependence on complex industrial systems makes the interaction between reliable networking, industrial software and local AI processing strategically important. Yet the commercial development of AI-RAN will depend on whether operators can translate technical research into products that satisfy the cost and reliability requirements of industrial customers.
Deutsche Telekom’s work with Nokia and NVIDIA is therefore significant beyond the telecommunications sector itself. The companies have reported laboratory work involving AI-based channel estimation, with subsequent field activity planned for 2027. The reported uplink performance improvements represent a defined technical result, but Germany’s broader strategic opportunity lies in applying future technologies to environments where production processes justify reliable local computing.
A manufacturing installation may require machine-vision processing, monitoring and coordination across production systems. The potential value of an integrated network-compute service depends on whether it can meet those requirements more effectively than existing industrial networks and local computing facilities. German industry is unlikely to adopt a new architecture at scale merely because it offers superior laboratory throughput. It will require convincing evidence concerning reliability, security, maintenance, interoperability and cost.
Germany’s telecommunications infrastructure also presents practical constraints. Urban and industrial centres differ considerably from rural areas in fibre availability, site conditions and demand concentration. A national deployment strategy must consequently recognise differences in the location and commercial value of computing services.
The Bundesnetzagentur’s June 2026 broadband measurement report found that 55.3% of the mobile measurements included in its 2024–2025 reporting period used 5G, compared with 43.8% in the previous period. This measures the composition of tests submitted through the regulator’s measurement tools, not the proportion of Germany’s entire population using 5G or the share of radio sites technically ready for AI-RAN. The distinction matters because adoption indicators can easily be misinterpreted when their statistical definitions differ.
Germany’s industrial policy must also address the interaction between accelerated computing and electricity infrastructure. Dense computing facilities require dependable electrical capacity and suitable cooling. The economic value of local AI may be significant in industrial environments, but infrastructure costs must be assessed against energy conditions and alternative computing arrangements.
The country’s research and engineering institutions provide opportunities to develop alternatives and complementary technologies. German participation in European 6G research, advanced radio engineering and international standards activities can strengthen technological competence even if commercial AI-RAN deployment follows a gradual trajectory.
The most important national decision is whether to support a broad telecommunications migration or concentrate initially on industrially justified deployments. The latter may provide clearer evidence of demand and allow operators to learn from operational experience before committing to larger investments.
Germany’s defence and cybersecurity considerations further reinforce the need for controlled infrastructure design. Industrial networks and strategically important communications systems must not acquire uncontrolled dependencies simply because computing resources are consolidated. Supplier assurance, independent operations and appropriate separation between public networks and sensitive industrial or defence systems will remain essential.
Germany’s most distinctive opportunity is to use its industrial base as a source of real-world technical requirements. If German manufacturers can help define commercially relevant use cases, the country may influence future specifications and system design without needing to dominate every semiconductor or software layer.
The United Kingdom: commercial experimentation, telecommunications resilience and the economics of cloud-native transformation
The United Kingdom enters the transition with a different institutional environment, combining a major commercial telecommunications sector, established research capabilities and a regulatory framework separate from the European Union. Its industrial significance lies partly in the potential to develop cloud-native communications, software-based network operations and specialised enterprise services within a market where operators already face substantial infrastructure investment requirements.
Ofcom’s Connected Nations Spring 2026 update provides a useful baseline. Based on network information for January 2026, the regulator reported gigabit-capable broadband availability for approximately 89% of UK homes, equivalent to 27.1 million premises. Across the three mobile operators that had deployed 5G Standalone, outdoor premises coverage ranged from 49% to 85%. Overall 5G coverage, including standalone and non-standalone networks, ranged between 76% and 94% outside premises for individual operators, while coverage outside premises from all operators was reported at approximately 64%.
These figures illustrate both the scale and the unevenness of network development. A substantial commercial network footprint creates opportunities for advanced services, but differences between operators and geographical areas affect where such services can be deployed economically.
BT’s planned AI-RAN field trial in Birmingham during 2027 provides an important test of operational feasibility. Its significance will depend on whether the trial produces measurable evidence concerning radio performance, shared computing, operating costs and commercial applications. The announcement itself does not establish the commercial scale or financial return of the eventual deployment.
The United Kingdom’s competitive position is influenced by the relationship between telecommunications operators and cloud providers. A market with strong software and service capabilities may create opportunities to develop commercial applications around distributed network computing. At the same time, operators must avoid becoming infrastructure providers whose capital expenditure primarily benefits external platforms.
Cybersecurity and national resilience are central considerations. The United Kingdom possesses established institutions for communications regulation and national cybersecurity, while its telecommunications infrastructure supports essential government, commercial and public services. AI-native architectures should therefore be evaluated against the requirements of continuity, supplier assurance and recovery rather than solely through their potential contribution to innovation.
The UK’s policy flexibility outside the EU regulatory framework could permit different approaches to certain market and technology decisions, but divergence is not inherently advantageous. Operators and suppliers participate in international markets where interoperability and compatibility remain economically important. Unnecessary divergence could increase equipment costs or complicate standards participation.
The most credible British strategy is to exploit research and commercial experimentation while maintaining demanding requirements for evidence and resilience. Successful trials could support selective deployment and new services, but network-wide investment should remain conditional on demonstrable economic performance.
European comparative evidence: infrastructure maturity and financial constraints
| Indicator | Italy | France | Germany | United Kingdom |
|---|---|---|---|---|
| Principal official regulatory institution | AGCOM | ARCEP | Bundesnetzagentur | Ofcom |
| Latest relevant official baseline reviewed | AGCOM Annual Report 2026, mainly May 2025–April 2026 | ARCEP Q2 2026 and full-year 2025 market reports | Bundesnetzagentur 2024–2025 measurements published June 2026 | Ofcom Spring 2026, January 2026 network snapshot |
| Specific verified connectivity indicator | National market and investment baseline documented in AGCOM annual reporting | 37.5 million active 5G SIMs in Q2 2026 | 55.3% of regulator-app mobile measurements were on 5G in reporting year 2024–2025 | 5G SA outdoor premises coverage of 49–85% among three deploying operators |
| Fixed-network infrastructure indicator | FTTH and fixed access indicators available through AGCOM statistical reporting | 28.1 million fibre subscriptions; more than 95% fibre premises eligibility in Q2 2026 | Broadband performance reported through the regulator’s measurement programme | 89% gigabit-capable broadband availability in January 2026 |
| Quantified financial constraint | Operator investment capacity affected by market competition and spectrum obligations | €10.3 billion sector investment excluding spectrum in 2025, down approximately 15% | Industrial deployment economics and infrastructure costs must be assessed separately | Continued commercial network renewal and expansion |
| Specific AI-RAN-related development | TIM and Fastweb + Vodafone participation in the wider accelerated infrastructure ecosystem | Orange testing AI-RAN-related functions and applications | Deutsche Telekom–Nokia laboratory development, field validation planned | BT Birmingham field trial planned for 2027 |
| Principal strategic opportunity | Manufacturing districts, ports, industrial and public-service applications | Extensive fibre infrastructure and enterprise services | Advanced manufacturing, industrial AI and engineering research | Cloud-native services, enterprise applications and network automation |
| Principal strategic risk | Weak investment returns or externally controlled computing dependencies | Declining operator investment and pressure on service revenues | High integration requirements and uncertain deployment economics | Supplier dependence and insufficient commercial returns |
The indicators deliberately preserve their different definitions. Active SIM cards, test-sample composition, premises coverage and fibre subscriptions cannot be treated as comparable percentages of national AI-RAN readiness.
Four national strategies within one European industrial problem
Italy’s immediate challenge is the mobilisation of investment in a competitive telecommunications market. France must combine strong fibre infrastructure with an operator sector experiencing declining investment. Germany has the opportunity to connect advanced network research with demanding industrial applications. The United Kingdom can exploit commercial experimentation and software capabilities while maintaining infrastructure resilience.
These differences suggest that a uniform European deployment strategy would be economically inefficient. The most valuable European coordination may concern common standards, interoperability testing, procurement principles, cybersecurity assurance and research funding, while commercial deployment remains responsive to national and local conditions.
The European Union can provide a common framework for many of these activities, but national regulators retain important responsibilities, and the United Kingdom operates outside the EU legislative system. Cooperation must therefore accommodate different legal structures without sacrificing technical compatibility.
Chapter 8 judgment: European technological sovereignty will not be achieved by making all four countries follow the same industrial model. It will depend on connecting their complementary strengths while preserving sufficient competition, interoperable infrastructure and nationally appropriate investment decisions. The greatest risk is that fragmented procurement and weak commercial returns prevent European operators from influencing the next generation of technology platforms, even while European radio engineering remains internationally significant.
Chapter 9 — The Economics and Governance of 6G, 2027–2031
The next investment cycle must resolve a fundamental imbalance between technological ambition and telecommunications profitability
The economic transition towards 6G will occur within an industry whose capital requirements remain substantial but whose revenue growth is uneven. Telecommunications operators must continue to finance coverage, equipment replacement, fibre transport, cybersecurity, spectrum obligations and ordinary service improvements while evaluating new investments in accelerated computing and distributed AI. The critical issue is whether intelligent infrastructure can create enough additional economic value to justify a broader role for telecommunications operators in computing services, or whether it will increase their capital burden while allowing semiconductor and software suppliers to capture a disproportionate share of the returns.
The evidence from France provides a concrete illustration of this pressure. ARCEP’s 2025 reporting shows declining sector investment and reduced mobile service revenue despite continued growth in fibre adoption and 5G usage. This demonstrates that increasing consumption of telecommunications services does not necessarily translate into increasing financial resources for infrastructure investment. If AI-RAN raises equipment and operating costs without generating sufficient additional revenue or measurable efficiency gains, operators may face greater financial strain rather than improved competitiveness.
The financial model of 6G must therefore distinguish the cost of maintaining connectivity from the potential returns of computing services. Operators may be required to invest in new radio technology regardless of whether local AI applications become profitable. Conversely, a successful AI service may be delivered through computing infrastructure that does not require a complete transition to 6G. The economics of radio modernisation and AI service provision are linked but not identical.
This distinction is relevant to public policy because governments may be tempted to support advanced infrastructure primarily through the expectation of future technological growth. Public research funding can help reduce uncertainty and produce useful industrial knowledge, but large-scale deployment support should be justified by clearly identified economic or public-interest objectives. Without such discipline, investment programmes may finance expensive systems before sufficient demand exists.
The allocation of value between operators, semiconductor suppliers and AI platforms
The future distribution of financial value is likely to depend on which participants control resources that are difficult to substitute. Telecommunications operators possess spectrum rights, network locations, customer relationships and regulated infrastructure. Equipment suppliers possess specialised radio engineering and integration expertise. Accelerator manufacturers control important computing architectures and software tools. Cloud providers and AI developers may own the applications customers are ultimately willing to purchase.
These resources have different commercial characteristics. Spectrum and physical infrastructure are capital-intensive and geographically constrained. Software platforms can sometimes expand internationally with relatively low marginal distribution costs. Semiconductor manufacturing requires enormous fixed investment and specialised technical capability. AI models can create differentiated services but face uncertain demand, competitive substitution and substantial development costs.
A potential economic imbalance arises when the operator finances distributed computing equipment but external application providers retain control of the most profitable services. The operator may receive hosting or connectivity fees while bearing the costs of power, maintenance, physical security and equipment replacement. Such a model can be sustainable, but only if the fees adequately compensate the operator for the resources and risks involved.
The alternative is for operators to develop proprietary or jointly controlled AI services. This could increase their share of revenue but would expose them to competition from established software and cloud companies. Telecommunications engineering expertise does not automatically provide an advantage in every application market. Operators may consequently obtain better returns through partnerships with specialised service providers, provided contractual arrangements preserve appropriate control and revenue participation.
The strategic question is not whether operators should become artificial intelligence companies in every sense. It is whether they can negotiate a sustainable role in the emerging market for distributed computing without allowing their infrastructure investments to become a subsidised foundation for services controlled by others.
Infrastructure financing and the difference between research budgets, public support and commercial expenditure
The financial architecture of future networks will involve several distinct sources of capital. Public research programmes finance scientific and technical development. Telecommunications operators fund commercial deployment and service maintenance. Equipment manufacturers invest in product engineering and production. Cloud companies may finance facilities and computing systems. Public authorities may provide targeted infrastructure support where commercial investment is insufficient to achieve national objectives.
These flows must be kept separate when assessing the scale of national or European investment. The European Smart Networks and Services Joint Undertaking has a programme budget of at least €1.8 billion for 2021–2027, including a €900 million EU contribution intended to be matched by industry. This is a research and innovation funding framework, not a commitment to install €1.8 billion of AI-RAN equipment in commercial networks.
Similarly, the European AI Gigafactories programme concerns large-scale AI computing capacity and associated financing arrangements. Its announced public and private financing expectations cannot be represented as dedicated telecommunications investment. The initiatives may reinforce one another through shared technological capabilities, but their financial outputs and intended beneficiaries differ.
China’s coordinated 6G development programme and South Korea’s broader research budget illustrate different institutional models. The former emphasises coordinated industrial experimentation and regional implementation, while the latter establishes substantial public research resources across several strategic technologies. Neither provides a directly comparable measure of commercial AI-RAN capital expenditure.
For investment analysis, the critical distinction is between announced resources, legally committed funds, contracted expenditure, equipment delivered and services operating commercially. A government announcement can create important expectations without resulting immediately in usable infrastructure. Public authorities should monitor implementation through procurement awards, project completion, technical acceptance and actual service operation.
Verified public investment and policy baselines
| Programme or indicator | Reported amount or status | Period | Financial or institutional definition | Appropriate interpretation |
|---|---|---|---|---|
| EU SNS JU | At least €1.8 billion total planned framework | 2021–2027 | €900 million EU contribution intended to be matched by private members | Research and innovation programme |
| EU SNS research portfolio | €116 million for 20 additional projects | Announced March 2026 | Research and innovation funding announcement | Not commercial AI-RAN deployment expenditure |
| EU SNS broader programme | Approximately €630 million EU funding identified | By March 2026 announcement | Programme-level Horizon Europe contribution | Wider research funding context |
| EU future SNS activity | €270 million further investment planned | 2026–2027 | Forward-looking programme intention | Not automatically contracted expenditure |
| EU AI Gigafactories | Up to €10 billion public support and at least €20 billion expected private investment | July 2026 initiative | Announced large-scale AI infrastructure financing framework | Not a 6G-specific capital budget |
| South Korea MSIT | KRW 23.7 trillion | 2026 | Ministry-wide budget | Covers multiple strategic fields |
| South Korea government R&D | KRW 35.5 trillion | 2026 | Total national research and development budget | Not dedicated to telecommunications |
| France telecom investment | Approximately €10.3 billion | 2025 | Operator and mobile-infrastructure investment, excluding spectrum | Realised national sector investment |
| United States NTIA | New AI-RAN funding direction announced | March 2026 | Prospective restructuring of the Innovation Fund | Requires award-level verification |
| China MIIT programme | Central-provincial 6G coordination launched | June 2026 | Industrial research and pilot programme | Policy implementation, not a single budget line |
The source documents are the European SNS JU institutional framework, March 2026 EU research announcement, European AI Gigafactories initiative, South Korea’s 2026 budget statement, ARCEP’s annual market assessment, NTIA’s AI-RAN policy announcement and China’s MIIT programme.
Procurement strategy and the danger of irreversible platform commitments
Procurement decisions taken during the early development of AI-native networks may shape operator dependencies for many years. A server platform may be technically replaceable while the software running on it remains dependent on vendor-specific acceleration libraries, management tools or optimised implementations. The commercial cost of migration can therefore be substantially greater than the purchase price of alternative hardware.
Procurement authorities should distinguish compatibility with an open telecommunications interface from genuine computing portability. An equipment supplier may implement standard radio interfaces but still rely on proprietary execution environments. Likewise, software advertised as portable may deliver materially different performance on alternative accelerators.
The economically relevant question is the cost of exercising the operator’s right to change suppliers. A contractual right to terminate an agreement provides limited strategic protection if replacement would require extensive software redevelopment, operational interruption or unplanned equipment purchases. Effective procurement governance therefore requires evidence of practical substitutability.
The strongest contracts should establish responsibilities for software maintenance, vulnerability disclosure, technical documentation, interoperability testing and continuity following changes in commercial relationships. These provisions can reduce the risk that technical dependence becomes an irreversible financial commitment.
A further concern arises from rapid hardware development. Accelerators designed for AI applications may experience shorter competitive replacement cycles than traditional telecommunications installations. Operators must assess whether the expected service benefits justify the possibility of replacing equipment earlier than planned.
The interaction with public procurement is particularly sensitive. Governments may finance research or infrastructure intended to strengthen national technological sovereignty while inadvertently creating dependence on one computing platform. Supplier diversity, open interfaces and independently testable migration paths should therefore be considered in programme design rather than added after deployment.
Spectrum economics and the cost of long-term regulatory uncertainty
Spectrum regulation influences operators’ ability to commit capital because radio licences determine access to essential production resources. Investments in antennas, computing equipment and transport infrastructure are economically connected to the frequencies operators are authorised to use and the period over which those rights remain available.
Long-term uncertainty regarding licence renewal, fees or operating conditions can increase the financial risk of infrastructure modernisation. Conversely, excessively favourable licensing arrangements without adequate competition safeguards may transfer public value to incumbent operators without guaranteeing additional investment.
The appropriate balance depends on national market conditions. Operators require predictable rights, but governments must preserve efficient spectrum use, competition and the possibility of introducing new services.
Future 6G spectrum decisions also have implications for equipment standardisation. Divergent national allocations may reduce the economies of scale available to device and equipment manufacturers. Internationally aligned spectrum frameworks can support lower equipment costs, although national administrations retain legitimate reasons to protect existing uses.
China’s May 2026 experimental authorisation demonstrates how national regulators can enable research without making irreversible commercial allocations. European and other jurisdictions can pursue similar evidence-based experimentation while allowing international standards processes to mature.
The objective should be to create predictable investment conditions without assigning excessive financial value to technologies whose commercial characteristics remain uncertain.
Energy, sustainability and the competition for computing infrastructure
The economics of future telecommunications will be increasingly influenced by electricity availability and the infrastructure required to support advanced computing. The introduction of accelerated systems into network facilities may add demand for power, cooling and backup capacity, particularly where operators deploy substantial computing resources near densely populated areas.
Energy constraints will vary geographically. A facility with adequate electrical capacity and efficient cooling may support a computing installation at reasonable cost. Another may require expensive upgrades to power distribution, thermal management or resilient supply. Operators must therefore incorporate local infrastructure conditions into investment planning.
Sustainability claims should also distinguish improvements in efficiency from reductions in absolute consumption. An architecture may consume less electricity per unit of delivered service while increasing total demand because the volume of connectivity and AI processing expands. Similarly, better accelerator utilisation can improve capital productivity without necessarily reducing peak electrical requirements.
The economics of local AI services will depend partly on whether they displace computing performed elsewhere or simply add new demand. If processing moves from a central data centre to a distributed facility, the relevant comparison includes changes in transport energy, local cooling, computing efficiency and infrastructure utilisation. If new applications are introduced, their electricity consumption must be assessed as an additional activity.
Governments should therefore avoid treating AI-native infrastructure as inherently environmentally beneficial or harmful. The correct policy is to require measurable energy performance, transparent reporting boundaries and infrastructure planning that reflects local electricity conditions.
Skills, industrial organisation and the institutional capacity to operate more complex networks
Technological adoption depends on the availability of personnel capable of integrating radio systems, accelerated computing and software operations. These capabilities are distributed across disciplines that historically have not always worked within the same organisational structures.
Radio engineers understand propagation, interference, timing and telecommunications protocols. Software specialists understand virtualisation, orchestration and application development. AI engineers manage models, data and inference systems. Cybersecurity specialists assess vulnerabilities, privileged access and incident response. Infrastructure engineers manage electricity, cooling and physical facilities.
An AI-native operator must coordinate these capabilities effectively. The absence of organisational integration can create failures even when the underlying technology is technically sound. A computing team may optimise accelerator utilisation without recognising its effect on radio-processing deadlines. A network operations team may approve a software change without understanding the consequences for model execution. A security response may isolate equipment without adequate preparation for service continuity.
Workforce development should therefore focus on multidisciplinary competence and well-defined operational responsibilities. The goal is not to replace every telecommunications specialist with an AI developer, but to ensure that technological decisions reflect the constraints of the complete infrastructure system.
Public research institutions and universities can contribute by developing practical training environments, interoperability testbeds and joint programmes involving telecommunications, computing and industrial engineering. Such investment may provide longer-term benefits than narrowly subsidising one generation of commercial hardware.
Chapter 9 — Capital allocation and governance alternatives
| Investment model | Appropriate conditions | Expected economic mechanism | Principal downside | Procurement implication |
|---|---|---|---|---|
| Conventional network renewal | Existing architecture remains cost-effective | Lower integration risk and predictable operations | Limited new computing-service opportunities | Preserve upgrade flexibility |
| Selective AI-RAN deployment | Demonstrated demand at particular locations | Targeted radio and computing benefits | Uneven utilisation | Require location-specific business cases |
| Aggregated accelerated processing | Strong transport and sufficient workload density | Shared infrastructure and economies of scale | Concentrated failures and infrastructure cost | Require geographic resilience and isolation |
| Operator–cloud partnership | Identifiable AI service demand | Shared commercial investment and service expertise | Value capture by external platforms | Define revenue, control and exit rights |
| Industrial private-network integration | Strong enterprise demand and specialised applications | Contracted local services | Dependence on limited customers | Establish long-term service commitments |
| Public-interest infrastructure investment | Commercial returns insufficient for essential national needs | Resilience, inclusion or strategic capability | Fiscal exposure and inefficient allocation | Define measurable public outcomes |
| Research and standards investment | Technical uncertainty remains high | Knowledge, intellectual property and interoperability | Weak commercialisation | Link funding to verifiable technical outputs |
Chapter 9 judgment: The next network investment cycle should be governed by the economic value of specific services and the cost of maintaining resilient infrastructure, not by the assumption that AI-native computing will automatically generate new telecommunications revenues. Governments can improve innovation and competitiveness through targeted research, interoperability and regulatory certainty, but premature capital commitments may increase dependence and financial exposure before commercial demand becomes demonstrable.
Chapter 10 — Strategic Scenarios, Early-Warning Indicators and Government Policy Options
The international telecommunications order to 2031 will be shaped by adoption pathways rather than one inevitable architectural outcome
The strategic outlook for AI-native telecommunications remains open because technical feasibility, commercial economics, standards development and geopolitical conditions are evolving at different speeds. The successful demonstration of an accelerated radio-processing architecture does not establish that it will become the dominant implementation of future mobile networks. Equally, the continued attractiveness of specialised radio equipment does not preclude substantial adoption of shared computing in selected locations or services. The most plausible outcome may be a heterogeneous market in which different architectures coexist according to national conditions and application requirements.
A defensible forward assessment must distinguish the probability of continued experimentation from the probability of large-scale commercial replacement. The former is supported by the breadth of operator partnerships, research programmes and public policy initiatives already documented in 2026. The latter depends on evidence that remains incomplete, including production-scale reliability, independently comparable economics and practical interoperability.
Three broad future pathways deserve particular attention. They are not mutually exclusive: one may prevail in particular countries or applications while another dominates elsewhere.
Scenario A — Accelerated AI-native infrastructure becomes a major mainstream architecture
Under this pathway, commercial trials between 2027 and 2029 demonstrate that accelerated radio processing can satisfy service requirements while delivering economically meaningful improvements. Operators obtain sufficient benefits from spectrum utilisation, computing consolidation or commercial AI services to justify larger deployments. Hardware and software suppliers develop more interoperable products, while management systems reduce operational complexity rather than adding to it.
The principal industrial consequence would be a greater role for accelerated-computing suppliers and software ecosystems within telecommunications procurement. Operators might obtain more flexible infrastructure and new commercial opportunities, but their bargaining position would depend on whether they could maintain supplier diversity and capture enough of the value created by distributed computing.
The geopolitical implications would be substantial. Countries controlling important computing architectures, acceleration libraries and semiconductor capabilities could increase their influence over telecommunications technology. Governments would be required to evaluate dependence on computing platforms with the same seriousness previously applied to critical radio equipment and network cores.
This pathway would be supported by audited commercial deployments showing reliable service, measurable savings and meaningful external computing revenues. It would be weakened if benefits remained dependent on favourable laboratory conditions or if additional operating costs absorbed the gains.
Scenario B — AI-RAN develops into a selective infrastructure model concentrated in high-value environments
Under the second pathway, accelerated radio and computing integration proves valuable in particular locations but fails to justify universal deployment. Dense urban networks, major industrial facilities, transport hubs and selected public-service environments may support sufficient demand to sustain investment. Other sites continue to use specialised or more conventional virtualised architectures because their traffic profiles, electrical conditions or economics favour simpler solutions.
This outcome would produce a more differentiated telecommunications market. Major operators could combine multiple infrastructure architectures within one national network, using advanced computing where it creates value and preserving less expensive processing where additional capabilities are unnecessary.
The economic consequences may be favourable if selective adoption prevents excessive capital expenditure. The principal social risk would be unequal geographical access to advanced computing services if commercially attractive locations receive most of the investment.
Governments would need to distinguish genuinely essential public-interest applications from services whose value depends mainly on commercial demand. Targeted infrastructure support could be justified in some cases, but it should not become a general subsidy for uneconomic equipment deployment.
This pathway would be supported by profitable location-specific deployments and continued use of alternative architectures elsewhere.
Scenario C — Technological fragmentation and persistent dependence on proprietary ecosystems
The third pathway involves continued technological innovation without sufficient convergence in computing architecture, software portability or international standards implementation. Operators may adopt different accelerator environments, suppliers may optimise around proprietary frameworks and countries may introduce divergent technology restrictions or procurement requirements.
The result would not necessarily be complete incompatibility at the radio interface. International standards could preserve basic mobile connectivity while computing platforms, AI control systems and operational-management environments become increasingly fragmented.
The economic consequences could include higher integration costs, reduced supplier substitutability and more difficult cross-border operations. Smaller operators and countries with limited technical resources might become especially dependent on vendors providing integrated systems.
The geopolitical consequences could be severe if technology access becomes subject to more restrictive international conditions. Countries may have to choose between competing ecosystems or finance parallel capabilities to preserve strategic flexibility.
This pathway would be supported by evidence of escalating migration costs, incompatible implementations, persistent vendor concentration and the inability of standardisation processes to create usable interoperability beyond the basic communications interfaces.
Scenario comparison, 2027–2031
| Dimension | Mainstream adoption | Selective deployment | Fragmented ecosystems |
|---|---|---|---|
| Commercial architecture | Broad use of accelerated network computing | Hybrid deployment according to local demand | Multiple partially incompatible computing platforms |
| Principal investment driver | System-wide economic benefits | Location-specific value | Supplier and national ecosystem decisions |
| Operator negotiating power | Depends on practical supplier alternatives | Preserved through heterogeneous architectures | Potentially weakened by platform dependence |
| European industrial opportunity | Major market for interoperable radio and software | Strong specialised industrial opportunities | Higher costs and difficult integration |
| Semiconductor implications | Expanded telecommunications market for accelerators | Concentrated demand at selected facilities | Competing technology stacks and duplicated development |
| Cybersecurity challenge | Large-scale shared-compute assurance | Mixed-architecture operational governance | Complex supplier and software dependencies |
| Public-interest challenge | Preventing systemic failures | Avoiding geographical exclusion | Preserving interoperability and continuity |
| Main evidence needed | Audited national-scale commercial results | Profitable site-level deployments | Supplier portability and standards-conformance outcomes |
No numerical probabilities are assigned because the public record does not provide an adequate empirical base rate or reproducible forecasting model for the commercial adoption of AI-RAN through 2031.
Early-warning indicators: identifying the direction of the market before large-scale commitments become irreversible
Governments and operators need indicators capable of distinguishing substantive progress from promotional activity. Announced partnerships are useful evidence of industrial interest, but they are weaker indicators of commercial maturity than equipment acceptance, operational measurements and sustainable revenue.
The first indicator is the progression from demonstrations to independently evaluated production deployments. Operators should publish or make available to relevant authorities comparable measurements of performance, availability and recovery under realistic traffic conditions. The second concerns commercial economics, including capital expenditure, energy consumption, maintenance, accelerator utilisation and realised income from AI services. The third concerns interoperability, especially the ability to move between computing platforms without unacceptable cost or degradation.
A fourth indicator is the development of international specifications addressing relevant network and AI interfaces. The ITU’s IMT-2030 evaluation programme will provide important evidence concerning the evaluation of future radio technologies, while 3GPP work will be consequential for technical specifications implemented in commercial systems.
A fifth indicator concerns government policy and the allocation of public resources. Funding announcements should be followed through to contracted projects, completed research, technical demonstrations and commercial deployment where applicable. A large budget can support technological progress, but it is not itself evidence that the resulting infrastructure is commercially competitive.
The sixth indicator is industrial concentration. If the number of economically viable computing platforms decreases or if operators cannot substitute critical suppliers, technological dependence may increase even while apparent innovation accelerates.
Strategic monitoring dashboard
| Indicator | 2026 baseline | Positive signpost, 2027–2031 | Warning signpost | Principal evidence source |
|---|---|---|---|---|
| Commercial operating maturity | Bellevue commercial-network call; European trial activity | Multi-site production deployments with sustained measurements | Persistent reliance on isolated demonstrations | Operator acceptance and performance reports |
| Shared-compute performance | Concurrent workloads demonstrated in selected trials | Stable radio performance under varying AI demand | Deadline failures or service degradation | Independent technical assessments |
| Total cost of ownership | No sufficiently comparable public industry-wide dataset | Audited advantage against equivalent alternatives | Cost overruns or weak utilisation | Operator procurement and financial disclosures |
| Spectrum productivity | Defined laboratory improvements for selected techniques | Reproducible field gains under matched conditions | Inconsistent performance outside test environments | Operator and equipment tests |
| Accelerator portability | Multiple hardware environments under development | Demonstrated migration with manageable cost | Proprietary dependencies preventing substitution | Interoperability testing |
| Commercial edge revenue | Emerging application and service development | Contracted, recurring and economically meaningful services | Persistent speculative demand | Operator segment disclosures |
| Cyber resilience | Existing virtualisation and AI security frameworks | Independent assurance and tested recovery | Cross-workload incidents and cascading outages | Security authorities and operators |
| International standardisation | IMT-2030 draft evaluation requirements and guidelines | Stable standards and interoperable implementation | Persistent fragmentation | ITU and 3GPP records |
| European industrial capacity | Research programmes and strong radio engineering base | Competitive products, intellectual property and deployment | Research without industrial scale | European Commission and company disclosures |
| Energy sustainability | System-wide AI-RAN comparison remains incomplete | Transparent energy and lifecycle results | Rising consumption without proportional service value | Operators and energy authorities |
Government policy option I — Establish a common technical assurance framework for critical AI-native networks
The first policy option is to create a common set of technical assurance requirements for AI-native infrastructure used in essential telecommunications services. The framework should cover workload isolation, software integrity, model management, resource reservation, recovery procedures, privileged access and relevant supplier dependencies. It should distinguish ordinary commercial edge applications from functions whose failure could disrupt public communications.
Within the European Union, the Commission, national telecommunications regulators and competent cybersecurity authorities could develop coordinated expectations within their respective mandates. ENISA could contribute technical guidance and risk analysis, while operators would remain responsible for implementing and demonstrating appropriate controls. In the United Kingdom, Ofcom and relevant national cybersecurity institutions would operate within the corresponding domestic framework.
The expected effect would be greater clarity for procurement and supervision. Suppliers would understand the evidence required to demonstrate suitable protection, while operators could compare implementations against common criteria.
The principal implementation burden would involve independent testing, documentation and the development of specialised assessment capabilities. These costs may slow early adoption, but they would reduce the risk of deploying architectures whose failure modes are poorly understood.
The principal downside is the possibility that excessively prescriptive requirements favour established suppliers or discourage alternative designs. Requirements should therefore concentrate on verifiable outcomes rather than mandating one hardware or software architecture.
Government policy option II — Make interoperability and practical supplier substitution central procurement requirements
A second option is to establish procurement principles requiring operators and publicly supported projects to demonstrate the practical substitutability of critical components. The objective is not to prohibit proprietary technology but to prevent essential infrastructure from becoming unnecessarily dependent on one supplier.
The relevant authorities include public procurement bodies, communications regulators where legally competent, competition authorities and organisations administering research or infrastructure support.
The expected effect would be stronger negotiating power for operators and greater resilience against supply disruptions. The implementation burden would include migration testing, technical documentation and contractual provisions protecting access to essential software and operational information.
The principal risk is that strict portability requirements could reduce the performance benefits of specialised optimisation. Procurement should therefore balance portability against measurable advantages rather than treating uniform software execution as an absolute requirement.
Government policy option III — Concentrate public financial support on measurable public benefits
The third option concerns the allocation of public resources. Governments should distinguish between financing research, supporting industrial development and subsidising commercial deployment. Each requires different criteria.
Research funding should support technical advances, standards participation and the development of useful intellectual property. Industrial support should address identifiable market failures or strategic capabilities. Deployment subsidies should be reserved for clearly defined public-interest objectives that the market is unlikely to deliver independently.
The European SNS JU provides an existing institutional model for collaborative research funding. National infrastructure programmes could incorporate comparable requirements for verifiable outputs, but they should not automatically finance large-scale accelerator procurement without operational and economic evidence.
The expected effect would be better capital allocation and a reduced risk of creating expensive infrastructure without sufficient demand. The principal implementation challenge would be defining measurable outcomes and coordinating multiple public authorities.
A potential downside is slower deployment in a highly competitive international market. However, speed should not be pursued at the expense of financially sustainable infrastructure.
Government policy option IV — Coordinate spectrum planning with standards and investment cycles
Spectrum policy should support experimentation and innovation while preserving efficient use of existing frequencies. National regulators should monitor the development of international standards and avoid premature decisions based on commercial projections that have not been substantiated.
The responsible authorities would include national spectrum administrations, relevant regional coordination mechanisms and international bodies within their established mandates.
The expected effect would be greater regulatory certainty and improved opportunities for internationally compatible equipment. Implementation would require technical studies, consultation with existing users and coordination across borders.
The principal trade-off concerns the interests of established services and potential future uses. Allocating spectrum for new applications can impose costs on incumbent users, while excessive delay may constrain experimentation.
An effective approach would distinguish temporary experimental authorisations from long-term commercial allocation decisions.
Government policy option V — Develop national capabilities in computing, radio engineering and operational security
A fifth option is to strengthen the human and industrial capabilities needed to operate intelligent telecommunications systems. Governments can support university research, technical training, interoperability laboratories and cooperation between operators, semiconductor companies, equipment manufacturers and industrial customers.
The expected effect would be greater national ability to evaluate, integrate and maintain advanced infrastructure rather than relying exclusively on supplier assurances.
The implementation burden would involve multi-year funding and coordination across education, industry and public institutions. The principal limitation is that training alone cannot create a globally competitive semiconductor or software ecosystem. It must be linked to credible industrial opportunities.
The strongest programmes would develop practical knowledge relevant to multiple computing and telecommunications architectures, reducing dependence on a single technological trajectory.
Government policy option VI — Protect essential services against common infrastructure failure
The final option is to require critical deployments to demonstrate that essential communications can survive credible failures affecting shared computing, transport, power or management systems. The objective is not to eliminate every possible outage, but to prevent an efficiency-driven architecture from creating avoidable concentrations of risk.
Operators and competent national authorities should define service-continuity requirements appropriate to the criticality of the infrastructure. These should include recovery exercises, independent fault domains and procedures for isolating compromised or malfunctioning AI applications.
The expected benefit would be greater national resilience and reduced exposure to failures affecting several services simultaneously. The implementation cost may include redundant capacity, additional infrastructure and more demanding operational procedures.
The principal economic trade-off is clear: the strongest resilience arrangements may reduce the hardware-utilisation gains that make shared computing commercially attractive. Governments and operators must determine the acceptable balance according to the essential services at stake.
Policy option comparison
| Policy option | Principal authority | Expected effect | Implementation burden | Time to meaningful effect | Main downside | Reversibility |
|---|---|---|---|---|---|---|
| Critical infrastructure assurance | Regulators, cybersecurity authorities, operators | Stronger technical confidence | Testing, documentation and supervision | Short to medium term for initial rules; longer for mature certification | Compliance cost and possible barriers to entry | Adjustable as technology matures |
| Supplier portability | Procurement bodies and operators | Lower dependence and improved bargaining power | Integration and migration testing | Medium term | Performance compromises or additional costs | High before procurement; lower after deployment |
| Targeted public investment | Governments and funding institutions | Better allocation of research and deployment resources | Project evaluation and oversight | Multi-year | Slow implementation or weak project selection | Depends on contract and investment stage |
| Coordinated spectrum policy | National spectrum authorities and international bodies | Predictability and compatibility | Technical studies and negotiations | Multi-year | Conflicts with existing spectrum users | Limited after long-term rights are granted |
| National technical capability | Education, research and industrial authorities | Improved skills and integration capacity | Sustained funding and institutional coordination | Medium to long term | Benefits may not translate into industrial competitiveness | High for programme design; limited for completed expenditure |
| Infrastructure resilience | Operators and competent security authorities | Improved continuity and fault containment | Redundancy and operational testing | Short to medium term for existing sites; longer for new architecture | Higher capital and operating cost | Architecture-dependent |
Final geopolitical assessment — The architecture of future networks will determine the distribution of digital power
The transition towards AI-native telecommunications is significant because it changes the industrial and institutional conditions under which communications infrastructure is created and operated. The potential integration of radio processing, accelerated computing and distributed intelligence introduces new sources of value but also new forms of dependence. The suppliers that control computing architectures, software ecosystems and critical components may gain influence within a sector historically organised around spectrum licences, radio equipment and telecommunications services.
The international distribution of these capabilities is uneven. The United States possesses major strengths in accelerated computing and software. China combines extensive telecommunications infrastructure with coordinated industrial policy and large-scale research programmes. Japan contributes specialised communications, optical and electronics capabilities. South Korea possesses important semiconductor and device-manufacturing strengths. Europe retains globally significant radio engineering, network operators and regulatory institutions but faces challenges in financing investment and reducing dependence on external computing platforms.
These differences will shape the emerging telecommunications order, but they do not predetermine one country’s dominance. A future 6G network will continue to depend on multiple complementary technologies, many of which are produced through international supply chains. The central geopolitical question is whether those supply chains remain commercially accessible and technically interoperable or become instruments of strategic exclusion and technological fragmentation.
For Europe, sovereignty should be understood as the ability to make independent, informed and operationally effective decisions about essential infrastructure. This does not require the domestic production of every component. It requires control over critical functions, dependable access to technology, adequate security and the capacity to replace suppliers where necessary.
Italy, France, Germany and the United Kingdom will contribute through different national strengths. Italy can connect advanced networking with industrial demand and infrastructure modernisation. France possesses extensive fibre infrastructure and important telecommunications capabilities but must address financial pressure on operators. Germany can use its manufacturing base to validate demanding applications and influence system requirements. The United Kingdom can support experimentation and commercial software development while preserving national communications resilience.
The next five years will determine whether these complementary strengths produce an internationally competitive European ecosystem or remain fragmented across national markets and disconnected technology programmes.
The most important uncertainty concerns the economics of shared computing. If accelerated radio systems deliver sustained performance advantages and commercially valuable computing services, AI-RAN could become a major component of future network architecture. If the benefits remain concentrated in particular environments, selective adoption may provide the stronger investment model. If proprietary dependencies and geopolitical restrictions prevent effective interoperability, the transition could increase costs and strategic vulnerability even while technological capabilities improve.
The appropriate policy response is neither unconditional acceleration nor resistance to technological change. It is the establishment of measurable requirements for performance, cost, resilience, security and practical technological control.
The international standards process offers a crucial opportunity to preserve compatibility. The ITU’s IMT-2030 programme is developing the evaluation framework for future radio systems, while 3GPP and other technical organisations continue work on the architectures and specifications necessary for commercial implementation. These processes can reduce fragmentation, but they cannot substitute for competitive industrial capabilities or credible infrastructure investment.
The strategic significance of October 2026 is therefore not that a completed 6G system has emerged. It is that one possible architecture for integrating telecommunications and accelerated computing has crossed an important operational threshold, while governments and companies are beginning to organise research, financing and industrial policy around related technologies.
By 2031, the most successful countries and companies may not be those that install the largest number of AI accelerators or announce the greatest number of experimental partnerships. They will be those capable of combining commercially sustainable infrastructure with internationally relevant intellectual property, secure operational control, adaptable standards and services that deliver measurable economic and public value.
The final judgment of Pillar III is that the future balance of telecommunications power will depend increasingly on control over the relationship between connectivity, computation and intelligence. That relationship could strengthen industrial productivity and national resilience, but it could also deepen technological concentration if interoperability, supplier substitution and public accountability are neglected.
The strategic priority for governments is to preserve freedom of technological choice while investing in capabilities that remain valuable across alternative futures. For operators, it is to demand evidence of profitability and reliability before accepting irreversible platform dependencies. For European industry, it is to ensure that excellence in radio engineering translates into competitive participation across the wider intelligent infrastructure ecosystem.
The development of 6G will not eliminate the importance of spectrum, radio engineering or physical communications networks. It will place them within a more complex system in which semiconductor supply chains, AI software, electricity infrastructure, data governance and geopolitical relationships influence the delivery of essential services.
The central strategic choice for 2027–2031 is whether that complexity becomes a source of resilience and economic opportunity or a new structure of concentrated technological dependence.