



Strategic scenario assessment | Global capital markets, American hyperscalers, European industrial competitiveness and energy infrastructure
Scope: This assessment examines the financial, industrial and geopolitical consequences of a hypothetical 18-month delay in investment returns on the $725–760 billion AI infrastructure expenditure envelope attributed to Microsoft, Amazon, Alphabet and Meta for 2026. It evaluates the transmission mechanisms through the early 2030s, with particular attention to the United States, European Union, Italy, France, Germany and United Kingdom.
Executive Summary — Bottom Line Up Front
The central risk in the AI infrastructure investment cycle is not necessarily that artificial intelligence fails commercially, but that the financial maturity of capital commitments precedes the economic maturity of the assets they finance.
Under the stipulated 18-month return delay, capital expenditure continues absorbing liquidity and generating future operating obligations while the associated revenue, utilisation and operating leverage develop more slowly. Earnings per share could decline despite sustained revenue growth, raising price-to-earnings ratios even without any increase in share prices. If investors initially preserve an AI-related valuation premium, multiple expansion and declining reported profitability could coexist, making equity valuations increasingly dependent on deferred earnings recovery.
The subsequent market response would depend on whether the delay is interpreted as temporary underutilisation or evidence that the expected return on invested capital has permanently deteriorated. The former could favour the largest infrastructure owners; the latter could force selective project deferrals, slower capacity additions and asset impairments.
Electricity availability changes this financial calculation. The approximately 2,600 GW US interconnection backlog cited in the scenario represents a historical peak, not the current reported queue. Lawrence Berkeley National Laboratory’s latest published series shows that the generation-and-storage queue has subsequently contracted. It must also be distinguished from large-load connection requests. The stipulated five-to-eight-year connection horizon is therefore a scenario stress assumption, rather than a demonstrated universal US waiting period. Nevertheless, verified grid constraints make the underlying transmission mechanism credible. Queued Up: Characteristics of Power Plants Seeking Transmission Interconnection — Lawrence Berkeley National Laboratory — 2026
The strategic consequence is potentially paradoxical: an investment cycle that initially compresses hyperscaler returns could ultimately reinforce their market concentration, provided competitors face more severe financing, electricity-access and execution constraints.
For Europe, the exposure is simultaneously financial, industrial and geopolitical. Chinese manufacturing overcapacity may reduce equipment acquisition costs but also undermine European producers and increase import dependence in critical grid supply chains. Italy’s industrial position depends especially on whether cheaper equipment can accelerate electrification without weakening domestic capabilities in transformers, switchgear, power cables and electrical engineering.
The $760 Billion AI Infrastructure Trap: When Electricity, Not Technology, Determines Global Economic Power
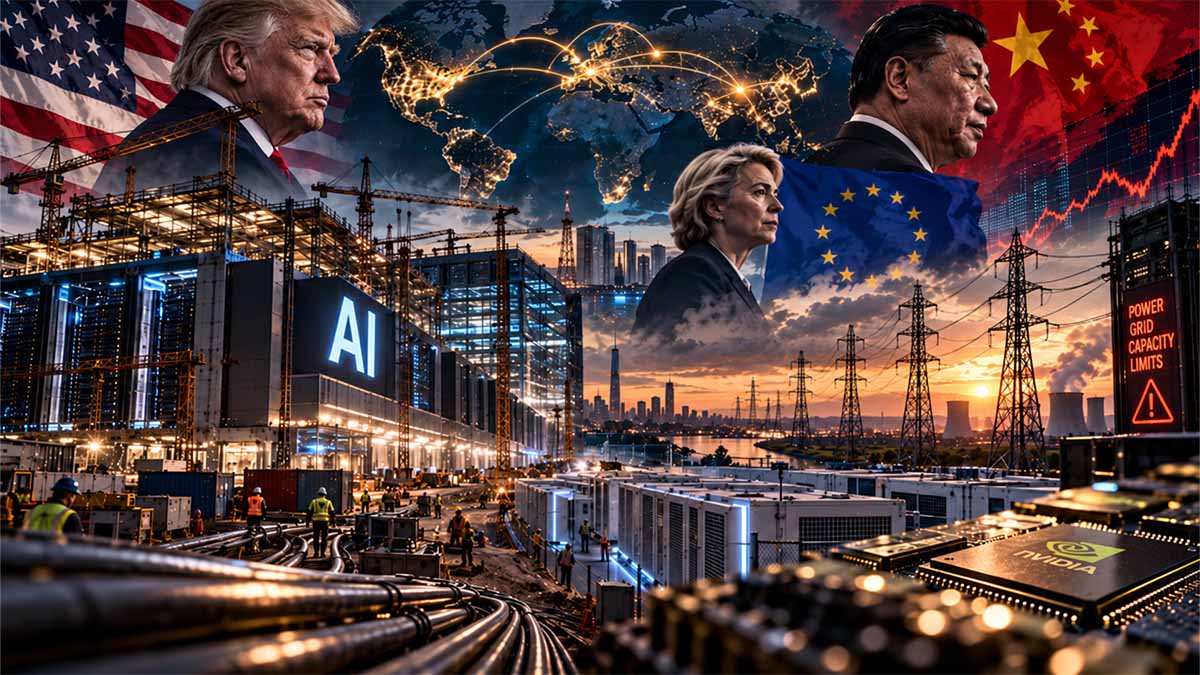
The investment race between Microsoft, Amazon, Alphabet and Meta is exposing a contradiction at the centre of the artificial intelligence economy: companies can finance computing infrastructure faster than electricity systems can make it productive. The $725–760 billion aggregate investment envelope examined for 2026, combined with a hypothetical 18-month delay in expected returns, raises a question that extends well beyond technology valuations. Who ultimately absorbs the cost of capital committed to facilities that cannot generate their anticipated returns on schedule? The consequences reach corporate earnings, electricity networks, industrial manufacturing and international trade. For Europe, and particularly Italy, the danger is that growing demand for AI infrastructure accelerates grid expenditure and equipment imports without delivering a comparable expansion of domestic industrial capacity. The companies controlling finance and reliable electricity connections may emerge stronger even if the initial investment cycle disappoints shareholders.
The $760 Billion Investment Race Conceals Four Different Financial Exposures
The first mistake in assessing the AI investment cycle is to treat the $725–760 billion attributed to the four hyperscalers as a homogeneous expenditure programme. The figure defines the scenario’s investment perimeter, not a reconciled corporate accounting total. Microsoft, Amazon, Alphabet and Meta finance different combinations of buildings, computing equipment, electricity infrastructure and long-term contractual commitments. Their financial statements also distinguish cash expenditure from finance leases, assets under construction and future obligations. These differences determine when investment absorbs liquidity, when costs enter reported earnings and how much management can realistically reduce expenditure if commercial returns disappoint.
Microsoft’s fiscal fourth quarter ended 30 June 2026 illustrates the distinction. The company reported approximately $41 billion in capital expenditure, including $35.8 billion in cash payments for property, plant and equipment and $5.6 billion in finance leases. Approximately two-thirds of the expenditure concerned shorter-lived assets, principally computing equipment. Management also revised its calendar-year 2026 capital expenditure expectation to approximately $175 billion, partly reflecting changes in lease classification. The significance is not merely the amount invested, but the different economic lives of the underlying assets: a data-centre building may remain productive through several equipment generations, while computing hardware faces a much shorter technological replacement cycle.
Amazon expected approximately $200 billion in capital expenditure during 2026, covering the group rather than exclusively AI infrastructure. By June, its trailing-twelve-month operating cash flow had reached $161.4 billion, while net purchases of property and equipment approached $169 billion, leaving reported free cash flow at negative $7.6 billion. Strong operating cash generation was therefore already coexisting with substantial investment-driven pressure on residual liquidity. Meta disclosed a $130–145 billion capital expenditure outlook and, more significantly, $278.99 billion of lease obligations that had not yet commenced as of 30 June 2026, followed by approximately $68 billion of additional data-centre lease commitments entered into during July. These obligations are not equivalent to immediate expenditure, but they demonstrate how future financial commitments can accumulate before infrastructure becomes operational.
Alphabet’s second-quarter accounts reveal a further dimension. Purchases of property and equipment reached approximately $44.9 billion, compared with $22.4 billion a year earlier, while the company reported substantial equity-related and debt-financing transactions. Its infrastructure expansion was therefore accompanied by changes in the financing structure supporting corporate investment. Across the four groups, the fundamental exposure is not simply the possibility that AI demand grows more slowly than expected. It is that capital commitments, replacement requirements and financing obligations develop on schedules that commercial demand cannot necessarily match.
Eighteen Months Can Separate an Earnings Disappointment From a Valuation Crisis
The hypothetical 18-month return delay becomes dangerous through the interaction between depreciation, operating costs and revenue recognition. Capital expenditure does not automatically reduce earnings when cash is spent: qualifying assets are capitalised, and depreciation generally begins when they become available for their intended use. Borrowing costs associated with qualifying construction may also be capitalised. The financial pressure can consequently accumulate before becoming fully visible in the income statement, while facilities already placed in service may begin generating depreciation before their commercial utilisation reaches the level originally anticipated.
The corporate evidence does not establish that this earnings trap has already produced an industry-wide profit collapse. Microsoft’s fiscal fourth-quarter 2026 revenue and operating income both increased 18%, while Alphabet reported second-quarter consolidated revenue growth of 24% and Google Cloud growth of 82%. Yet Alphabet’s depreciation of property and equipment rose to approximately $7.10 billion, from $5.00 billion in the corresponding quarter of 2025. The contrast captures the problem: strong revenue growth can coexist with a rising fixed-cost burden, and consolidated profitability may obscure the return generated by the most recent infrastructure investments.
The valuation consequences depend on how investors interpret the delay. If earnings per share decline while share prices remain stable, the price-to-earnings ratio rises mechanically. If investors continue paying a premium for anticipated AI earnings, the multiple can expand further even as current profitability weakens. Conversely, if the delay is interpreted as evidence that the expected return on invested capital has permanently deteriorated, investors can reduce both earnings expectations and the valuation multiple. What initially appears as temporary margin compression can then become a much more substantial equity-market adjustment.
Alphabet’s second-quarter 2026 results also demonstrate why headline earnings require careful interpretation. The company reported approximately $98 billion in net other-income gains, primarily associated with equity securities. Such gains can materially affect reported earnings without measuring the profitability of the infrastructure programme. Microsoft, meanwhile, reported approximately $678 billion in commercial remaining performance obligations, a substantial measure of contracted business that cannot be treated as revenue already recognised or as guaranteed operating profit. The decisive question is not the size of contractual demand, but when that demand becomes revenue and at what margin the required infrastructure can serve it.
The Electricity Grid Has Become the Hard Limit on Computing Expansion
The physical constraints underlying the investment cycle are more severe than a conventional technology-sector supply problem. The International Energy Agency estimated global data-centre electricity consumption at 415 terawatt-hours in 2024, increasing to approximately 485 TWh in 2025. Its 2026 assessment projected consumption of approximately 950 TWh by 2030. Demand is expanding within electricity systems already required to accommodate industrial electrification, renewable generation and network modernisation. The IEA also warned that approximately 20% of planned data-centre projects could face delays unless electricity infrastructure constraints were addressed, while new transmission lines in advanced economies can require four to eight years to develop.
The American interconnection figures reveal the scale of the problem, provided they are interpreted correctly. The often-cited 2,600 gigawatts represents the historical peak of the United States generation-and-storage interconnection queue at the end of 2023, not current data-centre demand. Lawrence Berkeley National Laboratory reported approximately 2,061 GW still in the active queue at the end of 2025, including 1,312 GW of proposed generation and 749 GW of storage across approximately 8,200 projects. Of that total, 549 GW had draft or executed interconnection agreements but had not reached commercial operation. These are primarily supply-side connection figures, not a measure of large electricity consumers awaiting service; nevertheless, they establish the duration and complexity of bringing new electricity capacity into operation.
The interaction with AI investment is consequential. If a computing project entering the relevant connection process in 2026 encounters a five-to-eight-year development horizon, commercial energisation could extend into 2031–2034. This is a stress-case implication, not a forecast for every hyperscaler facility. But it identifies a risk that conventional technology valuations can underestimate: equipment may be financed, buildings constructed and contractual obligations incurred long before a facility can operate at its intended capacity. Assets still under construction may not yet be depreciating, but the invested capital remains exposed to financing costs, delayed utilisation and technological obsolescence.
Electricity access therefore becomes a competitive asset in its own right. A company controlling an operational facility with reliable power may possess an advantage over a rival capable of buying equivalent processors but unable to energise them. The scarcity is not necessarily electricity generation at national level; it is dependable electricity delivered to a specific location, through suitable networks, within a commercially acceptable timetable.
Europe’s Industrial Contradiction Begins With the Transformer
For Europe, the transformation of AI into heavy industry creates a second dilemma. Additional computing capacity requires transformers, electrical steel, switchgear, cables, cooling equipment and specialised engineering. Lower-priced imports can reduce infrastructure procurement costs, but sustained substitution may weaken the European manufacturers required to maintain and expand those same electricity systems.
The contradiction is already visible in the European Commission’s treatment of grain-oriented electrical steel, a critical input for power transformers. On 27 March 2026, the Commission opened a safeguard investigation into imports of specified electrical-steel products and associated cores. Imports of the electrical-steel products concerned had increased from 91,362 tonnes in 2021 to 191,056 tonnes during July 2024–June 2025, approximately 109%. Imports of related laminations and cores rose from 33,163 to 60,334 tonnes, approximately 82%. The Commission identified import pressure associated with expanding external manufacturing capacity and global overcapacity, particularly involving China.
On 18 September 2026, Brussels introduced provisional safeguards involving tariff-rate quotas and price thresholds. The intervention illustrates the difficulty of protecting European industrial capabilities without raising costs for downstream transformer manufacturers. Electrical steel is a strategic industrial input, but companies assembling finished transformers also require competitively priced materials. Protecting one production stage can therefore alter the economics of another. The documented trade pressure concerns specific electrical-steel products and transformer-core inputs; it does not establish equivalent Chinese overcapacity across every category of transformers, switchgear or cables.
Italy sits directly inside this contradiction. Terna’s 2025–2034 Network Development Plan envisages more than €23 billion in transmission investment, while data-centre connection requests reached approximately 30 GW at the end of 2024 and 39.62 GW by 28 February 2025. The requests were concentrated predominantly in northern Italy, particularly Lombardy, where computing investment overlaps with established industrial electricity demand. These figures represent applications, not installed operating capacity. Their importance lies in the additional network planning, equipment procurement and investment decisions they may generate.
The consequence for Italian manufacturing depends on what is purchased, from whom and under which technical conditions. Cheaper imported components can improve the competitiveness of domestic transformer and equipment producers, while cheaper imported finished products may displace their output. Network reinforcement can support industry and computing activity simultaneously, but speculative connection reservations may absorb planning resources that commercially executable manufacturing projects also require. Italy’s industrial interest is therefore not simply to attract data centres. It is to ensure that electricity infrastructure investment strengthens domestic production, engineering and maintenance capabilities rather than creating a larger import-dependent capital stock.
Connection Rights Could Reinforce the Hyperscaler Oligopoly
The emerging competitive advantage of the four hyperscalers is not confined to computing technology or financing capacity. It increasingly includes access to suitable electricity connections, qualified equipment suppliers and locations where infrastructure can be brought into service without prolonged reinforcement. This creates the possibility that a disappointing investment cycle ultimately strengthens the companies capable of continuing construction while less financially resilient competitors postpone or abandon projects.
The United Kingdom provides direct evidence of how electricity allocation can influence market structure. On 29 July 2026, Ofgem reported that electricity-demand connection applications had increased from 41 GW to 125 GW in less than a year, with data-centre projects accounting for at least 80 GW of the increase. The regulator proposed commitment fees and development milestones intended to distinguish commercially credible projects from speculative applications. The measures remained proposals at the reference date, but their competitive implications are clear: requirements for financing, equipment procurement and demonstrable project progress can prevent capacity hoarding while also favouring established operators if imposed disproportionately on smaller entrants.
France and Germany face different versions of the same constraint. France can seek to convert the characteristics of its electricity system into an advantage for computing infrastructure, but available national generation does not guarantee a timely connection at every proposed site. Germany must accommodate additional digital demand within an electricity system serving a major manufacturing economy; its framework for flexible network connections offers a possible means of improving utilisation where operational requirements permit. Neither country can evaluate computing infrastructure independently of the industrial electricity users with which it shares network capacity.
The European Commission’s Strategic Roadmap for Digitalisation and AI in the Energy Sector, adopted on 3 June 2026, acknowledged that data centres already represented approximately 2.5% of EU electricity consumption and envisaged installed data-centre capacity increasing from roughly 12 GW in 2025 to 28 GW by 2030. Its proposed coordination among public authorities, electricity operators and data-centre developers reflects a shift in regulatory priorities: commercial investment announcements are no longer sufficient evidence that the electricity system can deliver the requested capacity.
Under the 18-month delay scenario, two outcomes remain possible. Markets may force selective capitulation through project deferrals, slower additions and, where accounting conditions require them, asset impairments. Alternatively, companies controlling already productive infrastructure may acquire greater competitive advantages as weaker developers lose access to finance or viable electricity connections. The outcomes can occur sequentially. But an oligopoly premium would be economically justified only if concentrated capacity generated durable operating returns. Scarcity that raises infrastructure costs without supporting profitable demand merely makes the investment problem more expensive.
The Next 24 Months Will Determine Who Absorbs the Industrial Cost
Between October 2026 and October 2028, the critical evidence will come from project completion rather than announcements. Investors will need to distinguish cash capital expenditure from lease commitments, assets under construction from productive capacity, and contracted demand from realised operating profit. Network operators will need to identify applications backed by credible development programmes, while governments will have to decide how project-specific reinforcement costs are allocated and whether connection rules preserve access for viable industrial users.
The European cost of inaction would not be limited to delayed data centres. Italy could carry additional grid-planning and procurement burdens while losing manufacturing investment to connection congestion or imported-equipment competition. France could attract electricity-intensive computing projects without securing a comparable share of the technological and industrial value created. Germany could face additional competition for electricity infrastructure while its equipment manufacturers absorb international price pressure. The United Kingdom could allow scarce connection rights to favour financially powerful incumbents unless its proposed reforms distinguish credible development from speculative reservation without excluding viable entrants.
For Microsoft, Amazon, Alphabet and Meta, the decisive measure will be the return generated by productive infrastructure rather than the amount invested. For European governments, it will be the share of electricity-network and industrial expenditure converted into durable domestic capability. The 2026 investment cycle may eventually reward the hyperscalers capable of securing electricity and sustaining construction through delayed returns. The costs of an unsuccessful adjustment, however, will fall on shareholders financing unproductive assets, electricity users exposed to inefficient network investment and manufacturers whose production capacity is displaced before reliable alternatives have been secured.
Navigational Index
PILLAR I — THE FINANCIAL ARCHITECTURE OF THE AI INVESTMENT CYCLE
- Chapter 1. The $725–760 Billion Capital Commitment: Financial Structure and Exposure
- Chapter 2. The 18-Month Earnings Trap: Depreciation, Financing Costs, Revenue Recognition and Operating Leverage
- Chapter 3. From Valuation Compression to Capital Capitulation: Market Discipline and Investment Deferrals
PILLAR II — ELECTRICITY, PHYSICAL INFRASTRUCTURE AND INDUSTRIAL POWER
- Chapter 4. The Interconnection Constraint: Grid Queues, Energisation and Stranded Development Capital
- Chapter 5. From Software Economics to Heavy Industry: Power Equipment, Construction, Cooling and Industrial Dependencies
- Chapter 6. Chinese Industrial Overcapacity and the European Equipment Market: Price Transmission, Import Substitution and Strategic Exposure
PILLAR III — GEOPOLITICAL CONSEQUENCES AND COMPETING MARKET OUTCOMES
- Chapter 7. European Industrial Exposure: Italy, France, Germany, the United Kingdom and EU Coordination
- Chapter 8. Partial Capitulation versus Oligopoly Reinforcement: Conditions, Financial Indicators and Industrial Consequences
- Chapter 9. Strategic Decisions Through the Early 2030s: Capital Allocation, Grid Prioritisation, Supply-Chain Resilience and Market Concentration
Master Abstract
The divergence between investment expenditure and economic returns
The hypothetical 18-month postponement of returns on the 2026 AI infrastructure spending envelope would expose a structural vulnerability in the transition from digital-service economics to infrastructure-intensive production. Microsoft, Amazon, Alphabet and Meta would be financing increasingly complex systems of computing hardware, data centres, power connections, land, cooling equipment and associated electrical infrastructure whose productive value depends on their timely integration into commercially usable capacity. The balance-sheet expansion would therefore precede the full development of the associated income streams.
The transmission into financial statements would not occur through a simple equivalence between capital expenditure and operating expenses. Cash-funded capital expenditure reduces liquidity, while qualifying assets are generally capitalised on the balance sheet. Depreciation ordinarily begins when assets are available for their intended use, not simply when they are ordered or paid for. Borrowing costs may be capitalised during qualifying construction periods rather than immediately expensed. The critical exposure is consequently the accumulation of capital committed to projects that cannot yet generate adequate returns, followed by an increase in depreciation, operating expenditure and potentially financing costs as capacity enters service.
Microsoft’s fiscal 2026 disclosures make the economic significance of this distinction apparent: management discussed its infrastructure investment mix, depreciation assumptions, leasing classifications and the influence of AI infrastructure costs on profitability. These are not incidental accounting matters. They determine when the economics of the construction programme become visible in reported earnings and how comparable different measures of capital expenditure actually are. Microsoft Fiscal Year 2026 Fourth Quarter Earnings Conference Call — Microsoft — July 2026
The earnings trap emerges when depreciation, operating expenditure and recognised financing costs increase faster than the incremental operating profit generated by AI capacity. If the share price remains stable while earnings per share fall, the reported price-to-earnings ratio increases mechanically. If investors also bid up the share price in anticipation of future AI revenue, the multiple expands further. This is not evidence that the underlying assets have become more productive. It is evidence that market capitalisation and current profitability have become more dependent on expectations about future utilisation, margins and capital efficiency.
Electricity as a determinant of capital productivity
The binding constraint is increasingly physical rather than computational. The International Energy Agency has identified grid connections, electricity equipment, planning requirements and supply-chain bottlenecks as material restrictions on the expansion of AI-focused data centres. The delivery of transformers, cables and other grid components is therefore inseparable from the delivery of computing capacity. Energy and AI — International Energy Agency — April 2025
An 18-month delay in commercial returns and a five-to-eight-year connection horizon represent different clocks operating on the same capital programme. A data centre ordered and financed during 2026 may encounter construction, permitting or grid-related delays that extend its path to full commercial utilisation into the early 2030s. This does not establish that all associated equipment must depreciate before energisation; it establishes that funds can remain tied to unfinished or commercially unusable capacity while financing commitments, contractual obligations and technological obsolescence risks accumulate.
The distinction is decisive for investment evaluation. A delayed facility may preserve its nominal book value while its economic value deteriorates as technology advances, alternative capacity becomes more efficient or electricity access is secured elsewhere. Conversely, an existing energised facility may command greater strategic value precisely because new competitors cannot reproduce its access to power within a commercially acceptable period. Electricity availability thus changes both sides of the valuation equation: it determines how quickly committed capital produces returns and how difficult successful infrastructure positions are to replicate.
The possible reversal from earnings pressure to oligopoly advantage
The scenario’s competing outcomes are not necessarily mutually exclusive across time. An initial earnings disappointment could force all four hyperscalers to reconsider the pace of capacity construction. If the resulting investment adjustments are limited to projects with weak expected returns, the companies may preserve liquidity and improve the allocation of future expenditure. If, however, financial pressure leads to indiscriminate reductions in productive capacity, the same adjustments could weaken the long-term earnings base on which present equity valuations depend.
The alternative outcome is that balance-sheet capacity and electricity access become durable barriers to entry. In that case, the largest operators could sustain development expenditure while smaller infrastructure providers face higher capital costs, weaker purchasing power and less favourable access to energy infrastructure. The oligopoly premium would re-emerge only if this scarcity translates into pricing power, contract durability or superior capital productivity. Concentration alone is insufficient: competition among the four incumbents could still compress returns, while cheaper computing and improved efficiency could reduce the scarcity value of installed capacity.
The most consequential distinction is therefore between infrastructure scarcity that protects profitable capacity and infrastructure scarcity that merely raises the cost of constructing and operating it.
Europe between lower equipment prices and strategic dependency
The European transmission channel runs through the manufacturing system. Chinese industrial overcapacity, redirected export supply and price competition could reduce the acquisition cost of electrical equipment and accelerate particular grid investments. Yet those same forces could weaken European manufacturing margins, discourage domestic capacity expansion and increase reliance on imported critical components.
This is a concrete policy concern rather than a purely hypothetical geopolitical analogy. The European Commission initiated a safeguard investigation in March 2026 into imports of grain-oriented electrical steel, an essential input for power transformers, identifying import pressure and global overcapacity as material concerns for EU producers. Its July 2026 revision of the import-monitoring mechanism similarly recognised sustained import increases associated with industrial overcapacity as a risk to European industrial production. These records support the existence of a broader industrial-pressure mechanism, although they do not establish that every equipment category in the scenario is currently experiencing Chinese trade diversion. Commission initiates safeguard investigation into imports of grain-oriented electrical steel — European Commission — March 2026
Trade and Economic SecurityCommission upgrades import monitoring mechanism — European Commission — July 2026
Italy faces a particularly consequential industrial choice. A reduction in equipment costs could support grid reinforcement, industrial electrification and data-centre development, but a procurement strategy driven exclusively by upfront prices could weaken the domestic industrial base responsible for electrical components, engineering, installation, servicing and future grid maintenance.
The same issue appears differently in France, Germany and the United Kingdom. France must reconcile computing-infrastructure development with the availability and location of dependable electricity supply. Germany faces the interaction between electricity-intensive manufacturing competitiveness and the additional demands of digital infrastructure. The United Kingdom confronts the allocation of constrained grid-connection capacity among competing projects, with its energy regulator already examining mechanisms to discourage speculative data-centre connection requests.
For the European Union collectively, the strategic problem is not whether imported equipment should be accepted or rejected categorically. It is how to capture short-term cost reductions without transferring long-term control of essential infrastructure supply chains outside European industrial capacity.
Key Evidence and Scenario Assumptions
| Indicator | Value or status | Reference period | Definition and evidentiary standing | Source |
|---|---|---|---|---|
| AI infrastructure investment envelope | $725–760 billion | 2026 | Aggregate scenario input for Microsoft, Amazon, Alphabet and Meta; not independently reconciled across company accounting definitions | User-supplied scenario |
| Return delay | 18 months | Relative to original expected return timing | Hypothetical postponement of economic returns, not a documented consolidated earnings forecast | User-supplied scenario |
| US interconnection backlog | Approximately 2,600 GW | Historical peak | Generation and storage connection queue; not the current queue or a direct measure of large-load requests | Lawrence Berkeley National Laboratory — 2026 |
| Large-load connection horizon | 5–8 years | Scenario development horizon | Stress-case assumption; not demonstrated as a uniform current US waiting time | User-supplied scenario |
| Possible commercial energisation | Early 2030s | Projects initiated in 2026 | Conditional outcome where grid and project-development bottlenecks persist | Scenario inference |
| European electrical equipment trade pressure | Documented in relevant industrial inputs | 2026 | Commission investigation and import monitoring; product-specific diversion still requires verification | European Commission — March 2026 |
| Italian grid investment exposure | Established development programme | 2025–2034 | Transmission expansion and data-centre connection pressures documented by Terna | Terna — Network Development Plan 2025 |
| Market outcomes | Partial capitulation or renewed concentration | Through the early 2030s | Conditional scenarios, without assigned probabilities | Analytical assessment |
Competing Market Pathways
The central scenario produces different outcomes depending on how revenue development, capital costs, electricity access and investor expectations interact. A temporary deterioration in reported earnings does not, by itself, establish the destruction of long-term shareholder value. Equally, continuing infrastructure investment does not demonstrate that the underlying assets will earn adequate returns.
| Pathway | Supporting mechanism | What would weaken it | Observable indicators | Assessment |
|---|---|---|---|---|
| Partial capital capitulation | Rising capital intensity, disappointing utilisation, tighter free cash flow and investor pressure to moderate expenditure | AI revenue and operating cash flow accelerate sufficiently to cover incremental costs | Project deferrals, lower capacity additions, cancelled commitments, impaired assets | Plausible if return delays persist and financial flexibility contracts |
| Oligopoly reinforcement | Capital strength and secured electricity access become scarce competitive advantages | Strong rivalry, efficiency gains, alternative infrastructure models or weak pricing power | Greater contract concentration, durable margins on energised capacity, competitors unable to finance expansion | Plausible if scarcity protects revenue-generating assets rather than only increasing costs |
| Selective rationalisation followed by concentration | Companies defer weak projects while preserving strategic sites, power rights and high-utilisation facilities | Indiscriminate retrenchment, structural demand weakness or rapidly depreciating technological value | Capex reallocation, retention of strategic energy contracts, rising utilisation of completed facilities | A coherent sequential scenario combining elements of both outcomes |
The third pathway merits particular attention. Capital capitulation and oligopoly reinforcement are not necessarily competing terminal states. The former can become a mechanism producing the latter if reduced investment disproportionately eliminates weaker competitors or low-quality projects while leaving the largest hyperscalers in control of scarce electricity-connected infrastructure.
That outcome would depend on competitive behaviour, capital-market access, contractual arrangements and the practical availability of alternatives. It cannot be inferred from company size alone.
Principal Gaps and Watch Indicators
The decisive evidence is not the aggregate capital-expenditure announcement in isolation, but the relationship between expenditure, asset readiness, commercial utilisation and financial returns.
A rigorous assessment should therefore follow the financial statements of the four hyperscalers to distinguish cash capital expenditure from finance leases, construction commitments and completed depreciable assets. Reported depreciation should be separated from impairment charges, and recognised borrowing costs from interest capitalised during construction. Revenue generated by new infrastructure should, where disclosed, be distinguished from gains in existing cloud, software and advertising businesses.
Physical monitoring must proceed in parallel. An interconnection request does not constitute guaranteed electricity supply, and an executed agreement does not automatically establish a completed facility. Evidence of grid reinforcement, energisation schedules, equipment deliveries and firm power arrangements is essential to understanding whether delays are being resolved or merely shifted into later financial periods.
For European industrial exposure, the relevant monitoring record includes product-level import trends, price movements, European production capacity, delivery times and supplier concentration. These indicators would distinguish beneficial substitution from the displacement of strategically important manufacturing capabilities.
Four developments would materially change the assessment: sustained monetisation that restores operating leverage before the delayed infrastructure programme reaches full utilisation; faster grid access that reduces capital immobilisation; further slippage that raises obsolescence and impairment risks; or evidence that concentrated infrastructure ownership produces durable pricing power rather than continued competitive expenditure.
The resulting strategic judgment is conditional but consequential. AI infrastructure may reinforce the dominance of its largest investors even while temporarily reducing their reported financial returns. The dividing line is whether the physical infrastructure financed today becomes scarce, productive capacity tomorrow—or remains an increasingly expensive claim on future electricity, equipment and demand.
No decision-useful quantitative visualisation is supportable from the verified record without introducing additional assumptions about company-level cash flows, asset commissioning schedules and infrastructure utilisation.
THE $760 BILLION
AI INFRASTRUCTURE TRAP
An institutional scenario assessment of delayed AI investment returns, electricity infrastructure bottlenecks, hyperscaler concentration and the geopolitical redistribution of industrial power.
Microsoft · Amazon · Alphabet · Meta
Combined proposed capital expenditure envelope for the four hyperscalers. Accounting comparability is not independently established.
Return generation falls behind infrastructure investment and associated operating commitments.
Historical generation and storage queue figure. Not equivalent to large-load connection requests.
3D Capital and Infrastructure Stress
The two charts show the supplied scenario endpoints. Their column heights are proportionate within their own panels. They do not represent forecasts or independent company-level measurements.
The Financial Earnings Trap
The financial exposure develops through the timing mismatch between financing infrastructure, placing assets into productive service and generating sufficient operating profit.
Equipment orders, construction spending, leases and infrastructure financing.
Construction assets, property and equipment, liabilities and reduced liquidity.
Energisation, capacity activation or AI monetisation arrives later than expected.
Recognised depreciation and other expenses outpace incremental operating profit.
Earnings per share fall while investors may preserve or raise equity valuations.
Capital expenditure is not automatically an immediate income-statement expense. Depreciation generally begins when an asset is available for its intended use. Qualifying construction borrowing costs may be capitalised. The economic risk can therefore accumulate before the full reported earnings impact.
Two Competing Market Outcomes
The same 18-month return delay can lead either to investment retrenchment or to reinforced market concentration. The determining factor is whether scarce infrastructure ultimately produces adequate returns on invested capital.
SCENARIO A — PARTIAL CAPITULATION
Capital intensity increases faster than monetisation and operating cash flow. Markets demand investment restraint.
SCENARIO B — OLIGOPOLY REINFORCEMENT
Balance-sheet strength and dependable electricity access become barriers to entry, protecting the commercially productive infrastructure base.
Selective capitulation can precede concentration: financially weaker or lower-quality projects are deferred, while the strongest operators preserve productive sites, grid access and capital flexibility.
The Physical Bottleneck
Electricity Connection
Grid access may determine whether completed computing infrastructure can enter service. Connection requests must not be confused with energised power capacity.
Industrial Equipment
Transformers, switchgear, cables, cooling equipment and related systems become critical inputs into AI infrastructure delivery.
Capital Productivity
Delayed commissioning extends capital immobilisation and increases exposure to financial costs and technological obsolescence.
Artificial intelligence is increasingly dependent on the economics of heavy industry: electricity, land, physical equipment, engineering capacity and long-lived infrastructure. Access to computing technology alone is not sufficient for deployment.
Chinese Overcapacity: European Transmission
Excess supply in selected industrial manufacturing categories.
Potential supply shifts towards European equipment markets.
Lower acquisition prices alongside pressure on European producers.
Domestic production competes with imported electrical equipment.
Short-term cost gains may increase longer-term supplier dependence.
Potential Opportunities
Lower equipment costs could facilitate grid reinforcement, infrastructure replacement, electrification and certain data-centre projects. European companies may also benefit from cheaper imported industrial inputs.
Strategic Vulnerabilities
Persistent import-price pressure could weaken domestic electrical-equipment manufacturing, reduce investment incentives and concentrate supply dependence outside Europe.
European Strategic Exposure
ITALY
The central issue is whether lower-cost equipment supports grid modernisation without damaging domestic electrical manufacturing.
Transformers, cable systems, switchgear, industrial engineering and grid investments form the principal exposure channels.
Cost versus industrial resilienceFRANCE
The strategic question concerns the ability to align growing data-centre requirements with electricity supply, network capacity and the location of industrial demand.
Power-to-compute integrationGERMANY
Electricity-intensive manufacturing and digital infrastructure compete for reliable energy access. Imported industrial equipment can reduce costs while intensifying pressure on domestic suppliers.
Industrial margin pressureUNITED KINGDOM
Grid-connection prioritisation, credible project readiness and competition between infrastructure applicants become decisive for data-centre development.
Grid access and project deliveryEUROPEAN UNION — COLLECTIVE EXPOSURE
European coordination must reconcile equipment affordability, grid development, procurement resilience and the preservation of industrial production capacity. Lower import prices alone are not evidence of improved strategic autonomy.
Strategic Risk and Opportunity Matrix
| Domain | Transmission Mechanism | Potential Financial or Industrial Effect | Observable Indicator | Exposure |
|---|---|---|---|---|
| Hyperscaler Earnings | Infrastructure costs precede adequate monetisation. | Reduced earnings growth and potential valuation stress. | Operating profit, depreciation and capital efficiency. | Downside risk |
| Balance-Sheet Capacity | Committed capital remains tied to unfinished or underutilised assets. | Reduced flexibility, with advantage to financially stronger operators. | Cash flow, debt, leases and construction commitments. | Dual effect |
| Electricity Connections | Delayed grid access postpones asset deployment. | Capital immobilisation and slower revenue generation. | Connection agreements and actual energisation. | Execution risk |
| Market Concentration | Power access and financing capacity create barriers to entry. | Potential reinforcement of incumbent market positions. | Utilisation, contractual pricing and competitor entry. | Conditional |
| Chinese Equipment Exports | Potential redirection of excess industrial supply. | Lower prices but possible displacement of EU production. | Product-level trade volumes and prices. | Mixed impact |
| Italian Supply Chains | Import substitution and intensified equipment competition. | Procurement savings alongside domestic margin pressure. | Supplier concentration, domestic output and import penetration. | Industrial trade-off |
| European Energy Systems | Grid investment and electrical-equipment availability interact. | Potential network acceleration or additional dependency. | Equipment deliveries and completed grid upgrades. | Strategic dependency |
Decision-Critical Watch Indicators
Financial
Capital expenditure, depreciation, free cash flow, operating margins, utilisation and asset impairments.
Infrastructure
Grid interconnection progress, firm power availability, construction completion and energisation timing.
Industrial and Trade
European electrical-equipment imports, domestic production, supplier concentration and delivery reliability.
The central bifurcation is between an investment cycle that destroys capital productivity and one that increases the scarcity value of productive infrastructure. These outcomes may occur in sequence rather than as mutually exclusive futures. The decisive variable is not infrastructure expenditure alone, but the ability to convert committed capital and electricity access into durable operating returns.
Evidence and Methodological Notes
Scenario inputs: $725–760 billion aggregate investment envelope; 18-month return delay; five-to-eight-year connection stress horizon. These are stipulated assumptions, not independently verified outcomes. No numerical probabilities are assigned.
Interconnection baseline: Lawrence Berkeley National Laboratory, Queued Up: Characteristics of Power Plants Seeking Transmission Interconnection. The approximately 2,600 GW figure refers to a historical generation-and-storage queue peak rather than current large-load demand. Official research series
Energy infrastructure: International Energy Agency, Energy and AI, April 2025. Official IEA analysis
European industrial trade: European Commission, safeguard investigation into grain-oriented electrical steel imports, March 2026. European Commission record
Italian electricity infrastructure: Terna, 2025 Electricity Transmission Network Development Plan. Official Terna documentation
Interpretation: The financial transmission chains, market scenarios and European industrial exposure assessments are conditional analytical models. The 3D graphic columns visualise only their stated numerical inputs. They do not imply measured company-specific results.
PILLAR I — THE FINANCIAL ARCHITECTURE OF THE AI INVESTMENT CYCLE
Analytical scope: Microsoft, Amazon, Alphabet and Meta; capital expenditure, financing structures, accounting recognition, investment returns, equity valuations and capital-allocation decisions through the early 2030s.
Chapter 1. The $725–760 Billion Capital Commitment: Financial Structure and Exposure
The transformation of the hyperscaler balance sheet into an industrial capital structure
The financial significance of the artificial intelligence investment cycle cannot be understood by treating the infrastructure expenditure announced by Microsoft, Amazon, Alphabet and Meta as an unusually large extension of conventional technology-sector capital spending. The underlying transformation is more fundamental. The four companies are progressively committing financial resources to productive systems whose construction, commissioning, depreciation, financing and commercial utilisation increasingly resemble the economics of capital-intensive industrial enterprises. Their competitive positions remain rooted in software, cloud computing, digital advertising, data and customer relationships, but an expanding proportion of the investment required to sustain those positions is being directed towards physical assets that cannot be activated, relocated, replaced or monetised with the flexibility traditionally associated with software businesses.
The $725–760 billion aggregate 2026 investment envelope stipulated in this assessment illustrates the scale of the possible financial exposure. It must, however, be understood as a scenario assumption rather than an independently reconciled aggregate of four comparable corporate forecasts. The companies report capital expenditure using different definitions, including variations in how they present finance leases, property and equipment purchases, equipment financing and other investment arrangements. Their financial calendars and expenditure categories also differ. Consequently, the aggregate cannot automatically be interpreted as cash spent entirely on artificial intelligence, as a uniform amount of newly installed computing capacity, or as a single measure of assets that will immediately enter depreciation.
This distinction is essential because the investment programme does not produce one homogeneous financial exposure. Spending on computing hardware may begin to generate depreciation over relatively short useful lives, while investment in buildings, electrical infrastructure and site development follows different accounting and operational timelines. Lease commitments can extend beyond the period in which the underlying infrastructure is constructed, while supply agreements and other contractual obligations may constrain future cash flows without appearing immediately as conventional debt. The apparent simplicity of the headline aggregate conceals an assortment of assets, contractual claims, financing structures and economic risks.
The latest corporate disclosures available for this assessment provide a more concrete picture of that complexity. Microsoft reported approximately $41 billion of capital expenditure in its fiscal fourth quarter ended 30 June 2026, of which approximately two-thirds related to shorter-lived assets, principally computing equipment. Management separately identified $5.6 billion of finance leases and $35.8 billion of cash payments for property, plant and equipment, demonstrating why accounting classifications matter when translating investment announcements into liquidity requirements. The company also explained that changes in the estimated useful lives of certain property assets would alter the classification of future data-centre leases and adjust its calendar-year 2026 capital expenditure expectation to approximately $175 billion, without representing an equivalent reduction in the underlying investment programme. Microsoft Fiscal Year 2026 Fourth Quarter Earnings Conference Call — Microsoft — July 2026.
Amazon’s industrial commitment is similarly substantial, although its disclosure encompasses a broader operating system than its cloud business alone. In its February 2026 earnings announcement, Amazon stated that it expected approximately $200 billion in capital expenditures during 2026, covering investment opportunities across the company rather than exclusively AI infrastructure. Its second-quarter results subsequently showed the growing financial significance of infrastructure investment: trailing-twelve-month operating cash flow reached $161.4 billion, while net purchases of property and equipment reached approximately $169 billion, resulting in reported trailing-twelve-month free cash flow of negative $7.6 billion. This combination is analytically more informative than the capital expenditure announcement in isolation, because it shows how substantial operating cash generation can coexist with negative residual cash flow when the investment programme absorbs resources faster than current operations replenish them. Amazon Announces Fourth Quarter Results — Amazon — February 2026 and Amazon Announces Second Quarter Results — Amazon — July 2026.
Meta presents another variation of the same structural transformation. Its second-quarter regulatory filing projected $130–145 billion of capital expenditure during 2026, intended to support both AI development and the company’s established businesses. More consequentially, the filing disclosed approximately $278.99 billion of operating and finance lease obligations that had not yet commenced as of 30 June 2026, associated with data centres, colocation arrangements and network infrastructure. Those obligations were scheduled to commence over subsequent years, while the company also disclosed approximately $68 billion of additional data-centre lease obligations entered into during July 2026, expected to commence in 2027 and 2028. These amounts are not equivalent to immediate capital expenditure or conventional outstanding financial debt. They nevertheless demonstrate how future infrastructure commitments can become extensive before the associated facilities contribute fully to operating results. Meta Platforms Form 10-Q, Quarter Ended 30 June 2026 — US Securities and Exchange Commission — 2026.
Alphabet’s financial statements reveal a particularly important interaction between infrastructure investment and capital-market financing. During the second quarter of 2026, the company reported approximately $44.9 billion of purchases of property and equipment, compared with approximately $22.4 billion during the corresponding quarter of 2025. The company also disclosed approximately $49.6 billion of net proceeds from an equity and mandatory-convertible-preferred financing transaction and approximately $20.3 billion of net proceeds from senior unsecured notes issued during the quarter. These financing transactions are relevant because they demonstrate that the expansion of AI infrastructure can change not only the asset composition of a technology company but also its mix of equity claims, debt obligations and future capital costs. Their existence does not establish financial distress; it does establish that the financing architecture itself deserves examination alongside operational performance. Alphabet Announces Second Quarter 2026 Results — Alphabet, Form 8-K Exhibit 99.1 — July 2026.
The central financial question is therefore not whether four exceptionally large technology companies possess enough resources to announce ambitious investment programmes. It is whether the additional assets and commitments produce incremental operating cash flows sufficient to compensate shareholders and creditors for the capital employed, the time elapsed before commercial utilisation and the possibility that technological or market conditions change before the investment reaches its expected productivity.
The documented financial baseline: four companies, four different capital structures
The financial evidence should not be flattened into an artificial comparison of identical expenditure categories. The most useful approach is to distinguish official corporate guidance from realised expenditure, financing activity, operating cash generation and contractual obligations, preserving the economic meaning of each figure.
| Company | Verified financial indicator | Amount | Period | Interpretation |
|---|---|---|---|---|
| Microsoft | Capital expenditure, including finance leases | $41.0bn | Fiscal Q4 2026 | Quarterly investment measure; includes shorter- and longer-lived assets |
| Microsoft | Cash paid for property, plant and equipment | $35.8bn | Fiscal Q4 2026 | Cash-investment component |
| Microsoft | Finance leases included in reported capex | $5.6bn | Fiscal Q4 2026 | Lease-financed investment component |
| Microsoft | Revised capital expenditure expectation | Approx. $175bn | Calendar 2026 | Management outlook affected by lease-classification changes |
| Amazon | Announced capital expenditure expectation | Approx. $200bn | Calendar 2026 | Company-wide investment guidance |
| Amazon | Operating cash flow, trailing twelve months | $161.4bn | To June 2026 | Cash generated by operating activities |
| Amazon | Net property and equipment purchases, trailing twelve months | Approx. $169.0bn | To June 2026 | Infrastructure and other capital investment after specified offsets |
| Amazon | Free cash flow, trailing twelve months | −$7.6bn | To June 2026 | Reported cash flow after defined capital spending |
| Alphabet | Purchases of property and equipment | $44.9bn | Q2 2026 | Quarterly cash investment |
| Alphabet | Net equity and preferred-stock financing proceeds | $49.6bn | Q2 2026 | Capital raised from equity-related securities |
| Alphabet | Net proceeds from senior unsecured notes | $20.3bn | Q2 2026 | Debt financing raised during the quarter |
| Meta | Capital expenditure outlook | $130–145bn | Calendar 2026 | AI and core-business investment guidance |
| Meta | Capital expenditure including finance-lease principal payments | $31.08bn | Q2 2026 | Quarterly investment and lease-related cash measure |
| Meta | Not-yet-commenced lease obligations | $278.99bn | At 30 June 2026 | Future contractual obligations, not immediate capex |
| Meta | Additional data-centre lease commitments | Approx. $68bn | July 2026 | Subsequently contracted future infrastructure obligations |
Sources: Microsoft FY2026 Q4 Earnings Conference Call — Microsoft — July 2026; Amazon Q2 2026 Results — Amazon — July 2026; Alphabet Q2 2026 Results — Alphabet — July 2026; Meta Q2 2026 Form 10-Q — Meta Platforms — 2026.
These figures establish a common trend towards greater infrastructure intensity, but they do not demonstrate that all four companies are experiencing identical financial pressure. Nor can the table’s different categories be added together to derive a verified industry expenditure total. The investment burden varies according to the source of operating cash flows, the profitability of established businesses, the ownership or lease structure of infrastructure, the timing of construction and the degree to which investments are directed towards internal operations rather than customer-facing capacity.
Microsoft’s investment programme can be evaluated against the recurring revenue generated by its enterprise software, cloud and related activities. Amazon’s programme must be assessed within a group containing cloud infrastructure, retail operations, logistics and advertising, each with distinct capital requirements. Alphabet’s infrastructure expenditure serves both external cloud customers and the computing needs of its established digital businesses, while Meta’s investment proposition relies substantially on the contribution of AI infrastructure to advertising efficiency, user engagement and future products rather than only on the direct sale of computing capacity.
The resulting difference is fundamental: a unit of infrastructure expenditure can support several economically distinct forms of return, and the absence of separately reported AI revenue does not necessarily mean that the investment produces no commercial benefit. Conversely, improvements in consolidated revenue or profitability cannot automatically be attributed to the incremental infrastructure under examination.
Capital deployment, operating cash flow and the loss of financial flexibility
The earliest financial constraint in the 18-month delay scenario is likely to emerge in capital allocation and free cash flow before it becomes fully visible in earnings. A company can report strong operating profit while substantially reducing its available liquidity through expenditure on facilities that will not reach their expected commercial utilisation until a later period. The accounting result and the cash result therefore reflect different phases of the same investment decision.
A simplified financial sequence begins with an infrastructure commitment. The company may then pay suppliers, capitalise assets under construction, recognise qualifying lease arrangements, raise external financing or draw down existing liquidity. During construction, the balance sheet expands while cash is consumed or financing liabilities increase. Once the facility becomes available for its intended use, depreciation and certain operating costs begin affecting reported profitability. Commercial revenues may develop alongside commissioning, after commissioning, or through existing businesses that use the new infrastructure.
The precise relationship between these stages depends on the contract. Equipment ordered under a purchase commitment may not immediately appear as owned property and equipment. A finance lease can produce a recognised asset and liability, while an operating lease produces a different pattern of expense recognition. A facility still under construction may require continuing financing and maintenance expenditure even if depreciation has not yet commenced. These distinctions are indispensable because the hypothetical earnings trap is not based on an assumption that every dollar of committed investment immediately reduces net income.
The more important financial problem is the erosion of discretionary capacity. Funds committed to an infrastructure programme cannot necessarily be recovered at their recorded value if management subsequently decides that market conditions no longer justify the original investment. Buildings, power infrastructure and advanced computing systems may have different alternative uses, resale possibilities and technological lifetimes. An unfinished data centre with favourable electricity rights may retain considerable strategic value, while specialised hardware awaiting installation may face more immediate exposure to technological replacement.
Amazon’s second-quarter figures demonstrate the cash-flow mechanism particularly clearly. Despite substantial growth in operating cash generation, the company’s reported trailing-twelve-month free cash flow was negative, principally because property and equipment expenditure expanded substantially. This is not, in itself, proof that the investment programme is failing. It indicates that current operating cash flows are being converted into future productive capacity at a rate that materially reduces residual financial flexibility. Whether that conversion creates or destroys value depends on the subsequent profitability of the assets financed. Amazon Announces Second Quarter Results — Amazon — July 2026.
Meta’s future lease commitments reveal a complementary form of exposure: financial rigidity can develop through contractual obligations even before the infrastructure has entered service. The existence of long-duration commitments does not mean the corresponding assets are currently available, nor does it establish that all future lease payments are economically unavoidable under every contingency. It does, however, narrow the ability to adjust the programme without examining cancellation provisions, commencement conditions and contractual remedies. A company may therefore retain substantial cash reserves while simultaneously carrying a progressively less flexible portfolio of future infrastructure obligations.
Alphabet’s financing transactions introduce another dimension. New equity-related financing can preserve liquidity and support construction without producing the same immediate contractual servicing requirements as conventional debt, but it may dilute existing shareholders or alter claims on future distributions. Senior notes provide a different financing route, involving interest obligations and refinancing considerations. The economic comparison depends on the actual instruments, their terms, the returns generated by the investment programme and the extent to which financing proceeds are used to fund productive assets rather than other corporate purposes.
For decision-makers, the central indicator is not simply gross debt or current liquidity. It is the relationship between operating cash generation, committed infrastructure spending, contractual obligations and the capacity to finance projects that have not yet reached their expected return profile.
The hidden distribution of risk between short-lived computing equipment and long-lived infrastructure
The financial structure of AI infrastructure creates a pronounced distinction between technology assets and the physical systems supporting them. Computing equipment may have a relatively short economic life because its productivity and commercial competitiveness depend on rapid technological development. Buildings, substations, cooling infrastructure and site improvements may remain economically useful for considerably longer periods. A large investment programme consequently combines assets whose expected lifetimes, replacement requirements and residual values differ materially.
Microsoft’s disclosure that approximately two-thirds of its fiscal fourth-quarter capital expenditure related to shorter-lived assets provides direct evidence of the importance of this distinction. An investor analysing the programme as though it were primarily the construction of long-lived property would underestimate the significance of hardware replacement and technology-driven depreciation. Equally, an assessment treating the programme entirely as short-lived computing equipment would overlook the potential durability of land, buildings and electrical infrastructure. Microsoft FY2026 Q4 Earnings Conference Call — Microsoft — July 2026.
The interaction becomes particularly consequential if commercial utilisation is delayed. Hardware installed and placed in service before the associated capacity achieves sufficient demand may begin consuming its accounting and economic life while producing suboptimal returns. Hardware not yet available for use may avoid immediate depreciation, but it can still face changes in expected recoverable value if newer technology reduces its future economic competitiveness. Long-lived infrastructure can preserve value under such conditions if it remains adaptable to subsequent generations of computing equipment, but that adaptability depends on the technical and physical characteristics of the facility.
The capital programme should therefore be analysed as a collection of investment vintages rather than as one cumulative expenditure figure. Each vintage has a commitment date, cash-payment profile, commissioning schedule, depreciation start date, expected useful life and commercial return curve. The hypothetical 18-month delay does not affect all vintages identically. It may leave already productive installations relatively unaffected while exposing unfinished projects and recently commissioned facilities to substantially different financial pressures.
A useful investment analysis would consequently separate committed but unpaid expenditure, assets under construction, available computing capacity, productive capacity and infrastructure approaching replacement. Without this separation, apparently reassuring measures of aggregate installed capacity or contracted expenditure may conceal deteriorating capital efficiency.
Chapter 1 — Key judgments
The documented corporate accounts establish that the AI investment cycle has become a major balance-sheet, liquidity and financing consideration for all four companies, although its effects differ materially by business model and financial structure. The stipulated $725–760 billion aggregate is suitable as a scenario perimeter, but not as a reconciled measure of identical capital expenditure across the companies.
The most important immediate vulnerability is the mismatch between the timing of capital commitments and the development of incremental operating cash flow. The principal risk is not necessarily insolvency or even a decline in consolidated revenue. It is the possibility that the companies continue increasing their invested capital while the marginal economic returns on that capital fall below the level required to justify the programme.
What would change the assessment: Corporate disclosures showing a sustained improvement in incremental capital productivity, stronger free cash flow after infrastructure investment, commercially credible utilisation of newly completed facilities and greater flexibility in outstanding contractual commitments would weaken the financial-stress pathway. Conversely, a growing stock of unfinished assets, falling cash conversion and repeated revisions to commissioning schedules would strengthen it.
Open official record: The most consequential unresolved requirement is a comparable company-by-company reconciliation of AI-specific cash expenditure, lease-related investment, construction commitments and incremental operating returns. Current corporate reporting does not provide a complete uniform basis for calculating that relationship across all four hyperscalers.
Chapter 2. The 18-Month Earnings Trap: Depreciation, Financing Costs, Revenue Recognition and Operating Leverage
When revenue growth ceases to provide a reliable measure of investment profitability
The central vulnerability of the hypothetical 18-month delay is the possibility that the hyperscalers continue reporting expanding commercial activity while the financial productivity of their newly committed capital deteriorates. This is a materially different problem from a conventional downturn in demand. A technology company facing declining sales can attempt to preserve margins by reducing discretionary expenditure, adjusting employment or moderating investment. A hyperscaler committed to an extensive infrastructure programme faces a more complicated situation because a substantial proportion of its future expenditure may already be embedded in construction contracts, financing arrangements, equipment orders and lease obligations, while the capacity under development cannot necessarily be activated at the time originally anticipated.
The distinction between revenue growth and investment profitability is particularly important in the current reporting environment. Microsoft’s fiscal fourth-quarter 2026 results showed consolidated revenue growth of 18%, while operating income also increased 18%. Its reported company-wide gross margin nevertheless declined to 67%, with management identifying the changing sales mix towards Azure, continued AI infrastructure investment and greater product usage among the factors affecting profitability. The evidence does not establish an earnings collapse; rather, it demonstrates that strong revenue and operating income growth can coexist with increasing pressure on the margins of activities absorbing additional infrastructure investment. The company’s Azure growth also shows why the scenario must remain conditional: Microsoft reported that newly available computing capacity was rapidly monetised during the quarter, providing a direct counterexample to any assumption that all infrastructure investment was suffering delayed utilisation. Microsoft Fiscal Year 2026 Fourth Quarter Earnings Conference Call — Microsoft — July 2026.
Alphabet presents a similar need to distinguish underlying performance from the accounting composition of reported results. In the second quarter of 2026, consolidated revenue increased 24%, Google Cloud revenue increased 82%, and consolidated operating income increased 30%. At the same time, depreciation of property and equipment reached approximately $7.10 billion, compared with approximately $5.00 billion during the corresponding quarter of 2025. This increase demonstrates the growing income-statement consequences of prior infrastructure investment, although it cannot be attributed exclusively to AI without a more granular breakdown. More importantly, Alphabet’s reported net income was materially influenced by investment-related gains outside ordinary operating activity, including approximately $98 billion of net other-income gains, primarily associated with equity securities. Consequently, an analysis based on headline net income or reported earnings-per-share growth alone would risk confusing financial investment gains with the operating economics of AI infrastructure. Alphabet Announces Second Quarter 2026 Results — Alphabet — July 2026.
The problem is not restricted to accounting presentation. It concerns the way physical assets change the economic characteristics of the business. Software revenues can expand through additional customers, subscription upgrades or product adoption without requiring an equivalent proportional increase in dedicated physical infrastructure. Computing-intensive AI services are different because incremental usage can require additional hardware, electricity, cooling, networking capacity and operational expenditure. Software-level monetisation may still produce attractive margins, but those margins increasingly depend on the cost and utilisation of the infrastructure supporting them.
The earnings trap begins when the rate of growth in these infrastructure-related costs exceeds the incremental gross profit attributable to the services they enable. In this situation, higher customer demand is not sufficient to guarantee higher returns. Additional demand must also be monetised at prices and utilisation levels capable of recovering the capital committed, operating expenses, financing costs and eventual replacement of the productive assets.
Depreciation, technological replacement and the difference between accounting life and economic life
Depreciation is one of the principal mechanisms through which earlier capital expenditure affects subsequent operating profitability, but its timing is frequently misunderstood. The accounting recognition of a new asset ordinarily occurs as qualifying expenditure is incurred or the asset is obtained, while depreciation generally begins when that asset is available for its intended use. A data centre still under construction may therefore increase the recorded value of property and equipment without immediately producing the same depreciation expense as a completed operating facility. Conversely, computing equipment that has been placed into service may begin depreciating even when commercial utilisation is lower than management originally expected.
This distinction creates two different forms of financial exposure. The first is the risk associated with assets that are still being developed and cannot yet enter productive service. The second is the risk associated with assets that have entered service but do not generate sufficient incremental operating profit. The former predominantly affects invested capital, liquidity, financing and potentially recoverable value; the latter also creates a recurring income-statement burden.
Microsoft’s July 2026 announcement concerning the estimated useful lives of certain property assets illustrates why depreciation assumptions deserve close scrutiny. The company stated that, effective from the beginning of fiscal 2027, it would extend the estimated useful lives of its data-centre and office buildings from 15 to 25 years. Management indicated that the resulting adjustment would have only a minimal benefit to fiscal 2027 operating income, while producing a more significant change in the classification of certain future leases. This is an important example of how reported capital expenditure, future depreciation and lease accounting can change without a corresponding change in the physical infrastructure programme. Microsoft Fiscal Year 2026 Fourth Quarter Earnings Conference Call — Microsoft — July 2026.
An extension of the expected useful life of buildings should not be confused with an extension of the economically competitive life of computing hardware. Buildings can remain operational through successive generations of installed equipment, provided their electrical, mechanical and spatial characteristics permit adaptation. Servers and accelerators are exposed to changes in computational efficiency, customer preferences and available technology. Their economic usefulness may consequently evolve differently from their accounting depreciation schedules.
Under the 18-month delay scenario, this divergence becomes financially consequential. If new computing equipment is commissioned before the revenue associated with its deployment develops sufficiently, depreciation may reduce reported margins during the period of underutilisation. If commissioning itself is postponed, depreciation may not yet begin, but the equipment or associated commitments can still be exposed to economic obsolescence. The difference determines whether the adverse development first appears through the income statement, through liquidity and invested capital, or through an impairment assessment.
The conditions for impairment require particular care. An adverse market environment, delayed project or declining share price does not automatically require a write-down. The relevant accounting analysis depends on the applicable asset category, impairment framework, level of asset grouping, recoverability assessment and evidence concerning future economic benefits. An impairment becomes relevant when the applicable accounting criteria indicate that the asset’s carrying amount is no longer supported. It is therefore more accurate to treat selective infrastructure write-downs as a possible later consequence of persistently deteriorating project economics rather than as a mechanical result of an 18-month delay.
Financing costs and the migration from construction risk to operating risk
The financial effects of a prolonged commissioning cycle extend beyond depreciation because the infrastructure must be financed throughout the period between initial commitment and economic maturity. Some investments are funded internally through operating cash flow, while others involve debt issuance, leases, supplier financing or arrangements with infrastructure partners. The financing structure determines when cash payments occur, whether interest is capitalised during qualifying construction and which obligations ultimately affect operating or financing expenses.
This produces an important asymmetry. During construction, qualifying borrowing costs may be included in the carrying value of an asset rather than immediately recognised as an expense. Once the relevant capitalisation conditions cease, financing costs associated with the remaining obligations may affect reported earnings directly. The transition from construction to productive operation can therefore involve a change in both depreciation and interest recognition at precisely the point when commercial revenue may still be developing.
Meta’s disclosures are particularly instructive. Its quarterly filing identifies substantial future infrastructure lease commitments, while its cash-flow statements separately report interest paid net of capitalised amounts. This distinction is evidence of an accounting structure in which cash financing costs, recognised interest expenditure and amounts incorporated into asset values must be analysed separately. It would be incorrect to treat the entire nominal amount of future lease commitments as current debt expense, just as it would be incorrect to conclude that capitalised financing costs impose no economic burden. Meta Platforms Form 10-Q, Quarter Ended 30 June 2026 — US Securities and Exchange Commission — 2026.
The decisive financial measure is the cost of maintaining committed capital until it becomes productive. This includes the direct price of financing where applicable, but also the opportunity cost of using internal liquidity that might otherwise support investment, acquisitions, distributions or balance-sheet resilience. An internally funded infrastructure project is not economically free of financing costs merely because it does not generate an explicit interest expense. Shareholders still require an adequate return on the capital allocated to it.
The hypothetical delay consequently affects companies differently according to their ability to absorb temporary reductions in cash generation. A company with substantial operating cash flow, a diversified business portfolio and manageable contractual obligations may be able to sustain delayed returns without altering the programme materially. A company facing more restrictive contractual payments, substantial refinancing requirements or limited alternative sources of cash may be forced to reduce planned investment even where the long-term commercial opportunity remains attractive.
The revenue-recognition problem: contractual demand is not equivalent to earned revenue
The other side of the earnings trap concerns the conversion of commercial demand into recognised revenue. A hyperscaler may report customer commitments, bookings, backlog or remaining performance obligations that suggest substantial future demand, but these measures are not interchangeable with recognised revenue, collected cash or operating profit.
Under ordinary revenue-recognition principles, a commercial commitment is reflected in the income statement according to the satisfaction of the relevant contractual performance obligations. The precise timing depends on the nature of the services provided, whether the customer has access to the contracted capacity, the contract’s enforceable terms and the applicable accounting treatment. It is therefore possible for a large infrastructure contract to support an expanding backlog while contributing only gradually to reported revenue.
Microsoft’s July 2026 disclosures reported commercial remaining performance obligations of approximately $678 billion, with management discussing the expected timing of future revenue recognition. That figure is economically relevant because it demonstrates the scale of contracted business commitments. It is not, however, equivalent to cash already received, future operating profit or revenue exclusively attributable to new AI infrastructure. The company’s reporting also indicated that customer demand exceeded available Azure capacity, reinforcing the distinction between commercially identified demand and infrastructure available to serve it. Microsoft Fiscal Year 2026 Fourth Quarter Earnings Conference Call — Microsoft — July 2026.
An 18-month delay can therefore produce several distinct financial outcomes. If the relevant customer contracts remain enforceable and commercial demand is sustained, the consequence may be delayed recognition rather than permanent revenue destruction. If customers reduce their planned usage, seek alternative providers or renegotiate contractual arrangements, the expected revenue may deteriorate more substantially. If the contracted infrastructure becomes available only after a commercially relevant technological transition, the original assumptions about utilisation and pricing may no longer be achievable.
The risk is particularly important where customer commitments and infrastructure development are economically linked. A large contract can justify construction, but the existence of the contract does not eliminate the possibility of counterparty concentration, changes in customer financing or technical delays. Similarly, contracted revenue does not determine the margin at which services will ultimately be delivered. A company can satisfy its commercial commitments while earning a lower return than originally projected if electricity, equipment, financing or operating costs exceed expectations.
The distinction between backlog quality and backlog volume is consequently central to the scenario. A defensible financial assessment must examine how much contracted demand relates to capacity that is already available, how much requires additional construction, how payment obligations are structured and how much operational flexibility remains if the customer’s requirements change.
Why earnings can deteriorate while valuation multiples expand
The relationship between earnings and valuation is often described imprecisely. A decline in earnings does not by itself demonstrate that investors are assigning a higher economic value to the company. The price-to-earnings ratio is determined by the relationship between market price and earnings per share. If earnings per share decline while the share price remains unchanged, the reported multiple rises mechanically. If the share price rises while earnings decline, the multiple expands more sharply. If the share price falls proportionately more than earnings, the multiple can contract despite deteriorating profitability.
Under the stipulated scenario, the critical question is whether investors continue treating the earnings weakness as temporary while preserving expectations of substantial future growth. If they do, the share price may remain supported even as depreciation and operating costs compress near-term profitability. The observed P/E ratio would then become increasingly sensitive to expectations regarding capacity utilisation, pricing and long-term returns.
That outcome should not automatically be interpreted as speculative mispricing. Equity valuations are forward-looking, and investors can rationally accept temporarily weaker earnings if future cash flows justify the price paid. The financial vulnerability arises when the future earnings recovery required to justify the existing valuation becomes progressively more demanding while the evidence supporting that recovery remains uncertain.
This is especially relevant when reported net income contains large non-operating items. Alphabet’s second-quarter 2026 results provide a documented example: its investment-related gains materially increased reported net income and diluted earnings per share. A valuation analysis using that exceptional earnings figure without adjustment could understate the economic multiple associated with recurring operating profitability. The reverse problem can arise when temporary charges reduce reported earnings without indicating an equivalent permanent deterioration in the company’s core cash-generating capacity. Alphabet Announces Second Quarter 2026 Results — Alphabet — July 2026.
The appropriate analytical framework therefore separates reported earnings, recurring operating profit, operating cash flow, free cash flow and the expected return on incremental invested capital. These measures address different questions and should not be used interchangeably.
| Financial measure | What it establishes | Potential distortion during an 18-month delay | Required analytical correction |
|---|---|---|---|
| Revenue growth | Expansion of recognised commercial activity | Growth from existing businesses may conceal weak returns from new AI assets | Isolate relevant business segments and incremental revenue |
| Gross margin | Profitability after direct operating costs | Revenue mix and infrastructure depreciation can change margins | Examine segment margins, cost composition and utilisation |
| Operating income | Profit after operating expenses | Depreciation and fixed operating costs can rise ahead of incremental revenue | Reconcile infrastructure-related cost growth with commercial returns |
| Net income | Profit after non-operating items and taxes | Investment gains, financing effects and exceptional charges can dominate changes | Separate recurring operations from material non-operating items |
| Earnings per share | Net income attributable per diluted share | Equity issuance, repurchases and unusual income items affect comparability | Analyse diluted share count and normalised earnings |
| Operating cash flow | Cash generated through operations | Can remain strong while investment expenditure accelerates | Compare with actual cash investment and commitments |
| Free cash flow | Residual cash generation under the company’s definition | Capex classifications and lease treatment affect comparability | Reconcile definitions and lease-related cash flows |
| Return on invested capital | Profitability relative to capital employed | Unproductive construction assets can depress returns before full operation | Distinguish committed, commissioned and productive assets |
| P/E ratio | Relationship between equity price and earnings | Can increase mechanically as earnings decline | Compare earnings quality, expected recovery and price movements |
| Asset impairments | Recognition of qualifying deterioration in asset carrying values | Potentially concentrated in specific projects rather than the whole portfolio | Examine asset groups, recoverability and project-specific evidence |
This framework reveals why a capital-intensive investment cycle can continue generating apparently contradictory financial signals. Revenue may increase while gross margins weaken. Operating income may grow while free cash flow declines. Share prices may remain strong while current P/E ratios expand. Contracted demand may rise while operating capacity remains constrained. None of these combinations is inherently inconsistent. They reflect the interaction between different stages of capital deployment and different financial measurement systems.
Operating leverage, marginal returns and the distinction between demand growth and economic value
The decisive financial outcome depends on operating leverage. Infrastructure businesses can become highly profitable when substantial fixed costs are distributed across growing volumes of commercially productive activity. The same cost structure produces the opposite effect when utilisation remains insufficient, because the assets continue generating fixed expenses while revenue does not expand enough to recover them.
For AI infrastructure, the economics are complicated by the relationship between hardware efficiency, market prices and demand. Improvements in computing efficiency can increase the productive output obtainable from installed equipment, potentially improving margins. They can also reduce the price customers are willing to pay for a unit of computation, especially if competitors adopt similar technologies. The net effect on returns depends on whether productivity gains translate into higher operating profit, lower capital requirements or competitive price reductions.
A similar issue arises with the composition of demand. Some infrastructure supports services sold directly to cloud customers, while other infrastructure contributes to internal applications, advertising systems, software development or research. Incremental revenue and cost savings must consequently be assessed together. A company may earn an attractive return from infrastructure that reduces internal operating costs even without reporting a corresponding standalone revenue stream. Alternatively, an expanding externally marketed AI service may generate substantial revenue but weak profitability if the hardware and electricity costs required to deliver it remain elevated.
The scenario’s 18-month delay should therefore be interpreted as a delay in achieving expected economic returns, not necessarily as an absence of revenue during the period. This formulation avoids imposing an unsupported uniform revenue trajectory on four businesses with different commercial models.
For Microsoft and Amazon, the financial test is substantially connected to the ability to monetise cloud infrastructure and associated services while preserving acceptable segment profitability. For Alphabet, it includes both external cloud economics and the contribution of AI capabilities to its wider operations. For Meta, the relevant returns may be realised through changes in the economics of established advertising and engagement businesses rather than exclusively through direct infrastructure sales.
The common denominator is whether incremental operating profit ultimately compensates for incremental capital employed. Without a comparable estimate of that relationship, neither high revenue growth nor high reported capital expenditure is sufficient to establish that the programme creates value.
Chapter 2 — Key judgments
The 18-month earnings trap is a credible conditional mechanism because the financial recognition of infrastructure investment is distributed across different periods and financial statements. It should not, however, be presented as an established deterioration in the earnings of all four hyperscalers. The corporate disclosures examined show both substantial infrastructure-related financial pressures and strong operating performance, including demonstrated demand for additional computing capacity.
The decisive vulnerability is the possible deterioration in incremental returns when infrastructure-related depreciation, operating costs and financing obligations increase faster than the economic benefits attributable to new capacity. The effect can appear first in free cash flow, subsequently in operating margins and eventually in asset valuations if the expected commercial returns weaken sufficiently.
What would change the assessment: Sustained improvements in capacity utilisation, computing efficiency, realised pricing and infrastructure-related margins would weaken the earnings-trap scenario. A continuing divergence between capital investment and incremental operating profit, particularly when accompanied by declining cash conversion or asset recoverability, would strengthen it.
Open official record: Company-level disclosures do not provide a uniformly comparable schedule identifying the depreciation, utilisation, revenue contribution and incremental return of the 2026 AI infrastructure investment vintages. That limitation prevents a defensible calculation of a common 18-month earnings impact or an aggregate percentage reduction in profitability.
Chapter 3. From Valuation Compression to Capital Capitulation: Market Discipline and Investment Deferrals
The point at which an investment delay becomes a capital-allocation crisis
The transition from an earnings delay to capital capitulation is neither automatic nor necessarily immediate. Financial markets can tolerate extended periods of negative free cash flow when investors believe that the underlying capital expenditure is creating assets capable of generating sufficiently attractive future returns. This tolerance changes when the observed development of operating cash flow, margins and capital productivity begins to contradict the assumptions that justified the investment programme.
The distinction between temporary earnings weakness and structural capital misallocation is therefore the central analytical problem. A temporary delay preserves the fundamental economic rationale for investment while postponing its financial benefits. Structural misallocation occurs when the assets are no longer expected to generate returns sufficient to compensate for the capital committed, including the risks associated with construction, technology, demand and financing. The same initial financial symptoms can be consistent with both conditions.
The four hyperscalers enter this hypothetical adjustment from materially different financial positions, but the relevant distinction is not simply the absolute amount of cash held or debt outstanding. Their capacity to sustain the programme depends on future cash generation, contractual obligations, financing flexibility and the expected productivity of projects already under development.
Financial markets would therefore have to judge whether further expenditure is required to complete economically valuable facilities or whether continuing to invest would merely increase exposure to projects whose original assumptions have deteriorated. That distinction becomes particularly difficult where substantial expenditure has already occurred. Previous investment cannot by itself justify additional investment, yet abandoning a nearly completed facility may destroy more value than financing the remaining work required to place it into service.
Capital discipline in this environment requires prospective project economics rather than retrospective justification. A rational continuation decision compares the additional expenditure needed to complete a project with the incremental benefits expected from completion, accounting for remaining contractual obligations and the value of alternative uses. The amount already spent is relevant to financial reporting and recoverability, but it should not determine whether further expenditure is economically justified.
This creates the conditions for selective capitulation: management preserves projects with credible future returns while postponing or cancelling investments that no longer meet its requirements.
Equity-market discipline and the changing interpretation of the AI investment premium
Valuation compression can develop through several mechanisms. Investors may lower their expectations for long-term AI revenue, increase the return required to compensate for infrastructure and technological risk, reduce the multiple applied to expected earnings, or reassess the amount of future capital expenditure necessary to sustain growth.
These mechanisms are related but not identical. A lower expected revenue trajectory reduces projected future operating profits. A higher required return reduces the present value assigned to those profits. A higher expected replacement burden reduces the cash available to shareholders even if accounting earnings remain positive. The interaction can produce a material decline in equity valuation without requiring a corresponding collapse in current revenue.
Under the 18-month delay scenario, the initial response may be relatively limited if investors conclude that project economics remain intact. A moderate postponement of returns could be absorbed through a longer valuation horizon, especially where management provides credible evidence of contracted demand and eventual operating leverage.
Pressure would intensify if successive disclosures indicate that the delay has become embedded in the capital programme rather than confined to specific projects. Repeated postponements, substantial additions to unfinished infrastructure and weaker cash conversion would undermine confidence in previously stated investment assumptions. Investors could begin demanding evidence of returns from completed facilities before supporting further increases in capital commitments.
The resulting change in valuation would affect management incentives. An infrastructure programme that previously appeared acceptable because investors rewarded long-term growth could become difficult to sustain if the market began rewarding cash generation and disciplined capital allocation instead. The company would then face pressure to preserve free cash flow, moderate financing requirements or redirect expenditure towards projects with shorter and more credible paths to profitability.
Such pressure would not necessarily take the form of an explicit instruction from shareholders to abandon artificial intelligence investment. It could arise through a lower equity valuation, an increased cost of external financing, reduced tolerance for earnings volatility or a widening gap between corporate capital expenditure guidance and the financial performance investors expect.
The consequences would be most acute for projects requiring significant additional investment before their commercial viability can be demonstrated. Infrastructure already generating adequate returns would remain comparatively defensible, while facilities dependent on uncertain demand, unresolved development requirements or extensive additional financing would become more vulnerable to postponement.
The hierarchy of investment adjustment: deferral, redesign, cancellation and impairment
Capital capitulation is not a single financial event. It is a progression of possible management responses, each with different consequences for future cash flows, reported earnings, suppliers and competitive positioning.
An initial adjustment may involve reducing the rate of new project approvals without abandoning previously approved investments. Management can preserve access to strategically valuable locations or infrastructure rights while postponing discretionary additions until demand visibility improves. Such a response reduces exposure to new commitments but may leave existing contractual obligations largely unchanged.
A more significant response involves rescheduling projects already under development. This may conserve near-term capital expenditure if supplier agreements and construction contracts allow flexibility, but it can also introduce additional costs or delay revenue that would otherwise have become available. The net economic benefit depends on the commercial and contractual conditions specific to the project.
Project redesign offers another possibility. Infrastructure investment could be modified to accommodate different computing architectures, equipment generations or customer requirements, provided the physical design permits such changes. The potential benefit is improved capital productivity, while the principal risk is further construction delay or additional expenditure without a corresponding improvement in expected returns.
Cancellation represents a more definitive decision. It may preserve future liquidity where substantial expenditure remains discretionary, but the company must account for cancellation penalties, unrecoverable development costs, supplier claims and any deterioration in the value of assets already acquired. Cancellation can therefore improve future capital allocation while simultaneously producing adverse near-term cash or accounting effects.
Impairment is different from cancellation. A company may continue operating an impaired asset, and a cancelled project does not necessarily result in a write-down equal to all expenditure previously incurred. The accounting outcome depends on the recoverability of the assets concerned and the applicable recognition rules.
| Capital-allocation response | Economic rationale | Potential liquidity effect | Accounting consideration | Main strategic cost |
|---|---|---|---|---|
| Slower approval of new projects | Limit exposure to unproven demand | Reduces future discretionary commitments | Generally limited immediate impact unless existing assets or obligations are affected | Potential loss of future capacity |
| Deferral of capacity additions | Match development more closely to demand | Preserves near-term cash where contracts permit | Existing commitments and capitalised costs remain relevant | Delayed commercial availability |
| Renegotiation of supply commitments | Improve payment timing or project flexibility | Potential reduction in near-term payments | Depends on amended contract terms | Supplier disruption or higher future costs |
| Technical redesign | Improve productivity or accommodate new technology | May increase or redistribute expenditure | Potential changes to asset costs and useful lives | Additional execution complexity |
| Selective cancellation | Avoid remaining expenditure on weak projects | Preserves future cash net of termination costs | Recoverability, contractual liabilities and impairment must be assessed | Loss of development options |
| Asset impairment | Reflect qualifying deterioration in asset value | Often non-cash at recognition | Reduces carrying value and reported earnings | Evidence of weakened investment economics |
| Portfolio reallocation | Concentrate resources on higher-return facilities | Redirects rather than necessarily reduces expenditure | Depends on assets and contracts involved | Concentration of capital in fewer projects |
The decisive feature of this adjustment process is that the largest reported reduction in capital expenditure does not necessarily represent the most successful response. A company that reduces investment indiscriminately may preserve cash while sacrificing commercially valuable capacity. A company that continues investing selectively may report substantial expenditure but improve its expected return on incremental capital.
The quality of capital allocation depends on the distinction between projects whose completion creates value and projects whose continuation merely postpones recognition of economic losses.
Contractual rigidity and the limits of managerial discretion
One of the most important variables in a potential capitulation scenario is the difference between expenditure management can still avoid and expenditure already embedded in enforceable commitments.
This is particularly relevant to data-centre infrastructure, where projects may involve long-term leases, equipment orders, construction contracts and arrangements with third-party infrastructure providers. A reduction in announced future capital expenditure does not necessarily eliminate obligations that have already been incurred. Conversely, the existence of a contractual commitment does not establish that all payments are immediately due or that the company has no contractual remedies or adjustment rights.
Meta’s disclosures of substantial not-yet-commenced lease obligations provide a particularly important example of this distinction. The reported obligations indicate that the company’s future infrastructure development is supported by extensive contractual arrangements extending across subsequent years. Their financial significance depends on commencement conditions, payment schedules, termination provisions and the economic value of the associated facilities. They should not be treated as an immediately payable amount, but they cannot be ignored when assessing management’s freedom to slow investment. Meta Platforms Form 10-Q, Quarter Ended 30 June 2026 — US Securities and Exchange Commission — 2026.
The same analytical principle applies to other hyperscalers. Long-term financing and infrastructure commitments can make the investment programme less responsive to deteriorating market conditions than headline capital expenditure guidance suggests. Reducing planned expenditure may be easier than reducing contracted expenditure, while reducing actual cash payments may be more difficult than modifying the timing of asset recognition.
Investors should consequently distinguish between capital expenditure flexibility, contractual flexibility and economic flexibility. Capital expenditure flexibility concerns the ability to change future investment plans. Contractual flexibility concerns the ability to amend or terminate existing commitments. Economic flexibility concerns the ability to redirect assets and resources towards alternative uses that preserve value.
A company can possess substantial accounting liquidity while having limited contractual flexibility. It can also possess significant contractual obligations while retaining strong economic flexibility if the underlying assets are commercially valuable and adaptable. The balance between these conditions determines whether management can conduct a selective investment adjustment or is forced into a more damaging retrenchment.
Why partial capitulation could strengthen rather than weaken the hyperscaler oligopoly
The central paradox of the scenario is that a financial correction can increase market concentration even when the companies involved experience temporary reductions in profitability.
This outcome requires more than the assumption that large companies can spend more than small companies. The relevant mechanism is differential access to the resources necessary to complete commercially productive infrastructure. If electricity access, financing capacity and contracted customer demand remain difficult to secure, companies that already control viable development projects may possess advantages that competitors cannot reproduce on comparable terms.
A period of market discipline could therefore encourage the largest hyperscalers to concentrate investment in their strongest facilities, preserve valuable infrastructure rights and reduce expenditure on marginal projects. Smaller or financially weaker operators might face greater difficulty maintaining their own construction programmes, particularly if the cost of external financing increases or capital providers demand stronger evidence of near-term returns.
The resulting market structure could become more concentrated even though aggregate investment growth slows. The critical condition is that financially stronger companies retain control of commercially productive capacity while their competitors lose the ability to develop equivalent alternatives.
However, this outcome is not automatic. A smaller infrastructure provider may possess a strategically valuable site, a competitive technological architecture or contractual access to financing and electricity that provides an advantage over a larger competitor. Similarly, concentration among infrastructure owners does not necessarily translate into higher operating margins if the remaining hyperscalers continue competing aggressively on price and service quality.
An oligopoly premium is economically defensible only if concentration produces durable advantages in cash generation or capital productivity. Scarcity that simply increases construction costs, equipment prices or financing burdens does not create an attractive investment return by itself. It can make entry more difficult while simultaneously reducing profitability for incumbents.
The distinction is especially important where long-term customer contracts limit pricing flexibility. A hyperscaler may possess scarce infrastructure capacity yet be unable to increase prices sufficiently to recover rising investment costs. Conversely, a company with commercially valuable capacity and flexible customer arrangements may benefit from stronger demand relative to available supply.
The potential reinforcement of concentration is therefore contingent on several interacting conditions: sustained demand, reliable infrastructure deployment, relatively strong operating margins, adequate financing capacity and the ability to translate scarce capacity into commercially profitable services.
The capital-market consequences of a sequential adjustment
The most analytically coherent pathway is not necessarily a binary movement towards either widespread capitulation or uninterrupted investment expansion. A sequential adjustment is possible in which an initial deterioration in free cash flow and expected returns leads to selective expenditure restraint, followed by renewed investment in projects that demonstrate stronger commercial economics.
Under this pathway, the first phase would be characterised by closer scrutiny of capital spending, reduced tolerance for projects without credible commissioning schedules and greater investor emphasis on cash conversion. Management would become more selective, potentially concentrating resources in infrastructure that can enter service and generate incremental operating profit within an acceptable period.
The second phase would depend on whether the reduction in marginal investment improves the economics of capacity that remains available or under development. If investment moderation prevents excess capacity from emerging while demand remains sufficiently strong, utilisation and commercial pricing could improve. Financial markets might then assign greater value to the infrastructure positions of companies capable of sustaining investment through the adjustment.
A third phase could involve renewed expansion, but under a different allocation discipline. Projects with secured demand, credible operating economics and dependable access to essential infrastructure would attract capital, while investments dependent on uncertain commercial assumptions would face stricter financial requirements.
This sequence would represent a transition from an investment environment primarily concerned with securing future scale to one concerned with proving the economic productivity of that scale.
The alternative is less favourable. If demand growth weakens structurally, technological efficiency substantially reduces the commercial value of existing equipment, or infrastructure costs remain elevated without corresponding pricing power, selective investment restraint may not restore returns. The companies could then experience sustained pressure on free cash flow and equity valuations despite moderating capital expenditure.
A reduction in investment would therefore be a necessary response to deteriorating project economics in some circumstances, but it would not automatically resolve the underlying profitability problem.
Decision conditions distinguishing the competing outcomes
The following framework identifies the evidence that would differentiate a temporary capital-market correction from a more durable deterioration in investment economics.
| Analytical dimension | Partial capitulation pathway | Concentration-reinforcement pathway | Decisive evidence |
|---|---|---|---|
| Incremental demand | Insufficient to justify planned capacity | Sustained relative to commercially available capacity | Contract conversion, utilisation and realised revenue |
| Operating leverage | Fixed costs grow faster than incremental gross profit | Productivity and utilisation improve margins | Segment profitability and infrastructure cost trends |
| Free cash flow | Persistent deterioration creates investment pressure | Operating cash generation supports selective expansion | Reconciled operating cash flow and capital expenditure |
| Financing conditions | Higher capital costs reduce project viability | Strong operators preserve access to financing | Debt terms, lease obligations and financing capacity |
| Contractual flexibility | High termination or deferral costs restrict adjustment | Valuable commitments preserve access to scarce assets | Contract terms and actual commissioning |
| Asset productivity | Obsolescence or weak utilisation impairs expected returns | Existing productive assets gain scarcity value | Recoverability, utilisation and operating margins |
| Competitive structure | Investment moderation reflects weak sector economics | Weaker competitors cannot reproduce viable capacity | Market entry, pricing and capacity ownership |
| Equity valuation | Earnings expectations and valuation multiples decline | Future cash-flow visibility supports a premium | Valuation relative to normalised operating earnings |
| Capital allocation | Broad reductions or cancellations | Selective preservation of economically superior projects | Project approvals, completions and cancellations |
The table does not assign numerical probabilities because the available evidence does not support a reproducible probability distribution for these outcomes. The conditions are also not necessarily mutually exclusive. A company can experience temporary earnings pressure, defer selected investments and subsequently strengthen its competitive position if the remaining portfolio produces attractive returns.
The appropriate monitoring approach is therefore evidence-based rather than dependent on a predetermined narrative about an inevitable AI investment collapse or inevitable hyperscaler dominance.
The governance implications of capital expenditure on an industrial scale
The investment cycle also changes the information that boards, audit committees and investors require to evaluate management performance. Traditional technology-sector financial analysis may place considerable emphasis on revenue growth, operating margins, customer adoption and earnings per share. These remain important, but the increased scale of physical infrastructure investment requires more systematic attention to capital budgeting, asset recoverability, financing commitments and project execution.
Board oversight should distinguish between investment authorised, expenditure incurred, contractual obligations undertaken and infrastructure that has become commercially productive. A project can remain within its announced capital budget while failing to meet its original investment objectives if commissioning is delayed or the expected commercial returns deteriorate. Conversely, an increase in capital expenditure can be economically justified where revised project economics indicate higher future productivity.
The relevant governance question is whether investment decisions are being revised as information changes. A credible capital-allocation process should be able to identify which projects remain commercially attractive under delayed-return assumptions, which require redesign or renegotiation, and which should no longer receive incremental capital.
External financial reporting cannot be expected to disclose commercially sensitive details of every infrastructure project. Nevertheless, the quality of public information matters because investors must distinguish strategic investment from the accumulation of commitments whose returns remain uncertain. Clearer disclosure of investment categories, asset commissioning, depreciation assumptions, lease obligations and capital efficiency would improve the ability to assess whether the programme is progressing economically.
The financial statements examined in the preceding chapters already demonstrate the importance of these distinctions. Microsoft provides evidence of how hardware composition and changes in asset-life assumptions influence reported expenditure and depreciation. Amazon illustrates the separation between substantial operating cash generation and negative residual cash flow. Alphabet demonstrates the interaction between infrastructure investment, external financing and non-operating earnings volatility. Meta illustrates the potential scale of future contractual obligations that extend beyond immediate cash capital expenditure.
Taken together, these examples establish that the investment programme should no longer be evaluated primarily through the language of technology adoption. It requires the financial discipline normally associated with substantial industrial capital formation.
Chapter 3 — Key judgments
The transition from delayed returns to partial capital capitulation would occur when management and investors conclude that the expected economic benefits of marginal infrastructure investment no longer justify the additional capital required. The existence of an 18-month delay would not, by itself, establish that threshold. The decisive evidence would be persistent weakness in capital productivity, constrained financial flexibility and a deterioration in the recoverability or expected commercial profitability of individual projects.
Selective deferrals and portfolio rationalisation could preserve financial resources without invalidating the broader economic rationale for AI infrastructure investment. The most favourable outcome for incumbent hyperscalers would arise if capital discipline improved the profitability of completed and strategically valuable capacity while weaker competitors became less able to finance comparable development.
The principal risk to that interpretation is the possibility that infrastructure scarcity increases costs without creating pricing power, or that changes in technology and customer demand reduce the economic value of assets before they achieve their intended returns.
What would change the assessment: A sustained increase in completed infrastructure utilisation, stronger capital-adjusted operating profitability and evidence of durable customer demand would support the concentration-reinforcement pathway. Repeated project cancellations, impairment charges, weaker contractual commitments and deteriorating returns across completed facilities would support the broader capitulation pathway.
Open official record: A defensible determination of the market outcome requires project-level economic information, including remaining capital commitments, completion schedules, expected operating margins, contractual flexibility and commercially available alternative capacity. Public corporate disclosures do not presently establish these variables on a sufficiently comparable basis to assign probabilities to the competing scenarios.
Pillar I — Integrated Financial Assessment
The financial architecture of the 2026 AI investment cycle creates a distinction between the capacity to finance infrastructure and the capacity to generate satisfactory returns from it. Microsoft, Amazon, Alphabet and Meta possess substantial established businesses and financial resources, but those advantages do not eliminate the economic consequences of committing capital to assets whose productivity depends on subsequent construction, commissioning, utilisation and commercial monetisation.
An 18-month postponement of expected returns would first challenge the relationship between investment expenditure and operating cash generation. Its later effects would depend on the composition of the assets, the timing of depreciation, the classification and servicing of financing obligations, the quality of commercial commitments and the capacity of incremental revenue to cover the economic cost of additional infrastructure.
The evidence available through October 2026 does not establish an industry-wide earnings collapse. Several of the companies report strong operating performance and significant customer demand. It does establish that the financial statements are becoming more sensitive to infrastructure investment, that financing and contractual commitments require increasingly careful interpretation, and that reported capital expenditure cannot be treated as a direct measure of newly productive AI capacity.
The resulting market bifurcation remains conditional. Financial discipline could force the abandonment of investments whose prospective returns have deteriorated, producing lower valuations and reduced infrastructure expansion. Alternatively, selective retrenchment could leave the strongest operators controlling a greater proportion of commercially valuable capacity, allowing market concentration to increase after an initial period of financial pressure.
The decisive financial question is whether the return on incremental invested capital can recover sufficiently to compensate for the resources committed during the period of delayed utilisation. Until that relationship becomes observable, the scale of the investment programme is evidence of industrial commitment, not proof of sustainable profitability or inevitable financial failure.
The analysis of Pillar II must consequently begin where conventional financial reporting becomes insufficient: the physical dependencies governing when infrastructure can enter productive service, how electricity and equipment constraints influence economic returns, and whether the industrial supply chain can support the development schedules embedded in corporate investment expectations.
PILLAR II — ELECTRICITY, PHYSICAL INFRASTRUCTURE AND INDUSTRIAL POWER
OPEN-SOURCE STRATEGIC INTELLIGENCE ASSESSMENT
Reference date: 25 October 2026
Geographic scope: United States, China, European Union, Italy, France, Germany and the United Kingdom.
Analytical horizon: The 2026 infrastructure investment cycle and its potential consequences through the early 2030s.
Chapter 4. The Interconnection Constraint: Grid Queues, Energisation and Stranded Development Capital
Electricity access is becoming a determinant of industrial competitiveness, not merely an operational input
The expansion of artificial intelligence infrastructure is exposing a structural limitation that cannot be resolved through additional investment in computing equipment alone. The ability to purchase advanced processors, commission buildings and secure customer demand does not guarantee that a computing facility can enter commercial operation at the intended scale. That requires dependable electricity supply, adequate transmission and distribution capacity, suitable interconnection infrastructure, voltage transformation, protection systems and a coordinated sequence of engineering, regulatory and construction approvals. These requirements introduce a different industrial timetable into an investment process previously dominated by technological development and capital availability.
The strategic consequence is that electricity has ceased to be merely a recurring operating expense for large computing facilities. It increasingly determines where productive capacity can be located, how quickly capital expenditure can be converted into revenue-generating operations, which projects remain commercially viable and which investors possess assets that competitors cannot replicate within a comparable development period. The economic value of an advanced data centre consequently depends not only on the performance of its computing equipment but also on its position within the electricity system, the availability of firm connection capacity and the reliability of the infrastructure required to sustain continuous operation.
The International Energy Agency, in its April 2025 report Energy and AI identified precisely this transition. It estimated that approximately 20% of planned data-centre projects could face delays unless electricity infrastructure risks were addressed, reported that new transmission lines can require four to eight years to develop in advanced economies, and observed that waiting times for critical grid components, including transformers and cables, had doubled during the preceding three years. These findings are significant because they identify a mismatch between the investment schedules pursued by data-centre developers and the substantially longer physical development cycles associated with electricity infrastructure. The report also warned that insufficient electricity-sector investment could force trade-offs between data-centre expansion, industrial electrification, manufacturing growth and electricity affordability.
The resulting industrial challenge is not simply a shortage of electricity generation in aggregate. An electricity system can possess substantial installed generation capacity while remaining unable to deliver additional firm power to a particular site because transmission lines, substations or local distribution infrastructure cannot accommodate the new demand. Conversely, a facility located near available network capacity may enter service more rapidly even where the wider regional electricity market remains constrained. National generating capacity, electricity production, transmission capability, local connection capacity and reliable power availability are therefore different variables. Treating them as interchangeable obscures the actual infrastructure constraint.
This distinction also changes the interpretation of hyperscaler investment announcements. A commitment to acquire computing equipment is not evidence that an equivalent volume of computing capacity will become operational according to the original commercial schedule. A data-centre construction announcement is not evidence that the facility possesses an executable electricity connection. Even an interconnection agreement may remain dependent on the completion of network reinforcement, the delivery of specialised equipment and the satisfaction of technical or regulatory conditions.
The hypothetical 18-month delay in financial returns must therefore be examined against the possibility that the underlying physical infrastructure experiences a much longer development cycle. An AI investment programme can remain financially committed during 2026 while portions of the associated facilities are unable to reach full commercial operation until subsequent years. Where network constraints persist, the delay can extend beyond the initial earnings stress period, creating a succession of infrastructure vintages whose economic availability is determined by electricity-system development rather than computing-equipment procurement.
The American interconnection backlog: what the official figures establish and what they do not
The frequently cited figure of approximately 2,600 gigawatts in the United States requires a precise definition. It represents the historical peak of the generation-and-storage interconnection queue at the end of 2023, not the current amount of data-centre electricity demand awaiting connection. The distinction is material because a generator seeking permission to inject electricity into the transmission system and a large industrial customer seeking permission to withdraw electricity from that system are not participating in the same engineering or administrative process.
The Lawrence Berkeley National Laboratory’s Queued Up: 2026 Edition, covering projects through the end of 2025, reports that the active American generation-and-storage queue had declined to approximately 2,061 GW by the end of 2025. This total comprised approximately 1,312 GW of generating capacity and 749 GW of storage, distributed across approximately 8,200 projects. The decline from the historical peak reflected high withdrawal rates and reduced additions to the queue, rather than evidence that the underlying connection problem had been comprehensively resolved.
The composition of the queue is particularly revealing. Solar projects accounted for approximately 773 GW, storage for 749 GW, natural gas generation for 253 GW, and wind for 220 GW. These figures describe the nominal capacities seeking connection, rather than electricity that can currently be supplied to operating facilities. Storage capacity is also not equivalent to continuously available generation capacity, because its ability to deliver electricity depends on charging conditions, discharge duration, operating arrangements and system requirements.
More consequentially, Berkeley Lab reported that 549 GW of capacity already had a draft or executed interconnection agreement but had not reached commercial operation. This category included approximately 256 GW of solar, 161 GW of storage, 76 GW of wind and 45 GW of natural gas. The distinction demonstrates that advancing through a formal connection process does not necessarily produce operational electricity capacity within the expected period. Commercial operation remains dependent on completion of the relevant generating facilities, connection works and other project requirements.
The laboratory also reported that, for regions with available data, the median period between an interconnection request and commercial operation exceeded five years for projects completed in 2025. Historical outcomes were even more revealing: of the generation capacity that submitted interconnection requests between 2000 and 2020, only 13% had reached commercial operation by the end of 2025, while approximately 75% had been withdrawn and 10% remained active. These are historical cohort outcomes rather than probabilities applicable to every current project. They nonetheless demonstrate why gross queue volumes should not be interpreted as a reliable pipeline of future electricity production.
The evidence establishes a substantial American infrastructure bottleneck, but it does not establish that every new large-load connection requires five to eight years. That duration remains a scenario assumption for the present assessment. The verified record supports a more precise conclusion: lengthy development periods are observable in generator connections, new transmission infrastructure can require several years, and the connection of large electricity consumers depends on different, location-specific network conditions that must be investigated separately.
American generation interconnection: verified baseline
| Indicator | Verified value | Reference period | Economic interpretation |
|---|---|---|---|
| Historical active queue peak | Nearly 2,600 GW | End-2023 | Maximum historical generation-and-storage queue |
| Latest active generation-and-storage queue | 2,061 GW | End-2025 | Projects seeking grid connection, not operating capacity |
| Generation projects | 1,312 GW | End-2025 | Proposed generating capacity |
| Storage projects | 749 GW | End-2025 | Proposed storage power capacity |
| Number of active projects | Approximately 8,200 | End-2025 | Requests rather than completed installations |
| Solar projects | 773 GW | End-2025 | Nominal solar capacity awaiting connection |
| Wind projects | 220 GW | End-2025 | Nominal wind capacity awaiting connection |
| Natural gas projects | 253 GW | End-2025 | Nominal gas-fired capacity awaiting connection |
| Capacity with draft or executed agreements but not operating | 549 GW | End-2025 | Contractual progress without commercial operation |
| Median request-to-operation duration | More than five years | Projects completed in 2025, regions with data | Historical generator-project duration |
| Historical applications reaching operation | 13% | Requests submitted 2000–2020, assessed end-2025 | Historical completion rate, not a present forecast |
| Historical applications withdrawn | 75% | Same cohort | Illustrates attrition and speculative project development |
The significance of these findings extends beyond the scale of the queue. They reveal that access to future electricity capacity is mediated by technical studies, network investment, contractual agreements, project completion and the ability of developers to absorb prolonged uncertainty. A hyperscaler considering a new data centre must therefore evaluate not only the expected electricity price but also the probability that the necessary physical connection can become operational within the economic life of the intended computing equipment.
The operational chain: from an electricity application to an energised data centre
The physical development of a large computing facility involves several dependencies that cannot always be compressed into a single construction schedule. The developer must establish its expected electrical load, operating profile, redundancy requirements and desired connection location. The relevant network operator must determine whether the existing system can accommodate the additional demand without compromising reliability, voltage stability or operating security. Where reinforcement is necessary, the project may depend on new substations, transformers, protection equipment, transmission infrastructure or upgrades elsewhere in the network.
These activities interact with the development of the data centre itself. The building may require structural completion, fire-safety approvals, mechanical systems, cooling infrastructure and internal electrical distribution before computing equipment can be commissioned. Even when the external electricity connection becomes available, the facility may not immediately be capable of absorbing its full contracted power requirement, because internal commissioning, testing, operational integration and customer installation can proceed in stages.
The relevant commercial milestone is therefore not necessarily the moment at which a building is structurally complete, an electrical connection agreement is signed or the first computing equipment is installed. It is the point at which the required combination of electricity, cooling, operational systems and computing capacity becomes available for commercially intended use.
The sequence matters because different delays produce different economic consequences. A delay in the delivery of computing hardware may leave completed electrical infrastructure underutilised. A delay in external network reinforcement may prevent already installed equipment from entering service. A delay in internal electrical or cooling systems may prevent a facility from using an otherwise available electricity connection. A delay in customer deployment may leave technically operational capacity below its expected commercial utilisation.
From an industrial perspective, these outcomes require different remedies. Additional computing equipment cannot resolve a missing substation. Additional generating capacity elsewhere cannot automatically resolve local transmission congestion. Faster building construction cannot eliminate the manufacturing lead time of specialised electrical equipment. The identification of the actual critical path is consequently more important than the aggregate amount of capital assigned to the project.
| Development stage | Principal physical requirement | Potential bottleneck | Commercial consequence | Record needed for verification |
|---|---|---|---|---|
| Site selection | Suitable location and network access | Local electricity-system constraints | Project location or scale may change | Grid-capacity assessment |
| Load application | Credible electrical demand profile | Incomplete or speculative applications | Queue congestion and uncertain allocation | Formal connection application |
| Network studies | System-impact and reinforcement assessment | Study capacity and network complexity | Connection conditions remain unresolved | Technical study and connection offer |
| Grid reinforcement | Transmission, substations and associated works | Permits, procurement and construction | External energisation postponed | Approved works and progress reporting |
| Equipment procurement | Transformers, switchgear, cables and protection systems | Manufacturing slots and delivery schedules | Critical-path extension | Supplier contracts and delivery milestones |
| Internal installation | Electrical distribution and cooling systems | Integration and commissioning problems | Facility remains technically incomplete | Testing and commissioning documentation |
| Energisation | Safe electrical connection and system acceptance | Outstanding network or site requirements | Computing capacity cannot reach intended operating level | Energisation confirmation |
| Commercial commissioning | Integrated operation of equipment and services | Performance testing or customer deployment | Revenue generation and utilisation lag | Operational acceptance and utilisation evidence |
The table identifies categories of project dependency rather than asserting that every project encounters each bottleneck. The engineering chain is consistent with the connection risks described in the IEA’s Energy and AI assessment, which specifically identifies the need for grid expansion, faster connection processes, equipment availability and more flexible data-centre operation.
The interaction between the 18-month return delay and a multiyear energisation constraint
The stipulated 18-month delay and the assumed five-to-eight-year connection horizon should not be added mechanically as though every project enters the electricity queue on the same date as its first capital commitment. Their interaction depends on when the relevant connection request was submitted, whether the site already possesses usable power capacity, whether network reinforcement has been approved and whether computing equipment has been ordered or installed.
A project that enters the connection process during 2026 without substantial existing network capacity could, under the stipulated five-to-eight-year stress assumption, face an electricity-availability horizon extending into 2031–2034. That is a conditional calendar implication, not a prediction for the aggregate hyperscaler programme. A facility already holding firm connection rights and requiring limited upgrades could follow a materially shorter timeline.
The crucial economic relationship concerns the relative timing of three processes: commitment of capital, physical availability of infrastructure and realisation of operating returns. The investment decision may become financially consequential before the electricity system is capable of supplying the relevant facility. Contractual payments, construction expenditure and potentially financing obligations may arise during the development period, while commercial benefits remain dependent on successful energisation.
The risk of stranded development capital is consequently more nuanced than a simple calculation of depreciation on unused servers. Assets still under construction may not yet be depreciated, while installed assets that are available for intended use may already be depreciating. The broader economic exposure consists of capital committed to facilities whose expected productive role remains uncertain or delayed. This can include land development, construction work, equipment deposits, engineering expenditure and network infrastructure that has limited alternative value if the original project is subsequently reduced or cancelled.
A distinction must also be made between physically stranded assets and financially stranded commitments. Physical stranding occurs when an asset cannot perform its economically intended function or lacks a viable alternative use. Financial stranding can arise when capital remains contractually committed to a project whose expected returns have deteriorated, even if the physical asset is eventually completed. The latter may occur without the former.
The practical implication is that project-level investment analysis should incorporate not merely the expected energisation date but the probability of achieving that date under relevant development conditions. A nominal commitment to future electricity capacity is not sufficient to establish commercial readiness. The strength of the connection agreement, the maturity of associated network works, equipment procurement and the developer’s ability to meet technical milestones must all be evaluated.
Electricity queue reform as a form of industrial capital allocation
The regulatory treatment of interconnection queues is increasingly consequential because queue position can determine whether an investment programme receives scarce network development resources. A system that allocates capacity according to application timing without adequately distinguishing credible projects from speculative proposals risks immobilising infrastructure planning around developments that may never be completed.
This problem is particularly visible in the United Kingdom, where the energy regulator has begun addressing the growth of speculative data-centre connection requests. On 29 July 2026, Ofgem reported that electricity-demand connection applications had risen from 41 GW to 125 GW in less than a year, with data-centre projects accounting for at least 80 GW of the increase in applications. The regulator proposed a new data-centre commitment fee and additional development milestones intended to distinguish viable projects from applicants unable to demonstrate credible development progress. Ofgem Acts to Free Up Grid Capacity by Tackling Speculative Data Centre Projects — Ofgem — July 2026.
The proposals are important because they convert administrative queue management into an instrument of industrial selection. Ofgem’s consultation requires attention to the credibility of the ultimate electricity consumer, the procurement of long-lead equipment and the financial and technical capacity of the developer. An application supported by substantial financial resources but lacking evidence of equipment procurement or a credible customer may therefore face greater scrutiny than an otherwise comparable project capable of demonstrating readiness. The measures remained proposals awaiting a regulatory decision at the reference date and should not be treated as fully implemented reforms. Proposed Data Centre Connection Reforms — Ofgem — July 2026.
This illustrates a wider shift in infrastructure governance. Electricity-network operators and regulators are increasingly required to distinguish between the speculative reservation of scarce capacity and projects with a credible path to productive operation. In a capital-intensive AI development cycle, that distinction directly influences which companies can convert financial resources into operational computing infrastructure.
A credible reform must nevertheless avoid creating a system in which only existing large companies can satisfy the financial or procurement requirements necessary to retain queue positions. Measures designed to eliminate speculative applications could inadvertently reinforce concentration if their financial burdens exclude viable smaller developers while favouring companies already possessing extensive capital resources and established procurement relationships.
The challenge is therefore to improve the credibility of grid allocation without transforming connection administration into an unnecessary barrier to competitive entry.
Italy: the collision between data-centre demand and electricity-network development
Italy offers a particularly relevant European case because the country’s electricity infrastructure programme must accommodate renewable generation, industrial electrification, growing demand from large electricity consumers and changes in the geographic distribution of electricity flows.
Terna’s 2025–2034 Network Development Plan provides a documented institutional baseline. The plan envisages more than €23 billion of investment across the ten-year period and identifies the reinforcement of the national transmission network as essential to integrating additional renewable generation, increasing electricity-transfer capability and supporting changes in consumption. Crucially, Terna reported approximately 30 GW of data-centre connection requests as of December 2024, an indicator of substantial prospective demand for new electricity connections rather than a forecast of equivalent data-centre consumption becoming operational. National Electricity Transmission Grid Development Plan — Terna — 2025.
The approximately 30 GW figure must not be interpreted as the installed electricity demand of Italian data centres. Applications can include alternative development proposals, projects at different stages of maturity and requests that do not ultimately become operating facilities. Their importance lies in the pressure they place on planning, network studies and the allocation of future infrastructure resources.
Terna’s plan also identifies substantial changes in generation and electricity transfer. It anticipates more than 65 GW of additional renewable capacity by 2030 compared with 2023, while indicating that approximately 43 GW of renewable capacity would need integration into the high-voltage network over a ten-year period. The plan envisages improvements in interzonal transfer capacity, reflecting the need to move electricity between regions with different generation and consumption characteristics. These objectives demonstrate that data-centre development is entering an electricity system already undertaking substantial structural transformation. National Electricity Transmission Grid Development Plan — Terna — 2025.
For Italy, the strategic risk is not merely that a new data-centre project may experience connection delays. It is that poorly coordinated development could introduce additional pressure on network investment programmes intended to serve a broader range of economic and energy-transition objectives. Industrial manufacturing, electrification, renewable integration and digital infrastructure all depend on the availability of reliable electricity transmission and distribution systems. A large computing facility requiring additional network reinforcement therefore competes not necessarily for a fixed national quantity of electricity, but for engineering resources, connection studies, equipment procurement and the timing of specific network investments.
There is also a potential opportunity. Large, financially credible data-centre investments can contribute to the justification of infrastructure reinforcement where their demand profile, location and contractual arrangements support efficient network development. The benefit depends on whether the required works serve a broader system purpose or primarily accommodate a single customer, and on how costs are allocated between the project and the wider electricity system.
The distinction is essential for public policy. Expanding transmission infrastructure can improve national electricity security and industrial competitiveness, but the economic allocation of costs must preserve incentives for efficient site selection and avoid transferring unjustified project-specific expenditure to other electricity users.
Chapter 4 — Key judgments
The latest verified evidence establishes that electricity interconnection is a material industrial constraint on the expansion of AI infrastructure, while also demonstrating why historical generator queues must not be presented as current data-centre demand. The United States had approximately 2,061 GW of generation-and-storage projects in active interconnection queues at the end of 2025, with substantial project attrition and lengthy historical completion periods. European evidence independently confirms the importance of network availability, with the United Kingdom moving towards stricter screening of speculative applications and Italy reporting a substantial volume of data-centre connection requests.
The 18-month financial delay becomes more consequential when physical development schedules are longer than commercial investment assumptions. The associated risk is the prolonged immobilisation of capital and contractual commitments, not necessarily the immediate depreciation of every asset ordered before energisation.
What would change the assessment: More rapid completion of network reinforcement, improved connection allocation, commercially verified energisation and evidence that projects can operate flexibly without compromising network security would reduce the infrastructure constraint. Continued expansion of connection requests without corresponding progress in operating capacity would strengthen it.
Open official record: The most consequential missing evidence is a comparable project-level register linking data-centre connection requests to confirmed capacity, network reinforcement requirements, expected energisation dates and actual commercial operation. Without that information, aggregate connection applications cannot be converted into reliable operating-capacity forecasts.
Chapter 5. From Software Economics to Heavy Industry: Power Equipment, Construction, Cooling and Industrial Dependencies
The emergence of artificial intelligence as an electricity-intensive production system
The industrial transformation of artificial intelligence is changing the composition of demand across sectors that were previously peripheral to the expansion of digital services. Electrical engineering, transformer manufacturing, high-voltage cables, cooling technology, construction materials, power management and grid infrastructure now participate directly in determining the scale and location of computing capacity. The implications extend beyond additional orders for established equipment suppliers. They concern the allocation of manufacturing resources between electricity networks, conventional industry, renewable generation and a new category of computing facilities whose power requirements can resemble those of major industrial installations.
The International Energy Agency’s Energy and AI report of April 2025 estimated global data-centre electricity consumption at approximately 415 terawatt-hours in 2024, representing around 1.5% of global electricity consumption. The United States accounted for approximately 45% of this consumption, China for 25%, and Europe for 15%. The IEA’s central projection at that time envisaged approximately 945 TWh by 2030, reflecting the expected expansion of AI applications alongside continued growth in other digital services.
The scale of this transformation must be interpreted carefully. Data-centre electricity demand remains a relatively limited proportion of global electricity consumption, but its geographic concentration can create disproportionately large local consequences. A significant additional load at a constrained network location may require substantial infrastructure reinforcement even where its contribution to national electricity demand appears modest. The economics of local capacity therefore matter more than the global proportion alone.
The IEA’s updated 2026 assessment provides a more recent reference point. In Key Questions on Energy and AI, the agency estimated that global data-centre electricity consumption reached approximately 485 TWh in 2025, representing an increase of 17% during the year, while electricity consumption from AI-focused facilities increased by approximately 50%. Its revised central projection envisages approximately 950 TWh in 2030, close to the trajectory published in 2025. The agency also reported that the capital expenditure of five major technology companies exceeded $400 billion in 2025, with a further increase expected in 2026. This is an independently defined five-company group and must not be equated with the four-company $725–760 billion scenario envelope.
These figures are important for two reasons. First, they demonstrate that the electricity consequences of AI infrastructure are no longer dependent exclusively on distant investment announcements; substantial growth in consumption has already been observed. Second, they show that the expansion of computing demand is occurring in parallel with improvements in computing efficiency, making future electricity requirements dependent on both the quantity of computation performed and the energy required to perform it.
The latest IEA analysis identifies precisely this tension. Improvements in hardware and software are reducing the energy required for individual AI tasks, while more computationally intensive applications are increasing the quantity and complexity of work performed. The resulting demand for electricity therefore cannot be forecast simply by multiplying the number of AI users by a fixed power requirement. Changes in model architecture, inference patterns, hardware efficiency, utilisation and commercial applications can materially alter the relationship between service growth and electricity consumption.
For industrial planning, this uncertainty creates an asymmetric challenge. Data-centre operators may be able to modify their computing architectures as technology evolves, but electricity networks and major power equipment must be planned, manufactured and constructed over longer periods. An incorrect demand estimate can therefore produce either underinvestment, resulting in connection delays and lost industrial opportunities, or overinvestment, resulting in underutilised network assets and unnecessary costs.
The electricity demand baseline and its industrial interpretation
| Indicator | Value | Reference period | Interpretation |
|---|---|---|---|
| Global data-centre electricity consumption | 415 TWh | 2024 | IEA estimate of annual consumption |
| Share of global electricity consumption | Approximately 1.5% | 2024 | Global average; does not capture local concentration |
| United States share | 45% | 2024 | Share of worldwide data-centre electricity consumption |
| China share | 25% | 2024 | Same geographic metric |
| Europe share | 15% | 2024 | Same geographic metric |
| Global data-centre electricity consumption | 485 TWh | 2025 | Updated IEA estimate |
| Annual increase in total data-centre consumption | 17% | 2025 | Observed year-on-year growth |
| Annual increase in AI-focused data-centre consumption | Approximately 50% | 2025 | AI-specific growth, not growth of all data centres |
| Central electricity-demand projection | Approximately 950 TWh | 2030 | IEA forecast, not commissioned capacity |
| Planned projects potentially exposed to grid-related delay | Approximately 20% | IEA 2025 assessment | Conditional estimate dependent on unresolved risks |
| Transmission-line development | 4–8 years | IEA 2025 assessment | Typical infrastructure development range in advanced economies |
Sources: Energy and AI — International Energy Agency — April 2025; Key Questions on Energy and AI — International Energy Agency — 2026.
The comparison demonstrates why the physical infrastructure associated with artificial intelligence must be assessed within the electricity sector rather than exclusively within the technology industry. Annual electricity consumption is a measure of energy used over time, whereas a connection request expressed in gigawatts represents a nominal power requirement. The two cannot be directly compared without assumptions about utilisation, operating patterns and the relationship between peak and average demand.
This distinction is particularly relevant to the concentration of AI workloads. A computing facility may require the electrical infrastructure necessary to accommodate a high level of simultaneous power consumption while operating below that level during parts of the year. Conversely, facilities running continuously at high utilisation can impose sustained demand on generation and transmission systems. The network must accommodate operating characteristics relevant to its security requirements, not merely annual energy consumption divided by time.
The industrial implications are consequently determined by power density, continuity of demand, operational flexibility and geographic location. A portfolio of smaller, geographically distributed computing facilities may produce different network requirements from a highly concentrated campus with equivalent aggregate annual consumption.
The transformer as a strategic industrial asset
Transformers occupy a particularly important position within the physical infrastructure of AI because they connect electricity systems operating at different voltage levels. Large computing facilities may require electricity delivered through transmission or high-voltage distribution networks, followed by transformation and distribution within the site. This creates demand for equipment whose engineering requirements differ substantially from those of the computing hardware installed in server halls.
Transformer manufacturing is not a purely standardised commodity activity. Equipment specifications depend on voltage requirements, capacity, cooling, insulation, network protection and operating conditions. Large units may require specialised manufacturing facilities, testing capabilities, transportation planning and installation procedures. The underlying supply chain includes electrical steel, conductor materials, insulation systems, mechanical components and engineering services.
The resulting manufacturing constraint is difficult to resolve simply by increasing purchase orders. Where producers operate specialised manufacturing lines, additional output may depend on expanding production capacity, obtaining materials, training qualified personnel or securing new equipment. Large transformers also require technical validation and coordination with the electricity system into which they will be installed.
This is why the availability of transformer manufacturing capacity becomes important to data-centre development even where the computing equipment itself is already financed and ordered. A facility requiring an additional substation may depend on equipment whose procurement schedule is linked to industrial manufacturing capacity rather than to semiconductor production.
The issue extends to the design of electricity networks. An electricity-system operator cannot automatically substitute one transformer for another merely because both are nominally capable of carrying comparable electrical loads. Differences in voltage, impedance, protection coordination, physical dimensions and other technical characteristics may determine whether a particular unit is suitable for the intended installation.
The strategic value of transformer manufacturing therefore lies not only in production volume but also in engineering expertise, testing infrastructure, conformity assessment, servicing capability and the ability to deliver equipment compatible with specific electricity networks.
Switchgear, protection systems and the reliability architecture of computing facilities
Transformers alone do not establish a functioning electricity connection. Switchgear, circuit breakers, protective relays, busbars, control systems and related electrical equipment are required to manage power flows, isolate faults and maintain safe operating conditions. Their role becomes particularly consequential in data centres because the economic cost of an electricity interruption may be substantial even when the interruption does not create permanent physical damage.
The engineering requirement extends beyond purchasing equipment that can accommodate the nominal electrical load. Protection systems must operate coherently with the upstream network and downstream facility. Fault-clearing capabilities, redundancy arrangements, maintenance requirements and operational monitoring must be integrated into the overall installation.
A supply shortage in switchgear can therefore delay a project whose transformer, building and computing equipment have otherwise been delivered. Similarly, a shortage of qualified engineering personnel or testing capacity can postpone commissioning after the physical equipment is installed.
The industrial significance is that AI infrastructure creates demand not only for electrical components but for integrated systems engineering. Manufacturing capacity and commissioning expertise become complementary production factors. An operator may obtain equipment at a competitive price but still experience substantial delay if installation, testing or network acceptance cannot be completed.
The United Kingdom’s 2026 regulatory consultation provides an unusually direct institutional confirmation of the importance of this manufacturing chain. Ofgem proposed that data-centre developers demonstrate progress in procuring long-lead electrical equipment, explicitly identifying switchgear as an example, when seeking to retain their positions in electricity-connection queues. The regulator thus incorporated equipment procurement into its assessment of whether a project is commercially and technically credible. Proposed Data Centre Connection Reforms — Ofgem — July 2026.
This development illustrates a broader consequence of AI infrastructure expansion: manufacturing procurement, previously treated primarily as a downstream construction activity, can become relevant to the allocation of scarce network capacity itself.
Power cables and the emerging competition for electrical materials
Power cables represent another critical interface between computing facilities and electricity systems. The relevant market includes equipment for transmission, distribution and internal electrical installations, with substantial differences in voltage, insulation, installation requirements and operating environment. Cables intended for major transmission projects cannot necessarily be substituted with products designed for lower-voltage industrial distribution.
The additional demand associated with AI infrastructure therefore interacts with broader investment in transmission expansion, renewable generation, industrial electrification and network resilience. These activities can compete for specialised manufacturing capacity even when the final applications differ.
The availability of cables is determined by more than the quantity of conductor metal. Manufacturing capability, insulation technology, product qualification, testing and installation expertise are also important. For certain projects, cable routes, construction permits and civil engineering can be as consequential as the manufacturing lead time of the cable itself.
This distinction matters for Europe because domestic industrial capabilities are distributed across different parts of the value chain. A country may possess substantial cable manufacturing capacity but remain dependent on imported materials or equipment used in production. Another may possess engineering and installation expertise while relying more heavily on imported finished electrical products.
A procurement policy that considers only the nationality of the final equipment supplier can therefore misrepresent the actual degree of supply-chain dependence. The relevant analysis must identify critical materials, intermediate products, specialised manufacturing processes, testing capabilities and maintenance requirements.
The economic effects of price competition also differ along this chain. Lower costs for imported raw materials or intermediate components can improve the competitiveness of European finished-equipment manufacturers. Lower prices for imported finished products may instead place more direct pressure on European producers. The industrial outcome depends on where substitution occurs and whether the imported product complements or displaces domestic manufacturing.
Cooling infrastructure and the changing engineering requirements of computing density
Cooling is another area in which AI infrastructure differs materially from conventional software economics. Electricity supplied to computing hardware is converted into useful computational work and heat, requiring systems capable of maintaining operating conditions within the technical limits of the equipment.
As computing density increases, the design of cooling systems becomes more closely integrated with computing architecture. Air-based cooling arrangements, liquid-cooling systems, heat exchangers, pumps, distribution equipment and facility-level thermal management can differ substantially in their equipment requirements and operational characteristics.
These systems create industrial demand for mechanical engineering, manufacturing, installation and operational maintenance. They also affect the overall electricity requirement of a facility, since energy is consumed not only by computing equipment but also by cooling and supporting systems.
The selection of cooling technology is therefore an economic and engineering decision rather than a peripheral facilities-management issue. A more efficient cooling arrangement may reduce operating energy consumption or support higher computing density, but its financial attractiveness depends on installation costs, maintenance requirements, reliability and compatibility with the hardware being deployed.
The interaction with electricity availability is particularly important. Improving cooling efficiency can increase the amount of computing capacity supported by a given electrical connection, potentially postponing the need for additional network capacity. However, such improvements cannot be assumed to eliminate the need for grid reinforcement where total computing demand expands sufficiently.
Cooling also introduces geographic considerations. Local climate, water availability, environmental requirements and opportunities for heat recovery can influence both engineering design and site economics. These factors may favour particular locations or require additional infrastructure, although their significance must be assessed through project-specific evidence rather than a uniform assumption about data centres.
The industrial implication is that computing density increasingly connects the semiconductor industry to mechanical engineering, electricity-system design and environmental infrastructure.
Construction, commissioning and the scarcity of integrated industrial execution
The development of a large AI campus requires the coordination of several industrial processes whose schedules do not necessarily align. Civil engineering, building construction, electrical installation, cooling systems, internal networks, equipment testing and external grid reinforcement must converge before the facility can operate commercially.
The challenge is not simply the availability of enough construction workers or contractors. Technical competence in high-voltage systems, specialised electrical installation, commissioning and systems integration can determine whether otherwise completed infrastructure becomes usable.
This creates a distinction between manufacturing capacity and delivered operational capacity. A transformer delivered to a site is not equivalent to an energised substation. Installed switchgear is not equivalent to an accepted protection system. A completed cooling installation is not evidence that the facility can maintain required thermal conditions under commercial operating loads.
The process requires coordination among the data-centre operator, engineering contractors, equipment suppliers, electricity-system operators and potentially public authorities. Each participant controls different aspects of project completion, making integrated scheduling and contractual accountability important.
This industrial structure also affects risk allocation. A hyperscaler can procure equipment and contract construction work, but it may not directly control the timing of external transmission investment or regulatory authorisation. Responsibility for delays therefore depends on the contracts and institutional arrangements governing each project.
The distinction becomes more significant as infrastructure investment expands geographically. Multiple projects may simultaneously compete for specialised contractors, equipment-manufacturing slots and qualified commissioning personnel. The resulting constraint can persist even when the underlying financial resources are available.
The emerging industrial value chain of AI infrastructure
| Industrial segment | Principal equipment or capability | Role in AI infrastructure | Potential supply constraint | European industrial implication |
|---|---|---|---|---|
| Electrical steel | Grain-oriented electrical steel and processed cores | Transformer magnetic circuits | Production capacity and import competition | Strategic upstream manufacturing exposure |
| Power transformers | High-voltage and distribution transformers | Voltage transformation and electricity delivery | Specialised production, testing and transportation | Demand for domestic engineering and manufacturing |
| Switchgear | Breakers, switches, protection and control equipment | Safe connection and network operation | Manufacturing lead times and qualification | Strong relevance to electrical-equipment suppliers |
| Power cables | Transmission, distribution and internal electrical cables | Transfer of electricity between infrastructure systems | Specialised production and installation | Opportunities and import-substitution pressure |
| Power conversion | Electrical conversion and power-conditioning equipment | Delivery of electricity suitable for computing systems | Component availability and systems integration | Demand for power-electronics capabilities |
| Backup and resilience | Backup generation, storage and related controls | Continuity and resilience of critical operations | Equipment, fuel and operating requirements | Infrastructure and engineering opportunities |
| Cooling systems | Heat exchangers, pumps and thermal management | Removal and management of computing heat | Manufacturing and installation complexity | Mechanical-engineering opportunities |
| Buildings and civil works | Structural facilities and site infrastructure | Housing and protecting computing installations | Construction execution and site constraints | Domestic construction and engineering demand |
| Grid engineering | Network studies, substations and protection design | Integration into the electricity system | Qualified personnel and project coordination | Strategic technical competence |
| Testing and commissioning | Electrical and mechanical acceptance | Conversion of installed equipment into usable capacity | Specialist expertise and operational integration | Higher-value engineering services |
| Industrial maintenance | Spare parts, servicing and technical support | Long-term operational reliability | Supplier access and component compatibility | Lifecycle dependence on industrial suppliers |
This classification identifies the functional relationships within the infrastructure chain. It does not assign unsupported market shares, prices or manufacturing capacities to individual countries or companies.
Why industrial sovereignty cannot be measured by semiconductor access alone
The geopolitical discussion surrounding artificial intelligence has frequently concentrated on semiconductor production, advanced computing equipment and model development. These activities remain critical, but the physical development of AI infrastructure demonstrates why technological capability does not automatically translate into operational industrial capacity.
A country may possess access to sophisticated computing equipment yet lack sufficient electricity-network capacity to deploy it at the desired scale. It may have adequate electricity generation but depend on imported transformers or switchgear whose delivery schedules postpone new infrastructure. It may finance major projects while lacking the specialised engineering and commissioning capabilities required to complete them efficiently.
The resulting dependency structure is cumulative. Shortages in one critical component or capability can delay the productive use of resources already committed elsewhere in the chain.
For Europe, this implies that industrial competitiveness in AI should not be evaluated solely through investment in computing facilities or access to advanced processors. The capacity to manufacture, maintain and upgrade the electrical and mechanical systems supporting those facilities has become part of the broader technological and industrial position.
This does not imply that every European country must manufacture every component domestically. Such a requirement would disregard the advantages of international specialisation and could raise infrastructure costs unnecessarily. It does imply that critical dependencies should be identified explicitly and assessed according to their substitutability, supply concentration, delivery requirements and strategic consequences.
The distinction between domestic production and supply-chain resilience is particularly important. A diversified international supply network can be resilient without being entirely domestic, while a nominally domestic manufacturing process can remain vulnerable if indispensable intermediate materials or technical capabilities are controlled by a limited number of external suppliers.
Chapter 5 — Key judgments
The expansion of AI infrastructure is creating a new industrial demand system in which electrical equipment, cooling, construction and integrated engineering are central determinants of computing capacity. The documented growth in data-centre electricity consumption demonstrates that this transition is already affecting energy systems, while the longer development cycles of physical infrastructure create constraints that cannot be resolved through financial expenditure alone.
The most strategically important industrial capabilities are not necessarily those associated with the highest equipment prices. They are the components and services whose absence can prevent an otherwise completed facility from operating. Transformers, switchgear, cables, network engineering and commissioning capacity can therefore exercise disproportionate influence over investment timelines.
The European opportunity lies in supplying these systems while preserving the manufacturing and engineering capabilities needed for future electricity-network development. The corresponding vulnerability lies in allowing essential industrial dependencies to become concentrated in external supply chains whose availability or pricing may not remain favourable.
What would change the assessment: Evidence of sustained reductions in equipment lead times, expanding manufacturing capacity, improved project commissioning and technological designs that require less additional network infrastructure would reduce the severity of the industrial bottleneck. Increasing supplier concentration or repeated equipment-related project delays would strengthen it.
Open official record: Product-specific manufacturing capacity, delivery times, equipment-import exposure and qualified installation capacity are not consistently reported across European jurisdictions. These data are necessary to distinguish actual production shortages from procurement, logistics or project-management delays.
Chapter 6. Chinese Industrial Overcapacity and the European Equipment Market: Price Transmission, Import Substitution and Strategic Exposure
The collision between China’s industrial capacity and Europe’s infrastructure investment requirements
The relationship between Chinese industrial overcapacity and European electricity infrastructure is becoming a consequential element of the international economic competition surrounding artificial intelligence. The mechanism is not confined to the displacement of European manufacturers by lower-priced imported goods. It involves the simultaneous possibility that additional supply reduces the cost of essential infrastructure equipment, accelerates investment in electricity networks and weakens the domestic productive capabilities on which future European infrastructure development may depend. The resulting policy problem is particularly complex because the interests of equipment manufacturers, electricity-network operators, industrial consumers and public authorities do not necessarily coincide.
China’s manufacturing position must be assessed by product and supply-chain segment rather than through a general assumption that every category of electrical equipment is subject to the same degree of excess capacity. A sustained increase in Chinese exports of electrical steel does not by itself establish equivalent overcapacity in finished transformers, high-voltage switchgear or specialised power cables. These products differ in manufacturing complexity, certification requirements, transportation costs, commercial specifications and the extent to which European buyers can substitute imported equipment for established suppliers.
The most concrete evidence concerns grain-oriented electrical steel, an indispensable input for the magnetic cores of power transformers. On 27 March 2026, the European Commission initiated a safeguard investigation into imports of certain grain-oriented flat-rolled electrical steel products and related laminations and cores. The Commission explicitly identified increasing import pressure, particularly involving China, and linked the problem to expanding production capacity in third countries and global overcapacity. The investigation reflected concern that import growth could cause serious injury to an industrial segment important to Europe’s electricity infrastructure. Commission Initiates Safeguard Investigation into Imports of Grain-Oriented Electrical Steel — European Commission — March 2026.
The official evidence provides a quantitative basis for assessing the magnitude of the trade pressure. According to the Commission’s March 2026 notice, imports of the electrical steel products covered by the investigation increased from 91,362 tonnes in 2021 to 191,056 tonnes during the period July 2024–June 2025, an increase of approximately 109%. Imports of the relevant steel laminations and cores increased from 33,163 tonnes to 60,334 tonnes, corresponding to approximately 82%. These figures concern the specified product categories and reporting periods, not the entire European market for electrical equipment. They are nevertheless substantial enough to demonstrate that the Commission’s concerns were linked to observable changes in trade volumes rather than exclusively to prospective geopolitical risks. Notice of Initiation of a Safeguard Investigation Concerning Imports of Certain Grain-Oriented Flat-Rolled Products of Silicon-Electrical Steel — Official Journal of the European Union — March 2026.
The situation subsequently evolved from investigation to provisional intervention. On 18 September 2026, the European Commission imposed provisional safeguard measures in the form of tariff-rate quotas combined with price thresholds. The measures covered electrical steel and extended to laminations and cores used in transformer manufacturing, including relevant cores incorporated into transformers. The Commission stated that urgent action was necessary to protect a strategic European industry exposed to high import pressure associated with global overcapacity and the closure of traditional export markets. Commission Imposes Provisional Safeguard Measures on Imports of Grain-Oriented Electrical Steel — European Commission — September 2026.
This sequence is significant because it demonstrates that the geopolitical problem is no longer limited to the possibility of future industrial displacement. European institutions have already intervened in a product category directly connected to the manufacture of power transformers, one of the critical equipment classes required for electricity-network expansion.
The policy dilemma is nevertheless more complicated than a straightforward argument for protecting European production. Transformer manufacturers purchase electrical steel and related components as industrial inputs. Measures that support upstream European steel producers can influence downstream manufacturing costs, particularly where domestic supply is insufficient, specialised product requirements restrict substitutability or imported inputs offer a commercial advantage. The Commission’s original investigation explicitly recognised the importance of considering the interests of transformer manufacturers, demonstrating that industrial protection and infrastructure affordability may pull policy in different directions.
The documented change in European import exposure
| Product category | Earlier import volume | Later import volume | Reported change | Industrial significance |
|---|---|---|---|---|
| Grain-oriented electrical steel | 91,362 tonnes | 191,056 tonnes | +109% | Critical material for transformer magnetic cores |
| Steel laminations and cores | 33,163 tonnes | 60,334 tonnes | +82% | Processed components used in transformers and inductors |
| Reference periods | 2021 | July 2024–June 2025 | Different reporting periods | Comparison used in Commission investigation |
| Provisional safeguard intervention | Not applicable | Adopted 18 September 2026 | Tariff-rate quotas and price thresholds | Trade-policy intervention affecting specified electrical-steel products |
Source: Notice of Initiation of Safeguard Investigation — Official Journal of the European Union — March 2026; Provisional Safeguard Measures on Grain-Oriented Electrical Steel — European Commission — September 2026.
The figures must be interpreted with particular care. The initial and final periods differ in their calendar definition, although they are the periods used by the Commission in its reported comparison. The measured increase refers to imports from the relevant external suppliers collectively and must not be misrepresented as an equivalent increase in Chinese imports alone. China’s role is identified in the Commission’s assessment of import pressure and global overcapacity, but a precise decomposition of the reported growth by country of origin requires the underlying customs data.
The distinction matters because trade policy should respond to the documented structure of import competition rather than assume that all external supply originates from a single country. The commercial consequences also depend on whether imports substitute for European production, satisfy demand that European producers cannot meet or provide intermediate inputs to downstream manufacturers.
How Chinese overcapacity transmits into European equipment prices
The first potential transmission channel is a reduction in the price of imported industrial equipment or intermediate materials. Where Chinese production capacity exceeds commercially sustainable domestic demand, manufacturers may seek additional export markets. If the resulting supply enters Europe at prices below those available from existing suppliers, European buyers can experience lower acquisition costs and stronger bargaining power.
For electricity-network operators, this outcome may initially appear favourable. Transformers, switchgear, cables and related equipment are significant components of infrastructure procurement. Lower acquisition prices can reduce the cost of particular investment projects, potentially allowing infrastructure developers to undertake additional work within established financial limits.
For data-centre developers, the effect could be similar. Lower equipment prices may reduce the expenditure required to build substations, internal electrical systems and associated facilities. This could improve the economics of projects whose viability is sensitive to infrastructure costs.
However, the relationship between imported prices and completed project costs is not one-to-one. The final cost of an electricity infrastructure project also includes engineering, construction, transportation, installation, testing, permitting and operational integration. A reduction in the purchase price of one component does not necessarily produce an equivalent reduction in total investment expenditure.
There is also a difference between equipment price and equipment availability. An imported transformer offered at a lower price may not accelerate a project if its technical specifications are unsuitable, certification remains incomplete or manufacturing and transportation schedules exceed the project’s requirements. Conversely, competitively priced equipment that satisfies the required standards and can be delivered reliably may materially improve project execution.
The principal economic benefit of import competition therefore depends on the delivered and operationally usable cost of the equipment, rather than its nominal purchase price alone.
This concept includes compatibility with European networks, conformity with applicable technical requirements, installation arrangements, maintenance availability and the economic consequences of potential delays. A procurement decision based solely on upfront acquisition cost can underestimate lifecycle expenditure and operational dependency.
The second transmission channel: pressure on European manufacturing margins
The corresponding risk arises when lower-priced imports reduce the profitability of European manufacturers producing comparable goods. Industrial producers must recover expenditure associated with manufacturing facilities, engineering, skilled labour, quality assurance and technological development. Where sustained import competition reduces prices below levels consistent with commercially viable domestic production, manufacturers may respond by reducing investment, consolidating operations or withdrawing from selected product categories.
The consequences can extend beyond immediate employment or profitability. Electrical-equipment manufacturing depends on accumulated technical capability, specialised machinery, supplier relationships and workforce expertise. Once a manufacturing activity contracts substantially, restoring it may require considerable capital investment, renewed training and the reconstruction of supplier networks.
This creates a potential temporal mismatch between commercial benefits and industrial costs. European infrastructure buyers may benefit immediately from lower imported-equipment prices, while the consequences of diminished domestic manufacturing capacity become visible only when future demand increases, international supply conditions change or replacement equipment is required.
Such an outcome is particularly relevant in an industry where equipment is expected to operate reliably over extended periods and maintenance requirements remain important after installation. The economic significance of domestic manufacturing is not limited to the original purchase. It includes the availability of replacement components, technical support, engineering expertise and the capacity to adapt infrastructure to changing system requirements.
The European Commission’s electrical-steel intervention reflects this concern. Its September 2026 measures were intended to address the risk that import pressure could damage a strategic upstream industrial capability. By extending the scope to processed cores and certain cores incorporated into transformers, the Commission sought to address the possibility that protection confined to an intermediate material could be undermined by a shift towards imports of products further along the manufacturing chain. Commission Imposes Provisional Safeguard Measures on Imports of Grain-Oriented Electrical Steel — European Commission — September 2026.
This is an important feature of modern industrial trade policy. Protection directed at one production stage may alter incentives elsewhere in the supply chain. If imported intermediate materials become more expensive while imported finished products remain comparatively inexpensive, domestic downstream manufacturers can face an adverse competitive relationship. Policymakers must therefore examine substitution across adjacent production stages rather than evaluating individual customs categories in isolation.
The third transmission channel: supplier dependence and industrial irreversibility
A temporary period of favourable import prices may induce European buyers to concentrate procurement among suppliers offering the lowest immediate costs. Such decisions are commercially rational where products are comparable and supply is dependable. They become strategically problematic when the resulting concentration reduces the number of viable suppliers, diminishes domestic technical capabilities or creates dependencies that cannot be reversed within the required operational timeframe.
The distinction between price dependence and technical dependence is important. Price dependence occurs when buyers become economically reliant on a source of supply because alternatives are more expensive. Technical dependence arises when equipment specifications, maintenance arrangements or component compatibility restrict the practical ability to change suppliers.
For critical electricity infrastructure, technical dependence can be particularly consequential. An operator may be able to purchase replacement equipment from another country in principle while facing significant difficulties integrating it into an existing installation without additional engineering or modification.
This does not imply that imported Chinese equipment is inherently unsuitable or that international procurement should be avoided. The relevant strategic concern is the concentration of capabilities and the cost of substitution under adverse conditions.
A resilient procurement structure may involve several qualified suppliers, sufficient technical documentation, access to maintenance services and the ability to obtain compatible replacement components. The objective is not absolute domestic self-sufficiency but the preservation of credible alternatives.
The potential vulnerability becomes more serious when prolonged import competition has reduced the capacity of European manufacturers to supply those alternatives. At that point, a future change in international trade conditions can create a problem that cannot be solved rapidly through procurement alone.
The resulting exposure is cumulative: lower import prices can encourage substitution, substitution can weaken alternative production capacity, and the reduction of alternatives can increase the strategic importance of the remaining suppliers.
Equipment-specific exposure: where substitution creates benefits and where vulnerability increases
The effects of Chinese manufacturing competition cannot be assessed through a uniform judgment covering all electrical equipment. Different product categories occupy different positions in the infrastructure chain, and their strategic importance depends on technical substitutability, manufacturing concentration and the availability of qualified suppliers.
| Equipment category | Potential benefit from import competition | Potential European manufacturing exposure | Strategic concern | Evidence status |
|---|---|---|---|---|
| Grain-oriented electrical steel | Lower prices for transformer inputs | Direct competition with EU electrical-steel producers | Loss of upstream transformer-material capacity | Documented import growth and provisional EU safeguards |
| Transformer laminations and cores | Lower cost of processed components | Pressure on EU intermediate manufacturers | Import substitution along successive production stages | Covered by Commission investigation and safeguards |
| Power transformers | Potential procurement savings | Competition for European finished-equipment producers | Qualification, maintenance and alternative supply | Conditional broader-market exposure |
| High-voltage switchgear | Potential cost reductions and additional supply | Competition for electrical-equipment manufacturers | Technical compatibility and delivery reliability | Product-specific trade diversion not established |
| Power cables | Potential lower material and equipment costs | Pressure on relevant cable manufacturing segments | Supply continuity and technical qualification | Product-specific trade diversion not established |
| Electrical protection equipment | More sourcing alternatives where standards permit | Competition for specialised manufacturers | Systems integration and maintenance support | Conditional |
| Power conversion systems | Potential reduction in project equipment costs | Competitive pressure on European power-electronics suppliers | Component supply and technical integration | Conditional |
| Cooling equipment | Lower imported mechanical-equipment costs | Competition for equipment manufacturers | Maintenance and lifecycle support | Conditional |
The table distinguishes documented regulatory evidence from plausible economic mechanisms that require further product-level verification. The available official record supports a substantial conclusion regarding electrical steel and transformer-core inputs. It does not justify asserting equivalent Chinese overcapacity, export growth or price reductions across every other equipment category.
Italy: the strategic interaction between industrial equipment supply and national grid investment
Italy’s exposure is particularly significant because its electricity-network development programme requires substantial industrial equipment and engineering services while the country also possesses manufacturing capabilities relevant to electrical infrastructure. The national interest cannot therefore be defined exclusively from the standpoint of equipment buyers or equipment producers.
The Terna 2025–2034 Network Development Plan envisages more than €23 billion of investment in transmission infrastructure. The programme is intended to support renewable integration, system resilience and changes in electricity demand and power flows. This establishes a substantial infrastructure-investment baseline against which international equipment-price competition becomes economically relevant.
If imported industrial equipment becomes less expensive while satisfying the required technical and operational standards, selected investments could become less costly. This may benefit the electricity system and ultimately support industrial consumers, depending on procurement outcomes, regulatory cost recovery and the extent to which lower equipment prices translate into completed projects.
However, Italy’s industrial exposure extends beyond the cost of network reinforcement. Domestic electrical engineering, cable manufacturing, equipment installation and maintenance activities depend on a functioning European industrial ecosystem. Competitive pressure on upstream manufacturers elsewhere in Europe can affect Italian firms even where the immediate imported product does not directly displace an Italian finished-equipment manufacturer.
The relationship is especially important in transformer manufacturing. Electrical steel and processed magnetic cores are intermediate inputs whose price and availability influence downstream production economics. Italian industrial firms that purchase these materials may benefit from lower input costs, while European upstream suppliers may experience competitive pressure. Restrictive trade measures can protect the latter but also affect the costs of the former.
An industrial strategy that treats these interests as identical risks producing unintended consequences. Protecting one production stage without considering downstream competitiveness can shift costs within the same European value chain rather than improve its overall resilience.
Italy’s interest therefore lies in preserving a diversified supply of strategic materials while ensuring that domestic engineering and manufacturing capabilities remain competitive. The policy question is not simply whether a particular component should be imported, but whether the cumulative pattern of imports and domestic investment preserves the capacity to construct, operate, maintain and upgrade critical infrastructure over time.
The geographical organisation of Italian electricity demand adds another dimension. Large new data-centre projects can increase demand for network reinforcement in areas where industrial activity, electricity infrastructure and other large consumers are already concentrated. The economic benefit of lower imported-equipment costs must therefore be evaluated alongside the actual ability to complete projects, the availability of connection capacity and the consequences for other industrial electricity users.
An inexpensive imported component that arrives after the project’s critical commissioning date may provide less economic value than a more expensive alternative available within the required schedule. Conversely, reliable imported supply may prevent delays where domestic production capacity is insufficient.
The Italian procurement problem is consequently one of total infrastructure productivity, not merely unit equipment prices.
France: electricity-system capacity and the competitiveness of industrial equipment procurement
France’s industrial exposure differs because the interaction between data-centre development and electricity availability must be evaluated within a national electricity system whose characteristics are not identical to those of Italy or Germany.
The relevant competitive question is whether the development of additional computing infrastructure can be coordinated with reliable electricity delivery and network reinforcement while preserving the economic viability of manufacturing activities that depend on those systems.
French industrial buyers may benefit from internationally competitive equipment prices, particularly where new electrical infrastructure is required. Domestic and European equipment producers, however, may face reduced margins if imported products compete directly with their existing output.
The strategic problem resembles that confronting other European economies, but the allocation of costs and benefits depends on the national electricity system, industrial demand and procurement structure.
A policy favouring lower infrastructure procurement costs could improve the economics of selected electricity investments. Yet a sustained deterioration in European equipment manufacturing could weaken the broader industrial capabilities available to French utilities, industrial consumers and infrastructure developers.
The resulting issue is not whether French electricity supply is inherently sufficient or insufficient for future AI development. That conclusion would require project-specific evidence concerning available network capacity, load location and connection schedules. The relevant strategic judgment is that access to dependable electricity and equipment procurement increasingly influence the ability to translate computing investment into productive capacity.
Germany: industrial competitiveness and the pressure of imported capital goods
Germany faces the same trade-off within an industrial structure where manufacturing competitiveness is especially sensitive to the cost and reliability of electricity and capital equipment.
Lower-priced imported electrical components can improve the economics of infrastructure investment and reduce costs for downstream users. At the same time, competition from lower-priced imports may weaken European suppliers whose products form part of the capital-equipment systems supporting German manufacturing.
The strategic distinction concerns the relative economic effects on producers and users. Manufacturers purchasing electrical equipment may benefit from lower procurement costs, while firms producing competing equipment may face declining margins. These effects can occur simultaneously within the same industrial economy.
The interaction becomes more consequential when infrastructure investment is expanding. A reduction in domestic manufacturing capacity during a period of substantial grid development can increase future import dependence, particularly where the affected products require specialised engineering or long-term maintenance.
Germany’s industrial interest therefore cannot be reduced to protecting domestic producers irrespective of cost. It is to maintain a competitive manufacturing system capable of accessing necessary equipment while preserving critical technical capabilities and alternatives to concentrated external supply.
The economic quality of procurement decisions must be evaluated across the lifecycle of the equipment and the consequences for industrial capacity rather than exclusively through the initial purchase price.
United Kingdom: connection reform and the industrial significance of equipment availability
The United Kingdom provides a distinct example because the regulator has connected the credibility of data-centre projects directly to the procurement of long-lead electrical equipment.
The July 2026 Ofgem consultation does not merely address abstract electricity-demand projections. It proposes milestones requiring developers to demonstrate concrete progress, including evidence concerning equipment procurement, commercial customers and the technical and financial capacity to complete facilities. Proposed Data Centre Connection Reforms — Ofgem — July 2026.
This approach illustrates how industrial equipment supply can become part of the regulatory infrastructure-allocation process. A developer unable to demonstrate credible procurement may face difficulties retaining a connection position, even if it possesses substantial financial resources or a commercially attractive location.
The implications for international competition are considerable. Manufacturers capable of providing reliable delivery commitments, appropriate technical specifications and supporting documentation may obtain a competitive advantage that exceeds the importance of nominal equipment prices.
The United Kingdom’s policy challenge is therefore to distinguish credible project development from speculative capacity reservation without unnecessarily favouring incumbent companies or limiting the range of qualified equipment suppliers.
The broader economic consequence is that procurement reliability and technical execution can become determinants of market access in the data-centre industry.
The European Union’s industrial-policy dilemma: affordability, resilience and competition
The European Union faces a collective coordination problem because electricity infrastructure and industrial manufacturing are connected through a value chain extending across multiple national economies. An upstream producer in one member state may supply transformer manufacturers in another, while the finished equipment may be installed in a third. Trade measures affecting intermediate products can therefore redistribute costs and competitive advantages across borders.
The electrical-steel safeguard illustrates the dilemma in unusually concrete form. The Commission’s provisional intervention seeks to protect an upstream manufacturing capability considered important to European energy infrastructure. Yet transformer manufacturers must continue obtaining suitable inputs at commercially viable prices. Measures that preserve domestic material production while substantially weakening downstream equipment manufacturers would not necessarily improve the resilience of the overall supply chain.
The appropriate industrial objective is therefore broader than the maintenance of production in a single product category. It concerns the ability of the European electricity-equipment ecosystem to supply strategically important infrastructure at competitive prices and within operationally acceptable delivery schedules.
This requires distinguishing between several different market failures. Predatory or injurious import competition is not identical to ordinary price competition. A shortage of domestic production capacity is not identical to dependence on a single external supplier. Technical non-substitutability is not identical to commercial preference for an established manufacturer. Each problem requires a different policy response.
Trade-defence instruments may be relevant where the applicable legal requirements are satisfied and documented import pressure threatens domestic producers. Industrial investment may be necessary where manufacturing capacity is structurally insufficient. Procurement diversification may be more appropriate where supply concentration creates vulnerability without evidence of unlawful trade practices. Technical standardisation and interoperability may reduce the costs of changing suppliers.
The relationship between these interventions must be assessed carefully. A trade measure can alter prices but cannot by itself create new manufacturing capacity or guarantee timely equipment delivery. A subsidy can encourage industrial investment but does not automatically produce competitive manufacturing or reliable long-term demand. Procurement diversification can reduce exposure to individual suppliers but may introduce complexity or higher operating costs.
The strategic objective is therefore the preservation of viable industrial alternatives rather than the elimination of international competition.
The four principal European transmission mechanisms
| Transmission channel | Immediate mechanism | Potential economic benefit | Potential strategic cost | Relevant public authority or commercial actor |
|---|---|---|---|---|
| Import-price competition | Additional foreign supply reduces prices | Lower infrastructure-equipment procurement costs | Pressure on domestic producers | Equipment buyers, manufacturers, trade authorities |
| Upstream material substitution | Imported electrical steel or cores replace European supply | Lower input costs for downstream production | Loss of strategic intermediate manufacturing | European Commission, material and transformer producers |
| Finished-equipment substitution | Imported transformers, cables or switchgear replace domestic products | Greater procurement choice | Increased reliance on external equipment supply | Utilities, data-centre developers, manufacturers |
| Supply concentration | Procurement shifts towards fewer external suppliers | Potential short-term economies of scale | Reduced substitutability and future bargaining power | Infrastructure operators and industrial buyers |
| Trade-defence intervention | Duties, quotas or price thresholds affect imports | Potential protection of domestic capacity | Higher input costs or downstream competitive effects | European Commission and member states |
| Manufacturing investment | Additional domestic production capacity | Greater supply resilience and industrial employment | Capital intensity and commercial execution risk | Industrial firms, national governments, EU institutions |
| Technical diversification | Multiple qualified suppliers and interchangeable systems | Lower disruption risk | Qualification and integration costs | Equipment purchasers and network operators |
These mechanisms are connected but should not be treated as evidence that a single outcome is inevitable. Lower imported prices may increase European infrastructure investment without significantly displacing domestic manufacturing where demand exceeds available production. Conversely, persistent import competition may weaken strategically important producers even where the short-term procurement benefits are substantial.
The implications for European infrastructure costs and industrial investment
The broader macroeconomic consequence depends on whether the European equipment market experiences a temporary adjustment in prices or a more persistent shift in manufacturing competitiveness.
In the first case, increased import competition may reduce selected equipment costs while European manufacturers remain commercially viable and capable of investment. Electricity-network operators and data-centre developers could benefit from a broader supplier base, while competition encourages greater efficiency across the manufacturing sector.
In the second case, sustained price pressure could undermine the profitability of European producers and discourage investment in additional manufacturing capacity. The immediate reduction in infrastructure procurement costs might then be followed by a deterioration in domestic supply options and increased dependence on external production.
A third possibility is a differentiated market in which European manufacturers concentrate on technically specialised, high-value equipment while imported products capture a larger share of more standardised categories. Such specialisation could preserve industrial competitiveness where European producers retain engineering advantages, but it could also create vulnerabilities if the supposedly standardised categories remain essential to maintenance or network expansion.
The outcome depends on product characteristics, technical standards, industrial investment, buyer preferences and the capacity of European manufacturers to compete internationally.
The crucial point is that lower prices are not inherently evidence of industrial weakness, and higher domestic prices are not inherently evidence of resilience. Industrial policy must establish whether the productive capabilities being preserved are genuinely important, whether they can operate competitively and whether alternative supplies are sufficiently dependable.
The relationship between Chinese overcapacity and the AI investment cycle
The connection between Chinese equipment exports and American hyperscaler investment is indirect but strategically important.
A slowdown in new AI infrastructure construction could affect the timing of demand for electrical equipment, while continued grid reinforcement and broader electrification may sustain investment in other parts of the electricity system. These demand channels should not be collapsed into a single forecast. A reduction in data-centre orders does not necessarily imply an equivalent reduction in European grid expenditure, just as an increase in European imports does not establish that the imported equipment was originally intended for the American market.
The trade-diversion mechanism requires evidence concerning production capacity, export destinations, prices and changes in demand across markets. Without such evidence, the proposition that Chinese overcapacity is being redirected specifically because of delayed American AI expenditure remains a scenario hypothesis.
Nevertheless, the documented increase in European electrical-steel imports and the subsequent safeguard intervention establish that Europe is already confronting import pressure in a strategically relevant part of the electricity-equipment value chain. This creates a plausible channel through which changes in international industrial supply and demand can influence European infrastructure economics.
The significance for AI is that the same electrical equipment industry supports data centres, conventional manufacturing, renewable generation and electricity-network reinforcement. International price movements affecting that industry can therefore influence several investment categories simultaneously.
The result is a geopolitical interaction between American computing investment, Chinese manufacturing capacity and European electricity infrastructure that extends beyond direct commercial competition among technology companies.
Chapter 6 — Key judgments
The strongest verified evidence of Chinese-related industrial pressure concerns grain-oriented electrical steel and the transformer-core supply chain. European imports in the relevant categories increased substantially between the reporting periods examined by the Commission, and provisional safeguards were introduced in September 2026. These developments establish a concrete industrial-policy issue rather than merely a prospective scenario.
The evidence does not support extending the same quantitative conclusions automatically to transformers, switchgear, cables or cooling equipment. Those markets require product-specific analysis of production capacity, import penetration, pricing, technical compatibility and supplier concentration.
For Europe, the principal economic benefit of international competition is the possibility of lower equipment acquisition costs and additional supply for infrastructure investment. The principal strategic vulnerability is the potential erosion of domestic manufacturing capabilities and the resulting reduction in alternative sources of critical equipment.
Italy’s exposure is especially consequential because the country combines significant electricity-network investment requirements with industrial capabilities relevant to electrical infrastructure. The strategic objective is to capture procurement benefits while preserving the manufacturing, engineering and maintenance capacity necessary for reliable infrastructure development.
What would change the assessment: Evidence that lower-priced imports are complementing rather than displacing European manufacturing would weaken the industrial-dependence scenario. Persistent reductions in European production, rising supplier concentration, reduced manufacturing investment or deteriorating access to replacement equipment would strengthen it.
Open official record: A comprehensive product-by-product assessment requires harmonised customs statistics, verified domestic production data, equipment delivery times and procurement information. The official electrical-steel record is sufficiently developed to support a specific assessment, but an equivalent evidentiary basis has not been established for every other equipment category.
Pillar II — Integrated Industrial and Geopolitical Assessment
The evidence examined across the three chapters establishes that the expansion of AI infrastructure is becoming inseparable from the physical economics of electricity networks and industrial equipment. The transition is not merely an increase in the energy consumption of digital services. It changes the competitive significance of electricity connections, transformer manufacturing, electrical materials, engineering capacity and the ability to coordinate complex infrastructure projects.
The United States demonstrates the scale of the interconnection challenge, although the historical generation-and-storage queue must remain analytically separate from large-load demand. Europe demonstrates the corresponding interaction between electricity infrastructure, industrial procurement and manufacturing resilience. Italy’s transmission development requirements, the United Kingdom’s regulatory scrutiny of data-centre connection applications and the European Union’s intervention in the electrical-steel market show that the relevant physical constraints are already entering public policy and industrial decision-making.
The financial consequences of these developments depend on their timing. An infrastructure project that is delayed by unavailable grid capacity may retain substantial long-term economic value, but capital committed during the development period remains exposed to changes in technology, financing conditions and commercial demand. Conversely, facilities already possessing reliable electricity access and commercially usable capacity may become more difficult for competitors to replicate when new connections require substantial additional infrastructure.
The interaction with Chinese industrial overcapacity introduces a second strategic dimension. Lower imported-equipment prices can improve the economics of European network development while simultaneously exposing domestic manufacturers to intensified competition. Whether the overall effect is beneficial depends on the balance between infrastructure affordability, industrial competitiveness, supply diversification and the preservation of essential technical capabilities.
The central industrial judgment is that electricity access and manufacturing capacity are becoming determinants of AI competitiveness alongside computing technology and financial capital. The capacity to finance a data centre is not equivalent to the capacity to energise it, and the ability to purchase electrical equipment at a low price is not equivalent to possessing a resilient industrial supply chain.
The next strategic question, addressed in Pillar III, is how these constraints affect the distribution of market power: whether delayed infrastructure investment reduces returns across the industry, whether the strongest hyperscalers acquire durable advantages from scarce electricity-connected capacity, and whether European economies can convert the resulting industrial demand into stronger manufacturing competitiveness without increasing strategically significant dependencies.
PILLAR III — GEOPOLITICAL CONSEQUENCES AND COMPETING MARKET OUTCOMES
Scenario perimeter: A hypothetical 18-month postponement of expected economic returns on the $725–760 billion aggregate AI infrastructure investment envelope attributed to Microsoft, Amazon, Alphabet and Meta. The aggregate and the delay remain stipulated scenario assumptions, not independently reconciled corporate forecasts.
Chapter 7. European Industrial Exposure: Italy, France, Germany, the United Kingdom and EU Coordination
Europe faces a conflict between becoming an AI infrastructure location and retaining control of the industrial system that makes AI possible
Europe’s exposure to the transformation of artificial intelligence into an infrastructure-intensive industry is fundamentally different from that of the United States. The American financial question concerns whether the largest technology companies can convert unprecedented infrastructure commitments into satisfactory returns on invested capital. The European strategic question is more complicated: whether additional computing investment can strengthen European industrial production, electricity networks and technological autonomy, or whether it will primarily increase demand for equipment, electricity and services supplied or controlled by companies operating outside the European industrial system.
The distinction is important because hosting computing infrastructure is not equivalent to controlling the associated value chain. A country can attract a major data-centre campus, provide electricity connections and finance substantial network reinforcement while obtaining only a limited share of the higher-value activities associated with computing services, specialised hardware, intellectual property and long-term commercial decision-making. Conversely, a European manufacturer can benefit from the worldwide expansion of AI infrastructure by supplying electrical equipment and engineering services without hosting the computing facilities themselves. These two forms of participation generate different industrial benefits, financial exposures and geopolitical dependencies.
The European Union’s own policy framework increasingly recognises the industrial character of the transition. The European Commission’s Strategic Roadmap for Digitalisation and AI in the Energy Sector, adopted on 3 June 2026, identifies data-centre electricity demand as a material challenge for energy security, affordability and the wider electrification of the European economy. The Commission states that data centres account for approximately 2.5% of EU electricity consumption and projects that installed data-centre capacity could increase from approximately 12 GW in 2025 to 28 GW by 2030. These figures describe installed computing-facility power capacity and electricity demand, rather than the volume of interconnection applications or completed AI-specific investments. Strategic Roadmap for Digitalisation and AI in the Energy Sector — European Commission — June 2026.
That projected expansion is economically significant because the European electricity system is simultaneously required to support industrial electrification, changes in power generation, transport decarbonisation and the reinforcement of existing infrastructure. Additional data-centre demand must therefore be accommodated within an already capital-intensive investment cycle. Where electricity networks possess available capacity, computing infrastructure can create opportunities for regional investment and industrial development. Where networks are constrained, the same projects can increase competition for connection capacity, accelerate the need for reinforcement and complicate the allocation of costs among industrial users.
The European Commission’s June 2026 roadmap moves beyond general statements about digital sovereignty by proposing institutional mechanisms to govern these trade-offs. Its model tripartite agreement would bring together data-centre operators, electricity-sector participants and public authorities to improve the credibility of project information, coordinate grid integration, facilitate clean-energy procurement and encourage operating flexibility. The proposal also addresses speculative queue reservation, the reuse of waste heat and the possibility of more flexible electricity-connection arrangements. These measures should be distinguished from binding rules already implemented across the Union: the roadmap establishes policy intentions and implementation priorities, while individual legal obligations depend on subsequent instruments and applicable national frameworks. Strategic Roadmap for Digitalisation and AI in the Energy Sector — European Commission — June 2026.
The industrial question becomes especially important when international equipment markets experience changing competitive conditions. Chinese overcapacity in selected electrical-industrial products could reduce procurement costs for European infrastructure developers while increasing competitive pressure on European manufacturers. The European Union must therefore reconcile objectives that may conflict in the short term: faster grid construction, lower equipment costs, preservation of domestic manufacturing capacity, supplier diversification and greater control over critical digital infrastructure.
A policy that maximises data-centre investment without examining the electricity and industrial systems required to support it risks producing an incomplete form of technological sovereignty. Europe could become a larger consumer and host of computing infrastructure without acquiring corresponding control over the strategic inputs that determine its long-term availability.
Italy: the interaction between Lombardy’s industrial concentration, grid investment and electrical-equipment manufacturing
Italy’s strategic exposure is unusually concentrated because the development of new data-centre infrastructure overlaps geographically and economically with one of Europe’s most important manufacturing regions. The Italian electricity system must accommodate prospective computing demand while supporting established industrial consumption, renewable generation, transport electrification and national transmission-network development. The resulting challenge is not simply whether sufficient electricity exists at national level, but whether the grid can deliver additional capacity at the locations and within the timeframes required by competing industrial users.
Terna’s 2025 Network Development Plan provides an important indication of that pressure. Data-centre connection requests had reached approximately 30 GW by 31 December 2024, representing a volume 24 times greater than in 2021. The requests were concentrated predominantly in northern Italy, particularly Lombardy. The plan also records an increase to approximately 39.62 GW by 28 February 2025. The difference between these figures reflects their reference dates and must not be represented as operating electricity capacity or as a forecast of eventual consumption. The reported average requested standard power for data-centre projects exceeded 100 MW, illustrating the scale of individual facilities relative to conventional commercial electricity users. Terna 2025 Development Plan — Terna — 2025.
This geographical concentration creates an industrial allocation problem. Lombardy combines large manufacturing activities, logistics, business services and a significant concentration of prospective data-centre projects. These activities differ considerably in their electricity demand profiles, investment horizons, sensitivity to connection delays and contribution to domestic value added. The regional development of computing infrastructure can generate demand for construction, electrical engineering, facility services and network reinforcement, but it can also require infrastructure that would otherwise support alternative industrial investment.
The economic question is not whether one category of electricity user deserves priority in every circumstance. It is whether connection capacity is allocated according to credible project readiness, expected network costs and the broader economic consequences of the investment. A speculative data-centre application should not prevent an executable manufacturing project from obtaining access to electricity. Equally, a commercially advanced computing facility should not be excluded merely because its business model differs from conventional manufacturing.
A technically credible approach requires Terna and the relevant distribution operators to distinguish requested, contracted, physically available and actually utilised capacity. This is especially important where developers submit applications for alternative sites or future expansion options. Without effective identification of duplicate or speculative requests, the nominal connection pipeline can overstate the amount of infrastructure that is likely to become operational, potentially distorting network planning.
Italy’s opportunity extends beyond site selection. Transmission investment and data-centre development create demand for power transformers, cables, switchgear, protection systems, cooling equipment, industrial installation and specialised engineering. The country can capture value from these activities if domestic and European producers retain the technical capabilities and manufacturing capacity required to compete. The existence of major domestic manufacturing capabilities does not, however, guarantee that Italian firms will obtain the relevant contracts. Procurement depends on technical requirements, delivery schedules, certification, total lifecycle costs and the competitive position of individual suppliers.
This is where Chinese industrial overcapacity becomes particularly consequential. Imported electrical steel, transformer components or finished equipment may provide cost advantages to infrastructure developers. Yet sustained substitution could affect domestic or European producers at different points in the value chain. An Italian transformer manufacturer may benefit from competitively priced imported components while competing against imported finished transformers. A cable manufacturer may benefit from imported materials while facing price pressure in certain categories of finished cables. The industrial consequences cannot therefore be inferred from aggregate import growth alone.
Italy must also distinguish between investment in transmission infrastructure and investment in computing capacity. Terna’s electricity-grid programme is intended to support wider national system requirements, whereas private data-centre investment is directed towards specific commercial activities. The economic benefits may overlap, but the cost-allocation principles should remain distinct. Infrastructure needed primarily for an individual project should be evaluated according to the applicable connection and charging framework, while investments providing broader network benefits may justify a different allocation of costs.
The strategic question for Italy is consequently whether new computing demand can stimulate an industrial supply chain that strengthens national electricity infrastructure rather than merely increasing imported capital goods and network expenditure.
An additional issue concerns manufacturing investment itself. If electricity connections for new industrial facilities become difficult to secure, Italy may experience a deterioration in its ability to attract capital-intensive production even while successfully attracting computing projects. This would represent a particularly adverse outcome: a growing stock of digital infrastructure accompanied by a weakening of the manufacturing base required to sustain it.
The appropriate industrial assessment should therefore measure not only the capital value of data-centre projects but also their effect on domestic procurement, industrial capacity, connection availability for other users and long-term maintenance requirements.
Italy: principal transmission channels and decision variables
| Industrial or infrastructure area | Documented baseline or exposure | Potential opportunity | Strategic vulnerability | Decisive indicator |
|---|---|---|---|---|
| Data-centre electricity connections | Approximately 30 GW requested at end-2024; 39.62 GW at February 2025 | Additional infrastructure and engineering investment | Speculative applications and connection congestion | Verified projects progressing to energisation |
| Lombardy industrial system | Geographic concentration of data-centre requests | Regional electrical engineering and services demand | Competition for local grid capacity | Industrial and data-centre connection completion |
| National transmission network | Terna development programme exceeding €23bn for 2025–2034 | Grid modernisation and improved capacity | Procurement, construction and commissioning delays | Completed network assets and operating transfer capacity |
| Transformers and electrical components | Exposure to European electrical-equipment supply chains | Domestic manufacturing and engineering orders | Imported-product substitution | Qualified suppliers, domestic output and import penetration |
| Power cables | Demand associated with network reinforcement | Manufacturing, installation and maintenance | Import competition or equipment-delivery delays | Product-level orders and delivery performance |
| Industrial electrification | Requires access to reliable electricity infrastructure | Modernisation of manufacturing assets | Competition for constrained connections | Connection capacity allocated to executable industrial projects |
| Data-centre equipment supply | Dependence on specialised global supply chains | Integration, construction and servicing opportunities | Limited capture of high-value equipment production | Domestic procurement and supplier qualification |
| Regional development | New physical investment and potential service activity | Employment and local industrial demand | Network costs without commensurate domestic value added | Procurement, fiscal contribution and completed economic activity |
The table distinguishes verified national planning information from analytical exposure categories. It does not assign monetary benefits, industrial employment effects or probabilities that cannot be derived from the available official record.
For Italian policymakers, the decision is therefore not simply whether to encourage or discourage data-centre investment. It is how to establish credible conditions under which additional computing capacity contributes to national industrial development, reliable electricity supply and the preservation of strategically relevant manufacturing activities.
France: electricity availability as a competitive advantage, but not a guarantee of European technological sovereignty
France enters the infrastructure competition with a different configuration of opportunities and constraints. Its electricity-generation system, particularly its established nuclear generation capacity, offers a potential advantage to electricity-intensive investments seeking dependable low-carbon supply. The strategic significance of this advantage is reinforced when computing-facility operators evaluate locations according to electricity costs, network availability, operational continuity and the carbon characteristics of their energy consumption.
However, national generation availability must be distinguished from physical access to electricity at the location of a proposed facility. A country can possess substantial electricity production and still encounter local transmission constraints, lengthy connection processes or competition among large electricity users. The economic value of French generating capacity therefore depends partly on the ability to translate it into commercially usable connections for new industrial and computing projects.
France’s transmission-system operator RTE has incorporated data-centre demand into its longer-term electricity planning. The French National Resource Adequacy Assessment published in December 2025 describes RTE’s approach to data-centre electricity forecasts, noting that it accounts for connection requests, the proportion of projects likely to proceed and gradual increases in site utilisation. This approach is particularly important because data-centre developments can require extended periods to reach their eventual operating load, meaning that contracted connection capacity is not equivalent to immediate electricity consumption. French National Resource Adequacy Assessment 2025 — French Ministry for Ecological Transition — December 2025.
The industrial opportunity for France lies in converting electricity availability into an advantage for high-value computing activities, domestic technological development and associated engineering. Yet the presence of foreign-financed data centres does not automatically establish sovereign control over computing hardware, cloud services, AI models or customer relationships. These different layers may remain controlled by separate companies operating under different contractual and legal arrangements.
A commercially successful data centre can therefore strengthen national electricity demand and infrastructure investment while contributing only partially to technological autonomy. The policy objective should be to distinguish between the economic benefits of hosting foreign infrastructure and the additional benefits associated with domestic ownership, technological capability, research and industrial participation.
This distinction becomes more consequential if an 18-month return delay changes the investment schedules of major international hyperscalers. France could retain an advantage in electricity availability while facing delays in the commercial deployment of projects dependent on external capital-allocation decisions. Conversely, projects with credible demand, secured connections and competitive operating costs may remain attractive even during a wider investment adjustment.
French policymakers must also consider the allocation of electricity between computing and industrial decarbonisation. Electricity availability has strategic value precisely because it can support several forms of economic activity. The relevant question is whether additional computing projects increase the overall productivity of the electricity system or create local infrastructure requirements whose economic benefits are not commensurate with their costs.
The industrial implication is that France should evaluate data-centre investment as part of its broader electricity and manufacturing strategy rather than as an isolated digital-sector programme.
Germany: the competitive interaction between digital infrastructure and electricity-intensive manufacturing
Germany’s exposure is shaped by the interaction between its established manufacturing base, electricity-system transformation and demand for additional digital infrastructure. The strategic problem is not identical to that of France. Germany must consider whether new computing investment can be accommodated while preserving the competitiveness of industrial production and supporting the ongoing adaptation of its electricity network.
The relevance of connection flexibility is already reflected in the German regulatory framework. The Federal Network Agency identifies Section 17(2b) of the Energy Industry Act, which provides a framework for flexible network-connection agreements involving storage and electricity-consuming installations. Such arrangements offer a possible means of connecting projects under defined operational constraints rather than treating every requested connection as an unconditional requirement for fully firm capacity from the outset. Grid Connection and Flexible Connection Agreements — Bundesnetzagentur — 2026.
This distinction has important industrial implications. A large computing facility capable of varying part of its electricity demand may be able to accept operating conditions that differ from those required by an industrial process dependent on uninterrupted production. Conversely, some AI workloads or customer services may not tolerate substantial operational interruptions. The available flexibility must therefore be demonstrated technically and commercially rather than assumed from the general category of data-centre demand.
Flexible connections could improve the utilisation of existing network infrastructure where appropriate, but their effectiveness depends on the facility’s operational requirements, contractual arrangements and the network constraints concerned. They cannot substitute universally for grid reinforcement.
Germany’s industrial position also creates exposure on the manufacturing side. European competition in transformers, switchgear, power electronics and associated equipment affects suppliers serving electricity networks and industrial facilities. Lower-cost imports may benefit equipment users while challenging producers. A deterioration in domestic or European manufacturing capability could therefore reduce longer-term supply resilience even if near-term infrastructure procurement costs fall.
The strategic consequence is that Germany must evaluate both sides of the market. Additional AI infrastructure can support digital services and increase demand for industrial equipment, but it can also compete for electricity-network development resources required by other manufacturing activities. The economic outcome depends on whether the new investments create sufficient domestic value while allowing the electricity system to serve a diversified industrial base.
A policy focused exclusively on data-centre attraction could neglect the wider opportunity cost of network capacity. A policy focused exclusively on protecting existing manufacturing could overlook commercially valuable computing investment and the industrial demand it generates. The more defensible approach is to evaluate projects using consistent criteria concerning readiness, connection costs, operating flexibility and economic additionality.
The United Kingdom: electricity connection rights as a factor in competitive market structure
The United Kingdom provides a particularly revealing case because its regulatory response directly addresses speculative demand for scarce grid connections. Ofgem reported on 29 July 2026 that demand-side connection applications had increased from 41 GW to 125 GW in less than a year, with data-centre projects responsible for at least 80 GW of that increase. The figures describe applications, not confirmed operating demand or additional capacity already supplied by the electricity system. Ofgem Acts to Free Up Grid Capacity by Tackling Speculative Data Centre Projects — Ofgem — July 2026.
The scale of the increase creates a market-design problem as well as an engineering challenge. Where developers can reserve scarce connection capacity without demonstrating a credible path to construction, queue positions may acquire economic value independently of the productive activity that originally justified them. This can encourage applications intended to preserve commercial options rather than support executable investments, potentially slowing projects that are ready to proceed.
Ofgem’s proposed reforms respond by introducing stronger evidence requirements, including a commitment fee, project-development milestones, credible end-user information and evidence of the procurement of long-lead electrical equipment. The measures are intended to distinguish viable projects from speculative applications and improve the allocation of network capacity. They remained proposals at the reference date rather than a fully established regulatory regime. Proposed Data Centre Connection Reforms — Ofgem — July 2026.
The competitive consequences deserve particular attention. Requirements for substantial financial commitments and advanced equipment procurement may improve the credibility of applications, but they can also favour companies with extensive capital resources and established supplier relationships. A smaller developer may possess a commercially sound project while finding it more difficult to finance early equipment commitments or satisfy demanding financial milestones.
The regulator therefore faces a trade-off between eliminating speculative queue occupation and maintaining competitive entry. A system that prioritises financial strength without adequately assessing project economics risks reinforcing the market position of existing large infrastructure operators. Conversely, a system that permits indefinite reservation of grid capacity without meaningful commitments can obstruct commercially viable projects and impose costs on other electricity users.
The British experience is consequently directly relevant to the hypothetical oligopoly-reinforcement scenario. Electricity-connection rules can influence market concentration by determining which companies can preserve access to scarce infrastructure. Regulatory design therefore becomes an independent factor shaping competition alongside financial resources and technological capability.
European Union coordination: avoiding a fragmented competition for electricity, capital and industrial capacity
National policies cannot fully resolve the strategic issues created by AI infrastructure because European electricity markets, industrial supply chains and digital-service markets extend across national borders. A data-centre investment in one member state may rely on equipment manufactured elsewhere in the Union, electricity imported through interconnected markets and digital customers located in several jurisdictions. Policies affecting one part of the system can therefore influence costs and investment incentives elsewhere.
The European Commission’s June 2026 roadmap provides a common policy direction through its emphasis on better energy-system integration, credible connection applications and more efficient data-centre operation. In September 2026, the Commission also launched a consultation on minimum energy-performance standards for data centres, with a legislative proposal planned for the second quarter of 2027. The consultation seeks to improve the efficiency and sustainability of facilities operating within the Union, while recognising the importance of the sector for digital competitiveness. Minimum Performance Standards for Data Centres in Europe — European Commission — September 2026.
A common framework can reduce regulatory fragmentation, but harmonisation should not ignore differences among national electricity systems. A connection rule appropriate for a region with substantial unused network capacity may be unsuitable for an industrial zone experiencing severe congestion. Similarly, requirements concerning operating flexibility must account for differences between computing workloads and contractual service obligations.
The broader European challenge is to avoid a competition in which member states attempt to attract the same infrastructure investments through increasingly favourable electricity arrangements without adequately evaluating the consequences for manufacturing, grid costs or domestic technological capabilities.
Industrial coordination is equally important. European trade measures affecting electrical steel or transformer components should be assessed alongside the needs of downstream manufacturers and network operators. The September 2026 provisional safeguards on grain-oriented electrical steel demonstrate the importance of protecting strategically relevant upstream production, but their full industrial consequences depend on the interaction between import restrictions, domestic supply capacity and downstream equipment costs. Commission Imposes Provisional Safeguard Measures on Imports of Grain-Oriented Electrical Steel — European Commission — September 2026.
The objective should not be a uniform European procurement rule or an unconditional preference for any particular origin of equipment. It should be an industrial system in which strategic dependencies are visible, alternative suppliers remain viable and infrastructure can be constructed within economically acceptable timeframes.
European comparative exposure and policy capacity
| Jurisdiction | Principal economic exposure | Institutional instrument or documented baseline | Industrial opportunity | Principal policy trade-off |
|---|---|---|---|---|
| Italy | Concentrated data-centre applications alongside manufacturing and grid development | Terna 2025 Development Plan; approximately 30 GW of data-centre applications at end-2024 | Electrical engineering, cables, transformers, construction and network investment | Attract computing investment without crowding out viable industrial connections |
| France | Electricity availability and conversion of generation capacity into commercially usable computing infrastructure | RTE electricity planning and resource-adequacy assessments | Electricity-intensive computing and associated industrial activity | Convert hosting capacity into domestic value while protecting other electricity uses |
| Germany | Competition for network resources within a major manufacturing economy | Energy Industry Act and Federal Network Agency treatment of flexible connections | Electrical-equipment production, engineering and flexible infrastructure | Support computing growth without weakening industrial electricity access |
| United Kingdom | Rapid growth in large-load connection applications | Ofgem July 2026 connection-reform consultation | Credible infrastructure projects and improved queue management | Remove speculative demand without restricting viable entrants |
| European Union | Fragmented energy systems and cross-border industrial dependencies | June 2026 strategic roadmap; September energy-efficiency consultation | Common standards, industrial supply-chain development and coordinated investment | Balance infrastructure affordability, manufacturing resilience and competition |
The national figures and regulatory measures are not directly interchangeable. Italy’s reported values concern data-centre connection applications, the United Kingdom’s concern a broader set of demand connection applications, and the EU’s figures describe projected installed data-centre capacity. Combining them would not produce a meaningful European capacity total.
Chapter 7 — Key judgments
European exposure to the AI infrastructure cycle cannot be evaluated solely through the volume of new data-centre investment. The strategically important question is whether computing capacity becomes part of a broader industrial system that strengthens electricity networks, manufacturing capabilities, technical expertise and domestic economic activity.
Italy faces a particularly consequential interaction between data-centre development in Lombardy and electricity infrastructure required by existing and prospective manufacturing. France possesses a potential electricity-related competitive advantage whose economic value depends on actual connection availability and the domestic share of the resulting activity. Germany must reconcile computing growth with the electricity requirements of its industrial base. The United Kingdom demonstrates how connection regulation can affect market concentration by favouring projects capable of establishing financial and technical readiness.
At EU level, coordination must preserve competition among viable projects while reducing speculative infrastructure reservation, improving energy efficiency and maintaining resilient electrical-equipment supply chains. The emerging European framework recognises these requirements, although its full effects depend on implementation.
What would change the assessment: Verified evidence of increasing domestic industrial procurement, faster energisation, greater flexibility in electricity demand and improved utilisation of network capacity would support a more favourable European outcome. Rising connection congestion, increasing supplier concentration and projects delivering limited domestic industrial participation would strengthen the vulnerability scenario.
Open official record: A comparable European dataset linking data-centre projects to actual electricity usage, grid-upgrade costs, domestic procurement, industrial employment, ownership and realised economic value would materially improve the assessment. Current national reporting remains insufficiently harmonised for those comparisons.
Chapter 8. Partial Capitulation versus Oligopoly Reinforcement: Conditions, Financial Indicators and Industrial Consequences
The market bifurcation will depend on who controls productive scarcity and who merely finances expensive capacity
The potential 18-month postponement of returns on the stipulated $725–760 billion AI infrastructure investment envelope creates a market adjustment whose consequences depend on the interaction between capital productivity, electricity availability and competitive structure. The central distinction is between an industry in which investment delays expose excessive expenditure and one in which the same delays increase the strategic value of infrastructure already capable of generating commercially profitable output. These possibilities can coexist, but they imply different investment decisions, different equity-market valuations and different consequences for suppliers, customers and governments.
An important development in the official record supports the need to examine both outcomes. The International Energy Agency’s 2026 assessment concludes that the scale of global data-centre investment is becoming too large to be funded entirely from corporate balance sheets, making capital-market financing and investor expectations increasingly influential. It also identifies electricity connections, equipment manufacturing, advanced semiconductors and finance as interacting constraints on the expansion of AI infrastructure. The agency’s central projection places global data-centre electricity consumption at approximately 950 TWh in 2030, compared with 485 TWh in 2025, while recognising that supply-chain bottlenecks could constrain more aggressive development scenarios. Key Questions on Energy and AI — International Energy Agency — 2026.
This creates an economic environment in which neither announced capital expenditure nor projected demand can independently determine the industry’s future structure. Even substantial demand growth cannot guarantee that a particular infrastructure investment will generate satisfactory returns. Equally, weaker near-term earnings do not establish that the productive assets financed by the investment programme will ultimately lose value.
The key distinction is between the scarcity of infrastructure inputs and the scarcity of commercially valuable computing services. Electricity connections, qualified electrical equipment and operational data centres may become difficult to obtain, but that scarcity creates an economic premium only where the resulting capacity can be sold or used at prices sufficient to cover its full costs. Scarce infrastructure that remains underutilised or supports unprofitable services may be strategically important without producing an adequate shareholder return.
The market bifurcation should therefore be examined through the relative position of different classes of participants. The four hyperscalers possess substantial established businesses and can allocate financial resources across several activities. Independent data-centre operators, infrastructure developers, specialised computing providers and equipment manufacturers face different combinations of financing, operating and contractual risk. Some smaller companies may possess valuable infrastructure positions, while some large operators may have committed substantial capital to projects whose prospective economics deteriorate. Size alone does not determine the outcome.
Partial capitulation: when market discipline produces selective contraction rather than an industry-wide collapse
Partial capitulation would occur if investors and corporate management conclude that a meaningful portion of planned infrastructure investment no longer offers an adequate expected return under revised assumptions about commercial utilisation, capital costs or commissioning schedules. The relevant threshold is not a predetermined fall in revenue or equity valuation. It is the point at which the incremental economic value of continuing selected projects becomes insufficient to justify the additional resources required.
Under this pathway, the initial adjustment would probably be visible in investment authorisations, construction schedules and equipment orders before it appeared as a comparable decline in the industry’s operating capacity. Projects already under construction may continue because the remaining expenditure required to complete them is economically justified, even if their original total investment estimates are no longer attractive. Projects at earlier development stages may be postponed because fewer contractual obligations have been incurred and greater financial flexibility remains.
This creates an uneven adjustment across the infrastructure value chain. Manufacturers supplying equipment for projects approaching commissioning may continue receiving orders, while suppliers dependent on new development approvals may encounter weaker demand. Construction contractors may experience schedule revisions, while electricity-network operators may need to reassess the credibility of connection applications associated with delayed or cancelled projects.
A decline in announced capital expenditure would consequently not translate immediately into a proportionate decline in spending across every supplier category. Existing contractual commitments, manufacturing lead times and project completion requirements would influence how the adjustment passes through the industrial system.
The geographical effects could also differ. Regions containing established, electricity-connected data centres might remain attractive because additional capacity can be deployed without the same degree of new network development. Regions where projects depend on substantial uncompleted reinforcement could experience more deferrals, particularly if the expected revenue trajectory no longer justifies the delay.
The financial effect would be similarly differentiated. A reduction in new commitments could improve future cash-flow flexibility, but termination penalties, unrecoverable development expenditure or the impairment of qualifying assets could create near-term losses. The absence of substantial write-downs would not necessarily establish that an investment adjustment had been economically successful, just as an impairment charge would not necessarily imply that the company’s remaining infrastructure programme lacked commercial value.
The relevant distinction is between recognising past investment losses and improving future capital allocation.
Oligopoly reinforcement: the conditions under which electricity and financing become durable barriers to entry
The alternative pathway begins with a different interpretation of infrastructure scarcity. If demand for commercially valuable AI services remains sufficiently strong while electricity connections and capital availability constrain the development of competing capacity, existing operators with productive infrastructure can acquire an advantage that is difficult to replicate.
That advantage could arise through several mechanisms. First, an operating facility with dependable electricity access may begin generating incremental revenue while competitors remain exposed to lengthy development processes. Second, a company capable of funding successive equipment upgrades may preserve the commercial productivity of its infrastructure as technology changes. Third, an operator with established suppliers and engineering relationships may obtain more reliable delivery schedules than a new entrant attempting to assemble an equivalent infrastructure programme.
These advantages are not identical to conventional software network effects. They are industrial barriers associated with capital requirements, project development, equipment procurement and access to physical infrastructure. They may strengthen market concentration even where the underlying computing technology becomes more widely available.
However, an oligopoly premium would require the resulting market structure to produce durable economic benefits. A reduction in the number of viable competitors does not automatically increase profitability if the remaining companies continue competing intensely. Nor does it guarantee that existing infrastructure retains its value if technological efficiency reduces the quantity of capital required to deliver comparable computing services.
The conditions supporting a renewed premium are therefore demanding. Commercial demand must remain sufficiently strong, installed capacity must achieve satisfactory utilisation, the cost of operating and replacing equipment must remain manageable, and operators must be able to retain a meaningful share of productivity improvements rather than transferring all benefits to customers through lower prices.
The relationship between hardware efficiency and market power is particularly important. More efficient computing systems can increase the amount of useful computation produced by an existing electricity connection, raising the economic value of that connection. At the same time, improved efficiency may reduce the infrastructure required by competitors, weakening barriers to entry. Which effect dominates depends on customer demand, deployment costs and the availability of alternative technologies.
The same ambiguity applies to electricity constraints. A severe connection shortage may protect existing operating capacity, but it may also increase the cost of new expansion for incumbent operators. Scarcity becomes a competitive advantage only when the operator’s relative position improves more than its own costs increase.
The sequential pathway: how a financial correction could create a more concentrated industry
The most important possibility is that partial capitulation and oligopoly reinforcement occur sequentially. An initial period of disappointing returns could trigger stricter investment discipline, reducing the number of projects seeking capital and electricity connections. Financially stronger companies might then preserve their most valuable infrastructure positions while less competitive projects are postponed or abandoned. If customer demand subsequently expands, the remaining productive capacity could become more valuable.
Under this pathway, market concentration emerges not simply from higher absolute expenditure by the largest operators, but from differential survival of infrastructure projects.
Companies possessing electricity-connected facilities with commercially viable utilisation would retain productive options that competitors could not quickly reproduce. The value of those options would depend on whether capacity could be expanded, upgraded or repurposed at acceptable cost. Companies dependent on unfinished infrastructure would remain exposed to commissioning risk, financing conditions and changes in technological requirements.
This could also change the bargaining relationship between hyperscalers and equipment suppliers. A smaller number of financially credible infrastructure buyers might gain purchasing leverage over some manufacturers, while suppliers of genuinely scarce or technically specialised equipment could preserve pricing power. The resulting industrial structure would not necessarily favour either side uniformly.
For European manufacturers, the consequences would depend on the composition of their order books. Suppliers heavily exposed to speculative or early-stage projects might experience a sharp reduction in prospective demand. Manufacturers serving grid reinforcement, replacement infrastructure and projects already approaching operation could experience more durable requirements. Equipment suppliers with substantial exposure to several infrastructure sectors might be less sensitive to a slowdown in new AI investment than those dependent primarily on data-centre construction.
The sequence could also influence governments. Public authorities might find that announced data-centre investment programmes produce fewer completed facilities than anticipated, requiring revisions to network plans or infrastructure-development assumptions. At the same time, the projects that proceed could become increasingly concentrated among operators capable of securing financing and satisfying connection requirements.
The outcome would therefore be a restructuring of the investment pipeline rather than necessarily a collapse in the commercial demand for AI services.
The distinction between infrastructure ownership and control of market power
The ownership of physical infrastructure does not establish control over the entire AI value chain. Data-centre owners, cloud-service providers, model developers, semiconductor suppliers and enterprise customers occupy different economic positions. A hyperscaler may control substantial electricity-connected infrastructure while depending on specialised external equipment manufacturers. A computing-service customer may possess bargaining power because of its commercial scale or ability to shift workloads between providers. An independent infrastructure operator may own valuable facilities without controlling the services delivered through them.
The analysis of concentration must therefore identify the relevant market and the mechanism through which competition is constrained. A high concentration of data-centre ownership is not, by itself, evidence of monopoly power in AI applications or cloud services. A company may possess important infrastructure assets without being able to impose higher prices on customers, particularly where competing services remain technically and commercially substitutable.
The European policy implications are substantial. If grid access becomes a major barrier to entry, competition authorities and sector regulators may need to examine whether connection rules systematically favour incumbents. However, granting preferential access to smaller companies without regard to project readiness could undermine network efficiency and impose costs on other electricity users.
The regulatory objective should therefore be non-discriminatory access under transparent criteria, combined with effective mechanisms to prevent the speculative reservation of capacity. A financially credible project should not obtain indefinite control of scarce electricity capacity merely because its sponsor possesses a large balance sheet.
Similarly, the competitive consequences of long-term electricity or infrastructure contracts depend on their actual provisions, duration, exclusivity and effect on alternative users. The existence of long-term commitments does not automatically establish unlawful exclusion or anti-competitive conduct.
Conditions differentiating the market outcomes
| Decision variable | Conditions favouring partial capitulation | Conditions favouring renewed concentration | Conditions favouring a less concentrated market |
|---|---|---|---|
| AI monetisation | Incremental revenue and profit remain below investment expectations | Strong demand supports utilisation of incumbent capacity | New providers can profitably serve differentiated demand |
| Capital-market access | Financing becomes more restrictive across projects | Largest operators maintain a relative financing advantage | Competitive financing remains available to credible entrants |
| Electricity connections | New infrastructure remains delayed or uneconomic | Existing operators control scarce productive capacity | Connection reforms enable viable new entrants |
| Technology efficiency | Equipment value deteriorates before adequate utilisation | Incumbents capture productivity gains through scale | Efficiency reduces the capital needed for entry |
| Customer pricing | Competition prevents recovery of infrastructure costs | Scarcity and service differentiation support sustainable margins | Customers can substitute providers effectively |
| Equipment procurement | Project cancellations reduce demand | Large buyers gain favourable access to suppliers | Manufacturing capacity expands and supplier access broadens |
| Contractual commitments | Rigidity makes project cancellation costly | Long-term contracts protect valuable capacity | Flexible contracts reduce entry barriers |
| European industrial effects | Weaker orders for marginal infrastructure projects | Orders concentrate among fewer large buyers | Diverse demand supports multiple qualified suppliers |
| Regulatory intervention | Stricter access requirements reduce speculative projects | Poorly designed rules favour established operators | Transparent readiness rules preserve competitive access |
| Asset recoverability | Delays reduce expected economic value | Energised facilities retain strong commercial value | Alternative uses and technological flexibility preserve competition |
The table establishes conditional mechanisms, not numerical probabilities. The three outcomes also need not be mutually exclusive across markets or time. A company may reduce its investment programme while increasing its share of commercially productive capacity, and one infrastructure segment may become concentrated while another remains competitive.
Financial and industrial indicators that would distinguish genuine capitulation from disciplined investment
A credible assessment should focus on observable changes in behaviour rather than the language used by companies to describe their investment strategies. Management may characterise reduced capital expenditure as efficiency, optimisation or disciplined allocation. Such descriptions are not sufficient to determine whether the underlying reason is weaker demand, improved productivity, project delay or a deterioration in expected returns.
The distinction requires examination of expenditure in relation to completed capacity and realised operating performance. A reduction in infrastructure investment accompanied by higher utilisation and improving margins would be economically different from a reduction accompanied by cancellations, declining contracted demand and asset impairments.
Similarly, continued high capital expenditure could indicate commercially justified expansion or an inability to reverse prior commitments. Its interpretation depends on whether incremental investment is producing assets with credible operating returns.
The International Energy Agency’s 2026 assessment explicitly identifies capital-market sentiment as a factor that can influence the pace of data-centre construction, reinforcing the importance of financing conditions alongside electricity and equipment availability. Key Questions on Energy and AI — International Energy Agency — 2026.
For industrial suppliers, changes in the timing of orders may offer earlier evidence than completed financial statements. Reduced demand for certain categories of new construction equipment could indicate project deferrals, while continued expenditure on grid reinforcement or replacement equipment may demonstrate that physical infrastructure requirements remain substantial despite moderation in speculative investment.
The most reliable assessment would therefore combine corporate financial information with project-level commissioning evidence and industrial order data.
Financial and industrial watch indicators
| Indicator | What it tests | Evidence favouring capital contraction | Evidence favouring durable competitive advantage |
|---|---|---|---|
| Capex relative to operating cash flow | Financing sustainability | Investment continues to absorb increasing cash resources without adequate returns | Cash generation increasingly covers productive expansion |
| Infrastructure depreciation relative to relevant gross profit | Operating leverage | Cost recognition outpaces commercial contribution | Margins improve as capacity utilisation rises |
| Commissioned versus planned capacity | Project execution | Growing divergence between announced and operating facilities | High completion rates for commercially credible projects |
| Contracted versus utilised capacity | Demand conversion | Persistent underutilisation or contract revisions | Sustained deployment and profitable utilisation |
| Project cancellations | Investment discipline or demand weakness | Broad withdrawal from projects previously considered viable | Selective removal of economically weak projects |
| Asset impairments | Recoverability of invested capital | Repeated or widespread write-downs | Limited impairment exposure and durable asset productivity |
| Electricity connection completion | Physical execution capability | Connection delays persist across important projects | Secured energisation supports commercial operations |
| Equipment-order composition | Industrial investment trajectory | Reductions concentrated in new development | Continued orders linked to viable projects and upgrades |
| Entry by independent operators | Competitive structure | Financial and grid barriers prevent credible entry | Multiple providers secure financing and infrastructure |
| Realised service pricing and margins | Economic value of scarcity | Competition prevents recovery of costs | Productive capacity earns durable operating returns |
A particularly important analytical distinction concerns the relationship between scarcity and productivity. Higher market prices for computing services may support profitability, but only if demand remains sufficient and the cost of service delivery does not rise proportionately. Similarly, high utilisation may improve operating leverage without establishing attractive returns if the capital required to build the facility was excessive.
Chapter 8 — Key judgments
Partial capital capitulation and renewed oligopoly concentration are credible conditional outcomes of the same infrastructure investment cycle. Their relative significance depends on whether demand, utilisation and commercial margins justify the capital employed, and whether electricity access and financing capacity create durable advantages for existing operators.
A sequential adjustment is possible in which weaker projects are postponed, investment becomes more selective and productive infrastructure becomes concentrated among companies capable of sustaining development. However, concentration creates an economic premium only where it supports durable cash generation or capital productivity rather than simply increasing the cost of infrastructure.
The most consequential distinction is therefore between financially disciplined investment selection and an involuntary contraction caused by deteriorating economics. Reduced expenditure is not necessarily evidence of failure, while continued expenditure is not necessarily evidence of success.
What would change the assessment: Stronger realised returns on productive infrastructure, sustained entry by independent providers and improved connection availability would weaken the concentration pathway. Persistent financing restrictions, inability of new competitors to secure commercially viable capacity and higher returns for established operators would strengthen it.
Open official record: The decisive missing information concerns incremental infrastructure profitability, realised service pricing, the commercial terms governing scarce capacity and the financing conditions faced by credible alternative providers. Without comparable evidence, the extent of any future oligopoly premium cannot be quantified defensibly.
Chapter 9. Strategic Decisions Through the Early 2030s: Capital Allocation, Grid Prioritisation, Supply-Chain Resilience and Market Concentration
The strategic task is to prevent a private investment boom from becoming a durable public infrastructure constraint
The principal policy challenge through the early 2030s is not to determine in advance whether the artificial intelligence investment cycle will produce excessive capacity or insufficient capacity. It is to create financial, regulatory and industrial arrangements capable of accommodating either outcome without unnecessarily weakening electricity security, manufacturing competitiveness or market competition. The distinction matters because the initial investment decisions are taken primarily by private technology companies, while many of the physical consequences extend into electricity networks, industrial supply chains and public infrastructure systems whose development horizons are longer than the commercial planning cycles of the companies generating additional demand.
An 18-month delay in expected economic returns would not justify an automatic government intervention to preserve every announced infrastructure project. Nor would it justify the assumption that private investors should bear every consequence of electricity-network reinforcement where the investment produces demonstrable benefits for the wider system. The appropriate boundary between private and public responsibility depends on the economic function of each asset, the beneficiaries of the expenditure and the risks that can reasonably be allocated through contracts and regulation.
For governments, the central danger is the premature conversion of uncertain private demand into irreversible public infrastructure commitments. Where a large data-centre developer requests substantial additional electricity capacity, the network operator may need to undertake engineering studies, reserve planning resources or develop reinforcement proposals. If the private project is subsequently delayed or abandoned, the public or regulated infrastructure system can remain exposed to expenditure that does not generate the originally expected benefit.
The opposite danger is equally important. If public authorities require unrealistic certainty before undertaking infrastructure development, commercially viable industrial and computing projects may be unable to proceed, even where the eventual network investment would support wider electrification and economic activity.
The policy problem is therefore one of risk allocation and sequencing. Public authorities must distinguish infrastructure that has substantial wider system value from infrastructure whose economic justification depends predominantly on a specific private project. They must also identify which commercial commitments provide credible evidence that the expected demand will materialise.
The European Commission’s June 2026 roadmap recognises this coordination requirement through its proposed tripartite arrangements among data-centre operators, electricity-sector participants and public authorities. The inclusion of project information, connection transparency, operating flexibility, clean-energy procurement and waste-heat recovery reflects a policy approach in which infrastructure integration becomes a negotiated and regulated industrial undertaking rather than simply a conventional commercial electricity purchase. Strategic Roadmap for Digitalisation and AI in the Energy Sector — European Commission — June 2026.
The strategic value of this approach will depend on implementation. Voluntary coordination can improve information exchange but may not resolve disputes over financing, priority or the allocation of scarce capacity. More binding requirements may be appropriate in some circumstances, but they must remain consistent with electricity regulation, competition requirements and the rights of other infrastructure users.
Capital allocation: preserving productive investment while limiting irreversible commitments
The most important financial decision for the hyperscalers is whether the expected return on remaining infrastructure expenditure continues to justify completion and subsequent operation. The relevant economic comparison should be forward-looking. Projects should not continue solely because substantial expenditure has already occurred, but neither should management cancel facilities whose completion would generate benefits exceeding the additional costs required.
The decision becomes more complicated where infrastructure assets possess strategic option value. A site with a credible path to electricity supply may remain attractive even if near-term computing demand develops more slowly than originally expected. The ability to install newer equipment at a later date can preserve economic flexibility, provided the site design and contractual terms permit adaptation without disproportionate additional expenditure.
Conversely, a project dependent on uncertain network reinforcement or inflexible technology commitments may become less attractive as delays accumulate. Its prospective value should reflect not only the expected commercial revenue but the costs of maintaining the development position and the possibility that alternative technologies or locations become more competitive.
A disciplined investment process should therefore distinguish among construction already undertaken, equipment not yet ordered, contractual obligations that can be renegotiated and strategic infrastructure rights that retain value independently of the original project schedule.
For investors, improved disclosure of these distinctions would be more informative than a single aggregate capital expenditure figure. The relevant analysis concerns how much capital remains discretionary, how much is contractually committed, how much supports assets already available for use and how much is dependent on unresolved physical or commercial conditions.
The same principles apply to public participation. Governments should avoid using announced private expenditure as a direct measure of future economic output. A project may be financially committed but physically delayed, commercially underutilised or structured in a way that transfers much of its economic value outside the host jurisdiction.
Public support, where legally and economically justified, should therefore be evaluated against deliverable outcomes rather than investment announcements alone. Such outcomes may include completed infrastructure with wider system benefits, measurable technical capability, additional competitive capacity or the development of industrial skills and manufacturing activities that would not otherwise emerge.
Grid prioritisation: from nominal demand reservations to evidence of project readiness
Electricity-network governance is likely to become one of the most consequential determinants of AI infrastructure competition. Scarce connection capacity has economic value, and rules governing its allocation can affect which projects proceed, which developers retain valuable options and how costs are distributed among electricity users.
A credible prioritisation framework should require evidence of project maturity without assuming that the financially largest developer necessarily offers the greatest economic benefit. The relevant criteria include the credibility of the end user, land and planning status, equipment procurement, financing arrangements, technical readiness and the maturity of associated network works.
These criteria must be applied consistently and proportionately. Requirements designed to exclude speculative projects can create barriers to entry if they impose financial burdens that only incumbents can satisfy. Conversely, insufficient commitment requirements can permit the reservation of scarce capacity without meaningful project progress.
The United Kingdom’s Ofgem consultation provides an operational example through its proposed commitment fees and development milestones. Its relevance lies not in prescribing an identical model for all jurisdictions, but in establishing that network-capacity allocation can incorporate evidence of actual project execution. Proposed Data Centre Connection Reforms — Ofgem — July 2026.
European coordination should also encourage appropriate flexibility. A computing facility able to modify certain operations in response to electricity-system conditions may require a different connection arrangement from a facility demanding uninterrupted firm capacity. However, flexibility must be demonstrated through technical capabilities and enforceable commercial arrangements. It should not be assumed merely because an operator claims that computing workloads can be adjusted.
The relevant policy goal is to increase the productive utilisation of existing and planned infrastructure while maintaining electricity-system reliability and fair access for other users.
Grid allocation and infrastructure policy options
| Policy option | Competent authority or actor | Intended economic effect | Implementation burden | Time to effect | Reversibility | Principal risk |
|---|---|---|---|---|---|---|
| Stronger project-readiness criteria | National regulators and network operators | Reduce speculative connection reservations | Technical and administrative assessment | Potentially within existing planning cycles, subject to legal framework | Rules can be revised; individual commitments may be harder to reverse | Exclusion of viable smaller developers |
| Connection commitment fees | Regulator or network operator under applicable authority | Align requests with credible development intentions | Fee design, collection and enforcement | Following regulatory adoption | Generally adjustable for future applications | Excessive barriers to entry |
| Milestone-based queue management | Network operators and regulators | Release capacity from projects failing to progress | Project monitoring and contractual administration | Depends on queue rules and existing agreements | Partly reversible | Legal disputes and investor uncertainty |
| Flexible connection arrangements | Network operators and consenting customers | Improve use of available grid capacity | Operational controls, metering and contract design | Project-specific | Contractually adjustable where permitted | Reliability or commercial-service constraints |
| Developer-funded reinforcement | Infrastructure developer and network operator | Allocate project-specific costs to beneficiaries | Financing and engineering coordination | Dependent on project construction | Physical investment largely irreversible | Disproportionate costs or inefficient duplication |
| Coordinated regional planning | Transmission operators, governments and regulators | Align computing, industrial and energy development | Cross-sector forecasting and consultation | Medium to long term | Plans adjustable; built assets less reversible | Forecast errors and misallocated investment |
| Transparent connection-capacity reporting | Network operators and competent authorities | Improve investment location decisions | Data governance and confidentiality controls | Potentially earlier than major construction programmes | Highly reversible | Disclosure of commercially sensitive or security-relevant information |
The table deliberately avoids unsupported numerical implementation periods or financial benefits. The timing and cost of each intervention depend on existing national legislation, network conditions and the maturity of individual projects.
Supply-chain resilience: securing alternatives without institutionalising unnecessarily high costs
The European industrial response to AI infrastructure demand should avoid treating domestic manufacturing protection and infrastructure affordability as mutually exclusive objectives. They can conflict in particular circumstances, but a well-functioning industrial supply chain requires both commercially competitive production and reliable access to critical equipment.
The first requirement is a clearer identification of critical dependencies. A strategic inventory should distinguish raw materials, intermediate components, finished equipment, engineering services and maintenance capabilities. It should also differentiate products that are readily substitutable from those requiring extensive technical qualification or network-specific integration.
The second requirement is to examine import competition at the correct level of the value chain. An imported material can strengthen a European finished-equipment manufacturer by reducing input costs, while an imported finished product can compete directly with the same manufacturer. A trade measure addressing the upstream product may therefore affect downstream competitiveness.
The European Commission’s September 2026 provisional safeguards on grain-oriented electrical steel provide an important case. The measures address import pressure on an upstream industrial capability while extending coverage to relevant processed components and certain transformer cores. Their effect should be assessed not only through import reductions or the profitability of the protected producers but also through the availability and competitiveness of downstream transformer manufacturing. Commission Imposes Provisional Safeguard Measures on Imports of Grain-Oriented Electrical Steel — European Commission — September 2026.
A third requirement is to distinguish supply security from the nationality of suppliers. A diversified international procurement structure can provide substantial resilience where alternative suppliers are technically qualified and commercially available. Conversely, a domestic manufacturing operation may remain dependent on a concentrated external source of indispensable materials or specialised technology.
The appropriate industrial objective is to preserve credible substitution options throughout the equipment lifecycle. This includes the availability of replacement components, maintenance capabilities, technical documentation and engineering services.
For Italy, these considerations are particularly relevant to transformers, cables, power electronics and electrical engineering. A national industrial strategy should identify where domestic capabilities can competitively supply infrastructure investment and where international procurement remains necessary. It should also assess whether European manufacturing investment could improve supply reliability without creating inefficient duplication of capacity.
The significance of equipment lead times should not be underestimated. A lower purchase price does not guarantee a lower total infrastructure cost if delivery delays postpone the energisation of economically valuable facilities. Procurement evaluation should therefore incorporate delivery reliability and lifecycle support alongside price and technical conformity.
Market concentration: preserving competitive access without undermining infrastructure investment
The possibility that the 18-month earnings delay reinforces the position of Microsoft, Amazon, Alphabet and Meta creates a competition-policy question that cannot be answered solely through conventional measures of corporate size.
The relevant issue is whether ownership or contractual control of scarce infrastructure creates barriers preventing otherwise viable competitors from entering or expanding. Electricity access, equipment procurement, long-term contracts and financing capacity may all influence entry, but their existence does not automatically establish anti-competitive conduct.
Competition assessment should distinguish legitimate advantages obtained through investment, engineering execution and commercially justified commitments from arrangements that unnecessarily restrict access to essential inputs or exclude viable alternatives.
The design of grid-connection rules is particularly important because electricity infrastructure serves multiple categories of users. A regulatory system should not reserve capacity indefinitely for projects lacking credible development progress, but neither should it establish financial requirements that systematically privilege incumbent hyperscalers where smaller developers can demonstrate commercially sound projects.
Similarly, the evaluation of long-term power agreements and infrastructure arrangements should consider their actual economic effects. Such agreements can provide the certainty necessary to finance new capacity, while particular contractual structures could also create exclusionary consequences depending on the relevant market and available alternatives.
The appropriate response is therefore evidence-based supervision rather than a presumption that concentration is either inherently efficient or inherently harmful.
Market-concentration decision framework
| Observed development | Possible economic interpretation | Competition concern | Relevant policy response |
|---|---|---|---|
| Hyperscalers retain high utilisation while smaller projects are delayed | Advantage from existing productive infrastructure | Barriers to entry from scarce connections | Examine access conditions and project-readiness rules |
| Large operators obtain favourable equipment terms | Economies of scale and procurement capability | Potential dependence of suppliers on concentrated buyers | Monitor supplier diversity and market conditions |
| Long-term electricity agreements expand | Financing certainty for infrastructure | Possible restrictions on alternative access | Examine contract effects under applicable law |
| New entrants fail to obtain connections | Genuine physical scarcity or inefficient allocation | Potential exclusion through queue administration | Transparent, proportionate connection criteria |
| Infrastructure ownership becomes more concentrated | Consolidation of productive assets | Reduced competition in relevant infrastructure markets | Market-specific competition assessment |
| Computing-service margins improve | Greater productivity or stronger pricing power | Possible market power if alternatives are constrained | Analyse prices, costs, substitution and customer choice |
| Smaller developers withdraw projects | Weak project economics or financial barriers | Loss of potentially viable competition | Distinguish speculative exits from exclusion of credible entrants |
These indicators do not establish legal infringements. They identify the evidence necessary to differentiate efficient industrial consolidation from potentially harmful restrictions on competition.
The early-2030s decision horizon: what should be monitored and when
The central difficulty of long-term infrastructure planning is that the relevant financial and physical processes move at different speeds. Corporate investment guidance can be revised relatively rapidly, while network construction, major equipment manufacturing and electricity-system reinforcement may require longer periods. Governments and infrastructure operators must therefore identify decision points at which new evidence should change policy or capital allocation.
The period immediately following the 2026 investment cycle is particularly important for distinguishing investment announcements from executable projects. The relevant evidence includes completed financing arrangements, credible equipment procurement, network agreements and observable progress in construction.
As the hypothetical 18-month return delay develops, financial monitoring should concentrate on operating cash generation, incremental profitability and the commercial utilisation of newly available capacity. A reduction in equity valuations without a corresponding deterioration in project economics would imply a different response from repeated evidence that infrastructure assets cannot produce the expected returns.
Later in the development horizon, attention should shift increasingly towards actual energisation, asset productivity and the effects of technology replacement. Projects initiated during 2026 but dependent on extensive grid reinforcement may remain under development into the early 2030s under the stipulated stress case. Their economic value will depend on whether the original technology and commercial assumptions remain relevant when they become operational.
For Europe, industrial monitoring must proceed throughout this period. Changes in equipment imports, domestic manufacturing capacity and supplier concentration may develop independently of the financial results of individual hyperscalers. A slowdown in speculative data-centre projects could coexist with continued investment in electricity networks and industrial electrification.
The appropriate strategic horizon therefore involves overlapping financial, physical and industrial observations rather than a single future date at which the success or failure of AI infrastructure investment can be conclusively determined.
Strategic decision calendar, 2026–2034
| Period | Principal decision problem | Corporate indicators | Electricity and infrastructure indicators | European industrial indicators |
|---|---|---|---|---|
| 2026 | Establish executable investment commitments | Capex guidance, financing structure, contractual commitments | Connection applications, project maturity, planned reinforcement | Equipment orders, import competition and manufacturing capacity |
| 2027 | Test whether initial return delays are temporary | Incremental operating profit, utilisation and free cash flow | Progress against commissioning milestones | Supplier investment, deliveries and trade-defence outcomes |
| 2028 | Reassess marginal capital allocation | Project deferrals, cancellations and expected returns | Energisation progress and construction delays | Domestic production and import substitution |
| 2029–2030 | Evaluate the quality of operating capacity | Capital productivity, recurring margins and replacement requirements | Completed capacity, network utilisation and flexible-load performance | Equipment availability and supply-chain resilience |
| 2031–2034 | Examine longer-horizon projects and market structure | Returns from later investment vintages and competitive concentration | Completion of projects exposed to prolonged connection horizons | Durability of European industrial capabilities and strategic dependencies |
The dates identify analytical review periods rather than predicted events. The five-to-eight-year connection stress assumption applies only where a project begins the relevant connection process in 2026 and experiences that full duration; it must not be generalised to projects already possessing usable grid capacity.
Policy priorities for Italy, France, Germany, the United Kingdom and the European Union
Italy’s most consequential priority is to integrate data-centre connection planning with industrial electricity requirements and national network development. The concentration of applications in Lombardy makes project credibility and efficient location selection particularly important. A policy based on verified development progress, transparent connection conditions and economically justified reinforcement could reduce the risk that speculative projects obstruct manufacturing investment. At the same time, industrial procurement policy should recognise the importance of domestic manufacturing and engineering capabilities without assuming that all imports undermine national competitiveness.
France’s priority is to convert electricity-related advantages into durable economic value. This requires distinguishing data-centre hosting from technological sovereignty, encouraging projects that can become operational within credible schedules and assessing how new computing demand interacts with wider industrial electrification. The economic benefit of a project should not be inferred solely from the amount of announced investment.
Germany’s priority is to preserve the competitiveness of its manufacturing system while enabling commercially valuable computing infrastructure. Flexible electricity connections may provide opportunities where technically feasible, but they should not substitute for necessary network reinforcement or impose operational requirements inconsistent with the needs of industrial users. Equipment manufacturing and supply-chain resilience remain integral to this calculation.
The United Kingdom’s priority is to improve connection-queue credibility while protecting competitive entry. The proposed commitment fees and development milestones illustrate a possible approach, but their eventual economic effects will depend on whether they distinguish genuinely viable projects from speculative applications without imposing disproportionate barriers on smaller developers.
At European Union level, the priority is to coordinate these different national approaches without creating a uniform system insensitive to local electricity conditions. Common standards, better information and consistent principles of non-discrimination can improve the investment environment, while product-specific industrial measures should preserve the competitiveness of the wider electrical-equipment supply chain.
Final Strategic Net Assessment
The hypothetical 18-month delay in expected returns on the $725–760 billion AI infrastructure investment programme does not lead inevitably to a collapse in technology-sector profitability or to the reinforcement of an entrenched hyperscaler oligopoly. Both outcomes remain conditional on the relationship between commercial demand, infrastructure commissioning, asset productivity, financing conditions and the availability of credible competitors.
The financial transmission begins when capital commitments advance more rapidly than the economic benefits generated by the assets they finance. The physical transmission occurs when electricity connections, equipment procurement and construction schedules determine how quickly those assets can become commercially productive. The industrial transmission develops when changes in infrastructure investment affect manufacturing orders, equipment prices and the competitive position of suppliers across international markets.
These processes can reinforce one another. A prolonged commissioning delay can weaken investment returns, encourage capital expenditure restraint and reduce the ability of financially constrained developers to proceed. If the strongest operators retain commercially productive infrastructure while their competitors encounter greater difficulties obtaining financing or electricity access, market concentration may increase. However, the resulting infrastructure scarcity would create a sustainable economic premium only if it supported durable operating profitability rather than merely increasing the cost of expansion.
Europe’s strategic exposure arises from its position within this system. The continent is simultaneously a prospective host of additional computing infrastructure, a major electricity-equipment manufacturing region and a market exposed to changing international industrial supply. The European Commission’s 2026 energy roadmap and electrical-steel safeguard measures demonstrate that these issues are already entering institutional policy, although the longer-term effects remain uncertain.
For Italy, France, Germany and the United Kingdom, the consequences will depend on national electricity conditions, industrial structures and the credibility of infrastructure planning. Their policy objectives differ, but each faces the same underlying requirement: to convert additional computing demand into productive economic activity without allowing scarce electricity connections, irreversible network expenditure or concentrated equipment dependencies to weaken the wider industrial system.
The most consequential strategic error would be to treat announced AI capital expenditure as equivalent to productive computing capacity, or installed computing capacity as equivalent to profitable economic output. Neither relationship is automatic. Financial resources can secure equipment and initiate construction, but they cannot eliminate the development requirements of electricity infrastructure. Similarly, control of scarce infrastructure can strengthen a competitive position, but it cannot guarantee that customers will pay prices sufficient to justify the capital invested.
The evidence therefore supports a conditional conclusion rather than a deterministic forecast. The financial and industrial architecture of AI is becoming more capital-intensive, more dependent on electricity-system development and more exposed to decisions taken beyond the technology sector itself. These developments create the possibility of an investment correction, increased concentration or a combination in which selective retrenchment precedes renewed expansion by the financially and operationally strongest participants.
The decisive strategic variable through the early 2030s will be the ability to transform committed capital, electricity access and industrial equipment into commercially productive capacity at returns sufficient to sustain further investment. The companies and countries that succeed will not necessarily be those announcing the largest expenditure programmes, but those capable of coordinating finance, infrastructure, manufacturing and commercial demand within credible economic and operational limits.
This is the defining industrial challenge of the emerging AI infrastructure economy: the distribution of market power will depend increasingly on who can deliver productive capacity, not merely who can finance its construction.


