

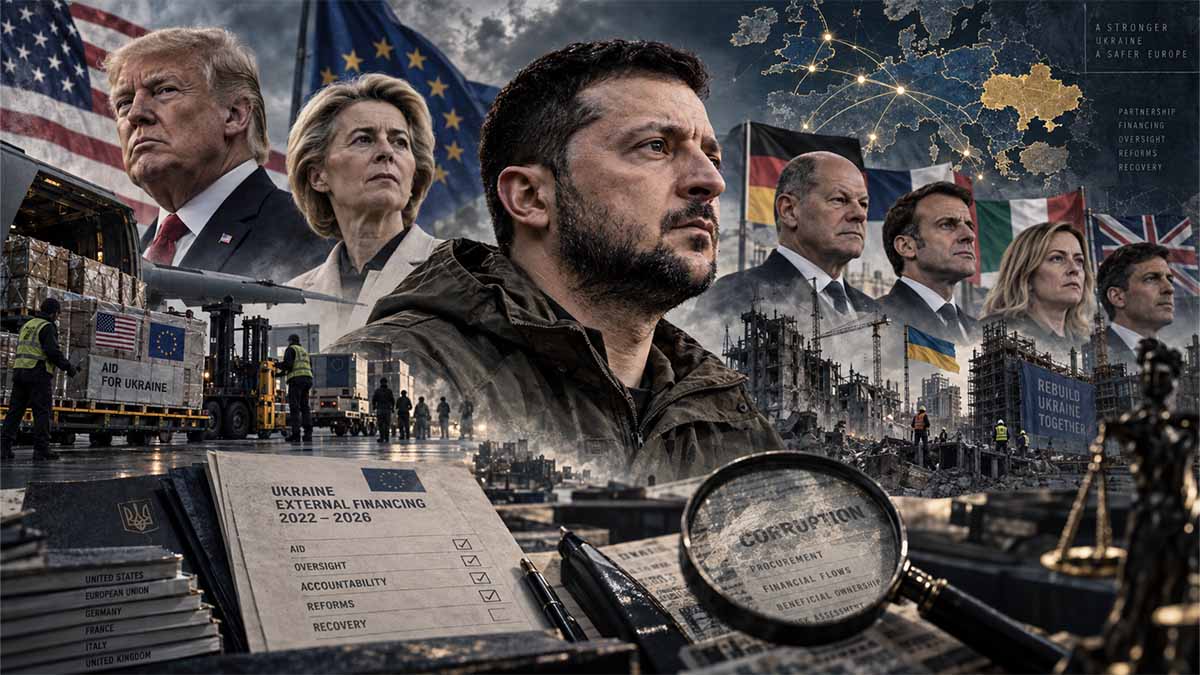
Scope: This assessment maps external financing and military-support channels available to Ukraine from 24 February 2022 through Q3 2026, distinguishes funds that enter Ukrainian public systems from equipment or expenditure controlled abroad, and overlays only corruption cases supported by official records or specifically identified high-quality investigative reporting.
Ukraine Aid Is Becoming a Procurement Test, Not Just a Financing Test
The governing risk in Ukraine’s external-financing system is shifting from whether donors can move money to Kyiv toward whether they can follow that money through procurement, delivery and recovery once it enters Ukrainian institutions. By September 2026, that distinction had become unavoidable: the United States had appropriated more than $174 billion through five supplemental acts, while USAID had disbursed about $30.2 billion in direct budget support; the EU had built a €50 billion Ukraine Facility and a further €90 billion Ukraine Support Loan for 2026–27; and the World Bank had become one of the principal transmission systems for Ukrainian public expenditure. The financing architecture is mature. The weaker link is now the contract: who receives it, who owns the supplier, what was prepaid, what was delivered, and what happens when performance fails.
The headline aid number conceals the real exposure
The first mistake is to treat every dollar or euro announced for Ukraine as money transferred to the Ukrainian state. U.S. congressional appropriations above $174 billion included weapons drawn from American inventories, replacement of U.S. stocks, procurement from American industry, humanitarian programmes and administrative expenditure, while direct budget support managed by USAID reached approximately $30.2 billion between April 2022 and December 2024. U.S. Government Accountability Office — Ukraine: Status and Use of Supplemental U.S. Funding U.S. Government Accountability Office — State Should Build on USAID’s Oversight of Direct Budget Support
Europe creates a different exposure. Under the Ukraine Facility, Pillar I had disbursed approximately €29.5 billion by June 2026, while the new €90 billion Ukraine Support Loan assigns roughly €30 billion to budget support and €60 billion to defence financing. European Commission — Ukraine Facility Council of the European Union — Council finalises €90 billion support loan to Ukraine The fiscal significance is clear: as European financing moves deeper into Ukrainian budget execution and defence production, donor exposure increasingly depends on Ukrainian procurement performance rather than only on allied logistics.
Defence procurement is now the critical transmission point
The most serious 2026 warning comes from defence procurement. Confidential Ukrainian audits reported by The New York Times identified approximately $1.2 billion in fraud, waste and mismanagement in 2024, including contracts awarded to suppliers with prior defaults, suppliers under investigation and cases in which lower-priced offers were reportedly bypassed. The New York Times — In Ukraine, Fraud and Waste Are Rewarded With More Weapons Contracts
That figure is not a court-proven theft total. Its importance lies elsewhere: it indicates that procurement losses can emerge before criminal corruption is established, through poor supplier qualification, unjustified intermediary selection, defective delivery, advances to non-performing contractors and weak recovery of receivables. One reported rocket procurement involved offers of roughly $4,200, $4,600 and $5,100 per unit, with the highest-priced intermediary selected; the additional cost was reported at approximately $130 million. The New York Times — 4 Things We Found in Secret Ukrainian Military Audits
That is the structural problem donors now have to solve. A clean transfer into the Ukrainian budget does not ensure a clean contract, and a competitive tender does not ensure clean acceptance, delivery or payment.
NABU’s cases show where the control chain breaks
The official criminal record reinforces the audit evidence without proving that donor money itself was stolen. In the State Service of Special Communications and Information Protection drone case, NABU and SAPO increased the estimated state loss in August 2026 from UAH90 million to UAH254 million, alleging simulated competition and procurement at prices previously described as 70–90% above market levels. NABU — Corruption in drone procurement: new suspicions in SSSCIP case
A separate State Border Guard procurement worth approximately UAH825 million generated an alleged $1 million bribe demand connected with smooth execution and acceptance of UAV supplies; by 23 September 2026, investigators had added allegations involving 50,000 USDT and more than UAH15.4 million converted into cryptocurrency. NABU — USD 1 million for unhindered drone supplies NABU — New suspicions in drone supply case
Another August 2026 case involved an alleged 20% kickback, UAH4.48 million, demanded for acceptance of electronic-warfare systems under a contract worth more than UAH22.4 million. NABU — UAH4.5 million for acceptance of electronic warfare systems These proceedings remain allegations, not final convictions, but collectively they identify the vulnerable stages with unusual precision: supplier selection, price formation, contract execution and acceptance.
Energoatom shows that corruption can begin after the tender is over
The Operation Midas investigation adds a different mechanism. NABU alleges that Energoatom contractors were required to surrender up to 15% of contract value to obtain payment or preserve supplier status, creating what investigators described as a barrier or tollgate system. NABU — NABU and SAPO results for H2 2025
By 2026, investigators alleged that more than $112 million in cash had passed through a trusted person during the period under investigation; another strand involved more than UAH460 million allegedly laundered through elite construction, while a former Energoatom security executive was suspected of laundering more than UAH30 million through vehicles and property. NABU — H1 2026 investigation report NABU — Operation Midas: new suspect
None of these figures has been established as a final criminal judgment, and the public record does not trace them to a named U.S., EU or IFI tranche. Their significance is institutional: a procurement system can satisfy formal tender rules and still be corrupted later if officials can control invoice payment, supplier status or contract acceptance.
Conditionality exists, but audit closure is weaker than audit production
Donors have not financed Ukraine without conditions. The European Union tied Ukraine Facility payments to reform steps under the Ukraine Plan, and by 24 September 2026 the Council reported that Ukraine had completed 84 of 95 steps then due, approximately 88%, while approving an eighth regular payment of nearly €3 billion. Council of the European Union — Ukraine support: Council approves payment of nearly €3 billion
The IMF’s $8.1 billion Extended Fund Facility follows a parallel logic. In July 2026 all end-March quantitative performance criteria had been met, but several structural reforms were delayed or missed; a benchmark requiring risk-based verification of senior officials’ asset declarations was reset toward end-September rather than abandoned. International Monetary Fund — First Review of the Extended Fund Facility and 2026 Article IV Consultation
The U.S. record is less comfortable. GAO found 161 unusual increases among 5,121 expenditure changes examined in direct-budget-support data and had five recommendations still open during its 2026 follow-up, covering anomaly investigation, congressional reporting, control weaknesses and remediation. U.S. Government Accountability Office — State Should Build on USAID’s Oversight of Direct Budget Support Oversight therefore exists; the unresolved issue is whether findings close quickly enough to alter subsequent payment and contracting decisions.
Russian-asset financing raises the standard, not just the amount
The G7 Extraordinary Revenue Acceleration mechanism adds another layer because approximately €45 billion of financing is serviced through extraordinary revenues generated by immobilised Russian sovereign assets, including an EU contribution of up to €18.1 billion. European Commission — Ukraine: Macro-financial assistance and ERA loans
This architecture requires four reconciliations rather than one: the immobilised principal, the extraordinary revenues generated, the loans serviced from those revenues and the Ukrainian expenditure ultimately financed. By 2026 the Council included approximately €3.8 billion from proceeds on immobilised Russian assets within the wider EU support architecture. Council of the European Union — Russia’s war against Ukraine
For budget committees, that creates a higher evidentiary standard. Money derived from sanctioned sovereign assets carries both legal and political sensitivity, and weaknesses in downstream procurement would therefore damage not only Ukrainian fiduciary credibility but the legitimacy of the financing mechanism itself.
The next 24 months will be decided by traceability
The next phase of support will expose donors to larger Ukrainian-controlled procurement flows at exactly the moment when the 2024–26 audit record has identified weaknesses in supplier performance, advance payments and contract enforcement. The practical answer is not another general oversight body but a common transaction chain linking donor instrument, Ukrainian budget programme, contracting authority, supplier beneficial owner, advance paid, value delivered, outstanding receivable, audit finding and recovery status.
The cost of failing to build that chain over the next 12–24 months will be distributed unevenly. Ukraine will pay first through slower procurement, higher financing friction and pressure on reconstruction credibility; European governments will pay through greater parliamentary resistance to new commitments; U.S. oversight institutions will carry growing difficulty distinguishing genuine anomalies from political claims; and defence suppliers with clean performance records will bear the cost of operating inside a system where reliable and unreliable contractors are not yet separated transparently enough.
The issue is no longer whether Western support can be mobilised. The evidence through September 2026 shows that it can. The question is whether the next euro can be followed all the way from appropriation to delivered output — and, when something fails, all the way back to the party responsible.
Navigational Index
Pillar I — Architecture of External Financing and Fund Transmission
Donor-by-donor financing map; U.S., EU, G7 bilateral and IFI structures; committed versus disbursed amounts; grants, loans and guarantees; military, budget and humanitarian channels; proportion of assistance entering Ukrainian public systems; money-flow mechanics and control points.
Pillar II — Corruption Exposure, Procurement Leakage and Verified Investigations
Defence procurement; DPA contract performance; NABU/SAPO/HACC proceedings; Energoatom and Operation Midas; border-service and UAV procurement cases; infrastructure and SOE exposure; distinction between alleged losses, suspicions, indictments, court findings and proven donor-fund tracing.
Pillar III — Donor Accountability, Conditionality and Forward Controls
U.S. and EU oversight models; World Bank and IMF safeguards; Ukraine Facility conditionality; immobilised Russian-asset proceeds; emergency-procurement vulnerabilities; counter-disinformation safeguards; traceability, audit and procurement-transparency recommendations.
Executive Brief
The central finding is that the proposition that Western governments have transferred a single, fungible pool of “Ukraine aid” into Ukrainian government hands is structurally wrong. External support since February 2022 has operated through several fundamentally different architectures: equipment transferred directly from allied inventories; weapons purchased by donor governments or multinational mechanisms; reimbursement and procurement mechanisms; grants and concessional loans to Ukraine’s Treasury; World Bank reimbursement of eligible civilian expenditure; direct investment and guarantees for state-owned enterprises and private companies; humanitarian spending implemented by international organisations; and, increasingly, financing backed by proceeds generated from immobilised Russian sovereign assets.
The United States illustrates the distinction particularly clearly. Congress had appropriated more than $174 billion under five Ukraine supplemental acts by April 2024, but that figure was never equivalent to cash transferred to Kyiv: substantial portions financed replacement of U.S. weapons stocks, U.S. military activity, procurement from American industry, humanitarian operations and other U.S.-administered expenditure. GAO reported that, of the first approximately $113.4 billion appropriated under the initial supplemental acts, agencies had obligated approximately $101.2 billion and disbursed approximately $67.5 billion by 31 December 2023. GAO — Ukraine: Status and Use of Supplemental U.S. Funding
The largest clearly identifiable U.S. channel entering or reimbursing the Ukrainian public budget was direct budget support. USAID disbursed approximately $30.2 billion between April 2022 and December 2024; separately, the U.S. Treasury disbursed $20 billion to the World Bank in December 2024 for economic assistance, including $15 billion intended for direct budget support. GAO — Oversight of Direct Budget Support to Be Provided by State Should Be Enhanced USAID OIG subsequently concluded in March 2026 that deficiencies in contractor deliverables weakened the assurance available to USAID regarding part of its PEACE oversight architecture, although the audit did not conclude that the $30.7 billion obligated for direct budget support had been stolen or diverted. USAID OIG — Direct Budget Support: Oversight Mechanisms Provided Limited Assurance
The European financing model has become still more consequential. By 25 September 2026, the Council reported €42 billion mobilised through the Ukraine Facility, whose regular payments are tied to reform and investment steps under the Ukraine Plan. Council of the EU — The Ukraine Facility Between 2022 and 2026, EU macro-financial assistance reached €43.3 billion, while the broader EU/Member State support architecture was reported by the Council at €224.5 billion, including financial assistance, military support, refugee expenditure and €3.8 billion from proceeds on immobilised Russian assets. Council of the EU — EU financial assistance to Ukraine Council of the EU — Russia’s war against Ukraine
Three residual risks dominate the architecture.
First, procurement-performance risk is materially greater than the narrower question of classic bribery. Wartime contracting creates exposure through advances for undelivered goods, defective materiel, supplier concentration, repeated contracting with underperforming vendors, inflated pricing and non-competitive procedures. The distinction matters because each category requires different remediation and because “loss”, “waste”, “suspected embezzlement” and “court-proven theft” are not interchangeable.
Second, state-system concentration risk has risen as donors have moved from emergency in-kind assistance toward Treasury support, Ukrainian defence-industry procurement, energy reconstruction and large infrastructure financing. The more financing is spent inside Ukrainian institutions, the greater the need for contract-level traceability, beneficial-ownership verification, delivery verification and interoperable donor–Ukrainian audit data.
Third, institutional credibility risk now operates in both directions. Genuine NABU/SAPO investigations demonstrate substantial corruption exposure, particularly in defence, energy and public procurement; simultaneously, cloned media sites and AI-generated content can manufacture spectacular fictitious seizures which then contaminate legitimate scrutiny. The evidentiary response must therefore be stricter rather than more permissive: allegations, suspicion notices, indictments and final judgments must remain separate categories.
The public evidence reviewed for this assessment does not establish that corruption has captured the entire foreign-aid pipeline, nor does a documented procurement fraud prove that the underlying money originated from a particular foreign donor. Conversely, the scale of external financing and the number of official corruption investigations make it equally untenable to dismiss fiduciary risk as marginal.
Financing Map
Figures below deliberately preserve the definitions used by issuing institutions. National totals, EU totals, Kiel allocations and IFI financing cannot be mechanically added because they frequently overlap.
| Donor / mechanism | Public commitment or mobilisation baseline | Disbursement / delivery evidence | Principal form | Main control conditions |
|---|---|---|---|---|
| United States — overall supplementals | >$174bn appropriated under five supplemental acts by Apr. 2024. GAO Ukraine Oversight | For first ~$113.4bn: ~$101.2bn obligated and ~$67.5bn disbursed by 31 Dec. 2023. GAO funding-status report | Military procurement, U.S. stock replenishment, DBS, humanitarian, economic and operational expenditure | Congressional appropriations, DoD/State/USAID IGs, GAO, end-use controls |
| United States — direct budget support | USAID obligated about $30.7bn in FY2022–24. USAID OIG March 2026 audit | USAID disbursed about $30.2bn Apr. 2022–Dec. 2024; Treasury later provided $20bn to World Bank, including $15bn intended for DBS. GAO direct-budget-support report | Grants / reimbursed civilian expenditure, primarily through World Bank mechanisms | PEACE expenditure verification, World Bank controls, independent monitoring and U.S. oversight |
| United States — security assistance | $65.9bn military assistance since 24 Feb. 2022 as of 9 Jan. 2025. State Department security-cooperation fact sheet | Equipment deliveries and USAI contracting occur on different schedules; commitment ≠ delivery | PDA inventory transfers, USAI procurement, FMF and associated support | End-use monitoring, contract oversight, DoD OIG, Special IG/OAR reporting |
| European Union — Ukraine Facility | >€50bn framework for 2024–27, approximately €33bn loans and €17bn grants. Council — Ukraine Facility | €42bn mobilised by 24 Sept. 2026 according to Council. Council — Ukraine Facility | Budget financing, investment and technical assistance | Ukraine Plan milestones, rule-of-law and anti-corruption conditions |
| EU — MFA | €43.3bn in macro-financial assistance during 2022–26. Council — EU financial assistance to Ukraine | Multiple MFA/MFA+ and later support-loan tranches disbursed | Primarily concessional loans plus some grants | Macroeconomic policy and reform conditionality |
| EU — Ukraine Support Loan 2026–27 | €90bn, with indicative €30bn economic and €60bn defence components. Council — EU financial assistance | By 30 July 2026 defence-window disbursements included €3.9bn, €1.1bn and €3.47bn; first MFA instalment €3.2bn on 25 June. European Commission — Support to Ukraine | EU borrowing backed by EU budget; defence procurement plus budget support | Financing strategy, procurement eligibility, monitoring and expenditure conditions |
| EU — EPF | €6.4bn mobilised in 2022–25 under the EPF according to current Council military-support accounting; broader Ukraine Assistance Fund ceiling decisions are separately reported. Council — EU military support | Equipment, ammunition, fuel, training and reimbursement mechanisms | Off-budget military assistance | Member-state reimbursement rules and EPF governance |
| EU / G7 ERA | G7 ERA architecture approximately €45bn; EU MFA component €18.1bn. European Commission — ERA MFA disbursement | Disbursements staged from 2025 onward | Loans serviced by extraordinary revenues from immobilised Russian sovereign assets | G7/EU legal framework, asset-income accounting and loan administration |
| Germany | >€43.3bn bilateral civilian support plus around €57.6bn military support provided or planned, Aug. 2026 German government tally. Federal Government — Germany’s support for Ukraine | Official total combines delivered assistance and future commitments; not equivalent to cash transfers | Military equipment/procurement, civilian, humanitarian, reconstruction | German budget and procurement controls; EU-linked reform conditions where applicable |
| United Kingdom | £25bn total: £16bn military, up to £5.6bn non-military, £3.5bn export-finance cover. UK Government Ukraine support factsheet | £4.1bn of fiscal-support guarantees sit within non-military total; military support combines actual and multi-year commitments | Equipment, procurement, guarantees, humanitarian and reconstruction | UK budget scrutiny, World Bank guarantees, procurement controls |
| France | France does not publish, in the official material examined here, a single consolidated 2022–Q3 2026 figure directly comparable to German or UK totals | Assistance includes transferred systems, procurement, training and bilateral defence-industrial arrangements | Predominantly military plus humanitarian/economic channels | French budget and defence-procurement controls; EU conditionality for EU-financed channels |
| Canada | >C$25.5bn overall support, including C$8.5bn military, Feb.–Aug. 2026 official baseline. Government of Canada — support four years after invasion | Mix of financial, equipment, humanitarian and development expenditure | Grants, military procurement/equipment, financial assistance, ERA contribution | Canadian appropriations, departmental controls, multilateral mechanisms |
| Japan | Major financial donor, including participation in the G7 ERA architecture; cross-donor Kiel reporting recorded about €2.8bn ERA allocation in the referenced 2025 update. Kiel — Europe now leading spender on weapons production for Ukraine | Primarily macro-financial, reconstruction and humanitarian rather than lethal military aid | Loans, grants, guarantees, World Bank-linked finance | IFI and Japanese public-finance controls |
| Netherlands | Official 2022–26 programme includes €5.3bn budget support, €1.4bn recovery/reconstruction, and €220m emergency/protection among other categories. Government of the Netherlands — Assistance to Ukraine 2022–2026 | Budget support and project financing coexist with substantial military aid | Budget support, military equipment/procurement, reconstruction | Dutch budget/procurement controls and multilateral safeguards |
| Denmark | Approx. €10.3bn military plus €1.1bn civilian support by 13 Aug. 2026, excluding Danish EU contributions. Danish Foreign Ministry — Danish support for Ukraine | Civil figure includes about €823m granted and €291m guarantees | Military, grants, guarantees, reconstruction | Danish Ukraine Fund and programme controls |
| Sweden | Approx. SEK156bn, including SEK128bn military and SEK28bn civilian, by 12 Aug. 2026. Government of Sweden — Sweden’s support to Ukraine | Military total includes packages and procurement; civilian includes humanitarian and budget support | Military equipment, procurement, civilian assistance | Swedish budget and programme oversight |
| Finland | Defence materiel delivered reached about €3.6bn by 15 Sept. 2026. Finnish Government — 34th defence assistance package | Finnish official figure explicitly refers to defence materiel delivered | Primarily in-kind and procured defence materiel | Finnish state procurement and security controls |
| Estonia | €1.41bn provided/planned for 2022–27; about €820m bilateral military support including related costs. Estonian MFA — Estonia’s support to Ukraine | Military assistance plus financial/humanitarian channels | Equipment, procurement, financial assistance | National budget, NATO/EU mechanisms |
| Latvia | €1.13bn state and societal support through 26 May 2026. Latvian MFA — Latvia supports Ukraine | Includes several categories whose definitions are not identical to bilateral-budget trackers | Military and civilian | Latvian and multilateral controls |
| Lithuania | Significant bilateral and multi-year military assistance; comparable delivered/committed separation remains less complete in official consolidated public reporting | Predominantly military plus rehabilitation and civilian aid | Equipment, procurement, training | Lithuanian national controls |
| Poland | Military donations actually carried out valued at PLN16.45bn by 6 July 2026. Polish Ministry of National Defence — donations to Ukraine | Figure is delivered-donation cost, not total Polish Ukraine-related fiscal expenditure | Predominantly equipment plus logistics/training | Polish MoD and state-budget controls |
| IMF | Current 48-month EFF $8.1bn | $2.2bn disbursed by 20 July 2026 after first review. IMF — First Review of 2026 EFF | Balance-of-payments / macroeconomic loan | QPCs, structural benchmarks, governance, SOE, fiscal, AML/CFT and anti-corruption measures |
| World Bank | $91bn mobilised for Ukraine as of 31 Aug. 2026 across World Bank and donor-linked mechanisms; PEACE alone reported at $53.5bn mobilised. World Bank — Financing Mobilized for Ukraine | Reimbursement/project disbursement varies by instrument | Budget reimbursement, grants, loans, guarantees, reconstruction | PFM controls, expenditure eligibility, verification and project procurement |
| EBRD | Wartime investments reached €10.5bn by June 2026. EBRD — wartime Ukraine support surpasses €10.5bn | Earlier 2025 total deployment €9.1bn; much directed to private sector, SOEs and energy | Loans, guarantees, grants, trade finance | EBRD project appraisal, procurement, covenants and donor guarantees |
| EIB Group | >€4bn EU-guaranteed financing delivered since 2022 by Feb. 2026. EIB — record €1.5bn in 2025 | €1.5bn new financing in 2025 | Infrastructure, energy, municipalities, SMEs | EIB procurement, EU guarantees, project controls |
The table demonstrates why aggregate donor comparisons require caution. Germany’s headline figure, for example, includes future military commitments, Poland reports cost of completed military donations, the United States reports congressional appropriations and agency obligations separately, the World Bank reports financing mobilised from donors as well as its own instruments, and Kiel deliberately distinguishes commitments, allocations and disbursements because governments disclose deliveries less consistently than pledges. Kiel Ukraine Support Tracker data and methodology
What Actually Enters Ukrainian State Systems
A precise universal percentage is not supportable because donors publish incompatible accounting categories. The following classification therefore describes exposure to Ukrainian spending systems, not a forensic assertion that every euro or dollar physically entered a Ukrainian bank account.
| Financing stream | Approximate exposure to Ukrainian public systems | Principal Ukrainian node | Audit implication |
|---|---|---|---|
| U.S. PDA transfers from U.S. inventories | Very low | Ukrainian armed forces receive materiel rather than appropriated cash | Main exposure is custody, diversion and end-use rather than Treasury theft |
| U.S. USAI / allied foreign procurement | Low–medium | MoD/end user influences requirements; donor normally contracts or finances procurement | Supplier-performance and end-use monitoring dominate |
| U.S. PEACE / direct budget support | Very high after World Bank verification/reimbursement architecture | Ministry of Finance / Treasury and eligible civilian payroll/social expenditure | PFM, beneficiary and expenditure verification |
| EU Ukraine Facility budget financing | Very high | Ministry of Finance and reform-linked spending architecture | Milestone verification, audit, procurement and anti-fraud controls |
| EU Ukraine Support Loan defence window | High where Ukraine conducts eligible defence procurement | Ukrainian MoD/DPA/defence industry | Contract, supplier, beneficial-ownership and delivery verification |
| EPF reimbursement of Member States | Low | Equipment delivered to Ukrainian forces | End-use and Member State reimbursement controls |
| ERA budget-support loans | High | Ukrainian public finances | Debt, expenditure and Russian-asset-income accounting |
| EIB / EBRD sovereign and SOE projects | Medium–high | Ukrzaliznytsia, Naftogaz, municipalities, infrastructure agencies and other borrowers | Project procurement and loan covenants |
| Humanitarian expenditure through UN/NGOs | Low–medium | Some local implementing partners; generally outside central Treasury | Implementer and beneficiary controls |
| Bilateral in-kind weapons | Low | Armed forces / logistics commands | End-use, inventory and battlefield-loss accounting |
| Ukrainian defence-industry procurement financed by donors | High | MoD/DPA/other defence procurement entities and Ukrainian manufacturers | Highest need for contract-performance transparency |
This distinction is indispensable when evaluating corruption risk. A bribe attached to a Ukrainian municipal drone purchase does not demonstrate diversion of a U.S. Presidential Drawdown package; conversely, a donor-financed budget reimbursement can be exposed to manipulation in Ukrainian payroll, beneficiary or procurement systems even though the initial transfer passed through a World Bank trust fund.
How the Money Moves
The canonical chain is:
donor appropriation or borrowing authority → donor ministry, implementing agency, EU institution or IFI → Treasury transfer, reimbursement mechanism, procurement fund or designated borrower → Ukrainian ministry/SOE/local authority or foreign procurement agency → contractor or beneficiary → verified end use.
The chain changes materially according to the instrument.
Under Presidential Drawdown Authority, the United States does not normally wire the headline valuation of a weapons package to the Ukrainian Ministry of Finance. Equipment is drawn from U.S. inventories and delivered, while appropriated funds can finance replenishment of U.S. stocks. This is one reason the $174 billion U.S. appropriations figure cannot be treated as $174 billion received by Kyiv. GAO explicitly identifies DoD expenditure on missiles, ammunition, combat vehicles and replacement of American stocks within the Ukraine-response appropriations. GAO — Ukraine Oversight
USAI uses another architecture: contracts are placed for equipment, services or capabilities rather than relying exclusively on immediately available U.S. stocks. Ukraine is the intended recipient, but much of the expenditure occurs through foreign—principally U.S.—industrial and contracting systems.
PEACE operates differently. The World Bank reimburses eligible Ukrainian civilian public expenditures after prescribed verification. USAID OIG stated that 84% of USAID direct budget support examined in its March 2026 audit had gone through PEACE, and that USAID additionally contracted Deloitte and KPMG for monitoring. The OIG’s criticism concerned weaknesses and delays in receiving some monitoring deliverables, which reduced the level of assurance available before further releases; it did not establish that the PEACE portfolio itself had been embezzled. USAID OIG direct-budget-support audit
The Ukraine Facility is closer to a reform-conditioned sovereign financing system. Payments depend upon implementation of the Ukraine Plan, which covers public administration, rule of law, anti-corruption and investment-related measures. On 30 July 2026 the Council amended the Plan to incorporate more than €8 billion of additional 2026 financing and introduced additional reform steps concerning rule of law and anti-corruption. Council — amendment of Ukraine Plan, 30 July 2026
The new EU Ukraine Support Loan creates an additional route because substantial defence financing is intended for procurement from Ukrainian and European industry. Unlike an allied stock transfer, this architecture can cause very large externally financed flows to intersect directly with Ukrainian procurement institutions and contractors. That increases Ukraine’s defence-industrial capacity but also makes contract-performance information more important to donor fiduciary assurance.
The IMF provides macroeconomic financing rather than procurement reimbursement. Its controls are therefore structurally different: quantitative performance criteria, prior actions and structural benchmarks influence access to tranches. In July 2026 the Fund said programme performance was broadly satisfactory but that reform implementation had slowed, with several structural benchmarks delayed or missed. Governance, anti-corruption, SOE reform, public-investment management and energy-sector reform remained explicit programme priorities. IMF 2026 Article IV and EFF First Review
Control Architecture
There is no Ukrainian equivalent of the former U.S. Special Inspector General for Afghanistan Reconstruction with universal jurisdiction over every donor dollar. Instead, oversight is distributed.
For U.S. programmes, the DoD, State and USAID Inspectors General operate jointly through Ukraine oversight arrangements, while GAO provides congressional audit and evaluation. The Special Inspector General reporting framework for Operation Atlantic Resolve was producing quarterly reports in February, May and August 2026. DoD OIG — Ukraine / Operation Atlantic Resolve reports
On the Ukrainian side, NABU investigates high-level corruption within its statutory jurisdiction; SAPO directs and prosecutes corresponding cases; and the High Anti-Corruption Court, HACC, adjudicates qualifying cases and pre-trial measures. A NABU notice of suspicion is therefore an important procedural event but is not a conviction.
EU controls combine Commission verification, Ukraine Facility milestones, audit rights, anti-fraud mechanisms, public-financial-management requirements and political decisions by the Council concerning payment tranches. The IMF superimposes its own conditionality, while the World Bank, EBRD and EIB maintain separate procurement and project-control systems.
The architecture is layered, but layering does not automatically create completeness. Multiple institutions can audit different portions of the same financial ecosystem while still leaving gaps at the point where a public entity chooses a supplier, certifies delivery, modifies a contract or accepts defective goods.
Verified Corruption and Leakage Cases
Defence procurement: drone procurement through SSSCIP
In October 2025 NABU and SAPO announced a case concerning procurement of DJI Mavic 3 and Autel Evo Max 4T drones by the State Service of Special Communications and Information Protection. NABU alleged that controlled companies simulated competition and supplied drones at prices 70–90% above market levels, initially producing estimated state losses above UAH90 million. More than $4 million in foreign accounts and UAH17 million domestically were frozen according to NABU. NABU — Corruption in defence sector: UAH90m drone procurement scheme
By 13 August 2026, additional evidence had caused NABU and SAPO to increase the alleged loss figure to UAH254 million and update suspicion notices. NABU — UAH254m drone procurement scheme: new facts disclosed
Legal status: suspicion / ongoing criminal proceedings, not final conviction.
Donor-fund attribution: the public NABU release identifies Ukrainian state procurement funds but does not establish that a particular U.S., EU or bilateral donor tranche financed the corrupt contracts.
Local-government UAV and electronic-warfare procurement
NABU and SAPO reported in April 2026 that they had completed the investigation into an organised group alleged to have misappropriated local-government funds allocated to UAV and electronic-warfare systems for the Defence Forces. The suspects included a former regional-administration head, a member of parliament, military/local officials and private-company representatives. NABU — Corruption in procurement of UAVs and electronic warfare systems
Legal status: pre-trial investigation completed and materials disclosed to the defence; this is not a conviction.
Donor attribution: the official statement describes local public money, not traced foreign-aid funds.
State Border Guard drone procurement
On 29 May 2026, NABU and SAPO announced that a State Border Guard Service official and a drone-company owner were suspected in an alleged demand for $1 million connected with a proposed UAH825 million UAV procurement. NABU — USD1 million for unimpeded supply of drones
On 23 September 2026 NABU stated that the investigation had identified an additional alleged transfer of 50,000 USDT, valued at more than UAH2.1 million, and alleged conversion of more than UAH15.4 million into USDT by the official between January and April 2026. NABU — USD1M for unhindered drone supplies: new charges
Legal status: notices of suspicion; presumption of innocence applies.
Donor attribution: not publicly established.
Dynamic protection for armoured vehicles
NABU and SAPO reported on 22 July 2026 that the pre-trial investigation into alleged misappropriation of approximately UAH102 million during procurement of dynamic protection for Ukrainian armoured vehicles had been completed. The underlying Ministry of Defence contract dated to April 2022. NABU — UAH102m dynamic-protection case
Legal status: investigation completed before referral to court; no conviction established by that release.
Wider 2024 defence-procurement loss estimates
A separate evidentiary category concerns the September 2026 reporting on confidential Ukrainian government audits. Ukrainian Pravda, summarising a New York Times investigation, reported that the audit material reviewed by the newspaper estimated around $1.2 billion in 2024 losses associated with fraud, waste and mismanagement in defence procurement, including repeated contracting with suppliers that had failed earlier obligations. Ukrainska Pravda — NYT reporting on 2024 procurement losses
This figure must not be reclassified as a court finding. It is investigative reporting based on non-public audit material. “Fraud”, “waste” and “mismanagement” also describe different legal and accounting phenomena, and the $1.2 billion figure should not be presented as $1.2 billion proved stolen.
NABU Director Semen Kryvonos had separately said in October 2025 that potential losses involved in defence-related cases being investigated by NABU reached approximately UAH12.5 billion. That was the value appearing in criminal investigations, not a final judicial assessment of actual state losses. Ukrainska Pravda — NABU director on defence-case exposure
These two figures should therefore remain analytically separate.
Operation Midas and Energoatom
Operation Midas concerns an alleged criminal organisation influencing procurement and payment relationships around Energoatom. According to NABU reporting, investigators allege that counterparties faced demands for kickbacks through a so-called “barrier” mechanism, under which refusal to make illicit payments could result in payments being blocked or supplier status threatened.
NABU’s first-half 2026 reporting states that the high-profile investigation expanded to a former energy minister and that investigators attributed more than $112 million in cash passing through a trusted person to proceeds from alleged illegal activity associated with the energy sector. NABU — Investigation report, first half 2026
In July 2026 NABU announced another suspicion against a former Energoatom security executive, alleging laundering of more than UAH30 million, including expenditure on luxury vehicles and property in Ukraine and Bali. NABU — Operation Midas: new suspect
The public case record also describes an associated alleged laundering scheme exceeding UAH460 million, part of which NABU says was derived from the Energoatom corruption mechanism. NABU — H1 2026 results
Legal status: these are active investigations and allegations by prosecutors/investigators. The public evidence reviewed here does not support describing Operation Midas defendants collectively as convicted.
Foreign-aid attribution: Energoatom and the wider Ukrainian energy sector receive extensive international financing, but the existence of donor financing in the sector is not equivalent to proof that a specific corrupt payment came from a named donor tranche. The public NABU releases reviewed here do not establish that chain.
That distinction is particularly important because EBRD and bilateral donors separately finance emergency energy purchases and infrastructure. For example, Norway’s latest EBRD-linked package included an €85 million grant for Naftogaz, complementing an EBRD loan of up to €500 million for emergency gas purchases. EBRD — Norway grant for Ukraine energy security The existence of such financing should trigger strong safeguards, not an inference that it funded unrelated alleged corruption.
Ukrzaliznytsia
NABU has also investigated procurement schemes involving the state railway. In one case it alleged losses above UAH140 million through inflated cable and wiring procurement, with eight people notified of suspicion. NABU — Corruption in cable procurement for Ukrzaliznytsia
Again, Ukrzaliznytsia’s access to EIB, EBRD and donor financing does not in itself prove that those external funds financed the allegedly corrupt purchases.
Frontline heating and water reconstruction
In November 2025 NABU and SAPO alleged that an organised group misappropriated more than UAH140 million intended for heating and water projects in frontline settlements in Donetsk region. According to NABU, controlled procurement, inflated costs, inadequate project documentation and false completion certification formed part of the alleged mechanism. NABU — heating and water procurement case
This case demonstrates why reconstruction finance requires controls not only at tender award but also at physical completion and asset functionality.
What Has Not Been Proven
The evidentiary record does not establish that:
- a fixed percentage of total Western aid has been stolen;
- the $174 billion U.S. congressional appropriation was transferred as cash to the Ukrainian government;
- every documented Ukrainian procurement loss involved U.S. or EU money;
- the reported $1.2 billion 2024 defence-procurement loss estimate represents $1.2 billion of criminal theft established by a court;
- alleged participants in Operation Midas are guilty merely because NABU or SAPO issued suspicion notices;
- corruption in Energoatom demonstrates corruption across all externally financed Ukrainian energy programmes;
- an isolated seizure of cash, even where genuine, establishes systemic capture of an entire donor pipeline.
These distinctions are not semantic. They determine what a parliamentary oversight body can responsibly conclude.
Donor-Side Responsibility
Emergency procurement creates a predictable control trade-off
Wartime procurement compresses tender periods, permits classified requirements, narrows public disclosure and sometimes requires direct negotiation with suppliers capable of rapid delivery. Those exceptions can be operationally justified while simultaneously increasing fiduciary exposure.
The critical control question is therefore not whether emergency procurement should ever be non-competitive, but whether the emergency justification survives after the immediate urgency has passed. A waiver originally justified by imminent battlefield need becomes materially different when renewed for multi-year recurring purchases.
The known cases suggest that supplier-performance history deserves as much attention as bid price. A vendor that repeatedly fails to deliver, supplies unusable equipment or remains in contracting pipelines despite unresolved performance problems creates a loss channel independent of bribery.
U.S. and EU oversight architectures diverge
The United States historically placed a higher proportion of support into military assistance, stock replenishment and procurement channels, creating extensive DoD/State/USAID IG and GAO reporting around appropriations, contracting and end use.
The European Union increasingly operates as Ukraine’s principal sovereign budget and reform financier. The Ukraine Facility, MFA architecture and 2026–27 Support Loan consequently bind financing more explicitly to macroeconomic and institutional milestones.
Neither approach eliminates corruption risk. They expose different surfaces.
The American model is particularly vulnerable to contract administration, valuation, delivery and end-use weaknesses across a very large defence-support ecosystem. The European model bears greater exposure to Ukrainian state capacity, public-financial management, sector reform and domestic procurement because more financing is designed to support the Ukrainian budget or procurement from Ukrainian industry.
Conditionality has been enforced, but not mechanically
The IMF’s July 2026 review is instructive. All end-March quantitative performance criteria had been met, but several structural reforms had been delayed or missed; rather than terminate the programme, the Fund agreed corrective actions and revised timelines while preserving governance, anti-corruption, energy and financial-sector objectives. IMF — First Review and Article IV Consultation
The detailed IMF staff report went further, noting that anti-corruption reform momentum had slowed in several areas and recording missed or delayed benchmarks, including a benchmark related to risk-based verification of senior officials’ asset declarations. IMF Country Report 2026/188 — Structural Reforms
The EU similarly continued payments while requiring Ukraine Plan milestones and later strengthened the Plan with additional rule-of-law and anti-corruption steps. This demonstrates conditionality operating as a continuing leverage mechanism rather than a binary “pay or suspend everything” system.
That model is defensible only if waivers, extensions and partial compliance remain visible. Repeatedly resetting missed conditions without measurable correction would eventually turn conditionality into formalism; automatically terminating macro-financial support after every delay would create its own fiscal and strategic consequences. Oversight bodies therefore require a transparent record of condition → deadline → compliance assessment → derogation or corrective action → eventual closure.
Russian-asset-derived financing raises an additional accountability requirement
ERA and related EU mechanisms introduce a new source of support: extraordinary revenues generated by immobilised Russian sovereign assets. The EU reports €3.8 billion in such proceeds within its broader support architecture, while EPF channels have also used revenues from immobilised assets for military support. Council — Russia’s war against Ukraine Council — EU military support to Ukraine
Because these arrangements combine sanctions law, sovereign assets, capital-market borrowing and future repayment structures, accountability must cover not merely Ukrainian expenditure but also the calculation, custody and allocation of the extraordinary revenues themselves.
Counter-Disinformation Note
The September 2026 “$140 million in refrigerator boxes” claim must not enter the corruption evidence base.
A cloned-media narrative circulated alleging that NABU had searched former Defence Procurement Agency head Arsen Zhumadilov and recovered more than $140 million in refrigerator boxes. The supposed story was reproduced in a site visually imitating Ukrainian media and subsequently amplified through social platforms. The relevant analytical fact is not the spectacular allegation but the absence of a corresponding NABU case record and the reporting that NABU denied conducting the claimed search.
This episode illustrates a recurrent information-operation technique: copy the visual identity of a credible publication, combine authentic institutional vocabulary with an extraordinary claim, use AI-manipulated or misattributed imagery, and rely on the emotional salience of physical cash to bypass normal verification.
Authentic NABU/SAPO cases look different. They develop through identifiable criminal-proceeding numbers, suspicion notices, court applications, asset restraints, completion of investigations, indictments and eventually judgments. Their evidentiary progression is slower precisely because it is legally consequential.
The correct response to disinformation is therefore not to minimise genuine Ukrainian corruption. It is to insist that real corruption be documented to a higher evidentiary standard than propaganda.
Assessment of Donor Exposure
The verified cases support a finding of material procurement and governance risk, particularly where financing reaches Ukrainian contracting systems, but they do not support an inference that external aid as a whole is structurally untraceable.
The most significant risk is concentrated at the transition between financing and execution: the point at which a ministry, SOE, local authority or defence procurement body converts budget authority into an actual contract and subsequently certifies delivery.
This is where otherwise well-controlled donor money can enter a weaker control environment.
The strongest existing safeguards are upstream—appropriation controls, tranche conditions, IFI financial management—and downstream—criminal investigation and prosecution. The comparatively weaker space is often the operational middle: supplier selection, beneficial ownership, advance payment, contract amendment, physical verification, acceptance of goods and enforcement against non-performance.
That is consequently where additional donor attention can produce the highest marginal benefit.
Ranked Recommendations
1. Establish a common traceability standard for every budget-support tranche.
Every major budget-support or Ukrainian-procurement financing stream should carry a machine-readable transaction lineage connecting donor instrument, Ukrainian budget programme, implementing entity, supplier or beneficiary category and sampled end use. Beneficial ownership should be verified against Ukrainian, EU, U.S. and relevant national sanctions and corporate registries, with enhanced review for suppliers operating through recently created entities or opaque intermediaries. This should not imply public disclosure of operationally sensitive defence details; classified procurement can retain restricted visibility while still producing auditable records.
2. Establish a protected joint donor–NABU/SAPO information protocol.
Major donors should be able to learn whether an externally financed contractor, beneficial owner or Ukrainian implementing body is implicated in a live corruption case without forcing NABU or SAPO to compromise investigative secrecy. The protocol should permit restricted risk flags rather than evidentiary disclosure, allowing donors to suspend new awards, intensify verification or require additional security without publicly prejudging guilt.
3. Publish Defence Procurement Agency contract-performance data.
For every contract whose disclosure would not create an operational security risk, publication should identify contracted value, advance paid, amount delivered, amount accepted, delivery delay, outstanding receivable, termination status and litigation/recovery status. Aggregate classified categories should still report total paid, delivered and overdue values. This would directly address the distinction between corruption, supplier failure and wartime delivery delay.
4. Apply sunset clauses to emergency procurement waivers.
Non-competitive wartime exceptions should expire automatically unless the responsible authority recertifies the operational reason for continuing them. Recertification should state why competition, framework contracting or multi-supplier qualification cannot yet replace the exceptional procedure. This would preserve battlefield flexibility while preventing emergency exemptions from becoming the default procurement architecture.
5. Independently reconstruct the 2024–2026 defence-procurement loss estimates.
The reported $1.2 billion 2024 figure should be subjected to a jointly governed audit reconstruction involving Ukrainian state auditors and major donors. The exercise should disaggregate criminally suspected loss, overpricing, non-delivery, defective delivery, delay damages, avoidable expenditure and accounting adjustments. Without that reconstruction, public discussion will continue to collapse legally distinct categories into one politically potent but analytically weak number.
Annex: Principal Open Investigations Relevant to External-Financing Risk
| Case | Publicly stated amount | Procedural status at cut-off | Proven donor-money link? |
|---|---|---|---|
| SSSCIP drone procurement | UAH254m alleged loss after updated investigation | Notices of suspicion; investigation continuing | No specific donor link established publicly |
| UAV / EW local-government procurement | Public-fund misappropriation alleged | Pre-trial investigation completed / defence reviewing materials | No |
| State Border Guard drone case | Alleged $1m demand; 50,000 USDT episode and >UAH15.4m crypto conversion alleged | Suspicion notices as of 23 Sept. 2026 | No |
| Dynamic armour protection | UAH102m alleged misappropriation | Investigation completed; intended for court referral | No |
| 2024 defence-procurement audit estimate | Approx. $1.2bn reported as fraud/waste/mismanagement | Investigative-reporting/audit estimate, not a court finding | Not established across the aggregate |
| Operation Midas / Energoatom | >$112m alleged cash flow in one reported strand; additional alleged laundering | Continuing investigations and HACC pre-trial measures | No direct tracing from named donor tranches established publicly |
| Presidential Office-related laundering investigation connected partly to alleged Energoatom proceeds | >UAH460m alleged laundering | Continuing investigation | No |
| Ukrzaliznytsia cable procurement | >UAH140m alleged losses | Suspicion notices | No |
| Donetsk heating/water projects | >UAH140m alleged misappropriation | Five suspicion notices reported by NABU | No |
The absence of a proved donor-money link in these cases should not be interpreted as proof that donor resources could never have interacted with the affected institutions. It means only that the publicly available investigative record examined for this report does not establish the transaction-level chain necessary to make that claim.
Glossary
NABU — National Anti-Corruption Bureau of Ukraine. Investigative body responsible for specified high-level corruption offences. NABU announcements of suspicion represent investigative/procedural steps, not determinations of guilt. NABU official site
SAPO — Specialized Anti-Corruption Prosecutor’s Office. Specialist prosecutorial authority that supervises and prosecutes qualifying corruption cases investigated by NABU.
HACC — High Anti-Corruption Court. Specialist Ukrainian court dealing with high-level corruption cases within its jurisdiction. Pre-trial detention, bail or asset seizure ordered by HACC should not be confused with a final guilty judgment.
DPA — Defence Procurement Agency. Ukrainian procurement body responsible for significant defence acquisition. Its contract-performance architecture is particularly important as foreign assistance increasingly supports procurement from Ukrainian defence manufacturers rather than only allied inventory transfers.
ARMA — Asset Recovery and Management Agency. Ukrainian agency responsible for identifying, tracing and managing assets within the framework established by Ukrainian law; it is distinct from NABU’s investigative and SAPO’s prosecutorial functions.
PEACE — Public Expenditures for Administrative Capacity Endurance. World Bank mechanism supporting eligible Ukrainian civilian public expenditure through a structured reimbursement and verification model; the World Bank reported $53.5 billion mobilised through PEACE within a broader $91 billion financing mobilisation for Ukraine as of 31 August 2026. World Bank — Financing Mobilized for Ukraine since February 24, 2022
EPF — European Peace Facility. EU off-budget instrument financing military and defence assistance, including equipment, ammunition, fuel and training-related measures for Ukraine. Council — EU military support for Ukraine
ERA — Extraordinary Revenue Acceleration. G7 financing architecture under which loans to Ukraine are serviced using extraordinary revenues arising from immobilised Russian sovereign assets.
EFF — Extended Fund Facility. IMF programme providing Ukraine with medium-term balance-of-payments financing conditional on macroeconomic and structural-policy commitments.
Net Assessment
Ukraine’s external financing architecture should be understood as a network of controlled but heterogeneous pipelines rather than a single aid account. That distinction materially changes the corruption analysis. Tens of billions of dollars and euros in military assistance never become discretionary Ukrainian government cash; conversely, tens of billions in budget support, reconstruction finance and increasingly defence-industrial procurement do interact directly with Ukrainian public institutions and therefore expose donors to Ukrainian procurement, public-financial-management and institutional risks.
The documented corruption record is substantial enough to justify intensified fiduciary controls. NABU and SAPO have publicly developed serious cases involving defence drones, military equipment, border-service procurement, Energoatom, Ukrzaliznytsia and reconstruction. The reported 2024 defence-procurement audit findings, if independently reconstructed, could reveal weaknesses materially larger than the individual criminal cases presently visible in the public domain.
Yet the same record also demonstrates why sweeping conclusions are analytically unsound. An allegation is not a conviction; a contract loss is not necessarily theft; an institution receiving foreign financing does not mean every corrupt transaction within it used donor money; a U.S. appropriation is not equivalent to cash transferred to Kyiv; and a spectacular viral image is not evidence merely because it resembles a NABU raid.
For parliamentary budget committees and donor-oversight bodies, the policy implication is therefore neither unconditional confidence nor indiscriminate suspicion. It is transaction-level traceability combined with institutional conditionality: the capacity to move from donor appropriation, to implementing mechanism, to Ukrainian budget programme or procurement authority, to beneficial owner, to delivered asset or verified civilian expenditure, while preserving investigative independence and operational security.
That architecture is achievable because much of it already exists in fragments across the World Bank, IMF, EU, U.S. Inspectors General, GAO, NABU, SAPO and Ukrainian financial-management systems. The remaining task is to make those fragments interoperable before the scale of reconstruction and Ukrainian defence-industrial financing becomes still larger.
Pillar I — Architecture of External Financing and Fund Transmission
Principal judgment
Ukraine’s external-financing architecture between 24 February 2022 and Q3 2026 is not a single transfer mechanism but a layered system in which appropriations, commitments, sovereign loans, grants, guarantees, donor-procured military equipment, reimbursements of Ukrainian public expenditure, direct procurement from Ukrainian industry, and financing backed by revenues from immobilised Russian sovereign assets coexist under different legal and accounting rules. Any assessment of corruption exposure that fails to separate these channels will systematically overstate the amount of foreign assistance directly controlled by Ukrainian institutions in some areas while understating the fiduciary exposure created by budget support and Ukrainian defence procurement in others.
The most important quantitative distinction is between donor-side expenditure and Ukrainian state-budget financing. The Ukrainian Ministry of Finance stated on 21 September 2026 that Ukraine had attracted $31.3 billion in external financing during 2026 alone, while its broader historical accounting showed approximately $152 billion of external general-fund budget financing by late 2025, predominantly concessional loans. By contrast, the United States had appropriated more than $174 billion under five supplemental acts by April 2024 alone, but that amount included weapons procurement, replacement of U.S. inventories, humanitarian programmes, U.S. government operations and expenditure outside the Ukrainian Treasury. Ministero delle Finanze Ucraina
This distinction provides the controlling framework for the remainder of this pillar: the corruption-risk surface follows the transmission mechanism, not the political headline attached to an aid package.
The accounting problem: five different financial objects are routinely called “aid”
Before comparing donors, five accounting categories must remain separate because each represents a materially different exposure to Ukrainian state systems.
| Financial object | What it actually measures | Does the value normally enter the Ukrainian Treasury? | Principal corruption / control exposure |
|---|---|---|---|
| Appropriation / budget authority | Legal authority granted by donor legislature to spend up to a defined amount | Usually not directly | Donor-agency allocation, contracting and implementation |
| Commitment / allocation | Political or administrative decision reserving funds or equipment | Not necessarily | Contract execution, future delivery, valuation |
| Obligation / signed contract or grant | Legally binding donor expenditure commitment | Depends on instrument | Contractor performance and payment controls |
| Disbursement | Actual transfer or expenditure of cash | Sometimes | Treasury, beneficiary, contractor and end-use controls |
| In-kind delivery | Equipment or service supplied without transferring its headline value as cash | Normally no | Inventory, delivery, diversion and end use |
The U.S. case demonstrates the distinction quantitatively. GAO found that approximately $113.4 billion had been appropriated through the first four supplemental acts for FY2022–23; by 31 December 2023, agencies had obligated about $101.2 billion and disbursed about $67.5 billion. Within that same appropriation universe, DoD had received approximately $62.3 billion, of which about $52.3 billion had been obligated, including procurement of missiles, ammunition and vehicles and replacement of U.S. inventories. State and USAID together had received approximately $46.1 billion and obligated about $44.4 billion, including Ukrainian civilian-budget support. These are therefore fundamentally different expenditure chains despite appearing within the same congressional “Ukraine” legislation. GAO
The same definitional problem affects European numbers. The Council of the EU currently reports €224.5 billion mobilised by the EU and Member States, comprising €110.3 billion provided from or guaranteed by the EU budget, €77.9 billion in military assistance measures, €17 billion in support for refugees inside the EU, €15.5 billion from Member States and €3.8 billion from proceeds on immobilised Russian assets. A material proportion of that €224.5 billion never enters Ukraine because, among other things, refugee expenditure is incurred inside EU Member States and military assistance can take the form of equipment delivered directly. Consiglio dell’Unione Europea
The Ukrainian Treasury view: what actually reached the state budget
The Ukrainian Ministry of Finance provides the most useful counterweight to donor headline figures because its series measures external budget financing actually received by Ukraine, rather than the broader economic value of international support.
The Ministry reported in August 2024 that direct budget support received since 24 February 2022 had reached approximately $98.1 billion, and explicitly stated that partner financing was allocated to social, humanitarian and other priority non-military expenditure while domestic revenues funded defence and security. Ministero delle Finanze Ucraina
By November 2024, cumulative external budget support exceeded $100 billion, comprising $31.1 billion in 2022, $42.5 billion in 2023 and $27.2 billion through 14 November 2024. The Ministry identified the EU, United States, IMF, Japan and Canada as the five largest providers, together accounting for more than 90% of financing received. Ministero delle Finanze Ucraina
A later Ministry financing table showed approximately $152 billion in cumulative external general-fund financing by late 2025, with the following identifiable donor pattern. Ministero delle Finanze Ucraina
| Budget-financing source | 2022 | 2023 | 2024 | 2025 vintage shown by MoF | Cumulative amount shown |
|---|---|---|---|---|---|
| European Union | $7.961bn | $19.528bn | $17.326bn | $7.330bn | $52.145bn |
| United States | $11.976bn | $10.950bn | $7.314bn | $0 | $30.240bn |
| ERA loans | — | — | $1.0bn | $28.154bn | $29.154bn |
| IMF | Separate IMF loan series | Separate IMF loan series | Separate IMF loan series | Continued programme financing | Included separately |
| Japan | Budget loans / grants | Budget loans / grants | Budget loans / grants | ERA and World Bank-linked financing | Major bilateral source |
| Canada | Concessional loans | Continued support | Continued support | Guarantees / multilateral support | Major bilateral source |
These Ministry figures should not be mechanically added to donor-government totals, because ERA financing can also appear under lender or EU reporting, while World Bank financing can include bilateral donor guarantees or grants that are simultaneously reported by the donor country.
The most current 2026 Ukrainian figure available before the reporting cut-off states that $31.3 billion of external financing had been attracted during 2026 by 21 September, with EU instruments providing the principal contribution. Ministero delle Finanze Ucraina
United States: four financially distinct pipelines
The American architecture is best understood as four separate financial systems rather than as a single U.S. aid account.
Congressional appropriations and U.S.-side expenditure
Congress appropriated more than $174 billion through five Ukraine supplemental acts by April 2024. GAO emphasises that these appropriations funded arms, economic support, humanitarian operations, sanctions enforcement, refugee assistance and U.S. government activities associated with the response. GAO
A later GAO publication noted that the broader Ukraine-oversight accounting framework had reported $184.8 billion, because that methodology excluded approximately $10.6 billion within the $174.2 billion supplemental total that was not used directly for the Ukraine response while adding approximately $20.1 billion from regular annual appropriations and $1.1 billion from other supplemental legislation. The apparent contradiction is therefore definitional rather than evidence that one number is necessarily wrong. GAO Files
Presidential Drawdown Authority
Under PDA, defence articles are transferred from existing U.S. inventories. The financial exposure occurs primarily on the American side when Congress appropriates money to replace those inventories.
GAO reported that DoD planned, as of February 2025, to obligate the remaining $45.8 billion of replacement funding associated with defence articles provided through PDA and anticipated requiring additional appropriations to replace some items already transferred. GAO
For corruption-risk analysis, this is fundamentally different from Ukrainian budget support: the Ukrainian state receives missiles, vehicles, ammunition or services rather than control over an equivalent dollar amount.
Ukraine Security Assistance Initiative
USAI finances procurement for Ukraine rather than drawing equipment exclusively from U.S. inventories. According to the State Department’s January 2025 security-cooperation accounting, DoD provided $6.3 billion under USAI in FY2022 and $12.1 billion in FY2023, while total U.S. military assistance since the February 2022 full-scale invasion had reached $65.9 billion by 9 January 2025. Stati Uniti – Dipartimento di Stato
The corruption-risk exposure therefore sits predominantly in donor procurement, supplier performance, contract administration and final delivery rather than in Ukrainian Treasury controls, although Ukrainian requirements and end-use verification remain part of the chain.
Foreign Military Financing
Congress appropriated approximately $4.65 billion in FMF through two supplemental packages for Ukraine and countries affected by the war, of which approximately $4 billion had been formally notified to Congress by January 2025. The same source records several FMF packages intended not only for Ukraine but for NATO allies and other partners replenishing capabilities donated to Ukraine, again demonstrating why headline security-assistance values cannot be treated as cash received by Kyiv. Stati Uniti – Dipartimento di Stato
Direct budget support
This is the American channel with the highest direct exposure to Ukrainian public-financial systems.
USAID OIG reported that Congress appropriated and USAID obligated approximately $30.7 billion in direct budget support during FY2022–24, with the majority channelled through World Bank trust funds. oig.usaid.gov
GAO subsequently established that USAID had disbursed approximately $30.2 billion between April 2022 and December 2024. Responsibility for oversight transferred from USAID to the State Department on 1 July 2025. Separately, the U.S. Treasury transferred $20 billion to the World Bank in December 2024, including approximately $15 billion intended for direct budget support. GAO Files
Ukraine’s own Ministry of Finance recorded approximately $30.24 billion of U.S. budget financing through the 2022–24 cycle, broadly reconcilable with the USAID number once timing, instrument and accounting differences are considered. Ministero delle Finanze Ucraina
The critical point is therefore measurable: approximately $30 billion of the U.S. assistance architecture clearly entered or reimbursed Ukrainian civilian public expenditure, whereas the much larger headline appropriation total included extensive spending that never became Ukrainian Treasury cash.
European Union: the architecture has shifted from emergency macro-finance to structural financing
The EU financing model evolved in three distinct phases: emergency macro-financial assistance in 2022–23, the Ukraine Facility beginning in 2024, and the much larger Ukraine Support Loan architecture introduced for 2026–27.
Ukraine Facility
The Ukraine Facility has an overall envelope of approximately €50 billion for 2024–27.
Its first pillar provides €38.5 billion directly through the Ukraine Plan, comprising approximately €33 billion in loans and €5.5 billion in grants. By June 2026, the Commission reported €29.5 billion disbursed under Pillar I, equivalent to nearly 77% of its original available resources. Enlargement and Eastern Neighbourhood
The disbursement path is unusually well documented.
| Ukraine Facility budget-support stage | Amount | Status |
|---|---|---|
| March 2024 bridge financing | €4.5bn | Disbursed |
| April 2024 bridge financing | €1.5bn | Disbursed |
| June 2024 pre-financing | ~€1.9bn | Disbursed |
| August 2024 first regular payment | ~€4.2bn | Disbursed |
| December 2024 second regular payment | ~€4.1bn | Disbursed |
| April 2025 third payment | ~€3.5bn | Disbursed |
| August 2025 fourth payment | €3.05bn | Disbursed |
| November 2025 fifth payment | €1.8bn | Disbursed |
| December 2025 sixth payment | €2.3bn | Disbursed |
| June 2026 seventh payment | ~€2.8bn | Disbursed |
| September 2026 eighth payment | ~€3.0bn | Approved by Council; not yet equivalent to a recorded receipt at cut-off |
The Commission’s Facility record documents the earlier payment sequence and the €29.5 billion cumulative Pillar I disbursement by June 2026. Enlargement and Eastern Neighbourhood The Ukrainian Ministry of Finance reported on 24 September 2026 that the Council had approved an eighth regular payment of nearly €3 billion after Ukraine completed ten relevant Ukraine Plan indicators, with 84 of 95 steps then due having been completed, approximately 88%. Ministero delle Finanze Ucraina
Approval and receipt must remain distinct: the €3 billion eighth payment was politically and legally approved at the reporting cut-off, but should not be described as already received unless a later Treasury record confirms crediting.
Ukraine Facility investment architecture
The Facility does not consist solely of Treasury transfers.
Its Ukraine Investment Framework has approximately €9.6 billion of budgetary capacity, including €7.8 billion in guarantees and €1.8 billion in blending grants, designed to mobilise substantially larger investment through IFIs, development banks and financial intermediaries. By April 2026, approximately €8.5 billion of guarantee and grant agreements had been allocated, representing around 89% of the Framework. Enlargement and Eastern Neighbourhood
These resources do not necessarily enter the Ministry of Finance. They can support sovereign borrowers, municipalities, state-owned enterprises, banks and private companies, which means that their corruption-risk surface moves away from central Treasury execution toward project procurement, lender due diligence, SOE governance and beneficiary selection.
Ukraine Support Loan
The €90 billion Ukraine Support Loan for 2026–27 materially changes the architecture because it combines sovereign budget support with very large defence-industrial financing.
The EU framework allocates approximately:
| Component | Envelope | Share of €90bn |
|---|---|---|
| General budget / macro-financial support | €30bn | ~33% |
| Defence procurement and defence-industrial support | €60bn | ~67% |
The European Commission confirms the €60 billion / €30 billion structure and states that up to €45 billion was made available for 2026, consisting of approximately €16.7 billion in budget support and €28.3 billion for defence-industrial capacity. Defence Industry and Space
The first budget-support payment of €3.2 billion reached the Ukrainian State Budget on 25 June 2026. Ukraine’s Ministry of Finance explicitly records the funds as received and links subsequent tranches to conditions covering public-financial management, domestic-revenue mobilisation, expenditure efficiency, rule of law and anti-corruption. Ministero delle Finanze Ucraina
The defence side followed separately: the Commission records €3.9 billion disbursed on 30 June, €1.1 billion on 15 July and €3.47 billion on 30 July 2026, producing approximately €8.47 billion in defence-window disbursements by the end of July. Defence Industry and Space
This mechanism creates substantially more direct exposure to Ukrainian procurement than traditional allied stock donations because money is explicitly intended to strengthen and procure through Ukraine’s defence-industrial base as well as European suppliers.
Russian sovereign-asset proceeds: a new layer of financing
The G7 Extraordinary Revenue Acceleration initiative created approximately €45 billion, or roughly $50 billion, of loans backed by future extraordinary revenues generated from immobilised Russian sovereign assets.
The official G7 allocation was:
| Lender | ERA participation |
|---|---|
| European Union | €18.115bn |
| United States | $20bn |
| Canada | C$5bn |
| Japan | ¥471.9bn |
| United Kingdom | £2.258bn |
The G7 term sheet stipulated that the loans would be disbursed between December 2024 and December 2027 and that transparency and accountability requirements should remain coherent with existing Ukraine Facility and IMF programme conditions. Ministero delle Finanze
Ukraine’s Ministry of Finance recorded €14 billion of the EU’s €18.1 billion ERA contribution as received by 1 October 2025, while nearly $28 billion of aggregate G7/EU ERA financing had been provided during 2024–25. Ministero delle Finanze Ucraina
The mechanism has a dual control chain that ordinary grants do not: auditors must establish both the legitimacy and calculation of the extraordinary Russian-asset revenues and the lawful expenditure of the resulting loan proceeds inside Ukraine.
Major bilateral donors: the accounting profiles are radically different
Germany
Germany reported in August 2026 that it had provided more than €43.3 billion in bilateral civilian assistance since February 2022 and had either provided or earmarked approximately €57.6 billion in military assistance for current and future years. Bundesregierung
The wording matters: the military number combines provided and future earmarked assistance, whereas the civilian number is described as support already provided. A simple €100.9 billion “German aid delivered” total would therefore overstate executed assistance.
Germany’s civilian portfolio includes KfW-financed repair and maintenance of electricity and heating infrastructure, while much of its military assistance consists of equipment, procurement and multinational initiatives rather than unrestricted Treasury transfers. Bundesregierung
United Kingdom
The United Kingdom’s July 2026 official accounting records £25 billion committed, divided into approximately £16 billion military support, up to £5.6 billion non-military support and a £3.5 billion UK Export Finance cover limit. GOV.UK
The non-military component itself contains approximately £4.1 billion in fiscal support through World Bank loan guarantees, rather than £4.1 billion of British cash transferred directly into Kyiv’s Treasury. The UK also manages the International Fund for Ukraine, to which more than £2.7 billion had been pledged, reinforcing the importance of separating UK commitments from British-budget cash transfers. GOV.UK
Ukraine’s Ministry of Finance provides a much narrower Treasury measure: by 9 September 2026 it reported $3.83 billion in direct UK budget support since February 2022, of which $798 million had been received during 2026. Ministero delle Finanze Ucraina
The comparison—£25 billion total UK commitment versus $3.83 billion Ukrainian direct-budget receipts—shows precisely why total donor support and state-system exposure are different concepts.
France
Ukraine’s Ministry of Finance stated on 10 September 2026 that total French assistance since the full-scale invasion had reached €7.9 billion, while bilateral French budget support accounted for approximately €400 million. Ministero delle Finanze Ucraina
This indicates that only a relatively small part of France’s aggregate support has operated as direct bilateral budget financing, with the remainder distributed across military, humanitarian, reconstruction, guarantees, EU-level participation and other support channels.
The French case is also a warning against manufactured precision: there is no single official French public series at the reporting cut-off that provides, in one reconciled table, commitment, obligation, delivery and expenditure values for every military and civilian instrument through Q3 2026. The Ukrainian Ministry figure therefore provides the most defensible current aggregate, but it should not be mistaken for a French budget-execution ledger.
Canada
Canada reported by April 2026 that it had committed more than C$25.5 billion in multi-faceted support since February 2022, including approximately C$8.5 billion in military assistance. Canada
The architecture extends well beyond equipment donation. On 22 September 2026 Ukraine received $841 million through the World Bank under a Canadian sovereign guarantee, with the money used to reimburse eligible old-age social payments under PEACE. Ministero delle Finanze Ucraina
This transaction illustrates why guarantees require separate treatment: Canada bears contingent financial risk, the World Bank extends the financing, Ukraine receives the money, and PEACE rules determine eligible expenditure. Recording all four relationships as separate “aid” would double count the same underlying transaction.
Japan
Japan has become one of Ukraine’s largest financial rather than lethal-military bilateral supporters.
The Japanese government stated in February 2026 that it was implementing approximately $20 billion in assistance, including approximately $6 billion of financial support announced in December 2025, spanning humanitarian, financial, recovery and reconstruction programmes. MAE Cooperazione
Ukraine’s Ministry of Finance reported by March 2026 that direct Japanese budget support had exceeded $9.5 billion, including approximately $1.5 billion in grants; by August the cumulative budget-support figure had exceeded $9.8 billion, with approximately $850 million received in 2026. Ministero delle Finanze Ucraina
Japan also participates in ERA through a ¥471.9 billion loan, while separately providing World Bank credit enhancement: Japan’s Finance Ministry announced an additional $4.5 billion of credit enhancement to IBRD loans in 2026, on top of earlier support. Ministero delle Finanze
Netherlands
The Netherlands provides one of the clearest official bilateral breakdowns. Its January 2026 government accounting showed €20.8 billion committed, comprising approximately €13.6 billion of military support and €7.2 billion of non-military support. Governo dei Paesi Bassi
The non-military component included:
| Netherlands category | Commitment |
|---|---|
| Direct budget support | €5.3bn |
| Recovery and reconstruction | €1.4bn |
| Emergency aid and protection | €220m |
| Accountability programmes | €246m |
| Loans within non-military support | €200m |
| Guarantees | €3.3bn |
| Grants | €2.8bn |
| Total non-military commitment | €7.2bn |
The Dutch government explicitly labels the amounts indicative and subject to change, another example of why commitments should not be reported as completed cash transfers. Governo dei Paesi Bassi
Nordic and Baltic states
The Nordic and Baltic financing model is notable for the comparatively high proportion of military equipment, procurement from domestic industry and targeted bilateral instruments.
| Donor | Current official baseline | Dominant financial form |
|---|---|---|
| Denmark | ~€10.3bn military + ~€1.1bn civilian by 13 Aug. 2026 | Defence procurement, Ukrainian-industry financing, grants and guarantees |
| Sweden | ~SEK156bn total, including SEK128bn military and SEK28bn civilian by 12 Aug. 2026 | Equipment, procurement, budget support, humanitarian |
| Finland | €3.6bn defence materiel delivered by 15 Sept. 2026 | Primarily delivered equipment and Finnish-industry procurement |
| Estonia | €1.41bn provided/planned 2022–27; €820m bilateral military including related costs | Equipment, Estonian-industry procurement, financial aid |
| Latvia | €1.13bn state and societal support through 26 May 2026 | Military, training, humanitarian, societal |
| Lithuania | Military support exceeded $1bn by Feb. 2026; ~$265m earmarked for 2026 | Air defence, drones, ammunition, Ukrainian/European procurement |
Denmark’s Foreign Ministry reports approximately €10.3 billion of military support and €1.1 billion of civilian contributions, of which around €823 million had been granted and €291 million committed through guarantees and guarantee schemes. Ministero degli Affari Esteri
Sweden records approximately SEK156 billion in total support, comprising SEK128 billion military and SEK28 billion civilian; its military framework allocates SEK40 billion for 2026 and another SEK40 billion for 2027. Regeringskansliet
Finland’s accounting is unusually conservative because its September 2026 figure of €3.6 billion refers specifically to defence materiel actually delivered, not a broad multi-year commitment. Valtioneuvosto
Estonia reports €1.41 billion in provided and planned assistance for 2022–27, including approximately €810 million in direct military assistance, €820 million including associated logistical costs, and €88.22 million in financial support. Ministero degli Affari Esteri Estone
Latvia reports approximately €1.13 billion of state and societal support through 26 May 2026, but its denominator includes a wider societal category and is therefore not directly comparable with narrowly defined state-budget donor figures. Ministero degli Affari Esteri Lettonia
Lithuania reported in February 2026 that military assistance had already exceeded $1 billion, with another approximately $265 million earmarked for 2026 for air defence, Ukrainian drones and long-range artillery ammunition. LR Krašto apsaugos ministerija
Poland
Poland’s Ministry of National Defence provides a delivered-donation measure rather than a broad aid commitment: by 6 July 2026, the cost of military donations actually carried out for Ukraine totalled approximately PLN16.45 billion, of which PLN1.55 billion was associated with 2024–26. Gov.pl
Because that figure represents completed military donations, its direct exposure to the Ukrainian Treasury is extremely low; the relevant control risks concern valuation, logistical custody, transfer documentation and military end use.
International financial institutions
IMF
Ukraine’s current IMF EFF is a 48-month, $8.1 billion programme approved in February 2026. The first review was completed on 20 July 2026, releasing approximately SDR503 million, or $690 million, and bringing cumulative disbursement under the new programme to approximately $2.2 billion by July. IMF
Unlike project finance, IMF money is macro-financial sovereign financing and therefore enters the public-finance system directly. The control mechanism is not invoice-by-invoice expenditure certification but programme conditionality, quantitative performance criteria and structural benchmarks.
World Bank
The World Bank is not merely another donor; it is the central intermediary through which many bilateral donors convert political commitments into audited Ukrainian budget financing.
As of 31 August 2026, the Bank reported approximately $91 billion of financing mobilised for Ukraine, with the overwhelming majority raised on behalf of partners rather than financed solely from World Bank capital. PEACE accounted for approximately $53.5 billion of that total at that date. Banca Mondiale
A subsequent Ukrainian Ministry of Finance transaction on 22 September increased the total PEACE project volume to approximately $54.3 billion following the $841 million World Bank operation guaranteed by Canada. The Ministry also reported that more than $73.8 billion had been received through World Bank mechanisms since February 2022, including more than $53 billion in grants. Ministero delle Finanze Ucraina
The apparent difference between the Bank’s $53.5 billion PEACE figure and Ukraine’s $54.3 billion is therefore temporal: the Bank figure is dated 31 August; the larger Ukrainian figure incorporates the September Canadian-guaranteed financing.
EBRD
EBRD wartime investment in Ukraine exceeded approximately €10.5 billion by June 2026. Unlike PEACE, a substantial proportion of EBRD financing is directed to companies, banks, state-owned enterprises and infrastructure rather than the central budget. Its corruption-risk exposure therefore concentrates on borrower governance, procurement, project implementation, counterparty integrity and loan covenants rather than Ukrainian Treasury execution alone. Banca Mondiale
EIB
The EIB reported more than €4 billion of EU-guaranteed financing delivered since 2022 by early 2026, including approximately €1.5 billion of new financing during 2025. Its operations concentrate on infrastructure, energy, municipalities and private-sector recovery, producing a similarly project-specific control architecture rather than general-budget exposure.
Where foreign money actually touches Ukrainian systems
An exact donor-wide percentage cannot be responsibly calculated from the public record because the denominators use incompatible accounting conventions. A more defensible measure is instrument-level exposure.
| Instrument | Approximate share entering / reimbursing Ukrainian state-controlled systems | Primary Ukrainian control point | Principal fiduciary exposure |
|---|---|---|---|
| U.S. PDA | ~0% as Treasury cash | Armed Forces logistics / end users | Inventory and end use |
| USAI | Low | MoD requirements and acceptance | Donor procurement, contract performance |
| U.S. PEACE / DBS | ~100% of disbursed instrument value ultimately supports eligible public expenditure | MoF / Treasury / eligible agencies | Payroll, beneficiary and expenditure verification |
| Ukraine Facility Pillar I | ~100% of disbursed Pillar I financing enters state-budget financing architecture | MoF / Treasury | Budget execution and reform conditionality |
| Ukraine Facility Investment Framework | Variable | SOEs, municipalities, banks, private companies | Project procurement and beneficiary integrity |
| EU Support Loan budget window | High / effectively direct sovereign support | MoF / Treasury | PFM, revenue and expenditure conditions |
| EU Support Loan defence window | High exposure to Ukrainian procurement but not equivalent to Treasury cash | MoD / DPA / Ukrainian defence industry | Supplier ownership, pricing, delivery |
| EPF | Low as Ukrainian cash | Armed Forces / MoD | Equipment delivery and end use |
| ERA sovereign loans | High | MoF / Treasury | State expenditure plus asset-revenue accounting |
| IMF EFF | High | NBU / MoF / Treasury architecture | Macro conditionality and fiscal governance |
| World Bank PEACE | Very high | Treasury / line ministries / social-payment systems | Eligibility and reimbursement verification |
| EBRD/EIB SOE financing | Medium–high | SOEs / municipalities / project entities | Procurement and corporate governance |
| Bilateral equipment donation | Near zero as cash | Armed Forces | Custody, delivery and end use |
| Donor-funded Ukrainian weapons production | High procurement-system exposure | DPA / MoD / Ukrainian industry | Contracting, advances, delivery and beneficial ownership |
The analytical implication is substantial: the areas of greatest corruption exposure are no longer necessarily those with the largest headline donor commitments. A €1 billion ammunition donation controlled and procured abroad can create less Ukrainian fiduciary exposure than a much smaller direct procurement contract executed through a domestic Ukrainian authority.
The transmission chain in operational form
The external-financing architecture can be reduced to six sequential control gates:
Donor legislature / EU borrowing authority → donor agency or IFI → financial instrument → Ukrainian Treasury, procurement body, SOE or end user → contractor or beneficiary → verified economic or military output.
Each transition introduces a different control risk.
| Transmission gate | Decision being made | Typical control mechanism | Failure mode |
|---|---|---|---|
| Appropriation | How much legal spending authority exists? | Parliament/Congress, budget law | Political overstatement of executable resources |
| Allocation / obligation | Which programme receives resources? | Agency controls, financing agreements | Misclassification, weak programme design |
| Transfer / reimbursement | Does Ukraine receive cash or reimbursement? | World Bank, EU, Treasury verification | Ineligible expenditure, incomplete documentation |
| Procurement | Who receives the contract? | DPA, ministries, SOEs, IFI procurement rules | Collusion, hidden ownership, overpricing |
| Acceptance / delivery | Was the promised asset or service actually delivered? | Inspection, contract certification | Non-delivery, defective goods, false acceptance |
| End use | Did the equipment or expenditure produce its intended effect? | End-use monitoring, audit, beneficiary testing | Diversion, ghost beneficiaries, misuse |
The architecture is strongest when different institutions control consecutive gates. It becomes materially more vulnerable when one entity can define the requirement, select the supplier, approve advance payment, certify delivery and suppress contract-performance data.
The structural shift that changes the corruption-risk map
From 2022 through much of 2024, a large proportion of Western military assistance was structurally insulated from Ukrainian cash-management risk because allied states supplied weapons from their own inventories or purchased them through their own procurement systems.
By 2025–26, that model was changing.
Denmark increasingly funded procurement from Ukrainian defence manufacturers; Lithuania explicitly incorporated support for weapon production inside Ukraine into its assistance model; Estonia directed most of its 2025 military support toward procurement from Estonian defence industry while maintaining a dedicated industrial-support measure for 2026; and the EU’s €60 billion Ukraine Support Loan defence component places Ukrainian and European defence-industrial capacity at the centre of future assistance. Ministero degli Affari Esteri
This does not mean the system has become less legitimate or necessarily less controlled. It means the locus of oversight must change.
The relevant question for the next phase is no longer only “Was the weapon delivered to Ukraine?” but increasingly “Who selected the manufacturer, who owns it, how was the price determined, how much was advanced, how much was delivered, which defects were accepted, what happens to unpaid receivables, and which institution can suspend a repeatedly underperforming contractor?”
That transition is the central financial-governance issue connecting Pillar I to the subsequent corruption assessment.
Pillar I key judgments
The first judgment is that donor headline totals cannot be used as a proxy for money controlled by Kyiv. The clearest example remains the United States: more than $174 billion was appropriated through five supplemental acts, whereas approximately $30 billion can be identified as USAID direct-budget-support disbursement through the end of 2024. GAO
The second judgment is that EU exposure to Ukrainian state systems is structurally increasing. Ukraine Facility Pillar I had transferred approximately €29.5 billion by June 2026; the eighth regular payment of nearly €3 billion was approved in September; the Ukraine Support Loan adds up to €30 billion of general-budget assistance and €60 billion of defence financing for 2026–27. Enlargement and Eastern Neighbourhood
The third judgment is that World Bank intermediation has become one of the central plumbing systems of Ukrainian wartime public finance. PEACE reached approximately $54.3 billion after the September 2026 Canadian-guaranteed operation, while total financial assistance received through World Bank mechanisms exceeded $73.8 billion according to the Ukrainian Ministry of Finance. Ministero delle Finanze Ucraina
The fourth judgment is that bilateral donors should not be compared using unreconciled headline totals. Germany combines delivered and future military commitments; Finland reports materiel actually delivered; the Netherlands reports commitments; Poland reports the cost of completed donations; the UK combines grants, guarantees, military commitments and export-credit cover; and France’s €7.9 billion aggregate includes only €400 million in bilateral budget support. Bundesregierung
The fifth judgment is that the highest emerging fiduciary risk lies at the interface between external financing and Ukrainian procurement execution. As donors finance more Ukrainian defence production, reconstruction, SOEs and local implementation rather than simply shipping finished equipment, beneficial ownership, advance-payment control, contract-performance measurement and physical delivery verification become increasingly central to donor oversight.
What would materially change the assessment
The financing map would need to be revised if donor governments publish reconciled commitment-to-disbursement datasets covering all military and non-military instruments, if the Ukrainian Ministry of Finance releases a Q3 2026 donor-by-donor financing table that supersedes the current August/September disclosures, if the EU publishes contract-level execution data for the €60 billion defence window, or if defence procurement authorities disclose sufficiently detailed advance-payment and delivery-performance records to calculate the actual proportion of foreign-financed procurement retained inside Ukrainian public systems.
The currently available official record is already sufficient to reject any analytical model that treats total Western assistance as a single Ukrainian cash balance, but it is not yet sufficient to calculate one defensible donor-wide percentage representing the share of every donor’s total support that passed through Ukrainian state systems. Attempting to manufacture that percentage would combine incompatible appropriations, grants, loans, guarantees, weapons valuations and domestic refugee expenditure, violating the quantitative-integrity rules of the governing report protocol.
Ukraine External Financing & Fund Transmission
Decision-useful map of how international support moves from donor authorisation to Ukrainian budget systems, procurement structures, state-owned enterprises and final end use, with explicit separation between appropriations, commitments, disbursements, guarantees and in-kind military delivery.
Transmission Chain
Instrument Exposure to Ukrainian State Systems
| Instrument | Cash enters Ukrainian Treasury? | Primary Ukrainian node | Control exposure | Risk profile |
|---|---|---|---|---|
| U.S. Presidential Drawdown Authority | Normally no | Armed Forces / logistics system | Inventory, custody, end-use monitoring | LOW TREASURY EXPOSURE |
| USAI procurement | Limited | MoD requirements / acceptance | Donor contracts, supplier performance, delivery | MEDIUM |
| U.S. PEACE / Direct Budget Support | Yes, through reimbursement architecture | MoF / Treasury / eligible civilian programmes | Beneficiary eligibility, expenditure verification | HIGH STATE-SYSTEM EXPOSURE |
| Ukraine Facility Pillar I | Yes | MoF / Treasury | Budget execution, milestones, anti-corruption conditionality | HIGH |
| EU defence-loan window | Variable | MoD / DPA / Ukrainian defence industry | Supplier ownership, pricing, advances, delivery | HIGH PROCUREMENT EXPOSURE |
| EPF military assistance | Usually no | Armed Forces / MoD | Equipment delivery and end use | LOW TREASURY EXPOSURE |
| ERA sovereign financing | Yes | MoF / Treasury | State expenditure + Russian-asset revenue accounting | HIGH |
| IMF EFF | Yes | NBU / MoF / sovereign accounts | Macro conditionality, governance, fiscal benchmarks | SYSTEMIC |
| EBRD / EIB project finance | Not necessarily via central Treasury | SOEs, municipalities, project entities | Procurement, covenants, corporate governance | PROJECT-SPECIFIC |
| Bilateral weapons donation | No equivalent cash transfer | Military end user | Custody, diversion and battlefield end use | LOW FINANCIAL EXPOSURE |
U.S. architecture: headline value vs direct budget exposure
The graphic is intentionally indexed to total U.S. supplemental appropriations and does not imply that the categories have identical dates or accounting definitions.
Structural shift in corruption exposure
The principal oversight challenge is moving away from a model dominated by weapons transferred from allied inventories toward one in which donors increasingly finance Ukrainian defence production, reconstruction, state-owned enterprises and domestic procurement. The control question therefore shifts from simple delivery verification toward beneficial ownership, contract pricing, advance payments, supplier performance, physical acceptance and recovery from failed contractors.
Selected Donor Architecture
| Donor / institution | Reported scale | Accounting basis | Dominant transmission route | Direct state-system exposure |
|---|---|---|---|---|
| United States | >$174bn supplemental appropriations | Congressional budget authority | PDA, USAI, FMF, PEACE, humanitarian programmes | Mixed |
| European Union | €50bn Ukraine Facility + €90bn 2026–27 Support Loan | Multi-year financing envelopes | Budget support, investment, defence procurement | High and increasing |
| Germany | >€43.3bn civilian + ~€57.6bn military provided / earmarked | Delivered + future commitments mixed | Military procurement, civilian programmes, infrastructure | Mixed |
| United Kingdom | £25bn committed | Military + non-military + export-finance exposure | Equipment, IFU, World Bank guarantees, direct fiscal support | Medium |
| France | €7.9bn total assistance; ~€400m bilateral budget support | Aggregate support vs narrow Treasury support | Military, humanitarian, reconstruction, EU channels | Relatively limited direct bilateral exposure |
| Japan | >$9.8bn direct budget support by Aug. 2026 | Budget financing + guarantees + ERA | World Bank, sovereign support, reconstruction | High financial-system exposure |
| World Bank | ~$91bn financing mobilised; PEACE ~>$53bn | Donor-backed and Bank-mediated financing | Budget reimbursement, projects, guarantees | Very high |
| IMF | $8.1bn current EFF | Sovereign macro-financial programme | Balance-of-payments / sovereign financing | High, but controlled through programme conditionality |
Decision-relevant conclusion
The largest political aid number is not necessarily the largest corruption-risk surface. A donor-procured €1 billion weapons transfer can generate almost no Ukrainian Treasury exposure, whereas a much smaller domestic procurement programme can create direct vulnerabilities involving supplier ownership, advance payment, contract amendment, acceptance certification and state-enterprise governance. Oversight should therefore follow the financial transmission path rather than the headline value of the donor package.
U.S. congressional appropriations, obligations and disbursements: U.S. Government Accountability Office — Ukraine: Status and Use of Supplemental U.S. Funding .
U.S. direct budget support: GAO — Oversight of Direct Budget Support to Ukraine .
Ukraine Facility: European Commission — Ukraine Facility .
EU defence-support architecture: European Commission — Support to Ukraine .
Ukrainian external budget financing: Ministry of Finance of Ukraine — 2026 external financing .
World Bank financing: World Bank — Financing Mobilized for Ukraine .
G7 ERA structure: G7 — Extraordinary Revenue Acceleration Loans for Ukraine .
Germany: Federal Government of Germany — Germany’s support for Ukraine .
United Kingdom: UK Government — UK support to Ukraine factsheet .
IMF: IMF — First Review of Ukraine’s Extended Fund Facility .
Pillar II — Corruption Exposure, Procurement Leakage and Verified Investigations
Principal judgment
The verified public record through 25 September 2026 supports a materially more serious conclusion than a generic statement that Ukraine faces “wartime corruption”, but a materially narrower conclusion than claims that Western financial assistance has been proven to disappear systematically into a captured state apparatus. The defensible finding is that Ukraine has repeatedly experienced high-value procurement failures, alleged embezzlement, kickback demands, laundering structures, supplier-performance failures and weaknesses in contract enforcement across defence, energy, infrastructure and state-owned enterprises; however, the evidentiary status varies sharply from administrative audit finding to notice of suspicion to indictment to final judgment, and in most of the major wartime cases publicly disclosed by NABU and SAPO, a transaction-level link to a named U.S., EU or bilateral donor tranche has not been established.
That distinction is particularly important in defence procurement, where the strongest 2026 evidence no longer consists only of isolated criminal cases. Confidential Ukrainian State Audit Service and Ministry of Defence reviews obtained by The New York Times reportedly identified approximately $1.2 billion in fraud, waste and mismanagement in 2024 alone, while recording repeated contracts with suppliers that had already defaulted, lacked required licences or were under criminal investigation. This is an investigative-journalism finding based on undisclosed government audits rather than a judicial determination, and it must therefore remain separate from the criminal cases formally announced by NABU and SAPO. The New York Times — In Ukraine, Fraud and Waste Are Rewarded With More Weapons Contracts Ukrainska Pravda — Ukraine lost over US$1bn on defence procurement in one year – NYT
At the same time, the official enforcement record is substantial. NABU reports that from January through August 2026 it initiated 521 cases, served 153 new suspects, sent 72 indictments involving 148 people and alleged damages of UAH11.078 billion to court, and recorded 78 guilty verdicts involving 107 persons that entered into force. These aggregate convictions should not be confused with convictions in the specific cases discussed below, many of which remain at suspicion or pre-trial stage. NABU — current enforcement statistics
Evidentiary classification used in this pillar
| Status | What it means | What it does not mean |
|---|---|---|
| Audit finding | Financial or procurement irregularity identified by an authorised auditor | Proof beyond reasonable doubt of theft or corruption |
| Investigative reporting | Documentary evidence analysed by a first-tier media organisation | Court finding or official criminal determination |
| Notice of suspicion | Ukrainian investigators formally allege that evidence supports criminal suspicion | Conviction |
| Pre-trial investigation completed | Investigators consider evidentiary collection substantially complete and disclose materials to defence | Court has accepted prosecution theory |
| Indictment / case sent to court | Prosecution seeks judicial determination | Guilt |
| Interim HACC measure | Bail, detention, seizure or asset restraint ordered during proceedings | Final judgment |
| Conviction not final | Trial court has entered judgment subject to applicable appeal | Final legally effective conviction |
| Judgment entered into force | Criminal liability has become legally effective | Proof that related cases or institutions are also corrupt |
| Donor-fund tracing | Documentary chain links the alleged loss to a defined external financing instrument | Inference based merely on the institution also receiving foreign support |
This classification is indispensable because the public debate frequently collapses the first six categories into the word “proven”. NABU itself routinely reproduces the constitutional presumption of innocence in its releases, including defence and energy cases discussed below. NABU — UAH254 million drone procurement investigation
Defence procurement: the problem is larger than bribery alone
The most significant development in the defence file during 2026 is that the evidentiary picture now shows four distinct loss mechanisms rather than a single corruption typology:
- procurement at allegedly inflated prices;
- advance payments or contract awards to suppliers that fail to deliver;
- continuation of business with previously non-performing or legally compromised suppliers;
- bribery at the acceptance or contract-execution stage.
The interaction among those mechanisms matters because a system can lose substantial money even without proving a classic bribe. A supplier may receive an advance, fail to deliver, litigate recovery for years and thereby generate an economic loss or operational shortage without anyone yet being convicted of corruption.
Defence Procurement Agency: confidential audits and contract-performance exposure
The most consequential 2026 reporting concerns confidential reviews performed by Ukraine’s State Audit Service and an internal Ministry of Defence audit body covering procurement activity in 2024 and 2025. According to The New York Times, those reviews identified approximately $1.2 billion of fraud, waste and mismanagement in 2024, and documented repeated contracting weaknesses inside the defence-procurement system. The New York Times — In Ukraine, Fraud and Waste Are Rewarded With More Weapons Contracts
The disclosed findings, as reported by the newspaper and subsequently summarised by Ukrainian media, included 18 companies receiving contracts despite previous defaults, of which six reportedly had not successfully completed a single previous contract; seven of the ten largest military contractors reportedly received new business despite criminal investigations, previous delivery failures or arrests of company executives; and approximately $126 million was attributed to cases in which lower bids were reportedly bypassed without a lawful justification. The New York Times — 4 Things We Found in Secret Ukrainian Military Audits Ukrainska Pravda — summary of the audit findings
One reported transaction illustrates the pricing problem. Three suppliers reportedly offered the same Turkish-manufactured rocket at approximately $4,200, $4,600 and $5,100 per unit, yet the highest-priced intermediary received the contract; the additional cost attributable to that choice was estimated by the newspaper at approximately $130 million, while the audits reportedly stated that there was no justification for selecting the more expensive intermediary. The New York Times — defence-procurement investigation
A separate contract involved Pavlohrad Chemical Plant, which supplied thousands of defective mortar rounds. The reporting states that the DPA continued issuing contracts even after serious performance concerns had emerged, including a contract worth approximately $280 million while the plant’s director was already on bail in a corruption proceeding. The New York Times — defence-procurement investigation
These facts should not be overstated. The $1.2 billion figure is not equivalent to $1.2 billion proved stolen. It aggregates categories described as fraud, waste and mismanagement and derives from confidential audits that were reported by journalists rather than publicly released in full by the State Audit Service. A defensible reconstruction would therefore need to separate overpricing, non-delivery, defective delivery, unenforced penalties, advances outstanding, recoverable receivables and criminally suspected misappropriation.
The audit trail predates the September disclosure
The 2026 press investigation did not emerge in an institutional vacuum. In December 2025, the Ukrainian Cabinet formally announced that the State Audit Service was conducting audits across Energoatom and the defence sector, including 22 enterprises within Ukrainian Defence Industry, state enterprises subordinate to the Ministry of Defence, the Defence Procurement Agency and the State Logistics Operator, covering the 2022–2025 period. Prime Minister Yulia Svyrydenko instructed the State Audit Service to report weekly and provide relevant findings to law-enforcement agencies. The Cabinet also acknowledged that monitoring of defence procurement for 2024–25 had already detected shortcomings in how procurements were organised and conducted. Cabinet of Ministers of Ukraine — defence and energy audit programme, 10 December 2025
Arsen Zhumadilov subsequently left leadership of the consolidated defence-procurement structure on 31 August 2026, describing his departure as voluntary and concluding a three-year reform cycle. His departure occurred immediately before the publication of the New York Times investigation, but the public record reviewed for this report does not establish that his resignation was caused by those audit findings. Interfax-Ukraine — Zhumadilov announces departure effective 31 August 2026
The institutional issue after his departure is therefore not appropriately framed as presumed personal culpability. The more defensible oversight question is whether the DPA’s post-transition leadership will publish sufficient information on outstanding receivables, defaulting suppliers, advance payments, contract enforcement and corrective action to determine whether the audit weaknesses were systemic and whether they have been remedied.
DPA contract-performance risk: what should be measured
The public debate frequently focuses on procurement price, while the audit evidence suggests that performance history and recovery discipline are equally important.
| Contract-performance variable | Why it matters | Evidentiary significance |
|---|---|---|
| Advance paid | Measures state exposure before delivery | High when supplier capacity is weak |
| Percentage delivered | Distinguishes contracted value from actual military output | Critical |
| Delivery delay | Measures operational and financial non-performance | Critical in wartime |
| Supplier previous defaults | Reveals whether known risks were ignored | Central finding in reported audits |
| Required export licence | Tests legal ability to perform | Audits reportedly identified contracts without appropriate licensing |
| Penalties assessed | Measures contractual enforcement | Not equivalent to recovered cash |
| Penalties recovered | Shows whether enforcement produced financial restitution | More meaningful than assessment alone |
| Receivable outstanding | Quantifies funds still due to the state | Essential for loss reconstruction |
| Contract terminated | Shows administrative action | Does not itself recover money |
| Criminal investigation | Indicates possible misconduct | Does not establish contract invalidity |
| Supplier beneficial owner | Detects conflicts and concealed relationships | Increasingly important for donor-financed Ukrainian production |
The gap in the present public record is therefore not merely “how much was stolen”, but how much was prepaid, how much was delivered, how much remains legally recoverable and how much has become an irrecoverable economic loss.
SSSCIP drone procurement: alleged loss rises from UAH90 million to UAH254 million
One of the clearest officially documented wartime drone-procurement cases concerns procurement by the State Service of Special Communications and Information Protection.
NABU and SAPO initially alleged that officials and private-company representatives manipulated procurement of DJI Mavic 3 and Autel Evo Max 4T drones, creating artificial competition and procuring equipment at prices reportedly 70–90% above market levels. The initial alleged loss announced in October 2025 was approximately UAH90 million. NABU — original SSSCIP drone case
On 13 August 2026, NABU announced that additional evidence increased the estimated state loss to UAH254 million, updated the suspicion notices against four previously identified suspects and added another alleged participant described as the de facto controller of companies involved in the scheme. NABU — UAH254 million drone procurement scheme
| Element | Verified status |
|---|---|
| Procurement subject | DJI Mavic 3 and Autel Evo Max 4T drones |
| Procurement period | 2023 |
| Initial alleged loss | UAH90m |
| Revised alleged loss | UAH254m |
| Alleged pricing distortion | 70–90% above market in original case description |
| Status at cut-off | Suspicion notices updated; investigation continuing |
| Conviction | No final conviction established in cited release |
| Named donor funds traced | No |
The absence of a public donor-money trace is analytically important. These were Ukrainian public procurements for the Defence Forces, but the NABU release does not identify the money as originating from a specific U.S., EU, UK, German or other bilateral financing tranche.
Local-government UAV and electronic-warfare procurement
A second defence case demonstrates a different transmission route: local-government funds used for military needs.
NABU and SAPO announced on 17 April 2026 that they had completed their investigation into an organised group accused of systematically misappropriating public funds allocated by local authorities for UAVs and electronic-warfare systems. The suspect group included a former regional governor, a member of parliament, the head of a city military administration, a National Guard commander, corporate owners and directors, and regional political figures. NABU — UAV and EW procurement investigation completed
The significance of this case is institutional rather than merely monetary. It demonstrates that procurement risk does not reside only in the central Ministry of Defence or DPA. Wartime decentralisation allows local authorities to purchase equipment for frontline units, creating multiple parallel procurement nodes with uneven expertise and control maturity.
Status at cut-off: pre-trial investigation completed and files disclosed to the defence. This is a more advanced procedural stage than a notice of suspicion, but it is still not a final court finding. NABU — UAV/EW case
State Border Guard drone procurement: alleged $1 million demand and crypto trail
The State Border Guard Service case provides unusually detailed evidence of how corruption can emerge not when a tender is rigged successfully, but after a lower-priced supplier wins.
According to NABU, an SBGS unit initiated procurement of UAV systems in August 2025, and a company offering equipment for approximately UAH825 million entered the negotiation procedure. A competing manufacturer allegedly believed that its own company had been preselected because of relationships with border officials and asked the competing bidder not to reduce its price. When the rival bidder lowered the offer and won, the competing supplier and a border official allegedly demanded $1 million to ensure smooth contract signing and acceptance of the equipment. NABU — $1 million drone-supply case, 29 May 2026
On 23 September 2026, NABU announced new allegations within the same proceeding: the competing supplier allegedly transferred 50,000 USDT, worth more than UAH2.1 million, to a State Border Guard official; investigators further alleged that the official converted more than UAH15.4 million into USDT between January and April 2026, with some of the proceeds later converted to cash and used to purchase a Mercedes-Benz GLC 300 registered to his wife. NABU — new charges in Border Guard drone case, 23 September 2026
| Indicator | Amount / status |
|---|---|
| Relevant UAV procurement | UAH825m |
| Alleged requested bribe | $1m |
| Additional crypto payment alleged | 50,000 USDT |
| UAH equivalent stated by NABU | >UAH2.1m |
| Crypto conversions attributed to official | >UAH15.4m |
| Current legal status | Suspicion for bribery and money laundering |
| Court conviction | None established at cut-off |
| Donor-money trace | None publicly established |
The case is significant because the alleged mechanism sits at the acceptance and execution stage, demonstrating that even a competitive or price-reducing tender does not eliminate extortion risk once equipment must be inspected and accepted.
Electronic-warfare acceptance: alleged 20% kickback
NABU and SAPO disclosed another acceptance-stage case on 27 August 2026, involving two military personnel and a contract for electronic-warfare systems worth more than UAH22.4 million. According to investigators, an officer initially demanded a 10% kickback, UAH2.24 million, for smooth acceptance; after the supplier refused, the alleged demand doubled to 20%, or UAH4.48 million. One alleged accomplice received a first instalment of $20,000, while a further $80,000 was demanded. NABU — UAH4.5 million EW acceptance-bribe case
The procedural status is detention and notice of suspicion; the investigation remains open. No public evidence in the release links the contract to a named external donor.
The importance of this case is that corruption controls limited to supplier selection would not necessarily detect it. The vulnerability arises after production and before final acceptance, meaning donor audit design must test the certification stage as well as tender award.
Dynamic protection for armoured vehicles: alleged UAH102 million embezzlement
NABU and SAPO allege that a Ministry of Defence contract signed in April 2022 for dynamic protection for tanks was manipulated through a state-owned enterprise and a private supplier. According to the official account, components were purchased at nearly three times their actual price, with shell companies used to move and launder the resulting margin; the alleged state loss exceeded UAH102 million. NABU — dynamic protection procurement case
On 22 July 2026, NABU announced completion of the pre-trial investigation and stated that the case would be sent to court after the defence completed its review of the materials. NABU — investigation completed, UAH102 million dynamic-protection case
This is therefore more advanced procedurally than the drone cases but remains short of a court finding.
Armoured-vehicle parts: allegedly recycled military property sold back to defence companies
A June 2026 case is particularly important because the alleged mechanism does not involve conventional overpricing alone.
NABU and SAPO said that private businesses supplied state defence enterprises with more than UAH350 million in armoured-vehicle spare parts between 2022 and 2024, but investigators found no lawful source for part of the inventory. Some of the goods had allegedly been stored at a military unit in Kharkiv region and written off after the full-scale invasion as destroyed by Russian attacks before later re-entering commercial supply chains. NABU — armoured vehicle spare-parts scheme
This alleged mechanism matters because it shows how inventory accounting, battlefield losses and procurement can interact. An asset written off as destroyed becomes difficult to trace; if it later re-enters the market and is resold to state defence entities, the government can effectively pay twice for property it already owned.
Again, no final conviction or named donor-funding trace has been established in the public release.
Defence-sector case matrix
| Case | Amount / exposure | Alleged mechanism | Status at 25 Sept. 2026 | Court finding? | Specific donor funds traced? |
|---|---|---|---|---|---|
| Confidential 2024 defence audits | ~$1.2bn | Fraud, waste, mismanagement, non-performance | Audit / investigative reporting | No | No aggregate trace |
| DPA rocket intermediary | ~$130m additional cost, per NYT analysis | Higher-priced intermediary chosen over direct manufacturer | Audit reporting | No | Not established |
| Reported lower-bid bypass | ~$126m | Lower bids disregarded | Audit reporting | No | Not established |
| SSSCIP drones | UAH254m alleged loss | Simulated competition / overpricing | Suspicion | No | No |
| Border Guard UAV | $1m alleged demand | Bribe to secure execution / acceptance | Suspicion | No | No |
| Border Guard crypto episode | 50,000 USDT, >UAH15.4m conversions | Bribery / laundering alleged | Suspicion | No | No |
| EW acceptance | UAH4.48m alleged demand | 20% kickback for acceptance | Suspicion | No | No |
| Dynamic tank protection | UAH102m alleged loss | Nearly 3× pricing / shell companies | Investigation completed | No | No |
| Armoured parts | >UAH350m supplied | State property allegedly written off and resold | Investigation | No | No |
| Local UAV/EW purchases | Amount not consolidated in cited release | Inflated / manipulated local procurement | Investigation completed | No | Public funds identified; no donor trace |
The matrix demonstrates why the $1.2 billion audit number cannot be summed with the individual NABU cases. Some of the underlying events can overlap, the accounting periods differ, and the audit category includes waste and mismanagement that may not constitute criminal loss.
Operation Midas: the most consequential energy-sector investigation
Operation Midas, opened publicly in November 2025, represents the largest active high-level corruption investigation in the energy-sector material examined for this report.
NABU describes the alleged core mechanism as a “barrier” or “tollgate” scheme within Energoatom: contractors were allegedly required to surrender up to 15% of contract value in order to obtain payment for services already provided or products already supplied, or to avoid losing supplier status. NABU — results for H2 2025
The allegation is structurally significant because it differs from tender overpricing. If proven, the system would represent extraction from existing counterparties after contract award, potentially creating incentives for suppliers to incorporate expected kickbacks into prices or refuse participation entirely.
Former energy minister: more than $112 million allegedly passed through a trusted person
NABU and SAPO served a former energy minister with a notice of suspicion in February 2026 for alleged participation in a criminal organisation and money laundering. Investigators allege that during his tenure the organisation received more than $112 million in cash through a trusted intermediary, originating from illegal activity in the energy sector, particularly the Energoatom barrier mechanism. NABU — former energy minister suspected in Midas case NABU — H1 2026 investigation report
NABU states that cryptocurrency and a foreign fund were among the alleged laundering instruments. The agency separately reported that a fund registered in Anguilla in 2021 had been structured to attract approximately $100 million in “investments”, according to the investigation. NABU — Midas former minister case
These figures are prosecutorial allegations, not findings of guilt.
Energoatom security executive: more than UAH30 million allegedly laundered
On 10 July 2026, NABU and SAPO notified a former Energoatom executive director for physical protection and security of suspicion of laundering more than UAH30 million allegedly derived from the barrier scheme. Investigators state that the money was used to acquire two Mercedes-Benz vehicles worth more than UAH8 million, property in Ukraine and Bali worth more than UAH19 million, and other assets registered through an associate. NABU — Operation Midas: new suspect
The investigation remains open and no conviction is established.
The UAH460 million “Dynasty” laundering case
Midas subsequently intersected with a separate alleged money-laundering structure involving high-level political figures.
On 12 May 2026, NABU and SAPO announced suspicion notices against seven people, including a former head of the Presidential Office, a former deputy prime minister and an individual described as one of the leaders of the criminal organisation uncovered during Midas. Investigators allege that the group laundered more than UAH460 million through construction of an elite residential complex in Kozyn between 2021 and 2025. NABU — laundering of UAH460 million through elite construction
NABU states that nearly $9 million used in the construction was channelled through an alleged laundering centre and derived from corruption schemes at Energoatom. HACC ordered seizure of land and five unfinished properties at the request of NABU and SAPO. NABU — H1 2026 investigation report
This is one of the stronger examples in the current record of investigators alleging a specific chain from an SOE corruption mechanism to identifiable assets. It is still an investigative allegation rather than a final judicial determination.
Sense Bank and the UAH150 million bail-payment allegation
A further expansion occurred in August 2026.
NABU and SAPO announced that members of a separate alleged criminal organisation, including political figures and persons connected to the Presidential Office, had used representatives and officials of a state-owned bank to move UAH150 million in cash through accounts of shell companies and introduce the funds into the legal financial system for the purpose of paying bail for a participant in the Midas case. NABU — corporate raiding and laundering investigation, 20 August 2026
High-quality Ukrainian reporting identified the bank as Sense Bank and reported that the UAH150 million was allegedly intended for bail associated with former energy minister Herman Halushchenko; the reporting also identified four companies that allegedly provided the payments. These identifications go beyond the naming contained in the initial NABU English-language release and should therefore remain attributed to the reporting rather than treated as a final judicial fact. Ukrainska Pravda — alleged UAH150 million bail laundering through state-owned bank
NABU subsequently announced an additional suspect on 28 August 2026, alleging participation in the laundering structure used to finance bail for a member of the Midas organisation. NABU — new suspect in corporate-raiding and laundering case
| Midas-related strand | Amount cited | Official status |
|---|---|---|
| Energoatom barrier / cash flow attributed to organisation during former minister’s tenure | >$112m | NABU allegation; investigation ongoing |
| Dynasty residential complex | >UAH460m allegedly laundered | Suspicion; assets seized |
| Portion reportedly linked to Energoatom | ~$9m | NABU investigative allegation |
| Former Energoatom security executive | >UAH30m allegedly laundered | Suspicion |
| Bail-payment laundering | UAH150m | Suspicion; investigation ongoing |
| Court convictions in these Midas strands | — | None established in the sources cited above |
Energoatom beyond Midas: Tashlyk construction
Operation Midas should not obscure other independent Energoatom-related corruption investigations.
On 2 June 2026, NABU and SAPO announced allegations concerning construction at the Tashlyk Pumped Storage Power Plant. Investigators allege that a company repeatedly failed to meet deadlines and was already in bankruptcy proceedings, yet continued receiving supplementary agreements; more than 70 supplementary agreements were reportedly signed. Under one such agreement, automated control-system equipment was purchased for more than UAH305 million, while the use of a controlled foreign company allegedly inflated the price by nearly UAH170 million. NABU — Tashlyk PSPP case
Two suspects were identified in NABU’s H1 2026 reporting, and the investigation remained open. NABU — H1 2026 investigation report
This case is particularly relevant to international financiers because it concerns critical infrastructure and a state energy company, but the NABU release does not establish that the allegedly inflated equipment purchase was financed from a particular EBRD, EIB, EU, U.S. or other donor facility.
“Green tariff” payments: UAH141 million alleged loss
NABU’s 2026 reporting identifies another energy case involving a former deputy head of the Presidential Office and eight additional suspects. According to investigators, solar plants controlled by the group received more than UAH141 million in green-tariff payments during 2022–23 for electricity allegedly generated and supplied from Russian-occupied areas of Zaporizhzhia region, with inaccurate generation data allegedly used to justify the payments. NABU — H1 2026 investigation report
The case remains under investigation and is separate from Midas.
Energy-sector exposure matrix
| Case | Institution | Alleged amount | Alleged mechanism | Legal status | Donor tranche proven? |
|---|---|---|---|---|---|
| Midas barrier scheme | Energoatom | Kickbacks up to 15% of contractor payments | Payment / supplier-status extortion | Investigation | No |
| Former minister Midas strand | Energy sector / Energoatom orbit | >$112m cash alleged | Criminal organisation / laundering | Suspicion | No |
| Dynasty laundering | High-level political / property network | >UAH460m | Laundering through luxury construction | Suspicion / asset seizures | No |
| Energoatom-linked portion of Dynasty | Energoatom orbit | ~$9m | Alleged proceeds moved into property | Investigation | No |
| Energoatom security executive | Energoatom | >UAH30m | Laundering / luxury assets / crypto | Suspicion | No |
| Midas bail-payment structure | State-owned bank / shell companies | UAH150m | Alleged laundering for bail | Suspicion | No |
| Tashlyk PSPP | Energoatom | ~UAH170m alleged overpricing | Controlled foreign intermediary | Investigation | No |
| Green tariffs | Energy payment system | >UAH141m | Alleged false generation reporting | Investigation | No |
The table shows why it would be analytically false to describe these amounts as a single “Energoatom theft total”. They originate from separate proceedings, partly overlapping actors, different time periods and different legal theories.
Infrastructure and reconstruction: verified wartime cases
The reconstruction sector presents a different vulnerability: donors and Ukrainian authorities finance visible physical assets whose existence can be independently checked, yet invoice manipulation, contractor selection, incomplete construction and false acceptance certificates can still produce significant losses.
Donetsk heating and water projects
In November 2025 NABU and SAPO announced that an organised group allegedly misappropriated more than UAH140 million intended for heating and water infrastructure in frontline communities in Donetsk region. Investigators allege inflated equipment and construction costs, simulated competition and contracts awarded to a controlled company. NABU — frontline heating and water projects
A contract worth more than UAH200 million covered seven modular boiler houses in Selydove and Ukrainsk. NABU states that only two were connected and that even those were non-functional. In Sviatohirsk, investigators allege that works were either not performed or completed without necessary documentation and that completion certificates were falsified. Five people had received suspicion notices when NABU disclosed the case. NABU — Donetsk reconstruction case
This case demonstrates why donor oversight of reconstruction must include physical functionality testing, not merely confirmation that an invoice corresponds to a signed contract.
Kyiv Metro: free rolling stock, UAH137.5 million alleged transport loss
NABU and SAPO announced on 15 September 2026 that seven suspects were implicated in alleged misappropriation of UAH137.5 million connected with delivery of 60 metro cars that Warsaw had offered to Kyiv free of charge. NABU — Kyiv Metro carriage-delivery case
According to the investigation, Kyiv Metro conducted tenders for freight-forwarding services; a pre-selected company allegedly won contracts worth approximately UAH190 million, transferred the money through a controlled foreign entity, paid the genuine carrier only a portion and allegedly diverted the remaining UAH137.5 million. NABU — Kyiv Metro case
The State Audit Service assisted the investigation. The case is at suspicion / pre-trial stage.
Lviv road expenditure
In June 2026 NABU and SAPO served a suspicion notice on a senior regional infrastructure official in connection with approximately UAH94 million in expenditure allegedly made from inappropriate budget headings for capital works on the M-10 Lviv–Krakivets route. Investigators state that more than UAH92 million was paid in December 2022 and nearly UAH2 million more in 2023. NABU — Lviv road budget case
This case is legally different from the classic embezzlement files because the allegation concerns misuse of budget allocations, demonstrating why not every procurement irregularity should be classified as bribery or theft.
SOE and asset leakage: fuel, rail and state-property exposure
Ukrnafta petroleum-products case
On 15 September 2026 NABU and SAPO announced a major investigation concerning alleged misappropriation of 100,000 tonnes of petroleum products belonging to PJSC Ukrnafta and laundering of proceeds from their sale. The first public episode covered activity between 2017 and 2020 and involved suspicion notices against four alleged participants. NABU — 100,000 tonnes of petroleum products case
Because the underlying conduct largely predates the February 2022 invasion, it should not be presented as leakage from the post-2022 donor architecture. It remains relevant to SOE governance because it illustrates the legacy control problems that wartime external financing encounters.
Ukrzaliznytsia cable procurement
In another state-enterprise procurement case, NABU alleged losses exceeding UAH140 million through procurement of cable products at inflated prices for Ukrzaliznytsia, with multiple suspects identified. NABU — Ukrzaliznytsia procurement cases
Because Ukrzaliznytsia receives significant IFI and donor financing, the case has obvious fiduciary relevance; however, the public criminal record does not establish that the allegedly corrupt cable contracts were paid from a defined EIB, EBRD, EU or bilateral donor facility.
What the enforcement statistics actually show
NABU and SAPO reported an economic effect of UAH2.06 billion in the first half of 2026, comprising several categories that should not be conflated. NABU — economic impact H1 2026
| H1 2026 enforcement outcome | Amount |
|---|---|
| Reimbursed to the state in ongoing / court-referred cases | >UAH864m |
| Bail, funds and property transferred to Defence Forces by court decision | >UAH139m |
| Savings generated in UAV procurement | UAH726m |
| Funds/property confiscated under effective court decisions | >UAH321m |
| Civil forfeiture under effective decisions | UAH4.2m |
| Court fines | UAH736,100 |
| Cumulative reimbursement to state by 30 June 2026 | UAH12.3bn |
| Cumulative assets transferred to defence by court order | >UAH3.2bn |
These values cannot be interpreted as “corruption recovered” in a single accounting sense. Procurement savings represent avoided expenditure, while reimbursement is actual recovery, confiscation requires a legally effective decision and bail transferred to military purposes is a separate judicial mechanism. NABU — H1 2026 report
The statistics nevertheless demonstrate that anti-corruption enforcement is producing measurable financial consequences rather than only press announcements.
A critical distinction: suspected loss versus judicially established damage
The cases examined above can be arranged according to evidentiary maturity.
| Case | Audit / investigation | Suspicion | Case completed / sent toward court | Effective conviction cited here |
|---|---|---|---|---|
| $1.2bn 2024 defence-procurement estimate | ✓ | — | — | — |
| SSSCIP drones | ✓ | ✓ | — | — |
| Border Guard drone procurement | ✓ | ✓ | — | — |
| EW acceptance | ✓ | ✓ | — | — |
| Tank dynamic protection | ✓ | ✓ | ✓ | — |
| Local UAV / EW procurement | ✓ | ✓ | ✓ | — |
| Midas former minister | ✓ | ✓ | — | — |
| Dynasty laundering | ✓ | ✓ | — | — |
| Sense Bank / bail laundering strand | ✓ | ✓ | — | — |
| Tashlyk Energoatom | ✓ | ✓ | — | — |
| Donetsk reconstruction | ✓ | ✓ | — | — |
| Kyiv Metro | ✓ | ✓ | — | — |
The absence of an effective conviction in this table is not evidence that the allegations are false; it means only that the procedural record available at the reporting cut-off does not permit those allegations to be written as adjudicated facts.
Donor-fund tracing: the evidence is much weaker than institutional exposure
This is the most important forensic limitation in the chapter.
The public record establishes that organisations such as the Ministry of Defence, Energoatom, Ukrzaliznytsia, municipalities and other Ukrainian public bodies operate in sectors receiving substantial foreign support. It does not follow that every corrupt transaction involving those bodies used donor money.
A valid donor-fund attribution requires at least the following chain:
identified donor instrument → documented transfer or reimbursement → Ukrainian budget programme / designated project → contracting authority → contract → payment → alleged corrupt transaction.
The current public record for the principal NABU/SAPO cases discussed above generally stops before the first step can be connected to the last.
| Case | State/public money involved? | Foreign-supported sector? | Specific donor tranche publicly traced? |
|---|---|---|---|
| SSSCIP drones | Yes | Yes | No |
| Border Guard UAV procurement | Yes | Yes | No |
| Dynamic protection | Yes | Yes | No |
| Local UAV/EW procurement | Yes | Yes | No |
| Midas / Energoatom | Yes / SOE revenues | Yes | No |
| Tashlyk | Yes / Energoatom | Yes | No |
| Donetsk reconstruction | Yes | Yes | No identified donor trace in NABU release |
| Kyiv Metro transport | Yes / municipal funds | International in-kind donation involved | No donor-financed payment chain established |
| Ukrzaliznytsia procurement | Yes / SOE | Yes | No |
The Kyiv Metro case is especially instructive: Warsaw donated rolling stock at no charge, but Ukrainian authorities allegedly lost money in the transport contract, not in the donated asset itself. This demonstrates why a foreign connection to a project does not automatically mean foreign cash was diverted.
Donor response: stronger conditionality rather than documented case-specific suspension
The official sources examined for this assessment do not establish a broad U.S., EU, IMF or World Bank suspension of financing specifically because of any one of the defence, Energoatom or infrastructure cases described above.
The response visible in the official record is instead institutional.
The European Council amended the Ukraine Plan on 30 July 2026 to add further reform requirements, explicitly including new steps on rule of law and anti-corruption, while linking continued Ukraine Facility payments to implementation of agreed reforms. Council of the EU — amendment of the Ukraine Plan, 30 July 2026
The IMF’s July 2026 review recorded delays in structural reforms and specifically noted that a benchmark requiring risk-based verification of senior officials’ asset declarations had been missed and was proposed for reset to end-September 2026. The programme maintained requirements to preserve the operational independence of NABU, SAPO and HACC and continued to identify energy, public procurement and other high-risk sectors as anti-corruption priorities. IMF — 2026 Article IV and First EFF Review
The IMF’s September 2026 technical assessment further concluded that Ukraine’s asset-declaration system remains unusually extensive but is constrained by approximately 700,000 filers, limited administrative capacity, gaps in cross-border financial data and weaknesses in inter-agency cooperation, recommending greater concentration on senior officials and high-risk sectors such as SOEs, customs and public procurement. IMF — Ukraine: Enhancing the Asset Declaration System for Public Officials
On the U.S. side, GAO’s September 2026 priority recommendations to the State Department continued to emphasise fraud-risk management and oversight of U.S. security assistance, specifically stating that improved implementation would help determine whether direct budget-support funds had been used as intended. GAO — Priority Open Recommendations: Department of State, September 2026
GAO had already identified specific weaknesses in direct-budget-support monitoring: its analysis of Ukrainian expenditure data found 161 unusual increases among 5,121 expenditure changes, including one salary-category increase of 2,474%, or approximately $1.07 million, which GAO considered worthy of further examination. That analysis did not establish theft; it demonstrated that available data had not been systematically exploited for fraud detection. GAO — Foreign Assistance: Opportunities Exist for Agencies to Improve Their Management of Fraud, Waste, and Abuse Risks
This distinction matters: donor oversight has identified weaknesses and intensified controls, but those controls cannot be cited as proof that the criminal cases discussed above involved donor funds.
What has been established, what remains alleged
Established by official record
Ukraine’s official anti-corruption authorities have active cases involving defence procurement, energy-sector contracting, reconstruction and SOE assets; NABU and SAPO have issued suspicion notices in multiple high-value cases; several defence investigations have progressed to completion of pre-trial investigation; HACC has ordered asset restraints in some high-level cases; and anti-corruption enforcement produced more than UAH2.06 billion of quantified economic effect in H1 2026 according to NABU’s methodology. NABU — H1 2026 results
Established by first-tier investigative reporting, but not yet publicly released as complete official audit documentation
Confidential Ukrainian audits reportedly estimated approximately $1.2 billion of 2024 defence-procurement fraud, waste and mismanagement, identified persistent use of non-performing suppliers and documented decisions in which lower-cost offers were bypassed. The New York Times — defence-procurement investigation
Alleged by investigators but not proven by final court judgment
The $112 million Midas cash flow, the UAH460 million Dynasty laundering structure, the UAH150 million bail-payment laundering scheme, the UAH254 million SSSCIP drone losses, the $1 million Border Guard demand, the UAH170 million Tashlyk overpricing and the other active NABU/SAPO cases remain allegations subject to criminal adjudication. NABU — H1 2026 investigation report
Not established
The present public record does not establish that the $1.2 billion reported defence-procurement loss represents $1.2 billion of stolen money; it does not establish that the documented defence cases collectively consumed a specified percentage of Western military assistance; it does not prove that Operation Midas diverted U.S., EU, EBRD, EIB or IMF resources; it does not establish that every Energoatom contractor participated in the alleged barrier mechanism; and it does not justify treating an investigation, detention, bail decision or asset seizure as a conviction.
Analytical implications
The strongest evidence of systemic vulnerability is not any single stack of cash, individual bribe or spectacular raid. It is the recurrence of control failures across different stages of public contracting: supplier qualification, price evaluation, intermediary selection, advance payment, contract execution, acceptance, inventory accounting, amendment of underperforming contracts and recovery of losses.
The most serious defence-procurement warning is therefore the reported finding that suppliers could continue receiving contracts despite previous failures. If fully substantiated by publication of the underlying audits, this would imply that the system’s weakness is not confined to detecting corruption but extends to institutional memory and exclusion discipline: information existed about supplier risk but did not consistently prevent renewed exposure.
The energy evidence points to a different weakness. Operation Midas, if ultimately proven, would demonstrate that formal procurement competition alone cannot prevent corruption where an informal system can extract payments after contract award by controlling whether invoices are paid or supplier status is preserved. This is a cash-flow governance vulnerability, not merely a tendering vulnerability.
The infrastructure cases reveal a third problem: verification of physical outcome. Boiler houses can be delivered but remain unusable; free metro rolling stock can still generate an allegedly corrupt transport contract; road works can be financed from inappropriate budget lines. Effective controls therefore have to verify functionality and funding legality rather than merely documentary completion.
Residual risk matrix
| Risk | Evidence in public record | Financial consequence | Current control weakness | Residual assessment |
|---|---|---|---|---|
| Supplier repeatedly awarded contracts after default | Confidential audit reporting | High | Weak exclusion / performance history | Material |
| Overpriced intermediary procurement | Audit + investigative reporting | High | Direct-manufacturer comparison insufficiently enforced | Material |
| Advance payment without delivery | Procurement audit pattern | High | Recovery can be slow | Material |
| Acceptance-stage bribery | Multiple NABU cases | Medium–high | Inspector discretion | Material |
| Crypto laundering | Border Guard / Midas-related cases | Medium | Cross-border and wallet tracing | Material |
| SOE payment extortion | Midas allegation | Potentially very high | Control of payment / supplier status | Material if proven |
| Reconstruction false completion | Donetsk case | Medium–high | Physical verification | Material |
| Direct donor-fund theft | Limited transaction-level public proof in examined cases | Undetermined | Attribution gap | Not quantifiable from current record |
| Criminal convictions in principal active 2026 cases | Limited | — | Judicial process ongoing | Not yet established |
What would materially change this assessment
Publication of the underlying State Audit Service and Ministry of Defence audits covering 2024–25 would materially improve confidence because it would permit the reported $1.2 billion to be disaggregated into criminally suspected losses, economically recoverable receivables, ordinary contract disputes, defective deliveries, avoidable overpayments and administrative waste.
Publication by the Defence Procurement Agency of a contract-performance ledger containing contract value, advance paid, amount delivered, overdue amount, penalties assessed, penalties recovered, supplier previous defaults and current litigation status would make it possible to distinguish systemic financial leakage from wartime delivery friction.
Formal indictments or HACC judgments in the principal Midas, SSSCIP, Border Guard, Tashlyk and reconstruction cases would change the evidentiary classification of those claims.
Most importantly for the external-financing investigation, documentary evidence tracing a specific donor grant, loan or guarantee through the Ukrainian budget or project ledger to one of the impugned contracts would change the current conclusion that institutional exposure is demonstrated, but donor-fund diversion is generally not yet proven at transaction level.
Pillar II key judgments
The first judgment is that Ukraine’s wartime corruption exposure is empirically significant and cannot be dismissed as a collection of minor isolated cases. The combined audit evidence, official suspicion notices and enforcement statistics demonstrate recurrent weaknesses in defence, energy, infrastructure and SOE control systems. NABU — H1 2026 results
The second judgment is that the reported $1.2 billion 2024 defence-procurement figure is the most important unresolved quantitative finding, but it is not presently a judicially established theft figure. It combines fraud, waste and mismanagement according to confidential audits reported by The New York Times, and must be independently reconstructed before it is used as a measure of corruption loss. The New York Times — defence-procurement investigation
The third judgment is that the dominant control weakness is shifting from simple tender manipulation toward contract performance and post-award governance. Several cases concern acceptance, payment blocking, repeated use of non-performing suppliers, contract amendments, defective delivery or failure to enforce previous defaults rather than only the original tender.
The fourth judgment is that Operation Midas is institutionally serious because investigators allege a mechanism capable of taxing otherwise legitimate Energoatom counterparties through payment control, but the allegations remain under investigation and have not been converted into collective convictions. NABU — Midas reporting
The fifth judgment is that the current public record does not support a numerical assertion that a defined share of U.S., EU or bilateral donor assistance has been stolen. The evidence proves exposure of donor-supported institutions and sectors to corruption risk; it generally does not provide the complete transaction chain necessary to attribute the alleged criminal proceeds to a named foreign financing instrument.
The sixth judgment is that donor conditionality remains active rather than abandoned. The EU added anti-corruption and rule-of-law steps to the Ukraine Plan in July 2026, the IMF preserved anti-corruption and high-risk-sector benchmarks despite delays, and U.S. GAO continued to press the State Department to strengthen fraud-risk and direct-budget-support monitoring. Council of the EU — Ukraine Plan amendment IMF — First Review of Ukraine EFF GAO — September 2026 State Department priority recommendations
Procurement Leakage, Corruption Cases & Evidentiary Status
Forensic mapping of documented defence, energy, reconstruction and state-owned-enterprise corruption exposure, distinguishing audit findings, investigative reporting, suspicion, indictment, judicial measures, final findings and proven donor-fund tracing.
Where Corruption Risk Appears in the Procurement Cycle
Defence Procurement Case Matrix
| Case | Amount / exposure | Alleged mechanism | Procedural status | Court finding? | Donor funds specifically traced? |
|---|---|---|---|---|---|
| 2024 confidential defence audits | ≈$1.2bn | Fraud, waste, mismanagement, non-performance | AUDIT / REPORTING | No | NO AGGREGATE TRACE |
| DPA rocket intermediary | ≈$130m additional reported cost | Higher-priced intermediary allegedly chosen over cheaper alternatives | AUDIT / REPORTING | No | No public trace |
| Reported lower-bid bypass | ≈$126m | Lower offers allegedly bypassed without lawful justification | AUDIT / REPORTING | No | No public trace |
| SSSCIP drone procurement | UAH254m alleged loss | Artificial competition and overpricing | SUSPICION | No final conviction | No |
| State Border Guard UAV procurement | $1m alleged bribe demand | Payment for smooth contract execution and acceptance | SUSPICION | No | No |
| Border Guard crypto strand | 50,000 USDT + >UAH15.4m conversions | Bribery and laundering alleged | SUSPICION | No | No |
| EW acceptance case | UAH4.48m alleged demand | 20% kickback allegedly demanded for acceptance | SUSPICION | No | No |
| Dynamic tank protection | UAH102m alleged loss | Nearly 3× pricing and shell-company routing | INVESTIGATION COMPLETED | No final judgment cited | No |
| Armoured-vehicle spare parts | >UAH350m supplied | Military property allegedly written off and resold | INVESTIGATION | No | No |
SSSCIP Drone Procurement
Source: NABU — revised UAH254 million drone procurement case .
State Border Guard UAV Case
Sources: NABU — original $1 million allegation ; NABU — additional crypto allegations .
Operation Midas and Energy-Sector Exposure
| Strand | Amount cited | Alleged mechanism | Status | Donor tranche proven? |
|---|---|---|---|---|
| Energoatom barrier mechanism | Up to 15% of contractor payments | Kickback allegedly required to obtain payment / retain supplier status | INVESTIGATION | No |
| Former energy minister strand | >$112m cash alleged | Criminal organisation / laundering | SUSPICION | No |
| Dynasty residential complex | >UAH460m | Luxury-property laundering alleged | SUSPICION + ASSET SEIZURE | No |
| Energoatom-linked portion of Dynasty | ≈$9m | Alleged proceeds moved into property construction | INVESTIGATION | No |
| Energoatom security executive | >UAH30m | Luxury assets / property / alleged laundering | SUSPICION | No |
| Bail-payment laundering | UAH150m | Shell-company and state-owned-bank channel alleged | SUSPICION | No |
| Tashlyk PSPP | ≈UAH170m alleged overpricing | Controlled foreign intermediary / inflated equipment pricing | INVESTIGATION | No |
Operation Midas — Core Allegation
NABU alleges that Energoatom counterparties were pressured to surrender up to 15% of contract value to secure payment or avoid exclusion from supplier status. If ultimately proven, this would represent post-award extraction rather than ordinary bid rigging.
Source: NABU — H2 2025 results and Midas investigation summary .
Tashlyk PSPP
NABU alleges that more than 70 supplementary agreements were concluded with a contractor despite delays and bankruptcy proceedings, while procurement of automated control-system equipment worth more than UAH305 million allegedly produced nearly UAH170 million in overpricing through a controlled foreign company.
Source: NABU — Tashlyk PSPP investigation .
Infrastructure and Reconstruction Exposure
| Case | Exposure | Alleged mechanism | Operational consequence | Status |
|---|---|---|---|---|
| Donetsk heating and water projects | >UAH140m alleged misappropriation | Inflated costs, simulated competition, false completion documents | Only 2 of 7 boiler houses connected; reportedly non-functional | SUSPICION |
| Kyiv Metro rolling-stock transport | UAH137.5m alleged loss | Transport contract allegedly routed through controlled foreign entity | Free donated rolling stock generated paid logistics exposure | SUSPICION |
| Lviv road expenditure | ≈UAH94m | Alleged use of inappropriate budget headings for capital works | Budget-allocation integrity issue rather than classic bribery case | SUSPICION |
Why physical verification matters
Reconstruction controls fail if audit stops at invoice and contract verification. The Donetsk case shows that infrastructure can be formally procured but remain unusable; the Kyiv Metro case shows that a foreign-donated asset can still generate alleged corruption in a secondary logistics contract. The control requirement is therefore contract + payment + physical delivery + operational functionality.
Donor-Fund Traceability Test
| Case | Public money involved? | Foreign-supported sector? | Named donor tranche publicly traced? |
|---|---|---|---|
| SSSCIP drones | Yes | Yes | NO |
| Border Guard UAV procurement | Yes | Yes | NO |
| Dynamic protection | Yes | Yes | NO |
| Operation Midas / Energoatom | Yes / SOE funds | Yes | NO |
| Tashlyk PSPP | Yes / SOE funds | Yes | NO |
| Donetsk reconstruction | Yes | Yes | NO IDENTIFIED TRACE IN PUBLIC NABU RECORD |
| Kyiv Metro | Yes | Foreign donated asset involved | NO DONOR CASH TRACE |
NABU / SAPO Enforcement Output
| H1 2026 category | Amount | Meaning |
|---|---|---|
| Reimbursed to state | >UAH864m | Actual reimbursement in ongoing or court-referred cases |
| Bail / property transferred to Defence Forces | >UAH139m | Judicially authorised transfer, not ordinary recovery |
| UAV procurement savings | UAH726m | Avoided expenditure, not recovered stolen money |
| Confiscated funds/property | >UAH321m | Confiscation under effective court decisions |
| Civil forfeiture | UAH4.2m | Assets recovered through civil mechanism |
| Cumulative state reimbursement by 30 Jun. 2026 | UAH12.3bn | Cumulative enforcement result reported by NABU |
Critical forensic distinction
The figures above cannot be summed into a single “corruption recovered” total. Reimbursement, confiscation, avoided procurement expenditure, civil forfeiture and judicial transfer of bail represent different economic and legal categories. Mixing them would create an invalid measure of actual losses.
Residual Exposure by Control Failure
| Control weakness | Evidence in current record | Primary financial consequence | Assessment |
|---|---|---|---|
| Repeat contracting after supplier default | Confidential defence-audit reporting | Repeated exposure to known non-performance | Material |
| Higher-priced intermediaries | Audit / NYT reporting | Avoidable procurement cost | Material |
| Advance payment without delivery | Recurring procurement pattern | Outstanding receivables and battlefield supply failure | Material |
| Acceptance-stage bribery | Multiple NABU cases | Corrupted inspection and supplier payment | Material |
| SOE payment extortion | Midas allegations | Systemic contractor “tax” if proven | Material if proven |
| False physical completion | Donetsk reconstruction case | Payment without functional infrastructure | Material |
| Proven donor-fund diversion | Limited transaction-level public evidence in examined cases | Not presently quantifiable | Unresolved |
Decision-relevant conclusion
The strongest evidence does not show one monolithic theft channel. It shows repeated vulnerabilities at supplier selection, pricing, advance payment, performance enforcement, acceptance, payment control, inventory accounting and physical project verification. The highest-value unresolved question is not whether corruption exists, which the official record clearly establishes, but how much of the wider procurement loss identified by audits represents criminally recoverable loss, ordinary contract failure, defective delivery, administrative waste or still-recoverable receivables.
Defence procurement audit reporting: The New York Times — In Ukraine, Fraud and Waste Are Rewarded With More Weapons Contracts .
Audit summary: Ukrainska Pravda — Ukraine lost over US$1bn on defence procurement in one year .
SSSCIP drone procurement: NABU — UAH254 million drone procurement case .
State Border Guard drone case: NABU — additional allegations in Border Guard UAV procurement .
Dynamic protection: NABU — UAH102 million dynamic-protection investigation .
Operation Midas: NABU — H1 2026 investigation report .
Energoatom / Tashlyk: NABU — Tashlyk PSPP investigation .
Donetsk reconstruction: NABU — frontline heating and water projects .
Kyiv Metro: NABU — Kyiv Metro rolling-stock delivery case .
EU anti-corruption conditionality: Council of the European Union — amendment of the Ukraine Plan .
IMF governance conditions: IMF — Ukraine 2026 Article IV Consultation and First EFF Review .
U.S. fraud-risk oversight: U.S. GAO — Priority Open Recommendations: Department of State .
Pillar III — Donor Accountability, Conditionality and Forward Controls
Principal judgment
The decisive accountability question for Ukraine in 2026 is no longer whether donor oversight exists; it plainly does, through overlapping U.S., EU, World Bank, IMF, Ukrainian and independent-audit structures. The harder question is whether those structures are sufficiently integrated to identify the same underlying transaction across donor authorisation, Ukrainian budget execution, procurement, contractor ownership, delivery and criminal investigation, and whether financial consequences follow when agreed controls are missed.
The record through 25 September 2026 shows a system that is considerably more conditional than popular descriptions of “blank-cheque aid” imply, but less integrated than would be required for reconstruction and defence-industrial financing on the scale now contemplated. The United States operates through congressional reporting, GAO, State/DoD/USAID inspectors general, end-use monitoring and World Bank-mediated direct-budget-support controls; the European Union combines milestone-based disbursement with an independent Ukraine Facility Audit Board, Commission supervision, OLAF, potentially the EPPO, the European Court of Auditors and Ukrainian audit institutions; the World Bank verifies expenditure eligibility and layers independent audits over Ukrainian systems; and the IMF conditions access to financing on macroeconomic and structural benchmarks that explicitly include anti-corruption, SOE governance, energy regulation and preservation of the independence of NABU, SAPO and HACC. GAO — Priority Open Recommendations: Department of State, September 2026 EU Regulation 2024/792 establishing the Ukraine Facility IMF — Ukraine 2026 Article IV Consultation and First EFF Review GAO
The more important weakness is therefore fragmentation of assurance. A World Bank audit can establish that an expenditure was eligible for reimbursement without determining whether a subsequently procured asset was competitively priced; an EU milestone can establish that legislation or a reform measure was adopted without demonstrating that every downstream contract was clean; U.S. end-use monitoring can confirm possession of sensitive weapons without examining Ukrainian civilian-budget controls; and NABU can investigate a corrupt contract without necessarily having a machine-readable record showing whether the underlying budget programme had previously been reimbursed by an external donor.
For future accountability, the relevant objective is not simply “more audits”. It is interoperable auditability.
The accountability architecture: who controls what
| Oversight layer | Principal institution | What it can test | What it generally cannot establish alone |
|---|---|---|---|
| Appropriation legality | U.S. Congress / EU budget authority / national parliaments | Whether funds were legally authorised | Whether a Ukrainian contractor later performed |
| Donor programme execution | State, DoD, USAID legacy mechanisms, European Commission | Whether donor agencies complied with programme rules | Full downstream Ukrainian criminal liability |
| External audit | GAO, U.S. OIGs, ECA, Ukraine Facility Audit Board | Controls, compliance, weaknesses, value-for-money questions | Criminal guilt |
| IFI financial management | World Bank, IMF, EBRD, EIB | Expenditure eligibility, PFM, covenants, macro/structural compliance | Every subcontractor relationship |
| Ukrainian fiscal control | Ministry of Finance, Treasury, Accounting Chamber, State Audit Service | Budget execution and administrative compliance | Complete donor-side contractual history |
| Anti-corruption investigation | NABU / SAPO | High-level corruption and evidence gathering | Donor appropriation decisions |
| Judicial determination | HACC / other competent courts | Criminal liability and judicial remedies | Broader donor-policy effectiveness |
| End-use monitoring | DoD / State security-assistance mechanisms | Possession, custody and use of controlled defence items | Civilian expenditure integrity |
| Anti-fraud investigation | OLAF / potentially EPPO | EU-financial-interest fraud and related offences | Ukrainian matters falling outside EU financial interests |
The architecture is therefore complementary rather than hierarchical. No single institution controls the entire pipeline.
United States: oversight became more institutionalised, but GAO still identifies material gaps
The U.S. oversight model is unusually audit-intensive. State OIG describes Ukraine-related oversight as a priority and states that State, DoD and USAID OIGs coordinate through the Ukraine Oversight Interagency Working Group and the FY2026 Joint Strategic Oversight Plan, covering security assistance, non-security assistance and management operations. State OIG — Ukraine-Related Oversight stateoig.gov
The statutory Special Inspector General for Operation Atlantic Resolve reporting architecture adds quarterly reporting to Congress. The August 2026 report covered U.S. funding, programmes and operations from 1 April to 30 June 2026 and integrated oversight work by DoD, State, USAID OIG and other agencies participating in the interagency working group. State OIG — Special Inspector General for Operation Atlantic Resolve, Q2 2026 stateoig.gov
This system should not be confused with the former SIGAR model for Afghanistan. The Ukraine structure distributes responsibility across existing inspectors general, GAO and the Special Inspector General reporting mechanism rather than creating one standalone authority controlling every U.S. Ukraine dollar.
Direct budget support: the most important unresolved U.S. oversight issue
GAO’s September 2025 review established that the United States had provided more than $45 billion in direct budget support, of which USAID managed and disbursed approximately $30.2 billion, predominantly through the World Bank PEACE project. The Treasury separately transferred $20 billion to the World Bank in December 2024, with at least $15 billion intended for direct budget support financed through the Russian-asset-derived architecture. GAO — State Should Build on USAID’s Oversight of Direct Budget Support GAO
GAO identified 161 unusual increases among 5,121 expenditure changes in data it analysed and concluded that the causes warranted further examination. It also found that USAID had not used some expenditure data that could have strengthened fraud-risk oversight and that contractors had identified weaknesses in Ukrainian internal controls that had not been sufficiently prioritised. GAO did not conclude that the 161 observations represented fraud. GAO — Direct Budget Support oversight findings GAO
The distinction is central:
an anomaly is an investigative lead, not a corruption finding.
GAO issued five recommendations to the Department of State. As of the April 2026 status update reported by GAO, all five remained open. State said it intended to coordinate with the World Bank and had transmitted Deloitte recommendations to Ukraine, but GAO had not yet received sufficient evidence that State had systematically followed up the unusual expenditure changes, corrected earlier congressional reporting, submitted all required reporting, prioritised Deloitte’s identified weaknesses or verified remediation of weaknesses identified by PwC. GAO — recommendation status and agency responses GAO
By 8 September 2026, GAO elevated fraud management and security-assistance oversight among the Department of State’s priority open recommendations, explicitly stating that implementation would help determine whether Ukrainian direct-budget-support funding had been used as intended. GAO — Priority Open Recommendations: Department of State GAO
U.S. direct-budget-support control stack
| Layer | Function | Documented strength | Documented limitation |
|---|---|---|---|
| Ukrainian MoF | Collects and validates expenditure information | Centralised reporting to World Bank | Depends on underlying agency data |
| World Bank | Determines expenditure eligibility before reimbursement | Ex ante reimbursement verification | Does not replace all donor fraud-risk analysis |
| Independent financial audit | Tests financial statements / reporting | Formal annual assurance | Financial audit ≠ forensic investigation |
| PwC reviews | Additional control review | Identifies system weaknesses | Remediation must be tracked |
| Deloitte monitoring | Reviews Ukrainian control environment | Produced 56 recommendations according to GAO | USAID did not fully prioritise risk severity |
| KPMG audit work | Additional independent assurance | Added external audit layer | Different scope from fraud investigation |
| GAO | Independent congressional audit | Detected unusual expenditure changes | Cannot itself prosecute misconduct |
| State oversight | Responsible since July 2025 | Continuing World Bank coordination | GAO found follow-up actions incomplete |
The key forward-control issue is therefore closure of audit findings. Identifying 56 control recommendations is less consequential than documenting which were critical, which were implemented, which failed and what financial exposure remained after remediation.
U.S. military oversight: possession, valuation and contracting are different control problems
The United States operates separate controls over defence assistance because military aid creates risks that budget-support audits cannot detect.
State’s end-use-monitoring responsibilities include programmes under the Arms Export Control Act and Foreign Assistance Act, while DoD conducts enhanced end-use monitoring for designated sensitive systems. State OIG’s review describes the legally required end-use-monitoring architecture for U.S.-origin defence articles and services. State OIG — Review of Department of State End-Use Monitoring in Ukraine stateoig.gov
DoD OIG subsequently found that, despite improved reporting processes, hostile-environment conditions still limited serial-number inventories of enhanced-end-use-monitored equipment, although improved procedures gave DoD visibility over thousands of additional sensitive items. DoD OIG — Follow-up Evaluation of Enhanced End-Use Monitoring Dodig
Military accountability also has a valuation dimension. GAO reported that DoD had previously misvalued equipment provided to Ukraine under Presidential Drawdown Authority by approximately $6.2 billion, reflecting inconsistent valuation rules rather than evidence that Ukraine had stolen $6.2 billion. GAO recommended clearer PDA-specific valuation procedures, and DoD subsequently developed additional guidance. GAO — Ukraine Assistance: Actions Needed to Properly Value Defense Articles GAO
That episode demonstrates a fundamental forensic point: accounting error, procurement waste, diversion and corruption are separate phenomena and should never be merged into one “missing aid” figure.
The 2025 U.S. foreign-assistance pause: a real interruption, but not a corruption-case sanction
On 20 January 2025, a U.S. executive order required an immediate pause in new obligations and disbursements of foreign development assistance pending policy review. GAO later confirmed that the pause included early-recovery assistance to Ukraine; some activities were closed out while others subsequently resumed. GAO — State Should Take Additional Actions to Improve Planning for Any Future Recovery Assistance GAO Files
The public record reviewed for this report does not establish that this pause was triggered by a Ukrainian corruption case. It was a broader U.S. foreign-assistance policy review.
Similarly, the official sources reviewed through 25 September 2026 do not establish a case-specific congressional hold imposed because of the 2026 NABU defence or Energoatom investigations discussed in Pillar II. That absence should not be converted into a claim that no congressional office has ever raised or delayed Ukraine funding; it means that no such 2026 corruption-linked hold is established in the official evidence reviewed here.
European Union: conditionality is embedded directly into payment mechanics
The EU model differs structurally from the U.S. system because reform performance is part of the legal machinery governing disbursement.
The Ukraine Facility Regulation requires Ukraine to maintain effective democratic mechanisms and establishes the Ukraine Plan as the principal reform and investment roadmap. More than €40 billion of the €50 billion Facility is tied to reforms and investments, with payments dependent on qualitative and quantitative steps. Council of the EU — The Ukraine Facility Consiglio dell’Unione Europea
This conditionality is not purely theoretical.
For the seventh regular payment, approved in May 2026, Ukraine received nearly €2.8 billion after completing eleven of twenty steps required for that instalment plus outstanding steps from earlier payment cycles; the relevant reforms covered public financial management, the judiciary, corruption and money-laundering controls, financial markets, public assets, human capital, energy, transport and other sectors. Council — Seventh Ukraine Facility payment Consiglio dell’Unione Europea
On 24 September 2026, the Council approved the eighth regular payment of nearly €3 billion after Ukraine completed ten additional target steps. The Council reported that 84 of 95 steps due by that point had been completed, approximately 88%. Nearly €800 million of that payment was to come from the new Ukraine Support Loan. Council — Eighth Ukraine Facility payment, 24 September 2026 Consiglio dell’Unione Europea
The payment mechanism therefore allows partiality: failure to complete every step does not automatically terminate the entire Facility, but incomplete steps can reduce or defer amounts and be carried forward for later completion.
EU conditionality matrix
| Control component | Legal / institutional mechanism | Financial consequence |
|---|---|---|
| Democratic-system precondition | Article 5 / Facility framework | Support depends on continued compliance |
| Ukraine Plan reform steps | Quarterly qualitative and quantitative milestones | Determines regular payment eligibility |
| Commission assessment | Technical review before payment | Can reduce or defer payment |
| Council implementing decision | Member-state approval | Authorises payment |
| Framework Agreement | Management, audit, monitoring and anti-fraud obligations | Contractual/legal enforceability |
| Ukraine Facility Audit Board | Independent assessment of control systems | Recommendations, escalation to Commission |
| OLAF | EU administrative anti-fraud investigations | Recovery / administrative measures |
| EPPO where competent | Criminal investigation affecting EU financial interests | Prosecution |
| European Court of Auditors | External audit of EU finances | Independent public accountability |
| Ukrainian authorities | Prevention, detection, investigation and recovery | Domestic enforcement |
| Recovery clauses | Recovery / reduction / early repayment | Direct financial consequence |
The Ukraine Facility Audit Board: a significant but under-discussed control layer
The EU established the Ukraine Facility Audit Board in June 2024 specifically to increase the effectiveness of management and control systems and prevent fraud, corruption, conflicts of interest and irregularities. It operates independently of the Ukrainian government and is mandated through 30 June 2028. Commission Implementing Decision establishing the Ukraine Facility Audit Board EUR-Lex
The Commission describes the Board as consisting of three senior independent members based in Brussels supported by a secretariat in Kyiv, with authority to conduct audit checks on the ground and liaise with Ukrainian authorities. Five Ukraine Facility Dialogues with the European Parliament had also taken place by May 2026. European Commission — Ukraine Facility implementation and monitoring Enlargement and Eastern Neighbourhood
Its legal powers are more substantial than a purely advisory review mechanism.
Under Article 36, the Audit Board may report cases or serious concerns about mismanagement directly to the Commission, issue recommendations to Ukraine where authorities have not adequately prevented or corrected fraud or corruption, and transmit information to OLAF. Ukraine is expected to implement recommendations without undue delay or explain why it has not done so. EUR-Lex — Ukraine Facility Regulation, Article 36 EUR-Lex
The Regulation additionally requires organisations implementing Facility funds to report suspected or actual fraud, corruption, conflicts of interest and other illegal activities without delay to the Audit Board, Commission, OLAF and, where applicable, the EPPO. EUR-Lex — protection of EU financial interests under the Ukraine Facility EUR-Lex
This creates a legal reporting architecture that is substantially stronger than relying on ordinary post-expenditure financial audit.
EU recovery powers matter more than conditionality rhetoric
The Ukraine Facility Regulation expressly provides for prevention, detection and correction of fraud, corruption, conflicts of interest and irregularities, recovery of misused funds and measures against double financing.
Where irregularity, fraud, corruption or conflict of interest affects EU financial interests, the Commission can reduce financing or require early repayment, subject to proportionality and an opportunity for Ukraine to provide observations. Ukraine Facility Regulation — financial-interest protection and recovery EUR-Lex
This is a more meaningful control than political declarations because it establishes an actual financial remedy.
The principal accountability question for 2027 will therefore be not only how many irregularities the Audit Board identifies, but:
how many findings generate recovery, payment reduction, corrective action or procurement exclusion.
The €90 billion Ukraine Support Loan expands the importance of conditionality
The EU’s €90 billion support loan for 2026–27, consisting broadly of €30 billion for budget needs and €60 billion for defence-industrial capacity and military procurement, operates within what the Council describes as a “robust and conditional framework”, explicitly including adherence to the rule of law and the fight against corruption. Council — €90 billion Ukraine Support Loan, 23 April 2026 Consiglio dell’Unione Europea
The February 2026 legal framework states that defence procurement should in principle be sourced from companies in the EU, Ukraine or EEA-EFTA states, while allowing targeted derogations where urgently required military products are unavailable within that supplier universe. Council — legal framework for €90 billion support loan Consiglio dell’Unione Europea
Those derogations create a classic emergency-procurement control problem. Operational flexibility is necessary where battlefield availability is decisive, but each derogation weakens the normal supplier-universe constraint and should therefore produce a corresponding audit trail.
IMF conditionality: reform slippage has produced resets, not unconditional waiver
The IMF operates a different model because its primary objective is macroeconomic stability rather than project-level anti-fraud control.
In July 2026, the IMF Executive Board completed the first review of Ukraine’s new 48-month, $8.1 billion Extended Fund Facility, releasing approximately $690 million and bringing disbursements under the programme to about $2.2 billion. All end-March quantitative performance criteria had been met, but several structural reforms had been delayed or missed. IMF — First Review of Ukraine’s Extended Fund Facility IMF
The Fund’s detailed staff report is particularly important because it documents what “conditionality enforcement” actually means in practice.
The structural benchmark requiring the National Agency on Corruption Prevention to establish a risk-based system for verifying senior officials’ asset declarations was missed at end-June and proposed for reset to end-September 2026. A separate energy-sector analytical benchmark was proposed for reset from end-July to end-October. The IMF simultaneously introduced or reformulated additional benchmarks covering tax administration, state-owned enterprises, energy regulation and anti-avoidance measures. IMF — Structural Reforms and Governance Benchmarks, July 2026 eLibrary IMF
This is neither strict automatic suspension nor unconditional waiver.
It is conditionality with corrective action.
Anti-corruption institutions are themselves programme conditions
The IMF programme records a commitment by the Ukrainian authorities to preserve the operational independence, powers and resources of NABU, SAPO and HACC, including a commitment not to undermine those institutions through legal or regulatory changes. It also requires progress on senior-official asset verification and an independent external audit of the NACP. IMF — Ukraine governance and anti-corruption commitments eLibrary IMF
This matters because anti-corruption conditionality is no longer limited to passing procurement statutes. It extends to the institutional capacity to investigate and adjudicate breaches after they occur.
The IMF’s September 2026 technical-assistance assessment found that Ukraine’s asset-declaration system is among the largest and most advanced internationally but faces serious operational pressure from approximately 700,000 annual filers, capacity constraints and incomplete access to financial information, particularly cross-border data. IMF
That finding supports a risk-based rather than volume-based control strategy.
World Bank PEACE: reimbursement architecture with multiple verification layers
The World Bank’s PEACE project represents one of the most important experiments in large-scale wartime budget-support control.
The project uses Ukrainian financial-management systems rather than bypassing them completely. The Ministry of Finance collects and verifies expenditure information from spending entities, after which the World Bank determines whether expenditures meet eligibility criteria before reimbursement. If expenditure is determined to be ineligible, the Bank can recover the amount. World Bank — PEACE Project accountability architecture Banca Mondiale
The World Bank additionally reports:
- annual independent financial audits commissioned by the Ukrainian government;
- Agreed-Upon Procedures reviews by an independent audit firm;
- verification of expenditure controls;
- corrective-action recommendations;
- digital beneficiary-verification mechanisms;
- grievance-redress arrangements;
- the Listening to Ukraine survey for service-delivery verification;
- referral of fraud and corruption allegations to the World Bank Integrity Vice Presidency. World Bank — PEACE accountability safeguards Banca Mondiale
The World Bank reported that annual independent audits had issued clean opinions through the reporting period covered by its fact sheet. A clean financial audit should be interpreted narrowly: it supports the reliability of financial reporting within the audit scope; it does not prove that no corruption exists anywhere in the Ukrainian public sector.
PEACE accountability layers
| Control | Operator | Main function | Failure it is designed to detect |
|---|---|---|---|
| Expenditure verification | Ukrainian MoF | Validates submitted expenditure | Ineligible cost |
| Eligibility review | World Bank | Confirms reimbursement eligibility | Non-compliant expenditure |
| Independent annual audit | Independent auditor | Financial-statement assurance | Material financial misstatement |
| Agreed-Upon Procedures | External firm | Tests expenditure and control operation | Specific control weakness |
| Digital beneficiary verification | Ukraine / World Bank | Confirms eligible recipient | Ghost / duplicate beneficiary |
| Listening to Ukraine survey | World Bank | Tests service delivery | Payment without service effect |
| Grievance mechanism | Ukrainian system | Receives complaints | Local implementation irregularity |
| INT referral | World Bank Integrity VP | Investigates fraud/corruption | Sanctionable misconduct |
The 2025 Ukraine Relief, Recovery, Reconstruction and Reform Trust Fund report states that PEACE remained high risk, reflecting wartime security, political, social and macroeconomic conditions, even while enhanced controls remained in place. World Bank — URTF 2025 Annual Report World Bank
High residual risk and strong controls are therefore not contradictory. They describe different dimensions of the same programme.
Immobilised Russian sovereign assets create a two-sided accountability obligation
The G7 Extraordinary Revenue Acceleration structure introduces an accountability problem not present in conventional donor grants because the financing chain has two auditable sides:
generation of extraordinary revenues from immobilised Russian sovereign assets → allocation / servicing of G7 loans → Ukrainian use of the loan proceeds.
The EU contribution to the G7 ERA initiative is up to €18.1 billion, with servicing and repayment intended to come from extraordinary revenues generated by immobilised Russian sovereign assets. European Commission — ERA macro-financial assistance architecture Economy and Finance
The Council’s broader 2026 support accounting records approximately €3.8 billion in proceeds from immobilised Russian assets already incorporated within the EU support architecture. Council of the EU — Russia’s war against Ukraine: financial support totals Consiglio dell’Unione Europea
For oversight purposes, four separate ledgers are therefore required:
| Ledger | Audit question |
|---|---|
| Immobilised principal | What Russian sovereign assets remain immobilised and under whose custody? |
| Extraordinary revenue | How much income has been generated, under what accounting basis and period? |
| Loan servicing | Which ERA obligations are being serviced and when? |
| Ukrainian expenditure | Where did the corresponding financing ultimately go? |
Collapsing these four layers into one number would make reconciliation impossible.
Emergency procurement: flexibility is necessary, but waivers require their own control architecture
The principal wartime procurement vulnerability identified across Pillars I and II is not the existence of emergency procedures itself; it is the possibility that procedures designed for exceptional urgency become permanent and cease to generate sufficient evidence for later review.
A defensible emergency-procurement system needs to preserve six elements even where open competition is impracticable:
| Minimum control | Why it survives wartime urgency |
|---|---|
| Written emergency justification | Establishes why ordinary competition could not be used |
| Beneficial-owner identification | Detects conflicts and related parties |
| Price benchmark | Permits later assessment of reasonableness |
| Advance-payment ceiling | Limits loss before delivery |
| Delivery / acceptance record | Links expenditure to physical output |
| Time-limited waiver | Prevents emergency status becoming indefinite |
The EU’s €90 billion support-loan framework is relevant because it expressly permits targeted derogations from normal supplier-geography rules where urgently required defence products are unavailable from the EU, Ukraine or EEA-EFTA supplier base. Council — Ukraine Support Loan procurement framework Consiglio dell’Unione Europea
The audit issue is therefore not whether derogations should exist, but whether each derogation remains traceable, reviewable and temporary.
Counter-disinformation safeguards: verification must begin with the originating institution
The corruption-information environment introduces an unusual accountability problem because fabricated scandals can now circulate faster than real investigations.
On 25 September 2026, Ukraine’s Center for Countering Disinformation stated that online material claiming NABU had searched premises linked to former Defence Procurement Agency head Arsen Zhumadilov and found approximately $140 million in refrigerator boxes was false. The Center said NABU confirmed that no such search or procedural action had taken place and that the circulated video was AI-generated. Ukraine Center for Countering Disinformation — fake NABU search involving former DPA head cpd.gov.ua
This is especially instructive because a publication visually resembling a conventional Ukrainian media report had already presented the fabricated event as an exclusive story. That demonstrates why media appearance alone cannot satisfy a forensic source standard. nvukraine.com
The appropriate verification sequence for spectacular corruption allegations is therefore:
official NABU/SAPO register or release → HACC procedural record where applicable → identifiable case or proceeding → original media source → visual-forensics check → secondary replication only after primary confirmation.
The Center has documented related 2026 operations in which fabricated videos and false screenshots were presented under the branding of established media outlets, including an earlier fabricated claim about $11 million supposedly found in accounts associated with the President’s parents. cpd.gov.ua
The objective of such operations is directly relevant to donor accountability because invented “cash seizure” spectacles exploit a real vulnerability—public concern about corruption—to create false evidence intended to undermine confidence in external support.
Donor-control comparison
| Dimension | United States | European Union | World Bank | IMF |
|---|---|---|---|---|
| Primary accountability tool | IG / GAO / congressional reporting | Milestone conditionality + audit system | Expenditure verification | Programme conditionality |
| Direct transaction audit | Strong in selected programmes | Strong under Facility financial-interest rules | Strong for eligible expenditure | Limited |
| Reform conditionality | Programme-specific | Central to payment system | Project / DPO conditions | Central to programme |
| Criminal-investigation function | U.S. law-enforcement/OIG referrals | OLAF / EPPO where competent | INT sanctions/referrals | None |
| Ukrainian anti-corruption independence condition | Policy and programme concern | Rule-of-law conditionality | Governance requirements | Explicit programme commitment |
| Military end-use monitoring | Major component | More fragmented by Member State / mechanism | Not principal function | None |
| Payment reduction / recovery | Programme-specific | Explicit Facility recovery powers | Ineligible expenditure recovery | Tranche non-completion / waiver framework |
| Main 2026 weakness visible in record | Follow-up and fraud-risk integration | Effectiveness of downstream implementation | High residual wartime risk | Reform slippage / reset benchmarks |
The table shows that no system is categorically “stronger” in every dimension. They are designed to solve different accountability problems.
Conditionality enforcement: completed, delayed, reset and waived are four different statuses
A recurring analytical error is to divide reform conditions into only “met” or “ignored”.
The 2026 record requires at least four categories.
| Status | Meaning | 2026 example |
|---|---|---|
| Completed | Requirement fulfilled | Ten steps supporting eighth Ukraine Facility payment |
| Delayed but completed | Condition eventually implemented | IMF supervisory-board nomination reforms implemented after deadline |
| Reset | Requirement preserved but deadline formally changed | NACP asset-verification benchmark moved toward end-Sept. 2026 |
| Waived | Non-observance accepted under programme rules | IMF supported specific performance-criterion waivers while maintaining programme |
| Outstanding / payment-adjusting | Unfulfilled requirement affects payment calculation | Ukraine Facility payment mechanics |
| Abandoned | Requirement no longer operative | Not equivalent to reset or waiver |
The IMF explicitly supported waivers associated with specified programme criteria while also requiring corrective actions and preserving structural objectives. IMF — programme waivers, structural benchmark resets and corrective measures eLibrary IMF
This is an important safeguard against misleading claims that every waiver means conditionality has disappeared.
Forward-control options for parliamentary and donor oversight
The following measures address specific weaknesses identified in the official record; they are presented as control-design options, with their operational effects and trade-offs rather than as political endorsements.
Transaction-level traceability standard
A common traceability schema could assign each externally financed budget-support or Ukrainian-procurement transaction a persistent identifier connecting:
donor instrument → disbursement → Ukrainian budget programme → implementing body → procurement contract → beneficial owner → payment → delivery / beneficiary sample → audit finding → recovery status.
The evidence supporting such a design is strong because GAO has already demonstrated that expenditure data exist but were not always fully exploited, while the Ukraine Facility Regulation separately requires anti-fraud information, audit access and prevention of double financing. GAO — direct-budget-support data gaps EU Ukraine Facility Regulation — control and anti-double-funding obligations GAO
Expected effect: better ability to trace irregular contracts back to financing origin.
Implementation burden: high, because donor and Ukrainian accounting systems use different identifiers and disclosure rules.
Principal downside: excessive transparency for sensitive defence procurement unless classified access rules are built into the system.
Donor–NABU/SAPO restricted-information protocol
A second option would allow authorised donor-integrity units to receive restricted risk flags where a contractor, beneficial owner, public official or procurement body financed through a donor programme becomes implicated in a live NABU/SAPO proceeding.
The protocol would not need to disclose investigative evidence. It could communicate only:
- entity under investigation;
- conflict / corruption category;
- whether continued payment creates evidentiary or asset-recovery risk;
- whether suspension would compromise the investigation;
- reassessment date.
Expected effect: prevents new donor financing from unintentionally expanding exposure to an already-identified high-risk counterparty.
Implementation burden: substantial legal and confidentiality safeguards.
Principal downside: premature disclosure could jeopardise investigations or unfairly penalise entities not yet convicted.
Defence Procurement Agency contract-performance register
The weakness identified in defence procurement is not merely tender transparency but post-award performance opacity.
A donor-accessible DPA register could disclose, subject to security restrictions:
| Field | Oversight purpose |
|---|---|
| Contract value | Establish denominator |
| Amount prepaid | Measure state exposure |
| Value delivered | Compare money to output |
| Delivery deadline | Identify lateness |
| Amount overdue | Quantify non-performance |
| Previous defaults | Supplier-risk history |
| Penalty imposed | Contract enforcement |
| Penalty recovered | Actual financial restitution |
| Litigation / arbitration | Recovery status |
| Beneficial owner | Conflict screening |
| Funding source | Donor attribution |
| Classification status | Protect operational information |
This design would answer the central unresolved problem left by the 2024–26 defence-procurement debate: distinguishing money stolen, money overpaid, money tied up in receivables, money attached to defective goods and money merely delayed.
Emergency-waiver recertification
Instead of assuming that a wartime waiver remains valid indefinitely, emergency procurement could operate under a periodic recertification model.
A recertification record would state:
why normal competition remains impossible → whether more suppliers have become available → whether direct contracting remains necessary → benchmark used to establish price reasonableness → duration of renewed waiver.
Expected effect: preserves operational speed while creating retrospective auditability.
Principal downside: additional paperwork can slow genuinely urgent procurement if the threshold is too low.
Independent reconstruction of defence-procurement losses
The reported $1.2 billion 2024 defence-procurement figure should not become a policy metric until its components can be reconciled.
A technically valid reconstruction would separate at least:
| Category | Treatment |
|---|---|
| Criminally suspected embezzlement | Potential criminal loss |
| Bribery | Criminal offence; value distinct from contract loss |
| Price premium | Possible overpayment |
| Non-delivery | Receivable until proven irrecoverable |
| Defective delivery | Requires impairment valuation |
| Late delivery | Operational loss; financial loss may differ |
| Unenforced penalty | Potential recoverable amount |
| Contract dispute | Not automatically corruption |
| Administrative irregularity | Control failure |
| Accounting misclassification | Not necessarily economic loss |
The result would allow donor institutions to evaluate whether procurement losses are concentrated in criminal conduct, supplier failure, weak contract enforcement or emergency-market conditions.
The control objective for 2027
The external-financing system has now reached a scale at which separate oversight silos are no longer sufficient.
The next control frontier is not the creation of another general oversight institution. It is the creation of interoperable evidence between institutions that already exist.
The minimum viable chain is:
appropriation → disbursement → Ukrainian budget or procurement identifier → contractor beneficial owner → payment → physical or social output → audit result → investigative flag → judicial status → recovery.
No existing public system consistently provides that entire chain across U.S., EU, IFI and Ukrainian sources.
The consequence is that donor governments can often establish that their money was transferred according to programme rules while Ukrainian authorities can establish that a contractor is suspected of corruption, yet the public record still cannot always determine whether those two propositions concern the same money.
That attribution gap is the central unresolved accountability problem.
Pillar III key judgments
The first judgment is that Ukraine assistance is subject to multiple enforceable accountability systems rather than an absence of oversight. The U.S. system combines GAO, OIGs, congressional reporting and end-use controls; the EU combines legally conditioned payments, an independent Audit Board, OLAF and recovery provisions; the World Bank applies expenditure eligibility and independent audit; and the IMF uses programme conditions and structural benchmarks. State OIG — Ukraine oversight architecture EU — Ukraine Facility Regulation World Bank — PEACE safeguards IMF — Ukraine EFF governance conditionality stateoig.gov
The second judgment is that U.S. direct-budget-support oversight remains incomplete despite its layered architecture. GAO had five open recommendations concerning expenditure anomalies, congressional reporting, risk prioritisation and remediation as of the 2026 follow-up period, and fraud-risk management remained a priority issue in September 2026. GAO — DBS oversight and open recommendations GAO — September 2026 State priority recommendations GAO
The third judgment is that EU conditionality has demonstrated actual financial relevance. Payments are tied to defined Ukraine Plan steps, incomplete reforms can affect payment calculations, and the Facility contains explicit recovery and anti-fraud provisions rather than relying solely on political commitments. Council — Ukraine Facility payment conditions Consiglio dell’Unione Europea
The fourth judgment is that IMF conditionality has been enforced flexibly rather than abandoned. Missed structural benchmarks were reset or reformulated with corrective measures while programme financing continued after Board review; that is distinct from either strict automatic suspension or unconditional disbursement. IMF — July 2026 structural benchmark review eLibrary IMF
The fifth judgment is that financing based on immobilised Russian assets requires an additional accounting layer. Accountability must distinguish the immobilised principal, generated extraordinary revenues, loan-servicing mechanics and Ukrainian use of proceeds. European Commission — ERA loan framework Economy and Finance
The sixth judgment is that emergency procurement should be assessed through auditability rather than through a false choice between speed and control. Targeted derogations are already recognised in EU defence-financing rules; the unresolved issue is whether each exception produces a durable record capable of later supplier, pricing and delivery review. Council — defence procurement under the Ukraine Support Loan Consiglio dell’Unione Europea
The seventh judgment is that disinformation now represents an oversight risk in its own right. The fabricated September 2026 $140 million refrigerator-box story demonstrates that realistic AI-generated evidence and cloned-media presentation can create a false corruption event capable of contaminating legitimate donor scrutiny; institutional confirmation must therefore precede amplification. Ukraine Center for Countering Disinformation — 25 September 2026 debunk cpd.gov.ua
The final judgment is that the major residual weakness is attribution. Existing systems are increasingly capable of identifying programme-level irregularities and Ukrainian criminal cases, but they do not yet provide a universal, transaction-level chain connecting every donor euro or dollar to the Ukrainian contract, beneficial owner, delivered output, audit finding and judicial outcome. Closing that gap would materially increase the evidentiary value of both donor oversight and Ukrainian anti-corruption enforcement.
Conditionality, Oversight & Forward Controls
Comparative accountability architecture covering the United States, European Union, World Bank and IMF, with emphasis on enforceable conditions, audit closure, emergency-procurement safeguards, Russian-asset-derived financing and transaction-level traceability.
Oversight Architecture by Institution
| Institution | Primary control mechanism | What it can establish | What it cannot establish alone | 2026 control status |
|---|---|---|---|---|
| U.S. GAO | Independent congressional audit | Control weaknesses, anomalies, programme-management failures | Criminal guilt | OPEN RECOMMENDATIONS |
| State / DoD / USAID OIGs | Agency inspector-general oversight | Programme compliance, fraud risk, contracting, end-use weaknesses | Full Ukrainian criminal adjudication | ACTIVE |
| European Commission | Ukraine Facility milestone verification | Whether payment conditions were met | Every downstream procurement irregularity | PAYMENT-LINKED |
| Ukraine Facility Audit Board | Independent system and audit review | Fraud, corruption, conflict-of-interest and management concerns | Final criminal liability | ACTIVE THROUGH 2028 |
| World Bank | Eligibility review and reimbursement verification | Whether expenditure qualifies for financing | Every later procurement or criminal issue | MULTI-LAYERED |
| IMF | Quantitative and structural conditionality | Macroeconomic and reform compliance | Invoice-level procurement integrity | CORRECTIVE ACTION / RESETS |
| NABU / SAPO / HACC | Investigation, prosecution, adjudication | High-level corruption and criminal liability | Full donor appropriation history | DOMESTIC ENFORCEMENT |
Target End-to-End Accountability Chain
United States: Direct Budget Support Control Stack
| Control layer | Principal function | Documented strength | Documented limitation |
|---|---|---|---|
| Ukraine Ministry of Finance | Collects and validates eligible expenditure data | Centralised reporting architecture | Relies on underlying spending-agency data |
| World Bank | Determines eligibility before reimbursement | Ex ante verification | Does not replace donor fraud analytics |
| PwC reviews | Control-system assessment | Identified internal weaknesses | Requires documented remediation |
| Deloitte monitoring | Reviews Ukrainian control environment | Produced 56 recommendations cited by GAO | Risk prioritisation judged insufficient |
| GAO | Independent congressional audit | Identified unusual expenditure patterns | Cannot prosecute misconduct |
| State Department | Post-July 2025 programme oversight | Continues World Bank coordination | Five GAO recommendations remained open in 2026 follow-up |
GAO Anomaly Detection
Source: U.S. GAO — State Should Build on USAID’s Oversight of Direct Budget Support .
Open U.S. Oversight Issues
Source: U.S. GAO — Priority Open Recommendations: Department of State, September 2026 .
European Union: Conditionality Embedded in Payment Mechanics
| Control component | Mechanism | Possible financial consequence |
|---|---|---|
| Ukraine Plan milestones | Quarterly qualitative and quantitative reform steps | Payment can be reduced, delayed or deferred |
| Commission assessment | Technical verification before regular payment | Determines amount eligible for release |
| Council implementing decision | Member-state approval | Final political/legal authorisation of payment |
| Ukraine Facility Audit Board | Independent audit and system assessment | Recommendations, escalation to Commission and OLAF |
| OLAF / EPPO | Anti-fraud and criminal investigation where competent | Recovery, administrative measures or prosecution |
| Recovery clauses | EU financial-interest protection rules | Reduction, repayment or clawback |
Ukraine Facility — 2026 Payment Performance
Source: Council of the EU — Eighth Ukraine Facility payment .
Ukraine Facility Audit Board
Independent of the Ukrainian government, mandated through 30 June 2028, and empowered to report serious management concerns to the Commission, recommend corrective action and transmit relevant information to OLAF.
Source: European Commission — Decision establishing the Ukraine Facility Audit Board .
Conditionality Status: Do Not Collapse These Categories
| Status | Meaning | 2026 example |
|---|---|---|
| COMPLETED | Requirement fulfilled | Ukraine Facility steps supporting regular payments |
| DELAYED | Condition fulfilled after original deadline | Selected IMF governance reforms |
| RESET | Requirement remains operative but deadline formally changes | NACP risk-based asset-verification benchmark |
| WAIVED | Non-observance accepted under formal programme rules | Specified IMF performance criteria |
| OUTSTANDING | Unfulfilled requirement affects current or future payment | Incomplete Ukraine Facility steps |
Why this distinction matters
A reset is not the same as abandonment, and a waiver is not the same as unconditionality. Programme credibility depends on whether missed conditions remain visible, corrective actions are imposed, deadlines are documented and final completion is subsequently verified.
World Bank PEACE Safeguard Stack
| Control | Operator | Main function | Failure targeted |
|---|---|---|---|
| Expenditure validation | Ukraine Ministry of Finance | Confirms expenditure data before submission | Ineligible public expenditure |
| Eligibility review | World Bank | Determines whether reimbursement conditions are met | Non-compliant reimbursement |
| Independent annual audit | External auditor | Financial-statement assurance | Material misstatement |
| Agreed-Upon Procedures | Independent audit firm | Tests specific control operation | Control failure |
| Digital beneficiary verification | Ukraine / World Bank systems | Verifies eligible recipients | Ghost or duplicate beneficiaries |
| Listening to Ukraine survey | World Bank | Tests delivery of supported public services | Payment without service output |
| INT referral | World Bank Integrity Vice Presidency | Fraud and corruption investigation | Sanctionable misconduct |
PEACE risk interpretation
The programme can simultaneously have extensive safeguards and remain a high-risk operation because security, macroeconomic, political and implementation conditions remain adverse. Strong control architecture does not mean zero residual risk.
Immobilised Russian Assets: Four Separate Ledgers
| Ledger | Core audit question |
|---|---|
| Immobilised principal | What Russian sovereign assets remain immobilised, in which jurisdiction and under which custodian? |
| Extraordinary revenue | How much interest or extraordinary profit has been generated, over what period and under what accounting rule? |
| Loan servicing | Which ERA obligations are serviced by those revenues and on what schedule? |
| Ukrainian expenditure | Where did the corresponding financing ultimately enter the Ukrainian budget or procurement system? |
EU ERA Participation
Sources: European Commission — Ukraine / ERA financing ; Council of the EU — Russia’s war against Ukraine .
Why ERA Requires Dual Accountability
ERA oversight must verify not only the Ukrainian use of funds but also the generation, calculation, custody and allocation of extraordinary revenues derived from immobilised Russian sovereign assets.
Emergency Procurement: Minimum Controls That Should Survive Wartime
| Control | Why it remains necessary |
|---|---|
| Written emergency justification | Documents why ordinary competition was not practicable |
| Beneficial-owner identification | Detects conflicts, related parties and hidden supplier control |
| Price benchmark | Creates later evidence of reasonableness |
| Advance-payment ceiling | Limits state exposure before delivery |
| Delivery / acceptance record | Links expenditure to physical output |
| Time-limited waiver | Prevents emergency status becoming permanent |
Control standard for derogations
Emergency flexibility should create more retrospective documentation, not less. Each derogation should record why normal competition was impossible, how the price was benchmarked, which supplier universe was considered and when the waiver must be recertified.
Counter-Disinformation Verification Chain
September 2026 Fake Raid Narrative
The claim that NABU searched premises linked to former DPA head Arsen Zhumadilov and recovered approximately $140 million in refrigerator boxes was publicly identified as false, with Ukrainian authorities stating that the purported video was AI-generated and that no corresponding NABU procedural action had taken place.
Why It Matters for Donor Oversight
Fabricated corruption spectacles exploit genuine concern over public-sector integrity and can influence parliamentary, media and donor debate before formal verification occurs. The control response is not weaker scrutiny, but stricter source authentication.
Forward Control Package
| Control option | Expected effect | Implementation burden | Principal downside |
|---|---|---|---|
| Transaction-level traceability standard | Connect donor instrument to contract, owner, payment and end use | High | Potential exposure of sensitive defence information |
| Donor–NABU/SAPO restricted protocol | Warn donors when a funded counterparty enters a live high-risk investigation | High legal/confidentiality burden | Risk to investigations and presumption of innocence |
| DPA contract-performance register | Distinguishes paid, delivered, overdue and recoverable amounts | Medium–high | Security classification constraints |
| Emergency-waiver recertification | Prevents emergency exceptions becoming permanent | Medium | Potential slowing of urgent procurement |
| Independent reconstruction of defence losses | Separates theft, overpricing, non-delivery, defects and recoverable receivables | High forensic burden | Requires access to classified and non-public records |
Defence Procurement Performance Register — Minimum Fields
| Field | Why it matters |
|---|---|
| Contract value | Establishes financial denominator |
| Advance paid | Measures public exposure before delivery |
| Value delivered | Links financial outlay to physical military output |
| Delivery deadline | Identifies performance failure |
| Amount overdue | Quantifies non-performance |
| Previous supplier defaults | Provides institutional memory |
| Penalty imposed | Tests enforcement |
| Penalty recovered | Separates nominal enforcement from actual restitution |
| Beneficial owner | Supports conflict and related-party screening |
| Funding source | Permits real donor-fund attribution |
Decision-relevant conclusion
The principal residual weakness is attribution, not absence of oversight. Donor institutions can often establish that funds were legally authorised and properly disbursed, while Ukrainian authorities can establish that a contractor or official is under investigation, yet the public record may still be unable to show whether those two facts concern the same transaction. The strongest forward control is therefore not simply another audit body, but a shared evidentiary chain from appropriation to recovery.
U.S. direct budget support: U.S. GAO — State Should Build on USAID’s Oversight of Direct Budget Support .
U.S. priority recommendations: U.S. GAO — Priority Open Recommendations: Department of State .
State Department Ukraine oversight: U.S. Department of State OIG — Ukraine-Related Oversight .
Operation Atlantic Resolve quarterly oversight: State OIG — Special Inspector General for Operation Atlantic Resolve, Q2 2026 .
U.S. enhanced end-use monitoring: DoD OIG — Follow-up Evaluation of Enhanced End-Use Monitoring .
U.S. PDA valuation: U.S. GAO — Ukraine Assistance: Actions Needed to Properly Value Defense Articles .
Ukraine Facility: Council of the EU — The Ukraine Facility .
Ukraine Facility Regulation: EUR-Lex — Regulation establishing the Ukraine Facility .
Ukraine Facility Audit Board: European Commission — Decision establishing the Ukraine Facility Audit Board .
Eighth Ukraine Facility payment: Council of the EU — Eighth regular payment .
IMF programme review: IMF — First Review of Ukraine’s EFF .
IMF structural reform detail: IMF — Ukraine 2026 Article IV Consultation and First EFF Review .
World Bank PEACE safeguards: World Bank — PEACE Project Factsheet .
ERA financing: European Commission — Ukraine / ERA financing .
EU support totals and Russian-asset proceeds: Council of the EU — Russia’s war against Ukraine .
Counter-disinformation verification: Ukraine Center for Countering Disinformation .