



Scope: This assessment examines the United States federal power-sector greenhouse-gas rollback announced and signed on 14 September 2026, its interaction with emissions measurement, carbon-related taxation and incentives, electricity economics, future regulatory authority, and the resulting implications for the European Union, Italy, France, Germany and the United Kingdom over a five-year decision horizon.
Executive Summary / BLUF
The central finding is that the Trump administration has not abolished carbon accounting, carbon taxation or every federal greenhouse-gas obligation in the United States in a single legal act, but it has substantially dismantled one of the principal federal mechanisms through which CO₂ emissions from fossil-fuelled electricity generation were intended to be constrained, while simultaneously advancing a broader regulatory strategy that could remove most of the remaining federal EPA architecture for controlling greenhouse-gas emissions under the Clean Air Act.
On 14 September 2026, EPA Administrator Lee Zeldin signed a final rule repealing most of the 2024 Carbon Pollution Standards, specifically including the emission guidelines for existing fossil-fuel steam-generating units and the carbon-capture-and-storage-based requirements applicable to certain coal and new baseload gas units. At the same time, EPA issued a separate supplemental proposal, rather than a final rule, seeking to rescind the remaining greenhouse-gas findings and standards for fossil-fuelled power plants under Clean Air Act §111. The distinction is legally decisive: the majority rollback is final agency action, subject to Federal Register publication, effective-date requirements and judicial review, whereas complete elimination of the remaining power-sector GHG standards remains under rulemaking. Greenhouse Gas Standards and Guidelines for Fossil Fuel-Fired Power Plants — U.S. Environmental Protection Agency — Sep 2026
The EPA’s own regulatory modelling shows the scale of the environmental consequence relative to the regulatory baseline: the final partial repeal is projected to increase annual power-sector CO₂ emissions by 20 million metric tonnes in 2030, 406 million tonnes in 2035, 533 million tonnes in 2040 and 486 million tonnes in 2045, compared with the scenario in which the 2024 standards remained operative; importantly, EPA chose not to monetize the climate consequences of those additional CO₂ emissions in the final regulatory impact analysis. Regulatory Impact Analysis for the Final Partial Repeal of the Carbon Pollution Standards for Fossil Fuel-Fired Electric Generating Units — U.S. EPA — Sep 2026
The rollback does not automatically extinguish the physical measurement of power-sector CO₂ emissions, because greenhouse-gas emissions measurement and emission-control obligations arise under different regulatory structures; EPA’s Greenhouse Gas Reporting Program under 40 CFR Part 98, including Subpart D for power plants, currently retains reporting and calculation architecture, although the administration separately proposed in September 2025 to eliminate reporting requirements for 46 source categories, and EPA has extended the reporting-year-2025 deadline to 30 October 2026 while that reconsideration remains unresolved. Greenhouse Gas Reporting Program — U.S. Environmental Protection Agency — Jul 2026
Nor does the decision repeal a US federal carbon tax, because no economy-wide federal carbon tax comparable to the EU ETS exists in the United States; significant carbon-price mechanisms instead survive at state level, most prominently California’s Cap-and-Invest system, while federal fiscal instruments such as the Internal Revenue Code §45Q carbon-oxide sequestration credit also remain in force. Cap-and-Invest Program — California Air Resources Board — 2026 Credit for Carbon Oxide Sequestration — Internal Revenue Service — 2026
For Europe, the most consequential external effect is therefore not the disappearance of carbon accounting but an increase in the regulatory and carbon-price divergence between the United States and Europe, because the EU ETS continues to price emissions while the EU Carbon Border Adjustment Mechanism entered its definitive phase on 1 January 2026, requiring covered imports to bear a carbon cost linked to EU ETS allowance prices and allowing deductions only for carbon prices actually paid in the country of origin. CBAM Definitive Regime — European Commission — 2026
The implication is consequently not that the global carbon-pricing architecture collapses, but that two major economic blocs are moving further apart in the regulatory treatment of carbon, thereby increasing the strategic importance of emissions verification, border-carbon adjustments, product-level carbon intensity, corporate decarbonisation commitments, state-level US policy and the relative energy cost of American versus European industrial production.
What the Trump power-sector rollback actually means for the United States and Europe
Principal judgment
The clearest way to understand the September 2026 decision is to separate what becomes cheaper inside the United States from what becomes more expensive or strategically more difficult for Europe, because the policy does not produce a single global effect and it does not simply divide the world into a deregulated America and a regulated Europe. In the United States, the principal consequence is that coal- and gas-fired power generation can operate and invest under materially weaker federal greenhouse-gas constraints, which reduces the amount of capital that utilities would otherwise have had to devote to carbon capture, fuel switching, accelerated plant retirement and replacement generation; in Europe, by contrast, the principal consequence is not a direct regulatory change but a widening of the competitiveness gap between industrial production subject to explicit carbon pricing and American production that can increasingly benefit from cheaper fossil-based electricity without bearing an equivalent federal carbon price. EPA Finalizes Repeal of 2024 Power Plant Regulations — U.S. EPA — Sep 2026
For the United States, the short- and medium-term beneficiaries are therefore primarily owners of existing fossil-fuel generating assets, coal producers, parts of the electricity-intensive industrial base and consumers located in regions where avoided capital expenditure eventually translates into lower rates, while the principal economic losers relative to the previous regulatory baseline are CCS developers, CO₂ transport and storage projects, some renewable and storage developers, and industries whose competitive proposition depended on rapid decarbonisation of the US electricity system. EPA estimates approximately $310 billion in broad deregulatory savings, but that number should not be read as $310 billion appearing directly on household electricity bills, because its own underlying modelling distributes the gains over more than two decades and across different classes of investment, fuel expenditure, tax credits and avoided compliance costs. EPA Finalizes Repeal of 2024 Power Plant Regulations — U.S. EPA — Sep 2026
For Europe, the immediate effect is almost the reverse: European electricity and industrial regulation does not become weaker because Washington changes course, while the EU ETS and CBAM continue to impose a carbon-price architecture on domestic producers and covered imports; consequently, European companies increasingly compete against American producers whose domestic energy system may carry a lower prospective regulatory cost, while Europe progressively withdraws part of the free allowance protection historically granted to energy-intensive sectors. Under the revised EU ETS Directive, the CBAM-linked free-allocation factor falls from 97.5% in 2026 to 51.5% in 2030 and to zero from 2034, meaning that the economic importance of the transatlantic regulatory divergence grows with time rather than being fully visible in 2026. Directive (EU) 2023/959 — European Union
The central strategic conclusion is consequently straightforward: the United States is lowering one component of the cost of retaining dispatchable fossil generation precisely while Europe is increasing the role of carbon pricing in industrial competition, and this divergence can redirect production, investment and trade even if CBAM successfully prevents the most carbon-intensive imports from entering Europe without an equivalent carbon cost.
What changes inside the United States
The most important American effect is that utilities no longer face the same federal economic incentive to retire existing coal units or equip qualifying long-lived fossil generation with carbon capture, which changes the value of assets that have already been built and largely depreciated. Existing coal plants are particularly important because their original construction cost is largely sunk; once a plant is operating, the decision to keep it open depends primarily on fuel, maintenance, environmental compliance, labour and incremental capital requirements, so removing a future obligation to install expensive CCS equipment or accelerate retirement can substantially improve the economics of keeping that asset operating.
This is why the decision is more consequential for existing generating capacity than for the construction of an entirely new coal fleet. The United States generated approximately 4.43 trillion kWh of utility-scale electricity in 2025, of which natural gas supplied about 41%, coal around 17%, nuclear around 18% and renewables approximately 24%, meaning that fossil fuels still accounted for about 58% of total utility-scale generation immediately before the September 2026 repeal. Electricity in the United States — U.S. Energy Information Administration — 2026
The decision therefore operates on a system that is still heavily fossil-based rather than on a residual technology at the edge of the market. In 2025, the electric-power sector emitted approximately 1.485 billion metric tonnes of CO₂, including around 750 million tonnes from coal generation and 712 million tonnes from natural gas, while total US energy-related emissions reached approximately 4.904 billion tonnes. What Are U.S. Energy-Related Carbon Dioxide Emissions by Source and Sector? — U.S. Energy Information Administration — 2026
The effect is therefore not marginal. By weakening the regulatory pressure on the part of the electricity system responsible for nearly one-third of total US energy-related CO₂ emissions, the decision changes the expected operating life and utilisation of a very large asset base.
The American economic effect is not immediate cheap electricity, but cheaper future system transformation
The most important misunderstanding to avoid is the idea that repealing the rule means American households suddenly receive dramatically cheaper electricity in 2026. EPA’s own modelling does not show that pattern, because the largest savings appear only when the 2024 standards would otherwise have required large-scale investment in CCS, plant conversion, retirement and replacement capacity during the 2030s.
The economic mechanism is therefore better understood as avoided future investment. If a utility does not have to install carbon-capture systems on a coal unit, does not have to retire that unit early, and does not have to replace the lost generation immediately with a combination of gas turbines, solar, wind, storage and transmission, its system-wide capital requirement falls relative to the previous regulatory baseline. That avoided expenditure can eventually appear in lower electricity rates, but only after utility accounting, financing, regulatory approval and regional market structures transmit the saving to consumers.
This timing matters particularly because US electricity demand is increasing. EIA reports that electric-power generation increased by 3% in 2025, while power-sector CO₂ emissions rose by 4%, partly because electricity demand grew from data centres and manufacturing and because coal generation increased by 13%, or approximately 85 TWh. U.S. Energy-Related Carbon Dioxide Emissions, 2025 — U.S. Energy Information Administration — Jul 2026
The regulatory rollback therefore arrives at a moment when the United States needs additional electricity rather than at a moment of falling demand, which increases the economic value of keeping existing generating assets online because the system must simultaneously serve new demand and replace retiring capacity.
The United States gains flexibility, but sacrifices part of the decarbonisation trajectory
From the perspective of power-system economics, the repeal gives utilities more freedom to choose between keeping an existing coal plant operating, building new gas capacity, investing in renewables and storage, or developing CCS projects. From the perspective of emissions, the same flexibility means a slower transition away from unabated fossil generation.
The two effects cannot be separated because the source of much of the projected economic saving is precisely the ability to continue using infrastructure that emits more CO₂ than the technologies that would otherwise replace it. EIA’s 2025 data illustrate the underlying physics: coal produced considerably less electricity than natural gas but still generated approximately 750 million tonnes of CO₂, slightly more than the 712 million tonnes emitted by natural-gas generation, because coal produces more CO₂ per unit of electricity generated. What Are U.S. Energy-Related Carbon Dioxide Emissions by Source and Sector? — EIA — 2026
The September decision consequently exchanges part of the previously planned emissions reduction for greater discretion over fuel choice, plant retirement and investment timing.
The effect on American industry is broader than the electricity sector
Industrial competitiveness can benefit through several channels, because electricity and natural gas are important cost inputs for data centres, chemicals, steel, aluminium, semiconductor fabrication, cement, food processing, manufacturing and large-scale computing infrastructure.
The most direct gain occurs in regions where avoided fossil-plant retirement reduces the need for costly replacement generation, but the second channel operates through natural gas: if retaining coal reduces gas demand from the power sector during certain years, gas prices can also remain lower than they would have been under a faster coal-to-gas transition, benefiting manufacturers that use gas as both fuel and feedstock.
The effect is therefore not that every American manufacturer automatically becomes more competitive, but that the energy-cost floor against which investment decisions are made can fall in particular regions, especially those with existing fossil generation, available gas, large industrial loads and growing electricity demand.
This helps explain why the policy can matter for industrial investment even when the final manufactured product itself is not carbon-intensive. Semiconductor factories, AI data centres and advanced manufacturing plants may have relatively low direct CO₂ emissions but enormous electricity demand, so they benefit economically if regional power systems can satisfy new load without financing a faster replacement of existing generation.
What changes in Europe
Europe does not experience a corresponding relaxation. The EU ETS continues to require covered installations to account for emissions, while CBAM has entered its definitive phase and progressively replaces free allocation as the principal carbon-leakage protection for covered sectors. The result is that a European industrial producer can face an explicit carbon cost at home while competing against an American producer whose electricity supplier increasingly faces weaker federal climate constraints.
This is why the European effect is principally relative rather than absolute. The September EPA decision does not directly increase the EU ETS price, does not increase European gas prices and does not change European electricity regulations; what it changes is the comparative cost environment against which European industry competes.
The distinction matters because competitiveness is determined by relative costs. If a German plant continues paying European carbon and electricity costs while a comparable American plant’s power supplier avoids large future CCS and retirement expenditure, the American producer’s relative position can improve even if its own nominal electricity price remains unchanged.
CBAM protects Europe against one part of the problem, but not against all of it
CBAM is intended to prevent an imported tonne of steel, aluminium, cement, fertiliser or hydrogen from receiving an unfair advantage merely because it was produced in a jurisdiction with no equivalent carbon price. The EU importer must account for embedded emissions and surrender CBAM certificates linked to the EU ETS carbon price, subject to deduction for a carbon price actually paid abroad. CBAM Definitive Regime — European Commission — 2026
That mechanism is powerful, but it does not make European and American production costs identical because it adjusts primarily for carbon-price differences, not for every regulatory and energy-cost difference.
An American steel producer could, for example, receive cheaper electricity because its regional grid avoids expensive federal carbon-compliance investments, while CBAM subsequently adds a charge corresponding to the embedded carbon of the imported steel. The border adjustment can correct part of the carbon-price advantage, but the original electricity-cost advantage can remain.
The distinction can be expressed simply:
CBAM can approximate the missing carbon price; it cannot reproduce the entire European cost structure.
Europe also faces a timing problem because free allocation declines faster after 2028
The European competitiveness problem becomes substantially more serious after 2028 because the free-allocation reduction accelerates sharply. The CBAM factor remains 97.5% in 2026, 95% in 2027 and 90% in 2028, but falls to 77.5% in 2029 and only 51.5% in 2030, before declining further to 39% in 2031, 26.5% in 2032 and 14% in 2033. Directive (EU) 2023/959 — European Union
This means that the European industrial system does not experience the full transatlantic pressure immediately in 2026. The critical period is closer to 2029–2031, when European producers lose a much larger share of free allowances while US fossil electricity remains less constrained if the Trump regulatory architecture survives judicial and political challenge.
The effect on Europe therefore depends heavily on the electricity system of each country
France is structurally best positioned because its power system is dominated by nuclear and other low-carbon generation, which reduces the carbon component embedded in industrial electricity.
Germany is more exposed because coal and gas still represent a substantial share of electricity generation. Destatis reports that in 2025 Germany generated 438.2 TWh for grid injection, of which renewables accounted for 58.6%, coal 22.1% and gas 16.1%, meaning that approximately 38.2% of generation still came from those two fossil sources. Stromerzeugung aus Photovoltaik und Erdgas erreicht 2025 neue Höchstwerte — Statistisches Bundesamt — Mar 2026
Italy has very little remaining coal generation, but its vulnerability comes from gas-based thermoelectric production and electricity imports. Terna reports electricity demand of 311.3 TWh in 2025, with renewable sources covering approximately 41% of demand and photovoltaic production reaching a record 44.3 TWh, while the system remained dependent on substantial thermoelectric production and cross-border flows. Electricity Demand of 311.3 TWh in 2025 — Terna — Jan 2026
The United Kingdom operates separately from the EU but faces the same fundamental competitiveness problem because the UK ETS continues to cover power and heavy industry and the British CBAM enters into force on 1 January 2027 for aluminium, cement, fertiliser, hydrogen, iron and steel. UK Emissions Trading Scheme: Policy Overview — UK Government — Sep 2026 Carbon Border Adjustment Mechanism: Policy Summary — HMRC — Sep 2026
What this means in practical terms
For an American coal-heavy electricity region, the rollback can mean that existing plants run longer, fewer replacement assets need to be financed immediately and electricity prices can eventually be lower than under the previous regulatory trajectory.
For an American gas-heavy region, the result is more mixed because gas plants benefit from removal of future CCS requirements, but retained coal can also compete against gas and suppress some of the additional gas demand that would otherwise have emerged.
For an American industrial producer, the main benefit is cheaper or more abundant electricity and potentially lower gas costs in certain regions, rather than a direct cash payment from deregulation.
For a European industrial producer, nothing comparable happens automatically because EU carbon pricing remains in place, meaning that the relative cost gap can widen.
For a European importer, CBAM partially corrects the difference when the imported good belongs to a covered sector, but it does not cover every industrial product and does not neutralise every energy-cost difference.
For European governments, the strategic question therefore becomes whether they can reduce the non-carbon component of industrial energy costs quickly enough that the carbon policy remains economically sustainable.
Comprehensive United States–Europe comparison
| Dimension | United States after Sep 2026 rollback | European Union | United Kingdom | Net strategic consequence |
|---|---|---|---|---|
| Power-sector federal carbon constraint | Major 2024 requirements repealed; remaining standards separately targeted | Power sector remains inside EU ETS | Power remains under UK ETS | US fossil generation faces lower climate-related regulatory cost |
| Economy-wide carbon price | No federal economy-wide carbon tax or ETS | EU ETS creates explicit allowance price | UK ETS creates explicit allowance price | Europe retains explicit carbon-cost exposure absent at US federal level |
| Coal-generation economics | Existing coal becomes more economically durable relative to prior baseline | Coal generation continues to face ETS carbon cost | Coal nearly eliminated from GB power mix | US coal assets gain relative value |
| Gas-generation economics | Federal CCS requirement weakened/repealed for affected plants | Gas power pays EU ETS carbon cost | Gas generation pays UK ETS carbon cost | US gas generation can face lower regulatory cost |
| Electricity demand | Rapid growth from data centres, manufacturing and electrification | More moderate and uneven growth | Moderate growth, electrification pressure | US repeal occurs during unusually strong load growth |
| Electricity-system investment | Less forced replacement of existing fossil capacity | Continued investment in renewables, grids and low-carbon technologies | Continued clean-power build-out | US can defer part of capital replacement cycle |
| CCS | Becomes more optional and §45Q-dependent | Important for hard-to-abate sectors; ETS preserves carbon incentive | Supported within industrial decarbonisation strategy | US CCS market loses part of regulatory demand |
| Carbon capture subsidy | §45Q remains | EU/national funding and ETS incentive | UK subsidy and ETS mechanisms | US retains incentives without equivalent mandate |
| Renewable investment | EPA modelling implies lower additions relative to former CPS baseline | Remains central to policy framework | Remains central | Relative US renewable build requirement falls |
| Carbon accounting | Federal architecture remains but is under separate reconsideration | Mandatory ETS/CBAM measurement expanding | ETS/CBAM measurement expanding | Potential US–Europe data divergence increases |
| Industrial carbon cost | No equivalent federal ETS charge | Material for covered industry | Material for covered industry | US firms can have lower direct carbon cost |
| Border-carbon adjustment | None at federal import level comparable to EU CBAM | CBAM definitive phase from 2026 | CBAM from 2027 | Europe shifts part of carbon cost to imports |
| Recognition of foreign carbon price | Not relevant to US federal power rule | Deduction where qualifying carbon price paid abroad | Similar principle under UK CBAM | US exporters with no carbon payment receive limited deduction |
| Free allowance protection | Not applicable federally | Falls sharply through 2034 | Being adjusted with UK CBAM | European producers progressively internalise more carbon cost |
| Industrial electricity competitiveness | Potentially improves in fossil-rich regions | Highly country-specific | Intermediate position | US advantage strongest against high-cost European systems |
| Carbon intensity of electricity | Highly regional; national generation still about 58% fossil in 2025 | Varies greatly by member state | Falling rapidly | France has much stronger position than Germany/Italy |
| Coal share / fossil role | Coal 17%, gas 41% of utility-scale generation in 2025 | Large variation across EU | Coal largely exited; gas remains | US policy affects a large active fossil fleet |
| Power-sector CO₂ baseline | ~1.485 Gt CO₂ in 2025 | Lower aggregate than US but subject to ETS cap | Much smaller absolute volume | US rollback affects globally significant emissions volume |
| Manufacturing investment | Lower prospective electricity-system compliance cost can improve site economics | Higher carbon and often energy costs can weigh on investment | Similar challenge, mitigated by domestic policy | Investment-location pressure on Europe increases |
| Data-centre competitiveness | Potentially strengthened where power becomes more abundant or cheaper | Constrained in some regions by grid and power costs | Growing but grid-dependent | US can strengthen position in electricity-intensive digital investment |
| Steel | Domestic energy and carbon-cost advantage can improve | ETS + CBAM transition + declining free allocation | UK ETS + CBAM from 2027 | CBAM mitigates but does not erase energy-cost gap |
| Aluminium | Benefits where US power is cheap, though regional carbon intensity varies | Highly sensitive to power cost and carbon intensity | Similar dynamic | Low-carbon European producers can still compete effectively |
| Chemicals | Lower gas and electricity costs can be important | Particularly exposed in Germany and parts of Italy | Material industrial exposure | One of the sectors where US energy advantage can matter most |
| Hydrogen | US projects can combine cheap gas/renewables and incentives | EU producers face strict carbon-accounting structure | UK develops separate regime | Production pathway and electricity source become decisive |
| Fiscal impact | Lower anticipated regulatory expenditure and potentially lower §45Q outlays | Continued ETS revenue and decarbonisation spending | ETS revenues continue | US saves compliance/subsidy expenditure but sacrifices some decarbonisation investment |
| Environmental consequence | Higher fossil utilisation and higher CO₂ than prior regulatory baseline | Carbon cap continues tightening | Carbon cap continues | Climate-policy divergence widens |
| Trade effect | US goods can gain underlying production-cost advantage | CBAM offsets carbon-price component on covered imports | UK CBAM provides similar adjustment | Trade advantage is reduced, not eliminated |
| Investment effect | Potentially stronger than trade effect because not every product faces CBAM | Risk of new capacity locating outside EU | Similar UK concern | Investment leakage is the larger long-term strategic risk |
| 2030 strategic direction | Cheaper fossil option remains available if policy survives | CBAM factor falls to 51.5%, exposing more domestic carbon cost | CBAM operational and ETS retained | Transatlantic divergence becomes much more economically visible by 2030 |
Sources: EPA Finalizes Repeal of 2024 Power Plant Regulations — U.S. EPA — Sep 2026 ; U.S. Energy-Related Carbon Dioxide Emissions, 2025 — EIA — Jul 2026 ; Directive (EU) 2023/959 — European Union ; UK ETS Policy Overview — UK Government — Sep 2026 ; UK CBAM Policy Summary — HMRC — Sep 2026
Country comparison inside Europe
| Factor | Italy | France | Germany | United Kingdom |
|---|---|---|---|---|
| Primary vulnerability | Gas and electricity cost | Industrial/process emissions more than power carbon intensity | High industrial exposure plus residual coal/gas electricity | Carbon-price exposure plus gas-based marginal power |
| Coal dependence | Very low | Extremely low | Still significant | Coal largely removed from power mix |
| Gas dependence | High | Low-moderate for power | Significant | Significant |
| Renewable position | Rapidly expanding | Important but nuclear dominates low-carbon supply | High renewable share | High and rising clean-power share |
| Nuclear contribution | None currently | Very high | None | Material but below France |
| Carbon-intensity position | Intermediate | Strongest of the four | Weaker than France because fossil generation remains material | Stronger than Germany/Italy in many periods, weaker than France |
| Industrial sectors most exposed | Machinery, metals processing, ceramics, chemicals, food, energy-intensive SMEs | Chemicals, cement, steel, aluminium, hydrogen | Steel, chemicals, machinery, autos, basic materials | Steel, chemicals, cement, hydrogen |
| Sensitivity to cheaper US electricity | High for manufacturing | Lower where low-carbon French electricity remains competitive | Very high | High |
| CBAM protection | EU CBAM | EU CBAM | EU CBAM | UK CBAM from 2027 |
| Free-allocation transition | EU phase-down | EU phase-down | EU phase-down | Separate UK adjustment |
| Main strategic challenge | Convert renewable additions into lower industrial prices | Convert low-carbon electricity into long-term competitive contracts | Decarbonise without losing industrial scale | Combine ETS ambition with industrial competitiveness |
| Main structural advantage | Manufacturing depth, strong renewable growth, interconnections | Nuclear-based low-carbon electricity | Industrial scale and engineering capacity | Flexible market and rapidly decarbonising power system |
Italy’s problem is therefore primarily cost, France’s opportunity is primarily low-carbon electricity, Germany’s problem is primarily the combination of industrial scale and fossil/carbon exposure, and the United Kingdom’s challenge is primarily managing the transition between domestic carbon pricing and border protection without weakening industrial investment.
Who gains and who loses
| Actor | United States | Europe |
|---|---|---|
| Existing coal-plant owners | Clear relative gain from longer economic life | No corresponding benefit under ETS |
| Gas generators | Gain from weaker federal CCS obligation, but competition from retained coal increases | Continue paying carbon cost |
| Coal producers | Strong relative gain | Coal demand generally structurally declining |
| Natural-gas producers | Mixed because retained coal can suppress power-sector gas demand | Gas remains important but carries ETS carbon cost |
| CCS developers | Lose mandatory-market demand, retain §45Q opportunity | Carbon-price incentive remains stronger |
| Renewables developers | Face somewhat lower replacement need than under former US CPS baseline | Policy-driven demand remains strong |
| Grid developers | Demand remains high because US load grows rapidly | Very strong need for grid reinforcement |
| Industrial electricity users | Can benefit from lower future power-system cost | Face continued carbon and electricity pressure |
| Steel/aluminium producers | Potential domestic cost advantage | CBAM provides partial protection |
| Chemical industry | Potential gas/electricity advantage | Particularly exposed in Germany and Italy |
| Data centres | Potential advantage from abundant fossil-backed capacity | Grid constraints and higher power costs can be limiting |
| Taxpayers | Lower potential §45Q expenditure where CCS projects disappear | Continue funding transition through multiple mechanisms |
| Consumers | Potentially lower rates later, not necessarily immediately | Benefit depends on success of European energy transition |
| Climate/air-quality objectives | Weaker relative to prior federal baseline | Remain central to policy architecture |
The critical difference between 2026 and 2030
In 2026, the economic divergence is still partly prospective because much of the avoided US compliance investment would not have occurred immediately, while European free allocation remains largely intact at a CBAM factor of 97.5%.
By 2030, however, the situation becomes substantially different because the EU free-allocation factor falls to 51.5%, meaning that nearly half of the previous protection for CBAM sectors has disappeared, while US utilities may by then have invested according to a regulatory environment in which the most important federal power-sector GHG requirements have been removed. Directive (EU) 2023/959 — European Union
The real strategic test is therefore not whether European industry experiences an immediate shock in September 2026, but whether Europe can reduce industrial electricity costs, accelerate grid construction, secure low-carbon generation and enforce CBAM effectively before the free-allocation protection declines much more sharply.
The clearest possible net assessment
For the United States, the decision means that the federal government is choosing to preserve more of the economic value of the existing fossil-electricity system rather than forcing a faster technological replacement through power-sector greenhouse-gas regulation; the probable economic effect is lower prospective compliance and replacement cost, greater flexibility for utilities, a longer economic life for coal and gas assets, and potentially lower electricity and industrial energy costs in some regions, while the corresponding environmental effect is greater fossil-fuel utilisation and higher CO₂ emissions than under the regulatory baseline previously in force. EPA Finalizes Repeal of 2024 Power Plant Regulations — U.S. EPA — Sep 2026
For the European Union, the decision means that its industrial decarbonisation policy is becoming more difficult economically because European producers continue to face an explicit carbon-price architecture while a major industrial competitor is reducing part of the regulatory cost embedded in electricity production; CBAM reduces this disadvantage for covered products, but it cannot neutralise lower American electricity prices, cheaper gas, differing tax incentives or investment conditions.
For Italy, the principal concern is whether rapid renewable growth and grid investment can translate into electricity prices sufficiently competitive to protect an industrial structure dominated by manufacturing and energy-sensitive medium-sized enterprises.
For France, the principal opportunity is to turn its unusually low-carbon electricity system into a direct industrial advantage, because a low-carbon power system becomes increasingly valuable when foreign production is both cheaper and more carbon-intensive.
For Germany, the principal problem is that it faces the largest combined exposure among the four countries examined: a very large manufacturing base, continuing coal and gas generation, EU carbon-price exposure and intense competition with American industry.
For the United Kingdom, the central challenge is similar to the EU’s but institutionally separate, because the UK is simultaneously maintaining its own ETS and preparing a CBAM beginning in 2027, while competing for the same mobile industrial investment against the United States. UK Emissions Trading Scheme: Policy Overview — UK Government — Sep 2026 Carbon Border Adjustment Mechanism: Policy Summary — HMRC — Sep 2026
The broad transatlantic consequence is therefore not simply “America deregulates while Europe regulates.” The deeper change is that America is attempting to lower the cost of energy abundance while Europe is attempting to raise the carbon discipline of production and trade, and whether Europe can sustain that strategy without losing industrial investment will depend increasingly on whether low-carbon electricity also becomes abundant, reliable and inexpensive.
What the Trump Power-Sector Rollback Actually Means for the United States and Europe: Geoeconomic Asymmetry and the 2030 Cliff
BLUF / Strategic Assessment: The September 2026 rollback does not divide the world into an unregulated America and a regulated Europe, but establishes an asymmetric economic divergence between an American power system lowering the cost of dispatchable fossil generation and a European industrial base facing tightening carbon pricing under the EU ETS and CBAM. In the United States—where fossil fuels still supplied 58% of generation in 2025 (41% gas, 17% coal)—the primary dividend is avoided future capital expenditure: utilities avoid costly CCS mandates and premature retirements, freeing power generation to meet data center and industrial load growth. In Europe, the policy creates relative competitive friction: while CBAM taxes covered primary materials at the border, it does not equalize industrial electricity rates or prevent investment leakage in finished goods, a tension that accelerates between 2029 and 2031 as EU free allowances drop toward the 51.5% mark in 2030.
United States Generation Baseline & Fossil Asset Dominance (4.43 Trillion kWh)
U.S. Fleet Economics: Avoided Sunk-Asset Replacement & Load Expansion
Table 1: Strategic Divergence Across Energy, Carbon Pricing & Industrial Policy
| Policy Dimension | United States (Post-Repeal) | European Union (EU-27) | Strategic Market Implication |
|---|---|---|---|
| Power-Sector Carbon Limits | 2024 Standards Vacated: No mandatory CCS or fuel co-firing; §111 authority challenged. | EU ETS Enforced: Power generation covered under declining emissions cap; allowances required. | U.S. fossil generation operates without federal carbon pricing adders embedded in power rates. |
| Economy-Wide Carbon Price | No Federal Price: State systems (CA, RGGI) operate locally; no national ETS or carbon tax. | Statutory ETS: Transparent price signal across heavy industry and aviation (€60–€85/t). | Structural carbon-cost asymmetry between U.S. and European industrial manufacturers. |
| Trade-Border Mechanism | None at Federal Level: No import border carbon fees comparable to CBAM. | Definitive CBAM: Mandatory certificate surrender on imports in 6 energy-intensive sectors. | The EU applies border carbon charges to imports, with zero deductions for unpriced U.S. goods. |
| Free Allowance Protection | Not Applicable: No federal ETS allowance framework. | Declining Phase-Out: CBAM sector factor falls from 97.5% in 2026 to 51.5% in 2030 (0% by 2034). | European industry progressively internalizes full domestic carbon costs by 2030. |
| Carbon Capture Deployment | Incentive-Driven: Voluntary deployment supported by IRC §45Q tax credits ($85/t). | ETS Compliance Tool: Driven by high allowance prices and Net Zero Industry Act targets. | U.S. CCS shifts from a regulatory requirement to an optional financial investment. |
| Downstream Leakage Risk | Capital Destination: Attracts data centers, advanced manufacturing, and vehicle assembly. | Uncovered Exposure: Finished manufactured goods remain outside direct CBAM coverage. | European producers face competition from imported finished goods made with lower-cost energy. |
Table 2: Four-Country European Comparative Vulnerability & Structural Profile
| Country | Electricity Carbon Intensity | Primary Industrial Exposure | Key Transmission Channel | Strategic Position |
|---|---|---|---|---|
| France | 19.6 gCO₂e/kWh 95.2% low-carbon / 68.1% nuclear |
Chemicals, primary aluminium, green hydrogen, and electric-arc steelmaking. | Process emissions matter more than electricity carbon intensity; strong CBAM alignment. | Low-Carbon Shield |
| Germany | ~340–380 gCO₂e/kWh 58.6% renewable; 38.2% coal/gas |
€2.5B steel and €419M aluminium exports to U.S. (2025); machinery and automotive. | Marginal wholesale power set by fossil generation with embedded ETS carbon costs. | High Exposure |
| Italy | ~240–280 gCO₂e/kWh 153.1 TWh thermoelectric; 3 TWh coal |
Specialized machinery, secondary metallurgy, ceramics, glass, and industrial SMEs. | Vulnerability tied to imported gas reliance rather than coal; exposed to industrial electricity tariffs. | Gas-Linked Drag |
| United Kingdom | 104 gCO₂e/kWh 73.3% clean power; coal nearly 0% |
Domestic steel, chemicals, fertilisers; independent UK ETS (auction floor £28/t). | UK CBAM effective 1 Jan 2027; interim exposure to unadjusted U.S. and global imports in 2026. | Parallel Regime |
Tripartite Systemic Dynamics: Energy Abundance vs Carbon Discipline
U.S. ENERGY ABUNDANCE
AVOIDED REPLACEMENT- Sunk Asset Economics: Retaining existing coal and gas units avoids premature capital retirement, lowering required near-term investments in replacement generation.
- Serving Load Growth: Meeting new demand from data centers and advanced manufacturing without forced plant retirements eases pressure on regional grids.
- Emissions Tradeoff: Avoided compliance expenditures coincide with higher cumulative carbon dioxide emissions (+533 Mt in 2040) and increased conventional air pollutants.
EU CARBON DISCIPLINE
51.5% ALLOCATION IN 2030- Tightening Allocation: Free EU ETS allowances for CBAM sectors decrease steadily from 97.5% in 2026 to 51.5% in 2030, phasing out entirely by 2034.
- Rising Cost Exposure: As historical allocations decline, European producers bear increasing direct costs for unmitigated emissions under the EU ETS.
- Dependence on CBAM: The border mechanism must accurately verify embedded carbon to prevent foreign producers from capturing market share as domestic protections phase out.
INVESTMENT LEAKAGE
UNCOVERED MANUFACTURE- Scope Boundaries: CBAM assesses primary bulk goods (steel, aluminium, cement, fertilisers, hydrogen), leaving finished manufactured products and data services outside border adjustments.
- Capital Location Incentive: Industrial projects with high power consumption can benefit from lower regulatory costs in the U.S. without triggering EU border tariffs on finished exports.
- Downstream Vulnerability: European fabricators using domestically priced low-carbon materials compete with foreign imports made from lower-cost components.
Forensic Strategic Key Judgments: Transatlantic Impact Synthesis
Avoided Future Investment Drives U.S. Gains
The U.S. economic benefit is not an immediate price drop, but the avoidance of large capital expenditures in the 2030s, preserving depreciated fossil capacity to serve new demand.
European Exposure Expands Post-2028
As EU free allocation factors decline from 90% in 2028 to 51.5% in 2030, European heavy industry internalizes rising domestic carbon costs while competing against unconstrained U.S. production.
France Leverages Structural Low-Carbon Baseline
With a power grid operating at 19.6 gCO₂e/kWh and 95.2% low-carbon output in 2025, French electro-intensive manufacturing maintains low embedded emissions relative to fossil-heavy systems.
Germany Balances Trade Scale with Residual Fossil Costs
Exporting €2.5B in steel to the U.S. while relying on coal and gas for 38.2% of generation leaves German manufacturers exposed to both U.S. competition and domestic ETS compliance costs.
Investment Leakage Exceeds Direct Import Threat
Because CBAM applies primarily to bulk commodities, finished manufactured products and computing infrastructure remain uncovered, creating long-term incentives to direct capital investment to the U.S.
U.S. Exporters Face Unmitigated CBAM Tariffs
With no federal carbon price to claim under CBAM Article 9, U.S. primary material exporters face standard border carbon certificate fees, offsetting domestic energy cost advantages upon entry to Europe.
Open Official Record Gaps
- Realized CBAM Certificate Yields: Data reflecting actual financial settlements and certificate prices paid by EU importers of U.S. goods during the early definitive phase remains unpublished.
- Status of U.S. Subnational Deductions: Formal European Commission rulings clarifying whether allowance payments under California Cap-and-Invest qualify for Article 9 deductions are not yet finalized.
- UK CBAM Sectoral Rates: The definitive calculation methodology and overseas deduction criteria for the UK CBAM launching 1 January 2027 remain under secondary rulemaking.
- Capital Relocation Data: Verified statistics tracking capital shifts by European chemical and steel firms moving upstream assets to the U.S. remain commercially confidential.
Observable Watch Indicators
Navigational Index
Pillar One — Federal authority, power-plant standards and the surviving carbon-accounting architecture
The first pillar establishes what EPA actually repealed on 14 September, what remains only proposed, how §111 of the Clean Air Act interacts with West Virginia v. EPA, and why emissions measurement, regulatory emission limits and carbon pricing must not be treated as interchangeable legal instruments.
Pillar Two — Electricity economics, coal and gas dispatch, carbon capture and the distribution of regulatory costs
The second pillar examines EPA's projected compliance-cost savings against its own projections for additional CO₂ and conventional pollutants, the consequences for coal and natural gas generation, CCS economics and §45Q incentives, and the extent to which lower federal regulatory costs can translate into electricity-price or industrial-cost effects.
Pillar Three — Transatlantic carbon divergence and implications for Europe
The third pillar assesses the interaction with EU ETS and CBAM, the United Kingdom's independent ETS and forthcoming CBAM, and the differentiated exposure of Italy, France, Germany and the United Kingdom to a United States economy operating under materially weaker federal carbon constraints.
Master Abstract
The September decision is more significant than a normal regulatory repeal, but narrower than the proposition that Washington has already eliminated every power-sector CO₂ constraint
The legally accurate starting point is that two different EPA actions were announced in Houston on 14 September 2026, and collapsing them into a single completed repeal would overstate the present position. The first is a final Partial Repeal of the Carbon Pollution Standards for Fossil Fuel-Fired Electric Generating Units, through which EPA repealed most of the Biden administration's 2024 standards, including emission guidelines for existing fossil-fuel steam units and major CCS-based requirements; the second is a supplemental proposal arguing that Clean Air Act §111 should not be interpreted as authorising EPA to regulate power-plant emissions in response to global climate-change concerns and proposing, on that basis, the rescission of the remaining GHG findings and standards. EPA's prepublication final rule expressly states that it was signed on 14 September and was awaiting Federal Register publication, with effectiveness specified for 60 days after that publication, making the timing of Federal Register publication and subsequent litigation an immediate legal watchpoint rather than an administrative technicality. Partial Repeal of the Carbon Pollution Standards for Fossil Fuel-Fired Electric Generating Units — U.S. Environmental Protection Agency — Sep 2026
The broader initiative nevertheless belongs to a sequence rather than an isolated decision, because EPA had already finalized on 12 February 2026 the rescission of the 2009 Greenhouse Gas Endangerment Finding in the context of motor vehicles and repealed the associated federal vehicle GHG standards under Clean Air Act §202(a); the September power-sector proposal now attempts to extend the administration's underlying statutory theory into §111 by contesting EPA's authority to regulate fossil-fuel power plants for global climate purposes. EPA characterizes those actions principally as statutory-interpretation decisions rather than scientific determinations, and its February response-to-comments document explicitly states that its motor-vehicle rescission was based on its interpretation of statutory authority rather than a new scientific finding on climate change. Consequently, describing the September rule simply as legal codification of “climate denial” would obscure the formal legal argument the agency has actually adopted, irrespective of the broader political interpretation attached to the administration's climate strategy. Final Rule: Rescission of the Greenhouse Gas Endangerment Finding and Motor Vehicle Greenhouse Gas Emission Standards Under the Clean Air Act — U.S. EPA — Feb 2026
The strongest practical effect is the removal of a federal investment constraint on future fossil generation, not the disappearance of CO₂ as a measurable economic variable
The distinction between measurement, regulation and pricing is critical because they belong to separate institutional systems. EPA's Greenhouse Gas Reporting Program still contains detailed calculation and reporting requirements for qualifying power plants under 40 CFR Part 98, including Subpart D, which explains what emissions must be reported and how they are calculated, while EPA continues to operate the e-GGRT reporting infrastructure; however, a separate September 2025 proposal seeks to remove GHGRP obligations for 46 source categories, and the reporting deadline for 2025 emissions has been postponed to October 2026 while EPA develops its final position. In other words, federal carbon-data infrastructure is itself under pressure, but the 14 September power-plant rule did not automatically erase the measurement system that produced historical US emissions inventories and facility-level data. Subpart D Information Sheet — U.S. Environmental Protection Agency — current 2026 Rulemaking Notices for GHG Reporting — U.S. Environmental Protection Agency — Jun 2026
This distinction matters particularly for international trade because foreign carbon mechanisms do not require EPA to maintain US power-plant emission limits in order to calculate the embedded carbon of American goods. The EU CBAM definitive regime has applied since 1 January 2026 to covered goods including iron and steel, aluminium, cement, fertilizers, hydrogen and electricity, and EU importers must surrender certificates corresponding to embedded emissions, with the certificate price linked to EU ETS allowance prices; under Article 9 of Regulation (EU) 2023/956, a reduction is available only where the importer demonstrates that a carbon price has actually been paid in the country of origin. Consequently, weakening US domestic carbon pricing or regulatory constraints does not neutralize European carbon costs and can instead reduce the deduction available against CBAM where no corresponding domestic carbon payment exists. Regulation (EU) 2023/956 establishing a carbon border adjustment mechanism — European Union — May 2023
EPA's own modelling identifies a substantial emissions trade-off that cannot be inferred from the headline cost-saving figure alone
EPA publicly describes the final partial repeal as generating approximately $310 billion of savings, but that figure should be read as an agency-modelled regulatory cost result rather than an observed increase in national income or a guaranteed reduction in household electricity bills, because the Regulatory Impact Analysis models changes in capital, fuel, operations and maintenance, transmission, carbon-transport-and-storage expenditure, tax credits and related electricity-sector variables over a long analytical horizon. EPA's same model projects that power-sector CO₂ emissions under the repeal scenario exceed the 2024-standard baseline by 20 Mt in 2030, 406 Mt in 2035, 533 Mt in 2040 and 486 Mt in 2045, and its modelling also projects materially higher NOₓ and SO₂ emissions as fossil generation is dispatched differently. EPA expressly states that CO₂-related climate impacts were not monetized, pursuant to the administration's current analytical policy, so the $310 billion figure is not a comprehensive monetised social-benefit-minus-social-cost calculation in which the incremental climate damages associated with the additional emissions have been assigned an economic value. Regulatory Impact Analysis for the Final Partial Repeal of the Carbon Pollution Standards for Fossil Fuel-Fired Electric Generating Units — U.S. EPA — Sep 2026
The model also demonstrates why the impact cannot be reduced to a simple claim that deregulation mechanically lowers electricity prices. EPA projects a 0.7% increase in retail electricity prices in 2030 relative to its regulatory baseline, followed by estimated reductions of 5.8% in 2035, 1.1% in 2040 and 2.6% in 2045, while coal production for the power sector and delivered coal prices move substantially in the opposite direction as additional coal generation remains economic. These are model outputs rather than guaranteed market outcomes, and EPA itself identifies uncertainty around the power-sector modelling, CCS deployment assumptions, fuel prices, demand growth and technology costs, which is particularly relevant in an electricity system facing rapid data-centre and manufacturing-load growth. Regulatory Impact Analysis for the Final Partial Repeal of the Carbon Pollution Standards for Fossil Fuel-Fired Electric Generating Units — U.S. EPA — Sep 2026
The power sector matters because its emissions are already comparable with the national emissions of major economies
The United States electric-power sector emitted approximately 1.485 billion metric tonnes of energy-related CO₂ in 2025, compared with approximately 1.871 billion tonnes from transportation, making electricity generation the second-largest US energy-related CO₂ sector under EIA's classification; total US energy-related CO₂ emissions were approximately 4.904 billion tonnes, while power-sector emissions increased by 4% in 2025 as generation, electricity demand and coal use rose. EIA attributed part of that growth to increased electricity demand from data centres and manufacturing, as well as weather-related electricity demand, making the regulatory treatment of marginal power generation increasingly consequential as US electricity consumption expands. U.S. Energy-Related Carbon Dioxide Emissions, 2025 — U.S. Energy Information Administration — Jul 2026
This scale also explains why the regulatory dispute extends beyond conventional environmental policy into questions of electricity-system investment, AI infrastructure, manufacturing strategy, natural-gas demand and coal-plant retirement. The administration's position, reflected in the September rule, is that the earlier standards relied on CCS requirements that were not adequately demonstrated and could not realistically be deployed at the required scale by the 2032 compliance timetable; EPA therefore removed those requirements while leaving open the broader supplemental legal argument that §111 should not support power-sector GHG regulation for global-climate purposes. That technical conclusion is contested policy terrain, but the final rule's operative basis is observable: EPA has changed its BSER determination and its assessment of CCS achievability rather than merely suspending compliance discretionarily. Partial Repeal of the Carbon Pollution Standards for Fossil Fuel-Fired Electric Generating Units — U.S. EPA — Sep 2026
Carbon capture does not disappear economically simply because EPA has removed it as the regulatory baseline technology
The federal §45Q carbon-oxide sequestration tax credit continues to exist, which is a crucial distinction for industrial strategy because CCS can therefore migrate from being a regulatory compliance obligation toward being an investment undertaken where tax incentives, project economics, transport infrastructure and storage geology support deployment. IRS guidance current in 2026 continues to provide credits for qualified carbon oxide captured at eligible facilities and securely stored or used under statutory conditions, while the Treasury tax architecture includes specific reporting and lifecycle-analysis requirements. Credit for Carbon Oxide Sequestration — Internal Revenue Service — 2026
This creates a markedly different industrial signal from the Biden-era standard: rather than requiring certain electricity-generating units to reach an emissions-performance level premised upon large-scale CCS deployment, the emerging structure allows CCS investment to depend more heavily on fiscal incentives and project economics. The consequence is therefore not the technological extinction of carbon capture, but a shift from regulation-driven deployment toward incentive- and market-driven deployment, with potentially profound effects on pipelines, geological storage projects, engineering supply chains and the development schedules of gas-fired generation associated with high-load industrial and data-centre clusters.
Key Evidence Table
| Indicator | Value/status | Reference date | Definition/scope | Issuer | Exact source |
|---|---|---|---|---|---|
| 2024 power-plant GHG requirements | Most provisions repealed by final EPA action | 14 Sep 2026 | Existing fossil steam units and specified CCS-based standards among provisions repealed | U.S. EPA | Partial Repeal of the Carbon Pollution Standards for Fossil Fuel-Fired Electric Generating Units — Sep 2026 |
| Remaining federal power-plant GHG standards | Complete repeal proposed, not yet final | 14 Sep 2026 | Supplemental §111 proposal | U.S. EPA | Greenhouse Gas Standards and Guidelines for Fossil Fuel-Fired Power Plants — Sep 2026 |
| US electric-power energy-related CO₂ | 1,485 Mt CO₂ | 2025 preliminary | Electric power sector | EIA | U.S. Energy-Related Carbon Dioxide Emissions, 2025 — Jul 2026 |
| Transportation energy-related CO₂ | 1,871 Mt CO₂ | 2025 preliminary | Transportation sector | EIA | U.S. Energy-Related Carbon Dioxide Emissions, 2025 — Jul 2026 |
| Incremental power-sector CO₂ from final repeal | +20 Mt | 2030 | Lower 48; repeal versus 2024 CPS baseline | U.S. EPA | Regulatory Impact Analysis — Sep 2026 |
| Incremental power-sector CO₂ | +406 Mt | 2035 | Same modelling basis | U.S. EPA | Regulatory Impact Analysis — Sep 2026 |
| Incremental power-sector CO₂ | +533 Mt | 2040 | Same modelling basis | U.S. EPA | Regulatory Impact Analysis — Sep 2026 |
| Incremental power-sector CO₂ | +486 Mt | 2045 | Same modelling basis | U.S. EPA | Regulatory Impact Analysis — Sep 2026 |
| Claimed regulatory savings from partial repeal | approximately $310bn | EPA estimate announced Sep 2026 | Agency-modelled effects; not observed GDP gain | U.S. EPA | EPA Finalizes Repeal of 2024 Power Plant Regulations — Sep 2026 |
| Additional savings from complete remaining repeal | $370m PV at 3% discount rate | 2026–2047 | 2024 dollars; supplemental proposal | U.S. EPA | Economic Impact Analysis for Supplemental Proposed Rule — Sep 2026 |
| Federal GHG facility reporting | Still operative, but under separate reconsideration | Sep 2026 | 40 CFR Part 98 | U.S. EPA | Greenhouse Gas Reporting Program — 2026 |
| EU CBAM definitive phase | In force | 1 Jan 2026 | Cement, iron/steel, aluminium, fertilizers, electricity, hydrogen | European Commission | CBAM Definitive Regime — 2026 |
| UK ETS coverage | Power, heavy industry, aviation and expanded sectors | Sep 2026 | Approximately 25% of UK territorial emissions under the core scheme before expansion effects | UK Government | UK ETS: Policy Overview — Sep 2026 |
| UK CBAM | Starts 1 Jan 2027 | 2027 | Aluminium, cement, fertiliser, hydrogen, iron and steel | HM Government | Carbon Border Adjustment Mechanism — 2026 |
The European consequence is divergence rather than deregulation contagion
For the European Union, the American decision does not alter the legal operation of the EU ETS or CBAM because both depend upon EU law rather than reciprocal American regulation; instead, weaker US federal carbon constraints increase the importance of calculating actual embedded emissions and documenting any carbon price paid in the United States, because EU CBAM permits the importer to reduce its certificate obligation only where an effective carbon price has already been paid in the country of origin. US production situated in jurisdictions with no equivalent carbon charge therefore receives no automatic recognition simply because EPA previously imposed technology-based GHG standards, while facilities operating under California's carbon market or another qualifying carbon-pricing regime raise more complex attribution questions that depend upon the product, installation, payment actually made and applicable CBAM methodology. Regulation (EU) 2023/956 — European Union — May 2023
For Germany, the strategic issue is principally industrial competitiveness because electricity-intensive manufacturing remains exposed to the EU carbon-price architecture while comparable US facilities can increasingly operate in an electricity system whose federal environmental constraint on marginal coal and gas generation has been weakened; the consequence is not automatically a cost advantage for every American manufacturer, because US electricity prices remain regional and determined by fuel, transmission, capacity, weather and investment conditions, but the regulatory component of long-duration fossil generation becomes less restrictive precisely as American manufacturing and data-centre electricity demand are expanding.
For Italy, the direct exposure is smaller through domestic coal generation but substantial through manufacturing supply chains, imported energy-intensive intermediate goods and the operation of CBAM at the EU external frontier, because Italian steel users, machinery producers, construction-material buyers and industrial importers increasingly need auditable embedded-emissions data even where the exporting jurisdiction itself has relaxed climate regulation. The American rollback therefore makes reliable measurement more important to Italian trade administration rather than less important, particularly if EPA's separate proposal to reduce federal GHG reporting ultimately decreases the availability of standardized public emissions data.
For France, the relatively low carbon intensity of electricity generated from its nuclear-heavy system creates a structurally different exposure, because the competitive question is less the domestic electricity-sector compliance burden than whether carbon-intensive imports from economies with weaker constraints receive equivalent treatment at the EU border. A widening US-EU regulatory divergence can therefore strengthen the economic importance of CBAM from the French perspective even where American fossil-fired electricity does not itself cross the Atlantic, because electricity carbon intensity propagates through aluminium, hydrogen, chemicals, metals and other industrial production chains.
For the United Kingdom, the logic is similar but institutionally separate because the UK ETS places a carbon price on covered power, heavy-industry and aviation emissions, while the British CBAM is scheduled to begin on 1 January 2027 for aluminium, cement, fertiliser, hydrogen, iron and steel; the UK government states that CBAM rates will reference domestic carbon-pricing costs and that foreign carbon-price payments can be relevant to relief, so widening carbon-price divergence with the United States creates a parallel British requirement for credible foreign emissions and carbon-payment verification. UK Emissions Trading Scheme: Policy Overview — UK Government — Sep 2026 Carbon Border Adjustment Mechanism — HM Government — Sep 2026
The legal durability question remains open rather than settled permanently
The proposition that the September action would prevent a future administration from ever regulating power-plant greenhouse gases requires qualification, because one administration ordinarily cannot make its statutory interpretation permanently binding upon future administrations merely by issuing a regulation; a future EPA could attempt another rulemaking under the Administrative Procedure Act, provided that it supplied an adequate statutory and evidentiary basis and survived judicial review, while Congress could itself amend the Clean Air Act and the courts retain authority to determine the permissible scope of agency action.
The relevant judicial constraint is nevertheless substantial because in West Virginia v. EPA the Supreme Court held in 2022 that EPA lacked sufficiently clear congressional authorization to implement the particular generation-shifting regime embodied in the Clean Power Plan, applying the major-questions doctrine to that regulatory architecture, although the Court expressly did not decide that §111 categorically bars every source-level mechanism for reducing power-sector CO₂. West Virginia v. Environmental Protection Agency, 597 U.S. 697 — Supreme Court of the United States — Jun 2022
The September 2026 supplemental proposal attempts to move considerably further by arguing that §111 itself should not be read to authorize power-plant regulation directed at global climate-change concerns, which, if finalized and sustained by the courts, would raise the legal hurdle facing a future EPA because reinstating regulation would require reversing a formal statutory interpretation under conditions of intensive judicial review; nevertheless, the ultimate durability of that position cannot be established until the supplemental proposal becomes final, the administrative record is complete, litigation occurs and the judiciary determines whether EPA's new construction of §111 is permissible. Rescission of the Greenhouse Gas Findings for Fossil Fuel-Fired Power Plants and Repeal of Regulations for Power Plant Greenhouse Gas Emissions Under Clean Air Act Section 111 — U.S. EPA — Sep 2026
Principal Gaps and Watch Indicators
The first decisive indicator is Federal Register publication and the resulting effective date of the final partial repeal, because the EPA document available on 19 September remains a signed prepublication version stating that the official Federal Register version will control for compliance purposes. Partial Repeal of the Carbon Pollution Standards — U.S. EPA — Sep 2026
The second indicator is whether EPA ultimately finalizes the supplemental §111 proposal rescinding all remaining GHG power-plant standards, because the legal consequences of that action would be broader than the partial repeal already signed and would determine whether a residual federal performance-standard structure survives.
The third indicator is the resulting D.C. Circuit and potentially Supreme Court litigation, particularly whether challengers persuade the courts that EPA's new interpretation of §111 is inconsistent with the Clean Air Act, inadequately reasoned under administrative law, or insufficiently attentive to reliance interests and the existing statutory record.
The fourth indicator is EPA's still-pending reconsideration of the Greenhouse Gas Reporting Program, because elimination of facility reporting across dozens of sectors would affect not only domestic environmental administration but also data availability for investors, counterparties, supply-chain carbon accounting and potentially exporters attempting to establish actual embedded emissions for foreign regulatory purposes. Proposed Reconsideration of the Greenhouse Gas Reporting Program — U.S. EPA — Sep 2025
The fifth indicator is the behaviour of US power-sector investment itself, particularly coal retirement schedules, new combined-cycle gas construction, CCS final-investment decisions, transmission development and electricity demand from AI/data centres and manufacturing, because regulatory repeal changes incentives but does not override plant age, operating costs, regional gas prices, renewable economics, grid congestion or utility resource-planning decisions.
EPA-modelled increase in annual power-sector CO₂ emissions after the 2026 partial repeal
Difference from the EPA baseline retaining the 2024 Carbon Pollution Standards; million metric tonnes of CO₂, contiguous United States.
| Year | CPS baseline | Final repeal | Difference |
|---|---|---|---|
| 2030 | 1,551 Mt | 1,570 Mt | +20 Mt |
| 2035 | 1,108 Mt | 1,514 Mt | +406 Mt |
| 2040 | 878 Mt | 1,411 Mt | +533 Mt |
| 2045 | 720 Mt | 1,206 Mt | +486 Mt |
Source: U.S. Environmental Protection Agency, Regulatory Impact Analysis for the Final Partial Repeal of the Carbon Pollution Standards for Fossil Fuel-Fired Electric Generating Units, September 2026, Table 3-3. Values are EPA modelling projections rather than observed outcomes, and EPA states that CO₂ climate impacts were not monetized in this analysis.
Principal assessment: the September 2026 action should therefore be understood not as the disappearance of carbon accounting or of the international carbon-price architecture, but as a major retreat of federal US command-and-performance regulation of power-sector greenhouse gases, accompanied by a still-unfinished attempt to establish a much broader legal barrier to future EPA regulation. Its economic significance lies in extending the viable operating and investment horizon of fossil generation and reducing compliance expenditure; its environmental significance lies in the substantial additional emissions projected by EPA itself; and its international significance lies in widening the divergence between a United States increasingly removing federal carbon constraints and European systems that are simultaneously moving carbon pricing from domestic installations into the trade frontier through CBAM.
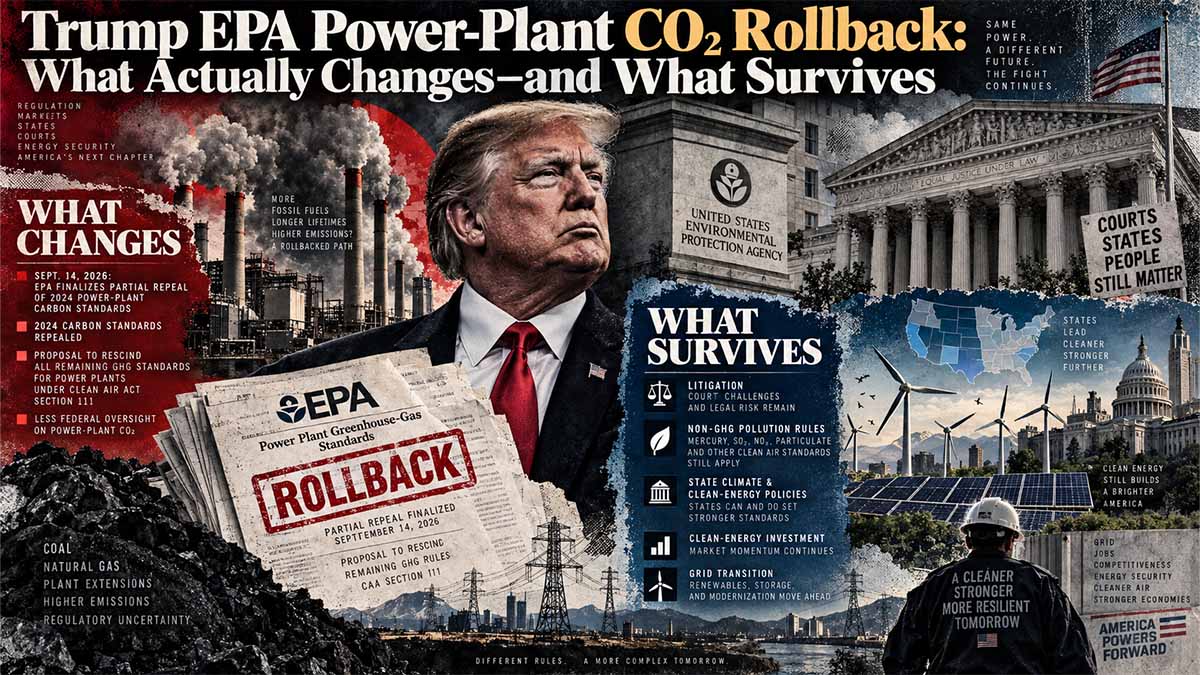
Trump EPA Power-Plant CO₂ Rollback: What Actually Changes—and What Survives
BLUF / Strategic Assessment: The 14 September 2026 EPA action does not abolish carbon accounting, eliminate all federal greenhouse gas oversight in a single legal instrument, or repeal a federal carbon tax (which does not exist at the federal level in the United States). Rather, it executes a major two-tier administrative maneuver: a signed final partial repeal of the 2024 Carbon Pollution Standards under Clean Air Act §111(d) vacating carbon capture and storage (CCS) mandates, paired with a supplemental proposal seeking to rescind all remaining power-sector GHG findings. EPA's own modelling reveals a substantial environmental trade-off (+20 Mt CO₂ in 2030, rising to +533 Mt in 2040), unmonetized in the agency's $310B regulatory cost-savings calculation. Crucially, facility measurement (40 CFR Part 98), §45Q tax credits, and state-level pricing (California Cap-and-Invest) survive, while the transatlantic carbon divergence widens—exposing U.S. industrial exports to full, unmitigated EU CBAM default tariffs without origin carbon deductions.
Incremental Power-Sector CO₂ Emissions Over 2024 Baseline (Million Metric Tonnes)
Power-Sector CO₂ Emissions Surge: The EPA Regulatory Impact Analysis
Table 1: Key Regulatory, Emissions and Trade Indicators (Audit Baseline 2026-09-19)
| Indicator / Instrument | Status / Audited Value | Date / Baseline | Scope & Operational Significance | Primary Issuer |
|---|---|---|---|---|
| 2024 Power-Plant GHG Standards | Repealed (Final Action) Prepublication signed |
14 Sep 2026 | Repeals guidelines for existing steam units and CCS mandates on coal and new baseload gas plants under CAA §111(d). | U.S. EPA |
| Residual §111 Power-Plant Standards | Proposed Rescission Rulemaking pending |
14 Sep 2026 | Supplemental proposal arguing §111 does not authorize EPA regulation of greenhouse gases for global climate concerns. | U.S. EPA |
| Claimed Regulatory Savings | ~$310 Billion +$370M PV in proposal |
2026–2047 | Agency-modeled capital, operating, and fuel cost savings; explicitly excludes monetization of climate damages. | U.S. EPA RIA |
| U.S. Power Sector Annual CO₂ | 1,485 Mt CO₂ +4% YoY increase |
2025 Prelim | Second-largest emitting sector (total U.S. 4,904 Mt); demand rising from data centres, AI clusters, and manufacturing. | U.S. EIA |
| Incremental CO₂ from Rollback | +20 Mt (2030) → +533 Mt (2040) +406 Mt (2035), +486 Mt (2045) |
Modeled Horizon | Direct emissions increase in Lower 48 over operative baseline; accompanied by substantial increases in NOx and SO₂. | U.S. EPA RIA |
| GHG Reporting Program (GHGRP) | Survives / Under Review Deadline pushed to 30 Oct 2026 |
40 CFR Part 98 | Facility measurement and e-GGRT remain operative, though separate proposal targets removal of 46 source categories. | U.S. EPA |
| IRC §45Q Carbon Sequestration Tax Credit | Fully Operative Statutory tax architecture |
2026 Current | CCS transitions from command-and-control regulatory mandate to market/fiscal incentive-driven commercial deployment. | U.S. IRS |
| Subnational Pricing (California Cap-and-Invest) | Fully Operative State-level enforcement |
2026 Current | Maintains state-level compliance and allowance surrender, proving U.S. carbon pricing is fragmented rather than extinct. | CARB |
| EU CBAM Definitive Regime | In Force (Definitive) Reg (EU) 2023/956 Art. 9 |
1 Jan 2026 | Requires certificate surrender at EU ETS price. Deductions permitted ONLY for carbon prices actually paid in origin state. | European Commission |
| UK CBAM Implementation | Scheduled Start Al, cement, fert., H2, steel |
1 Jan 2027 | Replicates border adjustment perimeter; reinforces transatlantic divergence for U.S. goods entering the British market. | HM Government |
Table 2: Differentiated Exposure Profiles: European Economies vs U.S. Carbon Divergence
| Jurisdiction | Primary Domestic Carbon Mechanism | Exposure Vector to U.S. Deregulation | Strategic Adaptation / Policy Lever |
|---|---|---|---|
| Germany | EU ETS + National nEHS (Heating/Transport) | Electricity-intensive industrial competitiveness; U.S. manufacturing operating on unconstrained fossil power. | Vigorous enforcement of CBAM on imported metals/chemicals; industrial electricity price bridge mechanisms. |
| Italy | EU ETS across heavy industry & power | Supply-chain verification drag; high reliance on imported energy-intensive intermediate goods (steel/machinery). | Customs infrastructure readiness for auditable embedded carbon data; protecting domestic re-rolling and fabrication. |
| France | EU ETS (Low grid intensity via nuclear baseload) | Low direct electricity compliance burden; high competitive concern over carbon-intensive imports in external markets. | Championing CBAM perimeter integrity to ensure low-carbon French output retains structural export advantages. |
| United Kingdom | UK ETS (~25% territorial emissions coverage) | Trade border vulnerability starting 2027; risk of unpenalized U.S. goods diverting into British markets pre-UK CBAM. | Accelerating 1 Jan 2027 UK CBAM implementation; coordinating technical verification with EU customs registries. |
The Tripartite Reality: Federal Deregulation, Surviving Levers & External Trade
FEDERAL RETRENCHMENT
FINAL & PROPOSED- Final Partial Repeal: Signed 14 September 2026, officially revoking 2024 emission guidelines for existing fossil steam and CCS mandates for coal and new gas baseload.
- Supplemental §111 Proposal: A distinct proposal arguing Clean Air Act §111 lacks statutory authorization to regulate greenhouse gases for global climate concerns.
- Judicial Vulnerability: The repeal relies on statutory interpretation rather than new scientific findings, facing review in the D.C. Circuit and Supreme Court under West Virginia v. EPA precedents.
SURVIVING ARCHITECTURE
MEASUREMENT & FISCAL- GHGRP 40 CFR Part 98: Facility-level emission measurement and e-GGRT remain operative, though a separate proposal to eliminate 46 source categories is pending (2025 deadline: 30 Oct 2026).
- IRC §45Q Tax Credits: Carbon capture shifts from an EPA regulatory mandate to a voluntary, market- and tax-driven investment model supported by statutory tax credits.
- Subnational Pricing: State carbon programs, such as California’s Cap-and-Invest system, continue operating independently of federal regulatory changes.
TRANSATLANTIC DIVERGENCE
EU CBAM IN FORCE- EU CBAM Enacted: In force since 1 January 2026; importers of steel, aluminum, cement, and chemicals must surrender certificates linked to EU ETS allowance prices.
- Zero Origin Offset: Because the U.S. lacks an economy-wide federal carbon tax, American exporters cannot claim origin deductions under CBAM Article 9, facing full default tariff charges.
- Competitive Asymmetry: While U.S. manufacturers gain domestic energy flexibility, their exports face carbon border adjustments in European markets, widening policy divergence across the Atlantic.
Forensic Strategic Key Judgments: Power-Sector Rollback Assessment
Two-Tiered Action: Final Repeal vs Proposed Rescission
The 14 September 2026 action signed a final partial repeal vacating 2024 CCS and existing fossil standards, while the broader proposal to eliminate all power-sector GHG authority under §111 remains under open rulemaking.
Substantial Modeled Emissions Rebound
EPA's official RIA models an incremental power-sector CO₂ increase of +20 Mt in 2030, +406 Mt in 2035, +533 Mt in 2040, and +486 Mt in 2045 over the 2024 baseline, accompanied by elevated NOx and SO₂ emissions.
$310B Savings Calculation Omits Climate Damages
The headline $310B regulatory cost savings figure is derived from power-sector system costs and explicitly excludes monetization of climate damages, leaving the economic analysis vulnerable to judicial review under the APA.
Facility Measurement Architecture Survives
Carbon accounting has not been abolished. The Greenhouse Gas Reporting Program (40 CFR Part 98) continues to collect facility-level data, even as a separate proposal to streamline 46 source categories remains pending.
CCS Shifts from Mandate to Tax-Incentive Model
Repealing technology-based performance standards does not eliminate carbon capture; investment now relies primarily on IRC §45Q tax credits, capital costs, and commercial project economics.
EU CBAM Enforces Full Carbon Tariffs on U.S. Goods
With the EU CBAM in effect and no federal carbon price to claim as an origin offset, U.S. exporters of steel, aluminum, and chemicals face default border carbon adjustments in European markets.
Open Official Record Gaps
- Federal Register Publication Date: The signed partial repeal remains in prepublication form; official publication in the Federal Register will establish the formal 60-day effective date.
- Outcome of Supplemental §111 Rulemaking: Public comments and final agency determinations on completely rescinding GHG findings under Section 111 remain pending.
- GHGRP Source Category Rulemaking: The EPA proposal to remove reporting mandates for 46 industrial categories is under reconsideration, with 2025 filings deferred to 30 October 2026.
- CBAM Subnational Credit Treatment: The European Commission has not finalized guidance on whether emissions from facilities in states with carbon markets (e.g., California) can claim partial tariff offsets.
Observable Watch Indicators
Pillar One — Federal authority, power-plant standards and the surviving carbon-accounting architecture
Principal judgment
The September 2026 EPA action changes the American climate-regulatory architecture more profoundly than a conventional rollback of emission limits because the administration is pursuing two legally distinct objectives at once: first, it has already removed the principal 2024 compliance mechanisms that would have required long-lived coal units and heavily utilised new gas turbines to achieve very large reductions in CO₂ emissions; second, through a separate supplemental proposal, it is attempting to establish that Clean Air Act §111 does not provide EPA with authority to regulate fossil-fuel power-plant greenhouse-gas emissions on the basis of their contribution to global climate change at all. The first objective alters regulated facilities' present compliance obligations; the second, if finalized and subsequently sustained in court, would change the legal foundation on which a future administration would have to rebuild federal power-sector climate regulation. Partial Repeal of the Carbon Pollution Standards for Fossil Fuel-Fired Electric Generating Units — U.S. EPA — Sep 2026
That distinction is essential because emission measurement, emission reporting, emission-performance standards and carbon pricing are separate legal systems even when all four ultimately use tonnes of CO₂ as an accounting unit. The September power-plant action directly attacks the third category, performance regulation under §111; EPA is separately reconsidering much of the Greenhouse Gas Reporting Program under 40 CFR Part 98; federal power-sector monitoring under other Clean Air Act programmes remains relevant; carbon-pricing systems operated by states are legally distinct from federal EPA performance standards; and the United States still does not possess a federal economy-wide carbon tax equivalent to the European Union Emissions Trading System. The institutional consequence is therefore fragmentation rather than the instantaneous disappearance of carbon accounting.
The legal architecture that existed before the September repeal
Section 111 of the Clean Air Act establishes a two-level stationary-source regime whose operation is substantially more complex than a single federal emissions ceiling. Under §111(b), EPA identifies source categories and establishes standards of performance for new, modified and reconstructed sources; under §111(d), EPA establishes a procedure through which states submit plans governing qualifying existing sources, subject to federal approval and ultimately federal intervention where a satisfactory state plan is not submitted. The statutory definition of a “standard of performance” ties the permissible emission limitation to the degree of reduction achievable through a best system of emission reduction, or BSER, that EPA determines has been adequately demonstrated after consideration of cost, non-air-quality health and environmental impacts, and energy requirements. The operative statutory text remains codified at 42 U.S.C. §7411. 42 U.S.C. §7411 — United States Code — current edition
This architecture matters because §111 does not simply allow EPA to declare an economy-wide quantity of permissible CO₂ and distribute it among generators. EPA first identifies the system of emission reduction that it believes satisfies the statute, derives an achievable level of performance from that system, converts the resulting determination into standards or emission guidelines, and then applies different implementation mechanisms depending upon whether the regulated plant is new or existing. The statutory controversy therefore concerns not merely how much CO₂ a power station may emit, but what technologies, operating practices and system boundaries EPA may legally consider when determining the BSER from which the standard is derived.
Clean Air Act §111 architecture relevant to power-sector greenhouse gases
| Legal layer | Primary function | Responsible authority | Application to fossil-power GHGs | Institutional significance |
|---|---|---|---|---|
| CAA §111(a) | Defines “standard of performance” and BSER framework | Congress / EPA implementation | Determines analytical basis for emission standards | Controls what EPA must demonstrate concerning technological feasibility, cost and energy effects |
| CAA §111(b)(1)(A) | Listing of stationary-source categories | EPA | Fossil-fuel electric generating units remain a listed source category | Threshold provision now central to EPA's supplemental 2026 legal theory |
| CAA §111(b) | Standards for new, modified and reconstructed sources | EPA | Historically covers new coal units and combustion turbines | Direct federal standards rather than state-plan mechanism |
| CAA §111(d) | Standards for qualifying existing sources | EPA + states | Used for existing fossil-fuel EGUs, particularly coal | EPA sets emission guidelines; states develop implementation plans |
| State plans | Source-specific implementation | State regulators, subject to EPA approval | Can incorporate source circumstances allowed under governing rules | Makes existing-source regulation partly federal and partly state-administered |
| Federal plan authority | Backstop where state obligations are unmet | EPA | Potential substitute where required state plan is absent or inadequate | Prevents §111(d) from depending entirely on voluntary state implementation |
Source: 42 U.S.C. §7411 — United States Code.
What the 2024 regulation attempted to require at plant level
The April 2024 Carbon Pollution Standards were constructed around different compliance pathways according to plant type, utilisation rate and intended operating life, rather than imposing a uniform national CO₂ rate on every fossil generator. For newly constructed combustion turbines, EPA divided units principally into low-load, intermediate-load and baseload categories; for existing coal-fired steam units, EPA differentiated plants according to their intended retirement horizon. This was consequential because a coal facility intending to remain operational after the end of the 2030s faced a fundamentally different regulatory pathway from a plant committing to retire before 2032. Overview: Final Carbon Pollution Standards for Fossil Fuel-Fired Power Plants — U.S. EPA — Apr 2024
The most demanding provisions concerned new baseload gas turbines and existing coal units intending to operate for the long term, for which EPA designated carbon capture and storage at approximately 90% capture as the relevant technological foundation for the second-phase or long-term performance requirement. Existing coal plants intending to operate after 1 January 2039 faced a compliance regime based on 90% CO₂ capture beginning in 2032, while coal units planning to cease operations before 2039 but remain operating beyond 2031 were placed under a separate pathway based on 40% natural-gas co-firing on a heat-input basis beginning in 2030. Plants committing to cease operations before 1 January 2032 were not given a CO₂-reduction obligation under that portion of the rule. Standards and Regulatory Impact Analysis — Final Carbon Pollution Standards — U.S. EPA — Apr 2024
2024 power-sector GHG requirements and their September 2026 status
| Plant category | 2024 regulatory architecture | Key threshold or technology basis | September 2026 status |
|---|---|---|---|
| Existing coal, operation planned ≥2039 | §111(d) emission guideline | 90% CCS; compliance from 2032 | Repealed by September 2026 final partial repeal |
| Existing coal, operation continuing beyond 2031 but ceasing before 2039 | §111(d) emission guideline | 40% natural-gas co-firing; compliance from 2030 | Repealed |
| Existing coal retiring before 2032 | No substantive CO₂-reduction obligation under 2024 long-term pathway | Retirement commitment | 2024 distinction largely rendered moot by repeal |
| Existing oil/gas steam EGUs | §111(d) guidelines | Routine operation/maintenance or fuel-related BSER by subcategory | Repealed components covered by partial repeal |
| New baseload gas combustion turbines | §111(b) NSPS | Initial efficient combined-cycle standard plus later CCS-based phase | CCS-based second phase repealed |
| New intermediate-load gas turbines | §111(b) NSPS | Efficient simple-cycle performance | Certain non-CCS emission-rate provisions remain |
| New low-load gas turbines | §111(b) NSPS | Low-emitting fuel / input-based approach | Residual requirements remain unless separate proposal is finalized |
| Modified/reconstructed covered units | §111(b) | Category-specific emission-rate provisions | Some residual standards continue pending broader rulemaking |
Sources: Final Carbon Pollution Standards — U.S. EPA — Apr 2024; Partial Repeal of the Carbon Pollution Standards — U.S. EPA — Sep 2026.
This table demonstrates the first major legal consequence of the September action: EPA has not merely postponed the 2030–2032 compliance dates. It has removed the regulatory determination that those CCS and natural-gas-co-firing pathways constitute the appropriate BSER for the affected classes of generating units. That distinction is important for utility investment decisions because a postponed requirement continues to influence capital planning through an expected future compliance obligation, whereas repeal removes the federal rule that would otherwise force the expenditure unless and until another valid regulation is promulgated.
The partial repeal leaves a residual federal CO₂ standard architecture
The 14 September action is deliberately described by EPA itself as a partial repeal because some greenhouse-gas standards remain in the Code of Federal Regulations while the separate supplemental proposal is pending. Among the surviving requirements are emission-rate standards applicable to certain new combustion turbines, including numerical standards retained for natural-gas-fired baseload and intermediate-load equipment. The signed regulatory text specifies, for example, baseload emissions limits of 360 kg CO₂/MWh-gross, equivalent to 800 lb CO₂/MWh-gross, for qualifying large natural-gas combustion turbines, with other limits varying according to turbine size and output basis; the intermediate-load standard identified in the regulatory text is 530 kg CO₂/MWh-gross, or 1,170 lb CO₂/MWh-gross, subject to the prescribed fuel-emission-rate adjustment. Partial Repeal of the Carbon Pollution Standards — Regulatory Text — U.S. EPA — Sep 2026
The difference between these surviving efficiency-oriented limits and the repealed CCS requirement is structurally important. An emission-rate standard based principally on efficient combustion constrains the amount of CO₂ produced per unit of electricity but does not require the very large post-combustion reduction that a 90% capture system was designed to achieve. Consequently, even before the supplemental proposal is finalized, the regulatory centre of gravity has already moved from a regime that contemplated deep decarbonisation of long-duration fossil generation toward one that, for the surviving new-source categories, principally governs the emissions performance of the combustion process.
Numerical examples from the residual combustion-turbine standards
| Category | Gross-output standard | Net-output equivalent stated in rule | Regulatory meaning |
|---|---|---|---|
| Large baseload natural-gas turbine | 360 kg CO₂/MWh-gross | 370 kg CO₂/MWh-net | Efficiency-related residual CO₂ standard |
| Same standard in imperial units | 800 lb CO₂/MWh-gross | 820 lb CO₂/MWh-net | Equivalent regulatory expression |
| Smaller qualifying baseload turbine reference | 410 kg CO₂/MWh-gross | 420 kg CO₂/MWh-net | Size-adjusted baseload reference |
| Intermediate-load turbine | 530 kg CO₂/MWh-gross | 540 kg CO₂/MWh-net | Higher permitted rate reflecting operating profile |
The remaining standards are therefore not trivial, but neither are they equivalent to the regulatory pathway that existed before 14 September. Their presence explains why the administration required a second proceeding if it wished to eliminate the power sector's remaining greenhouse-gas standards rather than simply repealing the CCS-based provisions.
The supplemental proposal targets the statutory gateway rather than merely another technical standard
The second September action is legally more ambitious because EPA is reconsidering the threshold proposition that permits §111 to be used for fossil-power greenhouse gases in the first place. In the final partial repeal, EPA expressly states that it is not finalizing the June 2025 primary proposal to repeal all GHG regulations on the basis that fossil-fuel EGUs do not “contribute significantly” to the relevant air pollution; instead, the agency issued a supplemental proposal seeking further comment on whether global climate-change concerns satisfy §111(b)(1)(A)'s requirement that a source category contribute significantly to “air pollution which may reasonably be anticipated to endanger public health or welfare.” Partial Repeal of the Carbon Pollution Standards — U.S. EPA — Sep 2026
This creates two conceptually separate legal routes to the same deregulatory destination. Under one route, EPA could conclude that fossil-fuel power plants do not make the statutorily required significant contribution to the relevant pollution; under the second, it could conclude that the form of global climatic harm at issue does not satisfy the statutory threshold in the manner necessary for §111 regulation of the source category. EPA states that both theories remain under consideration for a later final action. The legal significance is substantial because invalidating a particular BSER determines how EPA may regulate, whereas eliminating the underlying statutory predicate addresses whether EPA may regulate these emissions under §111 at all.
Regulatory ladder after the 14 September 2026 actions
| Question | Regulatory status on 19 Sep 2026 | Consequence |
|---|---|---|
| Must long-lived existing coal plants comply with the 2024 90% CCS-based guideline? | No, subject to completion/effectiveness of final repeal process and litigation | Principal 2024 coal decarbonisation pathway removed |
| Must affected medium-term coal plants meet the 40% gas co-firing pathway? | Repealed by final partial action | Major transition requirement removed |
| Must new baseload gas turbines satisfy the 2024 CCS-based second phase? | Repealed | Large new gas plants no longer face that federal CCS mandate |
| Are all CO₂ standards for new fossil generation gone? | No | Residual emission-rate standards continue |
| Has EPA finalized the proposition that §111 cannot regulate power-sector GHGs because of climate change? | No | Supplemental proposal remains subject to comment and final agency action |
| Could EPA still finalize the earlier “significant contribution” rationale? | Yes | EPA states both approaches remain available for later final action |
| Is judicial review complete? | No | Durability of the regulatory architecture is unresolved |
| Has Congress removed CO₂ or greenhouse gases from the Clean Air Act? | No | Statutory text remains unchanged; dispute concerns interpretation and implementation |
Sources: Greenhouse Gas Standards and Guidelines for Fossil Fuel-Fired Power Plants — U.S. EPA — Sep 2026; Partial Repeal of Carbon Pollution Standards — U.S. EPA — Sep 2026.
West Virginia v. EPA constrains the regulatory method, but it did not itself erase §111 authority over CO₂
The Supreme Court's 2022 decision in West Virginia v. EPA is central but frequently overstated. The Court considered the Obama administration's Clean Power Plan, under which EPA had interpreted §111(d) to permit a generation-shifting structure that effectively encouraged movement from higher-emitting generation toward lower-emitting or zero-emitting generation across the electricity system. The Court concluded that EPA's interpretation presented a “major question” and that Congress had not clearly granted EPA authority for the particular generation-shifting architecture adopted in that rule. West Virginia v. EPA, 597 U.S. 697 — Supreme Court of the United States — Jun 2022
The ruling did not, however, hold that EPA can never regulate CO₂ from fossil-fuel power plants under §111. That distinction influenced the Biden administration's subsequent 2024 design, which attempted to ground the most stringent standards in technologies applied at or to the regulated source—including CCS and fuel co-firing—rather than recreating the system-wide generation-shifting mechanism invalidated in West Virginia. EPA explicitly described its 2023–2024 approach as relying on technologies capable of being applied directly to generating units. Supporting Information — Proposed Greenhouse Gas Standards and Guidelines for Fossil Fuel-Fired Power Plants — U.S. EPA
The present administration is therefore advancing beyond the proposition established by West Virginia. The Court said, in substance, that the Clean Power Plan had exceeded the authority Congress clearly delegated for that extraordinary regulatory mechanism; the current EPA proposal asks whether §111 should be interpreted as not authorizing fossil-power GHG regulation for global climate purposes in the first place. Those propositions are legally different, and the latter has not yet been resolved by the courts.
Legal significance of the principal precedents and administrative actions
| Instrument or case | What it established | What it did not establish | Relevance in 2026 |
|---|---|---|---|
| Clean Air Act §111 | Statutory framework for standards of performance for stationary sources | Does not itself specify a particular power-sector GHG technology | Remains controlling statute |
| 2015 Clean Power Plan | EPA attempted §111(d) generation-shifting approach | Never became durable operative architecture | Triggered major-questions litigation |
| West Virginia v. EPA (2022) | CPP generation-shifting approach lacked clear congressional authorization | Did not categorically prohibit every §111 CO₂ standard | Constrains scope of agency interpretation |
| 2024 Carbon Pollution Standards | Recast GHG regulation around source-level technologies including CCS | Did not settle judicial question of whether all BSER determinations would survive challenge | Majority of key requirements now repealed |
| Sep 2026 partial repeal | Removes major 2024 CCS/co-firing requirements | Does not eliminate every power-sector GHG standard | Operative deregulatory action |
| Sep 2026 supplemental proposal | Challenges statutory foundation for remaining power-sector GHG regulation | Not yet final law or binding judicial interpretation | Potentially much more durable structural change |
Sources: 42 U.S.C. §7411 — United States Code; West Virginia v. EPA — Supreme Court — 2022; EPA Power-Plant GHG Rule History.
The February 2026 Endangerment Finding rescission is related but does not mechanically extinguish §111
A second source of possible analytical confusion concerns EPA's February 2026 rescission of the 2009 Greenhouse Gas Endangerment Finding, because that decision concerned a statutory finding originally made under Clean Air Act §202(a) in connection with emissions from motor vehicles and engines. EPA states that its February action eliminated the prerequisite it considered necessary for federal motor-vehicle GHG standards and consequently repealed those vehicle standards. Final Rule: Rescission of the Greenhouse Gas Endangerment Finding and Motor Vehicle Greenhouse Gas Emission Standards — U.S. EPA — Feb 2026
The power-sector question arises under §111 and therefore requires its own legal analysis. EPA's September proposal draws upon the administration's broader interpretation of the Clean Air Act after the vehicle-rule rescission, but the February action did not automatically delete power-plant §111 standards from the Code of Federal Regulations. This is precisely why EPA is now conducting a separate stationary-source rulemaking rather than treating the rescission of the §202(a) finding as self-executing across the entire statute.
The distinction can be expressed institutionally:
| Regulatory field | Clean Air Act provision | February 2026 effect | September 2026 status |
|---|---|---|---|
| Motor vehicles and engines | §202(a) | Endangerment Finding rescinded; GHG standards repealed | Final EPA action |
| New fossil power sources | §111(b) | Not automatically eliminated | Partial repeal plus remaining standards and supplemental proposal |
| Existing fossil power sources | §111(d) | Not automatically eliminated | Major 2024 guidelines repealed |
| Facility GHG reporting | CAA reporting authorities / 40 CFR Part 98 | Not automatically eliminated | Separate reconsideration proceeding |
| Conventional power-plant pollutants | Multiple provisions including §§111 and 112 | Not abolished by GHG action | Governed by separate pollutant-specific rules |
Sources: EPA Final Endangerment Finding Rescission; EPA Power-Plant GHG Rulemaking.
Measurement survives regulation because the United States built several overlapping emissions-data systems
A particularly important consequence for carbon markets, investors and trade policy is that eliminating an emission limit does not necessarily eliminate the underlying ability to measure emissions. US electric generators have long been subject to monitoring obligations that arose for purposes other than greenhouse-gas performance regulation, including the Acid Rain Program and related power-sector programmes, while the Greenhouse Gas Reporting Program subsequently created an additional facility-level reporting layer.
EPA's current Subpart D guidance states that the electricity-generation category under 40 CFR §§98.40–98.48 includes electric generating units subject to the Acid Rain Program and EGUs otherwise required to monitor and report CO₂ year-round under 40 CFR Part 75. Those facilities report annual mass emissions of CO₂, CH₄ and N₂O for qualifying electricity-generating units. Subpart D Information Sheet — U.S. EPA
This produces an important institutional layering that is often lost in public discussion:
United States power-sector carbon-data architecture
| Data or regulatory system | Principal purpose | CO₂ information | Current relevance |
|---|---|---|---|
| 40 CFR Part 75 monitoring | Continuous emissions monitoring and power-sector compliance infrastructure | CO₂ monitoring/reporting for covered EGUs | Remains important independently of CCS regulation |
| GHGRP Subpart D, 40 CFR 98.40–98.48 | Annual facility GHG inventory reporting | CO₂, CH₄ and N₂O mass emissions | Formally operative as of 19 Sep 2026, although major repeal proposal is pending |
| e-GGRT | Electronic submission system for GHGRP | Facility-level electronic GHG reports | Operational; 2025 reporting deadline extended |
| §111 NSPS / emission guidelines | Controls emission performance | Uses CO₂ rates as compliance metric | Major 2024 elements repealed; residual standards remain |
| State carbon markets | State-level emissions pricing/compliance | Allowance-based CO₂e accounting | Legally independent of federal §111 rollback |
| EIA energy/emissions statistics | Federal energy statistics and national analytical series | Sector and fuel CO₂ series | Continues independently of §111 |
Sources: Subpart D — Electricity Generation — U.S. EPA; e-GGRT — U.S. EPA; Greenhouse Gas Reporting Program — U.S. EPA.
The immediate implication is that there is no technical discontinuity on 14 September 2026 in the ability of covered US generating units to quantify CO₂ emissions. The regulatory obligation to prevent or capture a specified quantity of those emissions and the administrative obligation to measure or report them are legally different. This distinction becomes increasingly important if American industrial exporters must provide carbon-intensity evidence to European counterparties even while domestic federal GHG-control obligations are reduced.
The Greenhouse Gas Reporting Program is nevertheless facing a separate and potentially systemic contraction
The durability of the American measurement infrastructure cannot be assumed, because EPA proposed on 12 September 2025 to permanently eliminate GHGRP obligations for 46 source categories, while adopting a separate approach for portions of the petroleum and natural-gas sector. EPA's rulemaking page states that the proposed change would reconsider reporting requirements for all non-Subpart-W categories and natural-gas distribution and suspend reporting for the remaining Subpart-W segments until 2034. Rulemaking Notices for GHG Reporting — U.S. EPA
EPA had not finalized that substantive proposal by 19 September 2026. Instead, on 25 February 2026 the Administrator signed a rule extending the Reporting Year 2025 filing deadline, eventually establishing 30 October 2026 as the deadline while leaving the substantive reconsideration unresolved. EPA's own prepublication rule explains that the agency proposed to remove obligations after Reporting Year 2024 for the 46 covered source categories but that the February final action addressed only the deadline, not the substantive repeal. Reporting Year 2025 Deadline Extension — U.S. EPA — Feb 2026
GHGRP status matrix as of 19 September 2026
| Issue | Current status | Date | Analytical consequence |
|---|---|---|---|
| Existing Part 98 structure | Still codified | Sep 2026 | Reporting architecture has not yet disappeared |
| Proposal affecting 46 source categories | Pending | Proposed Sep 2025 | Could sharply contract facility-level federal GHG reporting |
| Natural-gas distribution reporting | Proposed permanent removal | Sep 2025 proposal | Would reduce reporting coverage |
| Other Subpart W segments | Proposed suspension until RY2034 | Sep 2025 proposal | Creates multi-year reporting gap if finalized |
| RY2025 ordinary deadline | Modified | Originally Mar 31, 2026 | Original reporting schedule displaced |
| Current RY2025 deadline | 30 Oct 2026 | Final deadline extension | Immediate compliance date still exists |
| EPA final substantive reconsideration | Not yet issued | As of Sep 19, 2026 | Ultimate post-2024 data continuity remains unresolved |
Sources: Rulemaking Notices for GHG Reporting — U.S. EPA; e-GGRT News — U.S. EPA.
The strategic importance of this separate proceeding exceeds environmental compliance alone. If the GHGRP is substantially reduced, public authorities, investors, universities, counterparties and foreign regulators may retain other sources of emissions information, but they would lose part of a standardised federal facility-level dataset constructed under common reporting rules. That outcome would not make carbon emissions physically impossible to calculate, because fuel consumption, continuous monitoring and engineering emission factors remain available in many contexts, but it could shift a larger portion of verification toward company-specific disclosures, state reporting systems, contractual assurance, private certification and foreign-import documentation.
Part 75 creates an important residual monitoring capability that the §111 repeal does not eliminate
The power sector differs from many industrial sectors because parts of its emissions-monitoring architecture predate the federal climate-regulation debate. EPA's Acid Rain Program and related trading programmes require affected generating units to measure and submit emissions information under 40 CFR Part 75, and EPA's 2026 power-sector calendar continues to list quarterly emissions-reporting periods and compliance functions for the Acid Rain Program and Cross-State Air Pollution Rule programmes. Key Program Dates & Contacts — U.S. EPA — 2026
Consequently, even a substantial contraction of Part 98 would not necessarily produce a total observational blackout for the electric sector, although the scope, pollutants, reporting purpose, aggregation rules and public accessibility of the surviving datasets would not be identical to the GHGRP. From a governance perspective, this is crucial: regulatory deregulation can proceed more rapidly than measurement deregulation because monitoring systems are embedded in multiple programmes with different statutory purposes.
Conventional pollutants remain governed by separate statutes and rules
The September GHG action also does not make coal and gas plants environmentally unregulated in the broader sense, because carbon dioxide is only one of the pollutants addressed by the Clean Air Act. Mercury and other hazardous air pollutants, sulfur dioxide, nitrogen oxides and particulate matter are governed through separate statutory and regulatory structures, and EPA would need distinct rulemakings to alter those requirements.
EPA already completed one such separate deregulatory action in February 2026 by repealing the 2024 amendments to the Mercury and Air Toxics Standards, but the agency explicitly stated that the earlier MATS requirements remained in force. According to EPA's description, the February rule removed the tighter filterable particulate-matter standard, the strengthened mercury limit for lignite units and the requirement to use particulate-matter continuous-emission monitoring systems introduced in 2024; it did not abolish the underlying MATS regime itself. Mercury and Air Toxics Standards — U.S. EPA
This means that a coal plant affected by the September CO₂ repeal can simultaneously experience substantially weaker federal greenhouse-gas obligations while remaining subject to other pollution-control requirements. Regulatory exposure must therefore be analysed pollutant by pollutant rather than described as a binary condition in which a plant is either “regulated” or “unregulated.”
A future administration would face a higher rebuilding burden, but not an absolute legal prohibition unless the courts establish one
A central long-term issue is whether the September initiative can prevent a future administration from restoring federal power-sector greenhouse-gas controls. The legally defensible answer is more nuanced than either an automatic yes or no.
A future EPA generally retains authority to reconsider an earlier agency interpretation through notice-and-comment rulemaking, but it must operate within the statutory text, applicable judicial precedent and administrative-law requirements governing reasoned decision-making. If the present EPA finalizes its supplemental interpretation and that interpretation survives judicial review, a later administration seeking to reverse course would have to explain why the statute should be interpreted differently, develop an administrative record supporting that new interpretation and construct standards that remain within the limitations established by West Virginia v. EPA and any later Supreme Court precedent.
The greater structural risk for future regulation therefore arises not merely from repeal of the 2024 numerical standards, which another administration could theoretically replace, but from the possibility that litigation over the 2026 action produces an appellate or Supreme Court ruling accepting a restrictive interpretation of §111's threshold authority. Agency regulations can be reconsidered; a controlling Supreme Court interpretation of the statute can ordinarily be displaced only by a later Court decision or by Congress changing the law.
Durability hierarchy of the 2026 rollback
| Layer of change | Ease of reversal by future administration | Principal requirement for reversal | Durability if upheld |
|---|---|---|---|
| Guidance or enforcement priority | Relatively high | New agency policy | Low |
| Technical BSER determination | Moderate | New technical record and rulemaking | Medium |
| Repealed emission guideline | Moderate | New §111 rule satisfying APA and statutory requirements | Medium |
| Formal statutory interpretation by EPA | More difficult | New interpretation with reasoned justification | Medium-high |
| D.C. Circuit interpretation | Difficult | Further judicial review or later precedent | High |
| Supreme Court statutory holding | Very difficult administratively | Congressional amendment or later Supreme Court reconsideration | Very high |
| Congressional amendment removing/clarifying authority | Cannot be reversed by EPA | New legislation | Highest institutional durability |
The table does not assign probabilities to future litigation outcomes because no defensible quantitative base rate exists for the specific statutory dispute now being created; it instead identifies the institutional hierarchy that will determine reversibility.
The administration's strategy therefore shifts the dispute from technology to statutory competence
The trajectory from 2015 through 2026 reveals a progressive movement in the locus of legal conflict. The Obama-era Clean Power Plan generated a dispute over whether EPA could treat changes in the electricity-generation mix as the relevant “system” of emission reduction; West Virginia rejected that approach. The Biden administration then attempted to move BSER back toward technologies applied at regulated generating units, particularly CCS and co-firing. The Trump administration's September 2026 action first attacks the technical and economic adequacy of those 2024 BSER determinations and then, in the supplemental proposal, advances a more fundamental argument that the climate-related statutory threshold itself is not met in a way that authorizes the remaining power-sector GHG regime.
Evolution of the federal legal dispute
| Period | Principal regulatory question | Federal approach | Core vulnerability |
|---|---|---|---|
| 2015 Clean Power Plan | Can BSER encompass system-wide generation shifting? | Yes | Supreme Court ultimately rejected this interpretation |
| 2019 ACE Rule | Must BSER remain more tightly source-focused? | EPA adopted narrower approach | Subsequently displaced administratively |
| 2022 West Virginia | Did Congress clearly authorize CPP's transformative generation-shifting structure? | Supreme Court: no | Major-questions constraint |
| 2024 Carbon Pollution Standards | Can source-level CCS/co-firing support deep CO₂ standards? | EPA: yes | Adequate demonstration, cost, feasibility and statutory challenges |
| 2026 partial repeal | Were key 2024 BSER determinations lawful and reasonable? | Current EPA: no for principal CCS/co-firing provisions | Judicial review pending |
| 2026 supplemental proposal | Does §111 authorize regulation of fossil-power GHG emissions for global climate concerns? | Current EPA proposes no | Potentially decisive statutory litigation |
Sources: West Virginia v. EPA — Supreme Court — Jun 2022; Supporting Information — Final Carbon Pollution Standards — U.S. EPA — Apr 2024; Greenhouse Gas Standards and Guidelines for Fossil Fuel-Fired Power Plants — U.S. EPA — Sep 2026.
Carbon accounting is consequently becoming detached from federal carbon-control policy
The deeper institutional consequence is that the United States can move toward a system in which CO₂ remains measurable, commercially relevant and internationally consequential even while federal requirements to reduce it are substantially weakened. The variable itself does not disappear because electric utilities still consume measurable quantities of fossil fuel, many generating units continuously measure emissions or operating parameters, corporate counterparties demand environmental data, states may retain their own reporting or carbon-market requirements, and foreign jurisdictions increasingly demand embedded-emissions information from importers.
This creates a regulatory asymmetry with practical consequences for large American companies. A generator or industrial facility can face little or no federal obligation to purchase carbon allowances or install CCS while nevertheless having to calculate emissions for a state programme, an investor disclosure, a supply-chain contract, a European CBAM importer or a multinational customer's internal carbon-accounting system. The September rule therefore separates domestic federal control of emissions from the increasingly internationalised economic accounting of emissions.
For internationally exposed industries, this distinction matters considerably more than whether Washington uses the phrase “carbon tax.” An American producer exporting a carbon-intensive product into a jurisdiction that calculates embedded emissions will continue to have an economic interest in demonstrating an accurate emissions intensity regardless of whether EPA requires that producer's electricity supplier to capture CO₂.
The institutional map after the September decision is therefore fragmented rather than empty
The resulting US governance model contains at least five overlapping layers: federal pollution regulation, federal emissions measurement, state environmental regulation, state carbon-pricing mechanisms, and external carbon-accounting requirements imposed by trading partners. The Trump administration can substantially reduce the first and may reduce the second, but it does not directly control the remaining three.
Carbon governance after the federal power-sector rollback
| Governance layer | Federal September action controls it directly? | Can it survive repeal of §111 power-plant GHG standards? | Principal authority |
|---|---|---|---|
| Federal CO₂ performance standards for power plants | Yes | Only residual standards unless further rulemaking changes them | EPA / CAA §111 |
| Federal GHGRP facility reporting | No, separate proceeding | Yes, unless separate repeal is finalized | EPA / 40 CFR Part 98 |
| Part 75 power-sector emissions monitoring | No | Yes | EPA / separate CAA programmes |
| State emission standards | No | Potentially | State law within federal constitutional/statutory limits |
| State carbon markets | No | Yes | State statutes and regulations |
| Corporate voluntary carbon accounting | No | Yes | Private governance |
| Foreign border-carbon reporting | No | Yes | Foreign sovereign law |
| Foreign carbon-price liability | No | Yes | EU, UK or other importing jurisdiction |
The principal conceptual error to avoid is therefore equating the repeal of federal GHG performance requirements with the abolition of the carbon-accounting ecosystem. The former has occurred to a large extent; the latter has not.
Key judgments
The September 2026 action has already removed the most consequential 2024 federal decarbonisation requirements for existing coal and new baseload gas generation, especially the standards built around 90% CCS and the medium-term coal pathway built around 40% natural-gas co-firing, meaning that utilities no longer need to organise their investment programmes around those specific federal obligations once the repeal becomes legally operative and survives any court intervention. Partial Repeal of the Carbon Pollution Standards — U.S. EPA — Sep 2026
The more consequential long-term question remains unresolved because EPA has not yet finalized its supplemental theory that §111 does not authorize the remaining regulation of fossil-fuel power-plant greenhouse gases on the basis of global climate change, making the next final rule and subsequent judicial review more important to institutional durability than the removal of any single numerical emissions rate. Greenhouse Gas Standards and Guidelines for Fossil Fuel-Fired Power Plants — U.S. EPA — Sep 2026
West Virginia v. EPA materially restricts the methods EPA may employ, particularly where an agency interpretation claims broad authority to restructure the electricity system without clear congressional authorization, but the 2022 decision did not itself hold that §111 can never regulate power-sector CO₂; the administration's 2026 supplemental proposal therefore asks the courts eventually to confront a broader statutory question than the one decided in West Virginia. West Virginia v. EPA — Supreme Court of the United States — Jun 2022
Carbon measurement remains institutionally separate from carbon regulation, because Subpart D of the GHGRP and Part 75-based monitoring continue to provide emissions information for covered generating units, although the separate proposal to eliminate GHGRP obligations for 46 source categories creates a material possibility that the federal facility-level greenhouse-gas data system will become substantially narrower. Subpart D Information Sheet — U.S. EPA Rulemaking Notices for GHG Reporting — U.S. EPA
The institutional endpoint is therefore not an American economy in which carbon ceases to be measured or economically relevant, but one in which federal emission control, federal reporting, state policy and international carbon accounting increasingly diverge, creating a substantially more fragmented governance structure than either the Obama-era Clean Power Plan or the Biden-era 2024 standards contemplated.
What would change the assessment
The assessment would become materially more restrictive concerning EPA's future authority if the agency finalizes the supplemental September proposal and federal appellate courts subsequently hold that §111 does not authorize the challenged category of power-sector GHG regulation, because the barrier would then move from a reversible administrative interpretation toward controlling judicial precedent.
The assessment would move in the opposite direction if a court vacates the partial repeal for failure to comply with the Administrative Procedure Act, rejects EPA's interpretation of the BSER requirements, or concludes that the agency has inadequately justified abandonment of its earlier technical findings regarding CCS and other control systems.
The assessment of US carbon-data continuity would deteriorate significantly if EPA finalizes the proposed elimination of reporting requirements for the 46 GHGRP source categories without substituting an equivalent federal reporting architecture, particularly if electricity-generation reporting is removed while international demand for installation-level carbon data continues to increase.
The assessment of practical deregulation would also require revision if state governments or regional programmes replace a significant portion of the federal requirements through enforceable state standards or carbon-price mechanisms, because federal withdrawal does not by itself pre-empt every form of state climate regulation.
Open official record
The most important unresolved official record is the final Federal Register publication of the September partial repeal and the precise effective date and litigation posture that follow publication; EPA's 14 September document available during this review remains identified by the agency as a signed prepublication version. Partial Repeal of the Carbon Pollution Standards — U.S. EPA — Sep 2026
The second unresolved record is the final disposition of the supplemental proposal addressing EPA's underlying §111 authority, including whether the agency ultimately relies principally on the interpretation of “air pollution which may reasonably be anticipated to endanger public health or welfare,” the “significant contribution” threshold, a combination of the two, or another rationale emerging from the administrative record.
The third is the final substantive action on the GHGRP reconsideration, because EPA has extended the Reporting Year 2025 deadline to 30 October 2026 without yet deciding the proposed removal of reporting obligations across the 46 source categories. Rulemaking Notices for GHG Reporting — U.S. EPA
The fourth is the judicial record that will emerge from challenges to the September actions, including any petitions for review, requests for stays, D.C. Circuit judgments and potential Supreme Court proceedings; until those instruments exist, claims that the administration has permanently eliminated a future president's ability to regulate power-sector CO₂ would go beyond the verified legal record.
Pillar Two — Electricity economics, coal and gas dispatch, carbon capture and the distribution of regulatory costs
Principal judgment
The economic significance of the September 2026 repeal lies less in an immediate fall in electricity prices than in a re-ordering of the investment and dispatch economics of the US power system, because EPA’s own modelling indicates that the largest effects emerge after 2030, when the repealed 2024 standards would otherwise have forced a substantial portion of the coal fleet either to install carbon capture, co-fire with natural gas, convert fuel or retire, while new baseload gas capacity would have faced increasingly stringent carbon-capture requirements. Under EPA’s final-repeal scenario, coal generation remains materially higher for much longer, coal retirements are deferred, fewer renewable and storage additions are required in the model, natural-gas consumption falls in some years because retained coal displaces gas-fired generation, and the federal tax expenditures associated with §45Q carbon sequestration credits decline sharply because much less CCS is installed. Regulatory Impact Analysis for the Final Partial Repeal of the Carbon Pollution Standards for Fossil Fuel-Fired Electric Generating Units — U.S. EPA — Sep 2026
EPA estimates $160 billion in present-value power-sector compliance-cost savings between 2026 and 2047 using a 3% discount rate, or $95 billion at 7%, whereas its transfer-adjusted estimate of avoided real-resource costs is considerably larger, at $280 billion at 3% and $180 billion at 7%. Those numbers cannot be treated interchangeably, because the first measures expenditures avoided by firms after accounting for taxes and subsidies, while the second attempts to measure actual resources—capital, labour, fuel, equipment, transport and storage—that society would no longer devote to compliance; tax credits such as §45Q are transfers rather than disappearing economic resources, which is why removing them from the calculation produces a different result. Regulatory Impact Analysis — U.S. EPA — Sep 2026
The modelling therefore identifies a real economic trade-off rather than a one-dimensional “deregulation dividend”: utilities and electricity consumers avoid large prospective capital and operating expenditures, while coal producers and existing fossil-generation owners retain substantially more economic activity; however, EPA simultaneously projects higher CO₂: Carbon dioxide, NOₓ: Nitrogen oxides (a general term for various nitrogen oxides, primarily nitric oxide and nitrogen dioxide), SO₂: Sulfur dioxide, mercury and, in later years, primary PM₂.₅ emissions, while the agency’s economy-wide model does not monetise the welfare effects associated with changes in environmental quality. For policy analysis, the $310 billion figure cited publicly by EPA must consequently be understood as an agency estimate constructed from compliance and broader economic modelling rather than as a verified cash saving already accruing to consumers or an economy-wide net welfare gain. EPA Finalizes Repeal of 2024 Power Plant Regulations — U.S. EPA — Sep 2026
The central economic change is the value of keeping existing coal capacity alive
The most striking effect in EPA’s Integrated Planning Model is not a large expansion in total electricity generation, which changes very little between the baseline and repeal scenarios, but a substantial change in which assets generate that electricity. Total national generation in the two scenarios remains almost identical in the principal model years, yet the composition diverges sharply because the 2024 standards would have pushed large quantities of coal generation toward CCS-equipped operation, gas co-firing, conversion or retirement, whereas repeal allows conventional coal capacity to continue dispatching without incurring those particular federal GHG-compliance costs. Regulatory Impact Analysis — U.S. EPA — Sep 2026
The result is visible first in fuel use: EPA projects total power-sector coal consumption at 398 million tons in 2030 under repeal compared with 383 million tons under the CPS baseline, widening to 392 versus 266 million tons in 2035, 385 versus 244 million tons in 2040, and 291 versus only 15 million tons in 2045. The extremely large percentage differences in 2045 reflect the collapse of unabated coal use in the regulatory baseline rather than a comparable multiplication relative to today's coal market, which is why the absolute tonnage is analytically more useful than the headline percentage. Regulatory Impact Analysis — Table 3-8 — U.S. EPA — Sep 2026
EPA projection of US power-sector coal consumption
| Year | Baseline with 2024 CPS | Final repeal | Absolute difference | EPA percentage difference |
|---|---|---|---|---|
| 2030 | 383 Mt | 398 Mt | +15 Mt | +4% |
| 2035 | 266 Mt | 392 Mt | +126 Mt | +48% |
| 2040 | 244 Mt | 385 Mt | +141 Mt | +58% |
| 2045 | 15 Mt | 291 Mt | +276 Mt | +1,832% |
Source: calculated from EPA Table 3-8; the very large 2045 percentage is generated by the very small 15-million-ton baseline rather than by a nineteen-fold increase from current coal consumption. Regulatory Impact Analysis — U.S. EPA — Sep 2026
The regional distribution is also material because the largest absolute response occurs in western coal supply. EPA projects western coal consumption rising from 169 to 267 million tons in 2035 and from 154 to 266 million tons in 2040 relative to the CPS baseline, while Interior Basin production rises from 41 to 57 million tons in 2035 and from 35 to 53 million tons in 2040. Appalachia also benefits from the altered dispatch structure, although the percentage effects are smaller than in the West. These results imply that the repeal redistributes economic value geographically toward coal-mining regions, rail and logistics systems serving those mines, existing coal generators and associated maintenance chains, rather than spreading the benefit uniformly across the US economy. Regulatory Impact Analysis — Table 3-8 — U.S. EPA — Sep 2026
Coal prices rise even though electricity prices are projected to fall
One of the most important results for interpreting the EPA model is that coal becomes more expensive under the repeal scenario even while average electricity prices generally become lower after 2030, because the repeal materially increases demand for coal while simultaneously avoiding much larger regulatory capital and operating expenditures elsewhere in the power system.
EPA projects the average delivered coal price rising from $2.15/MMBtu to $2.24/MMBtu in 2030, from $2.08 to $2.30 in 2035, from $2.16 to $2.38 in 2040, and from $1.88 to $2.39 in 2045, all expressed in 2024 dollars. The corresponding percentage increases are approximately 4%, 10%, 10% and 27%, respectively. Regulatory Impact Analysis — Tables 3-10 and 3-18 — U.S. EPA — Sep 2026
Coal-price transmission under the repeal scenario
| Year | Delivered coal price with CPS | Delivered coal price after repeal | Change |
|---|---|---|---|
| 2030 | $2.15/MMBtu | $2.24/MMBtu | +4% |
| 2035 | $2.08/MMBtu | $2.30/MMBtu | +10% |
| 2040 | $2.16/MMBtu | $2.38/MMBtu | +10% |
| 2045 | $1.88/MMBtu | $2.39/MMBtu | +27% |
Source: EPA IPM projections in constant 2024 dollars. Regulatory Impact Analysis — U.S. EPA — Sep 2026
This result illustrates who captures part of the economic surplus generated by repeal: some of the avoided regulatory cost is transferred into higher demand for coal and consequently higher mine-mouth and delivered coal prices, meaning that coal producers and the coal transport chain receive part of the economic benefit rather than electricity consumers capturing the full theoretical compliance saving. EPA's own model therefore does not support the proposition that every dollar of avoided compliance expenditure becomes a dollar of lower electricity bills.
Natural gas does not simply replace coal; in important years the opposite occurs
The interaction with natural gas is more complex than the assumption that weakening carbon rules automatically means more gas-fired generation. In EPA’s CPS baseline, significant coal retirement and fuel switching create additional demand for natural gas, while restrictions on new high-utilisation gas turbines affect the utilisation of existing NGCC units; under repeal, more coal remains on the system, which in several model years reduces gas consumption and gas prices relative to the regulated baseline.
EPA projects power-sector natural-gas consumption at 14.4 trillion cubic feet in 2030 under repeal compared with 14.6 Tcf under the CPS baseline, 16.4 versus 18.0 Tcf in 2035, 14.7 versus 14.4 Tcf in 2040, and 11.8 versus 12.2 Tcf in 2045. The largest divergence occurs in 2035, when repeal reduces power-sector gas demand by approximately 1.6 Tcf, or 8.9%, because retained coal generation displaces part of the gas generation that would otherwise substitute for constrained coal. Regulatory Impact Analysis — Table 3-9 — U.S. EPA — Sep 2026
EPA projection of power-sector natural-gas use
| Year | CPS baseline | Repeal | Difference | Percentage change |
|---|---|---|---|---|
| 2030 | 14.6 Tcf | 14.4 Tcf | −0.2 Tcf | −1.6% |
| 2035 | 18.0 Tcf | 16.4 Tcf | −1.6 Tcf | −8.9% |
| 2040 | 14.4 Tcf | 14.7 Tcf | +0.3 Tcf | +1.9% |
| 2045 | 12.2 Tcf | 11.8 Tcf | −0.4 Tcf | −3.1% |
Source: EPA Table 3-9. Regulatory Impact Analysis — U.S. EPA — Sep 2026
The gas-price consequences follow the same mechanism. EPA projects Henry Hub prices approximately 2% lower in 2030, 8% lower in 2035, around 1% higher in 2040, and 2% lower in 2045 under repeal, while delivered gas prices to the power sector move broadly in parallel. In 2035, the model places the delivered natural-gas price at $5.23/MMBtu after repeal instead of $5.72/MMBtu under the CPS baseline, a difference of roughly $0.49/MMBtu in 2024 dollars. Regulatory Impact Analysis — Table 3-11 — U.S. EPA — Sep 2026
This mechanism matters well beyond electricity because lower Henry Hub prices, if realised, can transmit into industrial feedstock costs, commercial and residential gas prices and LNG economics, although EPA's model does not establish a uniform downstream saving for each sector. The historical evidence confirms why this channel is economically relevant: EIA reports that natural gas commonly sets the marginal wholesale electricity price in US organised markets, while the Henry Hub benchmark averaged $3.52/MMBtu in 2025, 56% above 2024, contributing to higher wholesale electricity prices and helping produce an 11% rise in coal-fired generation as generators substituted away from more expensive gas. U.S. Wholesale Day-Ahead Electricity Prices Rose in 2025 with Higher Natural Gas Prices — U.S. Energy Information Administration — Feb 2026
The EPA repeal therefore changes not only environmental compliance but the relative demand curves of two major US fuels: in the medium term, the model allocates a greater share of generation to coal, thereby reducing gas demand sufficiently to depress gas prices relative to the regulated baseline, while in later years growth in total electricity demand and the changing capital stock produce a more mixed result.
Generation changes much more than total electricity demand
EPA's modelling keeps aggregate electricity demand broadly similar across the two policy cases, so the principal difference emerges in generation composition rather than total production. In 2035, conventional coal generation rises from only 43 TWh under the CPS baseline to 563 TWh after repeal, while coal generation equipped with CCS falls from 299 to 103 TWh, natural-gas generation edges down from 2,488 to 2,469 TWh, and non-hydro renewable generation falls from 2,011 to 1,778 TWh. By 2040, conventional coal generation reaches 553 TWh under repeal against 5 TWh in the baseline, natural-gas generation rises from 2,106 to 2,279 TWh, and non-hydro renewable generation is 2,515 TWh rather than 3,007 TWh. Regulatory Impact Analysis — Table 3-12 — U.S. EPA — Sep 2026
How EPA’s generation mix changes under repeal
| Generation category | 2035 CPS | 2035 repeal | Difference | 2040 CPS | 2040 repeal | Difference |
|---|---|---|---|---|---|---|
| Conventional coal | 43 TWh | 563 TWh | +520 | 5 TWh | 553 TWh | +548 |
| Coal + CCS | 299 TWh | 103 TWh | −196 | 299 TWh | 103 TWh | −196 |
| Natural gas | 2,488 TWh | 2,469 TWh | −19 | 2,106 TWh | 2,279 TWh | +173 |
| Natural gas + CCS | 65 TWh | 45 TWh | −20 | 65 TWh | 45 TWh | −20 |
| Non-hydro renewables | 2,011 TWh | 1,778 TWh | −233 | 3,007 TWh | 2,515 TWh | −492 |
| Nuclear | 675 TWh | 675 TWh | 0 | 638 TWh | 638 TWh | 0 |
| Total generation | 5,968 TWh | 5,985 TWh | +17 | 6,495 TWh | 6,503 TWh | +8 |
Source: EPA Table 3-12; differences calculated from published values and therefore subject to rounding. Regulatory Impact Analysis — U.S. EPA — Sep 2026
The economic implication is that the repeal changes the marginal investment need of the system: generation that the CPS baseline would have replaced with renewable capacity, new gas capacity or CCS-equipped generation remains available from existing conventional coal units, reducing the amount of replacement capital required to satisfy the same electricity demand. This is one of the main mechanisms through which the model generates cost savings.
The repeal extends the economic life of tens of gigawatts of coal capacity
EPA's capacity results reveal the same effect more directly. Under its baseline containing the 2024 standards, total coal capacity falls from 124 GW in 2030 to approximately 3 GW by 2045 when conventional coal, coal with CCS and gas-cofiring categories are combined; under repeal, approximately 127 GW remains in 2030 and roughly 85 GW remains by 2045. EPA states that repeal results in approximately 1 GW of avoided coal retirements by 2030, 32 GW by 2035, 41 GW by 2040 and 68 GW by 2045 relative to the regulated baseline. Regulatory Impact Analysis — U.S. EPA — Sep 2026
The 2035 compliance choices modelled under the CPS demonstrate why the capacity effect becomes so large: EPA's baseline assumes that approximately 44 GW of coal capacity installs CCS, 9 GW co-fires with natural gas, 6 GW converts to gas, and 68 GW retires in response to the regulatory and market conditions represented in the model. Those investments are no longer required under the repeal scenario, producing a very different capital-stock trajectory. Regulatory Impact Analysis — U.S. EPA — Sep 2026
Coal-capacity effects of repeal
| Model year | Avoided coal retirements relative to CPS | Approximate significance |
|---|---|---|
| 2030 | +1 GW | Limited near-term effect |
| 2035 | +32 GW | Major divergence begins |
| 2040 | +41 GW | Coal remains structurally relevant |
| 2045 | +68 GW | Fundamental difference from near-elimination in CPS baseline |
Source: EPA RIA. Regulatory Impact Analysis — U.S. EPA — Sep 2026
The distinction between avoided retirement and new investment is crucial. EPA is not forecasting construction of an entirely new 68-GW coal fleet; it is forecasting that existing capacity which would otherwise have retired in the CPS baseline remains economically available under the repeal scenario. That means much of the financial advantage comes from extending sunk assets rather than constructing new coal plants, which materially changes the capital economics because an operating plant whose original construction cost is largely sunk can compete on fuel, maintenance and incremental capital expenditure even when a new-build coal project would not be financially attractive.
The renewable effect is an investment displacement effect, not a regulatory prohibition
EPA also projects substantially less new renewable capacity under repeal, not because the September rule restricts renewable generation but because retention of fossil capacity reduces the amount of replacement generation needed to meet the same demand and resource-adequacy requirements. By 2035, the final-repeal scenario contains 87 GW fewer renewable additions than the CPS baseline, comprising approximately 79 GW less solar and 8 GW less wind, together with roughly 2 GW less storage. EPA projects non-hydro renewable capacity at 616 GW under repeal versus 704 GW under the baseline in 2035, widening to 850 versus 1,008 GW in 2040 and 1,153 versus 1,325 GW in 2045. Regulatory Impact Analysis — U.S. EPA — Sep 2026
Renewable and fossil capacity effects
| Year | Non-hydro renewable capacity with CPS | Repeal | Difference | Natural-gas capacity with CPS | Repeal | Difference |
|---|---|---|---|---|---|---|
| 2030 | 432 GW | 428 GW | −4 GW | 542 GW | 524 GW | −18 GW |
| 2035 | 704 GW | 616 GW | −88 GW | 642 GW | 627 GW | −15 GW |
| 2040 | 1,008 GW | 850 GW | −158 GW | 717 GW | 691 GW | −26 GW |
| 2045 | 1,325 GW | 1,153 GW | −172 GW | 817 GW | 751 GW | −66 GW |
Source: EPA Table 3-13; natural-gas values exclude the separately listed gas-with-CCS category. Regulatory Impact Analysis — U.S. EPA — Sep 2026
The implication is economically important because part of the repeal's projected saving derives from not building assets that the CPS baseline would induce. That effect lowers near- and medium-term capital requirements but also changes the future composition of the generation fleet, leaving the system with more existing fossil capacity and less renewable capacity than under the regulated counterfactual.
CCS economics change from mandatory compliance investment to optional subsidised investment
The most direct capital effect concerns carbon capture and storage. Under the 2024 rule, qualifying long-lived coal units and certain new baseload gas units would eventually have needed to achieve emission rates premised on approximately 90% capture, converting CCS from an optional technology into a compliance pathway for facilities choosing to remain in those regulatory categories. Repeal removes that compulsory demand.
EPA's modelling shows the scale of the response. In 2035, the CPS baseline contains 44 GW of coal capacity equipped with CCS, compared with only 15 GW under repeal, while new natural-gas capacity with CCS falls from 9 to 6 GW. EPA separately states that new NGCC additions are identical at 154 GW by 2035 in the two scenarios, but only 4 GW of new NGCC installs CCS after repeal versus 7 GW under the baseline. Regulatory Impact Analysis — U.S. EPA — Sep 2026
CCS deployment implied by EPA's model
| Technology | 2035 CPS baseline | 2035 repeal | Change |
|---|---|---|---|
| Coal capacity with CCS | 44 GW | 15 GW | −29 GW |
| Natural gas capacity with CCS | 9 GW | 6 GW | −3 GW |
| New NGCC additions receiving CCS, EPA narrative | 7 GW | 4 GW | −3 GW |
| Coal generation with CCS | 299 TWh | 103 TWh | −196 TWh |
| Gas generation with CCS | 65 TWh | 45 TWh | −20 TWh |
Sources: EPA Tables 3-12 and 3-13. Regulatory Impact Analysis — U.S. EPA — Sep 2026
CCS nevertheless remains economically relevant because Congress has preserved Internal Revenue Code §45Q, meaning that projects satisfying the statutory criteria can continue to receive a production-based tax credit even though EPA no longer requires CCS for the repealed power-plant categories. The IRS states that qualified electricity-generating facilities must capture at least 18,750 metric tons of qualified carbon oxide annually and that the applicable carbon-capture equipment must have design capacity equal to at least 75% of the generating unit's baseline carbon-oxide production; eligible facilities generally must begin construction before 1 January 2033. Credit for Carbon Oxide Sequestration — Internal Revenue Service — current 2026
For qualifying post-2022 equipment, the current statutory base credit is generally $17 per metric ton for captured carbon oxide under the relevant non-DAC categories after the 2025 legislative changes, and the amount can be increased fivefold where prevailing-wage and registered-apprenticeship conditions are satisfied, producing a potential $85-per-ton credit; direct-air-capture facilities have a higher statutory base rate and can reach $180 per ton under the corresponding increased-credit structure. The credit is generally available for 12 years from the date qualifying capture equipment is placed in service and is eligible for transfer or, where statutory conditions permit, direct payment. Credit for Carbon Oxide Sequestration — Internal Revenue Service — 2026 Instructions for Form 8933 — Internal Revenue Service — Dec 2025
Simplified §45Q economics for power-sector CCS
| Item | Current federal treatment |
|---|---|
| Standard qualifying point-source base credit | $17/t CO₂ under current post-July-2025 structure |
| Increased credit if prevailing-wage/apprenticeship conditions are satisfied | Up to 5 × base = $85/t CO₂ |
| Qualifying electricity-generator annual capture threshold | 18,750 t CO₂ |
| Minimum capture-design-capacity condition for generating unit | 75% of baseline CO₂ production |
| Credit period | Generally 12 years |
| Construction-start deadline for qualified facility | Before 1 Jan 2033 |
| Transferability/direct-pay mechanisms | Available subject to statutory eligibility |
Source: IRS current guidance; individual projects require application of the specific §45Q rules and tax-status conditions. Credit for Carbon Oxide Sequestration — Internal Revenue Service — 2026
The economic architecture after repeal is therefore fundamentally different: §45Q can make CCS commercially attractive in particular locations, but it no longer operates alongside an EPA rule forcing a broad class of generators toward capture. A project must instead clear a project-finance test based on capture capital cost, parasitic energy use, operating costs, pipeline distance, storage availability, injection costs, financing conditions, tax-credit monetisation and the expected operating life of the host power plant.
The capture credit can be large, but it is not equivalent to the full cost of CCS
A numerical illustration shows the scale of the incentive without assuming that it determines project viability. A power station capturing 5 million tonnes of qualifying CO₂ annually and satisfying requirements for an $85/t credit could generate a nominal §45Q tax-credit stream of approximately $425 million per year, or roughly $5.1 billion over twelve years before discounting, assuming constant qualifying capture and full credit eligibility. That calculation is simply 5 million tonnes × $85 × 12 and does not account for financing, capture availability, credit-transfer discounts, operating outages, tax restrictions, construction cost overruns, transport or storage charges.
The same calculation explains why repeal materially reduces federal tax expenditure in EPA's model. EPA estimates that the final repeal reduces projected CO₂ storage tax-credit transfers by approximately $180 billion in present value over 2026–2047 at a 3% discount rate, or about $120 billion at 7%, because considerably fewer tonnes are captured and sequestered under the repeal scenario than in the CPS counterfactual. Regulatory Impact Analysis — Table 3-7 — U.S. EPA — Sep 2026
EPA decomposition of repeal-related resource and transfer effects
| 2026–2047 present value, 2024 dollars | 3% discount rate | 7% discount rate |
|---|---|---|
| Power-sector compliance-cost change | −$160bn | −$95bn |
| Change in CO₂-storage tax-credit transfers | −$180bn | −$120bn |
| Change in clean-energy tax-credit transfers | −$0.93bn | +$0.87bn |
| Other government receipts/transfers | −$66bn | −$38bn |
| Transmission-use transfer | +$2.0bn | +$1.2bn |
| EPA calculated real-resource-cost change | −$280bn | −$180bn |
Negative values indicate reductions relative to the CPS baseline. Transfers and real-resource costs should not be added together as though they represented independent social costs. Regulatory Impact Analysis — Table 3-7 — U.S. EPA — Sep 2026
The table reveals a central distributional fact: a very large component of what the regulated power sector would have perceived as an offset to compliance expenditure under the CPS was expected to be financed through federal tax credits. Removing the regulatory obligation consequently reduces both utility expenditure and federal subsidy payments. From the perspective of the generator, that means less capital expenditure but also less tax-credit revenue; from the perspective of the federal budget, it means lower anticipated credit claims; from the perspective of resource accounting, the avoided construction, operation and energy consumption associated with CCS are treated differently from those financial transfers.
The technical cost of CCS remains highly plant-specific
The National Energy Technology Laboratory's current fossil-energy baseline explicitly models both pulverised-coal and NGCC configurations with and without carbon capture and reports levelized cost of electricity, cost of CO₂ capture and cost of CO₂ avoided as separate metrics, because a dollar-per-ton capture cost does not by itself describe the full effect on electricity cost. NETL Cost and Performance Baseline for Fossil Energy Plants — U.S. Department of Energy / NETL — current
The economics differ structurally between coal and natural gas. Coal flue gas generally contains a higher concentration of CO₂, which facilitates separation relative to dilute NGCC exhaust, while gas turbines generally have higher thermal efficiencies and lower uncontrolled CO₂ emissions per MWh; consequently, capture cost per tonne and the resulting cost of electricity need not rank the technologies in the same order. NETL therefore treats cost of capture, cost of avoided CO₂ and LCOE separately rather than reducing CCS economics to a single metric. NETL Cost and Performance Baseline for Fossil Energy Plants — U.S. DOE / NETL
Commercial deployment further requires more than the capture island. DOE describes the CCS chain as capture, compression, transportation and permanent geologic storage, with transportation potentially occurring by pipeline, truck, rail or ship and injection requiring separately permitted storage capacity. Carbon Capture Demonstration Projects Program — U.S. Department of Energy
This explains why EPA's September rule focuses heavily on infrastructure availability: the cost problem is not simply whether solvent equipment can capture 90% of the CO₂ at an individual plant, but whether a sufficiently large network of compression equipment, pipelines, injection wells, monitoring systems, pore-space rights and permitted geological storage can become available within the compliance timetable.
Demonstration experience proves technical feasibility, but not universal economic replicability
The United States already has evidence that large-scale post-combustion capture can operate on coal generation, but that evidence does not establish that every coal or gas plant can install CCS at the same cost. DOE's Petra Nova project in Texas was designed to capture approximately 90% of CO₂ from a 240-MW-equivalent flue-gas slipstream, corresponding to roughly 1.4 million metric tonnes of CO₂ annually, with the gas compressed and transported through an approximately 80-mile pipeline for enhanced oil recovery and associated geological storage. Petra Nova — W.A. Parish Project — U.S. Department of Energy
Petra Nova is therefore evidence that commercial-scale capture from coal flue gas is technically achievable, but it is not evidence that every large coal unit possesses equivalent storage access, pipeline economics, steam availability, project financing or enhanced-oil-recovery revenues. This distinction matters because EPA's 2026 repeal is based not principally on the proposition that CCS is physically impossible, but on the agency's revised judgment that the 2024 rule had not demonstrated the broad deployability and infrastructure necessary to achieve the prescribed standards across the affected fleet by the required compliance dates. Regulatory Impact Analysis — U.S. EPA — Sep 2026
Electricity-price savings emerge late and are highly regional
The politically salient claim that the repeal lowers electricity costs requires substantial qualification because EPA does not project an immediate national price decline. In 2030, the model actually produces a 0.7% increase in the national average retail price, from 134 to 135 mills/kWh in 2024 dollars, because the model selects an investment sequence that minimises discounted system costs over the full horizon rather than minimising every individual year's retail rate. EPA explicitly explains that its model assumes perfect foresight and that early investment in combustion turbines and later battery deployment can produce an initial price increase even when the discounted cost of the repeal scenario is lower over the whole period. Regulatory Impact Analysis — U.S. EPA — Sep 2026
The large projected decline occurs in 2035, when the CPS baseline assumes expensive CCS and other compliance investments have become binding. EPA projects the national average retail price at 127 mills/kWh under repeal versus 134 mills/kWh under the CPS, a decline of approximately 5.8%, equivalent to about 7.81 mills/kWh. The model then produces smaller reductions of approximately 1.1% in 2040 and 2.6% in 2045, yielding an average modelled reduction of approximately 2.2% across 2030–2045. Regulatory Impact Analysis — U.S. EPA — Sep 2026
National retail electricity-price effect
| Year | CPS baseline | Repeal | EPA change | Approximate difference |
|---|---|---|---|---|
| 2030 | 134 mills/kWh | 135 | +0.7% | +1 mill/kWh |
| 2035 | 134 | 127 | −5.8% | −7.8 mills/kWh |
| 2040 | 130 | 128 | −1.1% | −1.5 mills/kWh |
| 2045 | 130 | 127 | −2.6% | −3.4 mills/kWh |
Source: EPA Retail Price Model using IPM system-cost outputs; constant 2024 dollars. Regulatory Impact Analysis — U.S. EPA — Sep 2026
The regional spread is considerably larger than the national average. In 2035 EPA projects reductions ranging from roughly 1% to 14%, with some of the largest declines in regions containing both high expected load growth and substantial coal/gas generation. The EPA tables show −14% for PJMD, −12% for PJMC and MISE, −11% for RMRG, approximately −10% for PJME, and about −9% for TRE/ERCOT, NYUP and PJMW, while regions with lower fossil exposure or different generation structures show much smaller changes. Regulatory Impact Analysis — Table 3-15 — U.S. EPA — Sep 2026
Selected 2035 regional electricity-price effects
| EPA electricity region | CPS baseline | Repeal | Percentage difference |
|---|---|---|---|
| PJMD | 119 mills/kWh | 102 | −14% |
| PJMC | 133 | 116 | −12% |
| MISE | 140 | 124 | −12% |
| RMRG | 122 | 108 | −11% |
| PJME | 165 | 149 | −10% |
| TRE / ERCOT | 117 | 106 | −9% |
| NYUP | 182 | 165 | −9% |
| PJMW | 130 | 119 | −9% |
| National | 134 | 127 | −5.8% |
Source: EPA Table 3-15, constant 2024 dollars. Regulatory Impact Analysis — U.S. EPA — Sep 2026
This heterogeneity means that the industrial effect is geographically concentrated. A steel mill, chemical complex, semiconductor facility or data centre located in a region where EPA projects a double-digit electricity-price reduction would experience a potentially different competitive effect from a facility in a region where the change is close to zero; national-average figures consequently obscure much of the actual distributional geometry.
Lower utility compliance costs do not translate one-for-one into household bills
Three separate transmission mechanisms stand between EPA's compliance-cost savings and the consumer's electricity bill.
First, wholesale power costs represent only part of the retail tariff because transmission, distribution, capacity procurement, utility capital recovery, state taxes, public-policy charges and regulated rate structures differ by jurisdiction. A reduction in generation cost therefore does not mechanically appear as an equal proportional reduction in retail bills.
Second, ownership structure matters: in cost-of-service jurisdictions, regulators determine how utility costs and capital investments enter customer rates, whereas organised wholesale markets transmit marginal generation costs through market-clearing prices before retail suppliers and distribution utilities add other components.
Third, timing matters because avoiding an investment that would otherwise occur in 2035 produces little or no household benefit in 2026 if the expenditure had not yet entered the utility revenue requirement. This is why EPA's own price model generates a small increase in 2030 before larger reductions appear later.
A simple translation illustrates the scale. A household consuming 10,000 kWh annually would save approximately $78 per year from a 7.81-mills/kWh reduction if the entire EPA-modelled 2035 national-average reduction passed through proportionately to its retail tariff: 10,000 × $0.00781 ≈ $78. The calculation is illustrative rather than an EPA household-bill estimate because actual consumption, retail rate structures and pass-through vary materially by state and utility.
For a large industrial plant consuming 1 TWh annually, the same 7.81-mills/kWh differential corresponds to roughly $7.81 million per year before considering demand charges, negotiated industrial tariffs or self-generation. The absolute industrial stakes can therefore be much larger even where the percentage price movement is identical.
The principal industrial effect is concentrated in electricity-intensive production
The repeal's potential competitive consequences are strongest in activities where electricity and natural gas constitute a material share of variable production cost, including primary metals, chemicals, data processing, certain mineral-processing activities and some advanced manufacturing. EPA's economy-wide SAGE model explicitly distinguishes industries including chemicals, cement, primary metals, fabricated metals, electronics and technology manufacturing, transportation equipment, coal mining, natural gas and electric power when assessing cross-sector effects. Regulatory Impact Analysis — SAGE Dimensional Details — U.S. EPA — Sep 2026
For an industrial consumer, repeal can operate through at least three channels simultaneously: lower projected electricity prices, lower projected natural-gas prices in some years, and altered federal taxation/subsidy incidence. The result is therefore broader than the electricity bill alone, especially for chemical and manufacturing facilities that use natural gas both as fuel and feedstock.
The countervailing mechanism is that the same repeal produces a more carbon-intensive electricity supply than the CPS baseline, which can matter commercially for firms selling into markets where product-level embedded emissions are relevant. An American aluminium, steel, hydrogen or other covered producer can consequently experience lower domestic energy input costs while facing a higher reported emissions intensity or a smaller foreign carbon-price deduction where export markets apply carbon-border rules. That international transmission belongs to Pillar Three, but economically it begins with the dispatch changes documented here.
The $310 billion headline must be decomposed before it is used analytically
EPA's public announcement states that the final partial repeal is projected to deliver approximately $310 billion in savings, but the RIA itself contains several distinct measures that answer different economic questions and should not be collapsed into a single figure. EPA Finalizes Repeal of 2024 Power Plant Regulations — U.S. EPA — Sep 2026
EPA's main economic measures are not interchangeable
| Measure | 2026–2047 estimate | What it measures | What it does not measure |
|---|---|---|---|
| Power-sector compliance-cost saving | $160bn PV at 3% | Avoided sector expenditures net of taxes/credits | Not social welfare |
| Same measure at 7% | $95bn PV | Same, discounted more heavily | Not household bill saving |
| Real-resource saving | $280bn PV at 3% | Capital, labour, fuel and other resources no longer required after transfer adjustment | Does not include monetised climate damage |
| Real-resource saving at 7% | $180bn PV | Same concept | Not federal-budget saving alone |
| Economy-wide SAGE annualised social-cost reduction | about $23bn/year | General-equilibrium resource effects across economy | Model excludes change in welfare from environmental quality |
| Public EPA headline | ≈$310bn | Agency summary of broader deregulatory economic effects | Should not be interpreted as cash paid to households |
Sources: EPA RIA and final-rule announcement. Regulatory Impact Analysis — U.S. EPA — Sep 2026 EPA Finalizes Repeal — Sep 2026
The distinction is particularly important because EPA states that its SAGE economy-wide analysis does not currently estimate how changes in environmental quality affect the economy, meaning that the agency's estimated reduction in social costs is not a full monetisation of every consequence associated with the additional emissions. Regulatory Impact Analysis — U.S. EPA — Sep 2026
Conventional pollutant emissions increase alongside CO₂ because dispatch changes
The repeal affects more than carbon dioxide because retaining and dispatching more fossil generation alters emissions of pollutants already regulated under other Clean Air Act programmes. EPA's RIA projects annual NOₓ emissions rising by 13,000 tons in 2030, 191,000 tons in 2035, 257,000 tons in 2040 and 325,000 tons in 2045 relative to the CPS baseline, while annual SO₂ increases by 10,000, 375,000, 394,000 and 508,000 tons, respectively. Regulatory Impact Analysis — Table 3-4 — U.S. EPA — Sep 2026
Mercury differences remain small in the early model years but widen to approximately 1.9 tons annually by 2045, while direct PM₂.₅ emissions are roughly unchanged in 2030 before rising by approximately 7,000 tons in 2035, 14,000 in 2040 and 30,000 in 2045. EPA also projects substantially higher ozone-season NOₓ emissions as the fossil fleet remains more heavily utilised. Regulatory Impact Analysis — Table 3-4 — U.S. EPA — Sep 2026
EPA projected conventional-pollutant change under repeal
| Pollutant | 2030 | 2035 | 2040 | 2045 |
|---|---|---|---|---|
| Annual NOₓ | +13 kt | +191 kt | +257 kt | +325 kt |
| Ozone-season NOₓ | +8 kt | +71 kt | +98 kt | +140 kt |
| SO₂ | +10 kt | +375 kt | +394 kt | +508 kt |
| Mercury | 0.0 t | +0.6 t | +0.6 t | +1.9 t |
| Direct PM₂.₅ | −1 kt | +7 kt | +14 kt | +30 kt |
Source: EPA Table 3-4. Regulatory Impact Analysis — U.S. EPA — Sep 2026
These emissions are not evidence that the corresponding pollutant standards have been abolished; instead, they arise because even plants complying with surviving NOₓ, SO₂, mercury and particulate rules emit residual quantities, and greater output from those facilities produces more aggregate emissions than the lower-fossil-generation CPS baseline.
The carbon consequence is therefore mechanically connected to the economic benefit
The economic and emissions results cannot be understood independently because they are two outputs of the same dispatch change. In 2025, EIA estimates that US electric-power generation produced approximately 750 million metric tonnes of CO₂ from coal and 712 million tonnes from natural gas, with total power-sector energy-related CO₂ emissions of approximately 1.485 billion tonnes. What Are U.S. Energy-Related Carbon Dioxide Emissions by Source and Sector? — U.S. Energy Information Administration — 2026
Coal therefore emitted slightly more power-sector CO₂ than natural gas despite producing substantially less electricity, reflecting coal's higher carbon intensity per unit of useful energy and the higher efficiency of modern combined-cycle gas generation. A policy that extends conventional coal generation consequently produces a much larger CO₂ response than its effect on total national electricity output would suggest.
This is why EPA projects only negligible differences in total electricity generation while simultaneously projecting hundreds of millions of tonnes of additional annual CO₂ emissions in the 2035–2045 period: the economic change is fundamentally a composition effect.
Reliability effects depend on capacity availability, not merely installed megawatts
The administration presents the repeal partly as an electricity-reliability measure, and EPA's modelling does show that preserving dispatchable coal capacity reduces the requirement for alternative capacity. Nevertheless, reliability cannot be inferred from nameplate capacity alone because resource adequacy depends on forced-outage rates, fuel availability, transmission constraints, seasonal capacity accreditation, correlated weather events and the operating characteristics of the replacement portfolio.
EPA's IPM explicitly assigns capacity credits to wind, solar and storage as penetration rises and models resource-adequacy requirements rather than simply treating one installed megawatt as equivalent across technologies. Regulatory Impact Analysis — U.S. EPA — Sep 2026
The repeal therefore changes reliability economics by retaining dispatchable thermal capacity that the CPS baseline would have retired or modified, but the official record does not justify converting that result into a universal claim that every retained coal unit delivers a larger reliability benefit than every alternative portfolio; the answer depends on region, transmission topology, outage performance, fuel supply and load profile.
Data-centre demand makes the timing unusually consequential
EPA specifically identifies regions with high data-centre demand and significant coal and gas generation, including PJM and ERCOT, as regions where its model produces comparatively larger electricity-price effects. Regulatory Impact Analysis — U.S. EPA — Sep 2026
This interaction is important because rapid load growth changes the opportunity cost of retiring existing thermal capacity. In a stagnant-demand system, retirement can be accommodated largely by substitution; in a rapidly growing system, planners must simultaneously replace retiring assets and construct new capacity for incremental load. Removing a regulation that would otherwise accelerate coal retirement can therefore reduce the amount of replacement capacity required precisely during a period when utilities are already attempting to procure turbines, transformers, transmission, storage and generation for new loads.
EPA itself cautions, however, that its near-term projections are sensitive to real-world construction timelines and notes that utilities currently seek to maximise both combustion-turbine and battery deployment, even where its optimisation model might sequence those assets differently. Regulatory Impact Analysis — U.S. EPA — Sep 2026
Distribution of gains and losses
The repeal does not produce a single homogeneous “winner” or “loser” because the financial incidence differs across asset owners, consumers, taxpayers, fuel producers and technology suppliers.
Distributional map of the regulatory change
| Actor | Principal economic mechanism | Direction indicated by EPA modelling |
|---|---|---|
| Owners of existing conventional coal plants | Avoided CCS/co-firing/retirement pressure; longer asset life | Positive relative to CPS baseline |
| Coal mining companies | Higher power-sector coal demand and generally higher delivered prices | Positive |
| Coal rail/logistics chain | Higher tonnage transported | Positive |
| Existing gas producers | Lower power-sector gas demand in key years such as 2035 | Negative relative to CPS baseline in those years |
| New NGCC developers | CCS phase requirement removed, but total gas-capacity additions can also fall because coal stays online | Mixed |
| CCS equipment suppliers | Fewer mandatory projects | Negative relative to CPS baseline |
| CO₂ pipeline/storage developers | Lower captured volumes and lower §45Q-driven deployment | Negative relative to CPS baseline |
| Solar and wind developers | Lower modelled replacement/addition requirement | Negative relative to CPS baseline |
| Storage developers | Modestly lower additions in EPA modelling | Negative relative to CPS baseline |
| Electricity consumers | Lower average rates in most post-2030 model years, regionally uneven | Positive where reductions occur |
| Federal Treasury | Lower projected §45Q payments, but broader tax effects vary | Lower carbon-credit expenditure |
| States | Lower CPS plan/reporting burden | Administrative saving |
| Export-oriented carbon-intensive industry | Potentially lower energy cost but higher embedded-carbon exposure | Mixed |
This distributional structure is more informative than the national savings headline because it identifies where the regulatory change actually enters balance sheets.
The modelling remains a counterfactual, not a forecast guarantee
EPA's RIA repeatedly identifies uncertainties that materially affect the magnitude of the reported results, including electricity-demand growth, fuel prices, capital costs, CCS availability, construction lead times, transmission constraints, renewable and battery costs, generator retirement decisions and the assumption that market participants optimise with substantial foresight. Regulatory Impact Analysis — U.S. EPA — Sep 2026
The appropriate interpretation is therefore comparative rather than predictive: the RIA estimates how a modelled US electricity system behaves with and without the 2024 standards under a common set of assumptions. It does not establish that coal consumption will equal precisely 392 million tons in 2035 or that the national electricity price will necessarily be exactly 5.8% lower.
Several external variables could materially reduce the coal effect, including unexpectedly cheap renewable generation, lower battery costs, higher coal transport costs, plant-specific maintenance problems, tighter state policies or lower electricity demand; conversely, sustained high load growth, slower transmission expansion, gas-turbine shortages or high natural-gas prices could increase the value of keeping existing coal capacity operational.
Key judgments
The principal economic consequence of the repeal is the avoidance of a large 2030s capital-replacement cycle that the 2024 CPS would have accelerated, because coal plants no longer face the same federal requirement to install CCS, co-fire gas, convert or retire, and new baseload gas facilities no longer face the repealed CCS phase. EPA's model therefore retains tens of gigawatts of existing coal capacity and requires substantially fewer replacement renewable and gas assets than the regulated baseline. Regulatory Impact Analysis — U.S. EPA — Sep 2026
The effect is strongly coal-positive but not uniformly gas-positive: coal consumption rises sharply after 2030, while natural-gas use falls by nearly 9% relative to the CPS baseline in 2035 because retained coal generation displaces gas generation that would otherwise fill the gap created by coal retirement. Regulatory Impact Analysis — U.S. EPA — Sep 2026
The projected consumer benefit is delayed and regionally concentrated rather than immediate: EPA models a slight national electricity-price increase in 2030, a large 5.8% reduction in 2035, and smaller reductions thereafter, with selected PJM, Mountain and other fossil-intensive regions experiencing substantially larger changes than the national average. Regulatory Impact Analysis — U.S. EPA — Sep 2026
CCS remains economically viable as an optional federally subsidised technology because §45Q survives, but repeal removes the regulatory mechanism that would have created a broad mandatory market for power-sector capture equipment, and EPA consequently projects substantially lower CCS deployment and approximately $180 billion less present-value CO₂-storage tax-credit transfers at a 3% discount rate over 2026–2047. Credit for Carbon Oxide Sequestration — Internal Revenue Service — 2026 Regulatory Impact Analysis — U.S. EPA — Sep 2026
The official economic case for repeal and the official environmental consequence are therefore inseparable: the same dispatch and investment decisions that produce lower modelled compliance costs generate materially higher coal use, substantially less CCS deployment and higher CO₂ and conventional-pollutant emissions relative to the CPS baseline.
What would change the assessment
A materially different electricity-demand trajectory would alter the results because the value of avoiding thermal retirements rises when load growth is rapid and falls when demand growth disappoints; consequently, future EIA demand revisions, regional load forecasts and actual data-centre interconnection commitments are among the most consequential indicators for assessing whether EPA's modelled capacity effects are becoming observable.
A sustained natural-gas price substantially below EPA's modelled levels could reduce the relative dispatch advantage of coal and narrow the projected coal-generation response, whereas sustained high gas prices would strengthen the economic case for retaining coal generation, as the 2025 market experience already demonstrated when rising gas prices coincided with an 11% increase in coal-fired generation. U.S. Wholesale Day-Ahead Electricity Prices Rose in 2025 — EIA — Feb 2026
Large declines in solar-plus-storage costs, faster transmission construction, substantial improvements in turbine supply or state-level clean-energy requirements could also reduce the amount of conventional coal generation retained relative to EPA's repeal scenario.
Conversely, evidence of delayed turbine deliveries, transformer shortages, transmission bottlenecks, high load growth or extended nuclear construction timelines would increase the scarcity value of already-operating dispatchable fossil capacity and could strengthen the economic effect of the repeal.
A significant wave of voluntary CCS investment supported by §45Q despite repeal would weaken the conclusion that CCS deployment becomes predominantly regulation-dependent; the relevant indicators would be final investment decisions, Class VI injection permits, pipeline commitments, tax-credit transfer agreements and binding capture-equipment contracts rather than announcements alone.
Open official record
The most important unresolved quantitative record is the evolution of EPA's 2025 Reference Case and subsequent IPM updates, because the current RIA's long-term capacity and price results are highly sensitive to electricity-demand forecasts, capital-cost assumptions and fuel-price trajectories embedded in that model.
The second unresolved record concerns actual §45Q utilisation following the 2025 statutory amendments, including how many power-sector capture projects reach final investment decision and how much qualifying CO₂ is captured, stored and credited rather than merely announced.
The third is the actual regional retail-rate response once utilities file integrated-resource plans and rate cases reflecting the repeal, because EPA's Retail Price Model estimates national and regional outcomes but does not determine the tariffs that state regulators, municipal utilities or competitive suppliers will ultimately charge.
The fourth is the federal budgetary effect of reduced CCS deployment, because EPA models large reductions in §45Q transfers but the realised fiscal impact will depend on actual project construction, tax-credit eligibility, transfer prices and future legislative changes.
The fifth is the evolution of plant-level retirement decisions. EPA models 68 GW of avoided coal retirement by 2045, but retirement remains an owner-specific decision influenced by plant age, maintenance expenditure, local pollution-control obligations, fuel contracts, transmission requirements and state regulation, meaning that the extent to which the repeal becomes an actual extension of coal-plant operating life will become observable only through subsequent retirement filings, utility plans and market-capacity outcomes. Regulatory Impact Analysis — U.S. EPA — Sep 2026
Electricity Economics, Coal and Gas Dispatch, Carbon Capture and the Distribution of Regulatory Costs
BLUF / Strategic Assessment: The economic significance of the September 2026 Clean Air Act §111 repeal is not an immediate price drop for electricity, but a structural re-ordering of power-sector investment and dispatch economics emerging decisively after 2030. According to EPA’s Integrated Planning Model (IPM), the repeal preserves 68 GW of coal capacity by 2045 that would otherwise have retired under the 2024 standards, boosting coal burn by +126 Mt in 2035 (+48%) and +276 Mt in 2045. Conversely, natural gas consumption falls by 1.6 Tcf (−8.9%) in 2035 as retained coal directly displaces gas-fired generation, lowering Henry Hub prices by 8%. While EPA reports $160B in private compliance savings ($280B in real-resource savings at a 3% discount rate, framed publicly as ~$310B), this is offset by an estimated $180B drop in §45Q carbon-sequestration tax credit transfers, delayed and uneven consumer rate relief (+0.7% in 2030 before −5.8% in 2035), and higher unmonetized cumulative emissions across both greenhouse gases and conventional pollutants.
Coal Fleet Longevity: Projected Capacity & Consumption Divergence
Coal Fleet Retention: Sunk Asset Economics & Western Basin Surge
Table 1: Power-Sector Fuel Consumption, Delivered Pricing & Asset Dispatch Projections
| Economic / Dispatch Indicator | Model Year | 2024 CPS Baseline | Final Repeal Scenario | Absolute Delta | Relative Delta (%) |
|---|---|---|---|---|---|
| Power-Sector Coal Burn | 2030 | 383 Million Tons | 398 Million Tons | +15 Million Tons | +4.0% |
| Power-Sector Coal Burn | 2035 | 266 Million Tons | 392 Million Tons | +126 Million Tons | +48.0% |
| Power-Sector Coal Burn | 2045 | 15 Million Tons | 291 Million Tons | +276 Million Tons | +1,832%* |
| Delivered Coal Price (2024$) | 2035 | $2.08 / MMBtu | $2.30 / MMBtu | +$0.22 / MMBtu | +10.6% |
| Power-Sector Natural Gas | 2035 | 18.0 Tcf | 16.4 Tcf | −1.6 Tcf | −8.9% |
| Delivered Gas Price (2024$) | 2035 | $5.72 / MMBtu | $5.23 / MMBtu | −$0.49 / MMBtu | −8.6% |
| Conventional Coal Generation | 2035 | 43 TWh | 563 TWh | +520 TWh | +1,209% |
| Coal Generation with CCS | 2035 | 299 TWh | 103 TWh | −196 TWh | −65.6% |
| Non-Hydro Renewables Output | 2035 | 2,011 TWh | 1,778 TWh | −233 TWh | −11.6% |
Table 2: Breakdown of EPA Present-Value Cost and Transfer Measures (2026–2047 Horizon)
| Economic / Regulatory Cost Category | PV at 3% Discount | PV at 7% Discount | Economic & Fiscal Meaning |
|---|---|---|---|
| Power-Sector Compliance Cost Change | −$160 Billion | −$95 Billion | Expenditures avoided by generation owners, net of taxes and subsidies. |
| Avoided Real-Resource Cost (Calculated) | −$280 Billion | −$180 Billion | Social resources (capital, labor, fuel, materials) no longer diverted to compliance. |
| CO₂-Storage Tax-Credit Transfers (§45Q) | −$180 Billion | −$120 Billion | Reduced federal tax outlays due to lower projected carbon capture deployment. |
| Clean-Energy Tax-Credit Transfers (IRA) | −$0.93 Billion | +$0.87 Billion | Slight net adjustment in production/investment tax credits for replacement capacity. |
| Other Government Tax Receipts / Transfers | −$66 Billion | −$38 Billion | Net fiscal impacts from corporate income taxes and royalty payments. |
| SAGE Annualized Economy-Wide Benefit | ~$23 Billion / yr | ~$23 Billion / yr | General-equilibrium GDP effect; excludes monetized climate damages. |
Structural Pillars of Power-Sector Dislocation
GAS DISPLACEMENT PARADOX
−1.6 TCF IN 2035- Coal Displaces Gas: Retaining conventional coal units directly reduces gas-fired generation in the 2030s, cutting power-sector natural gas demand by 1.6 Tcf (−8.9%) in 2035.
- Feedstock & Pricing Tailwinds: Lower demand reduces delivered power gas prices by $0.49/MMBtu (−8.6%) and depresses Henry Hub by 8%, benefiting industrial consumers and LNG exporters.
- Upstream Repercussions: Gas producers face volume headwinds in the medium term, showing that environmental rollbacks do not uniformly benefit all domestic fossil fuels.
CCS BUSINESS MODEL SHIFT
§45Q TAX-ASSET MODEL- Mandate Vacated: Power-sector CCS with coal falls from 44 GW to 15 GW by 2035, while gas CCS capacity drops by a third, reflecting the removal of compliance deadlines.
- Fiscal Credit Contraction: Lower capture volumes reduce projected §45Q tax credit transfers by $180B (3% PV), cutting federal outlays for carbon sequestration.
- Project Finance Hurdle: CCS moves from a required utility cost into a voluntary project finance decision reliant on $85/t tax credits, pore space access, and local pipeline geology.
RETAIL PRICING DYNAMICS
PJM/ERCOT SAVINGS- Delayed National Relief: EPA models a +0.7% national retail rate increase in 2030 due to asset sequencing, followed by a −5.8% drop (−7.8 mills/kWh) in 2035 as avoided capital costs accumulate.
- Regional Concentration: Savings are concentrated in fossil-heavy, high-load regions: PJMD (−14%), PJMC (−12%), MISE (−12%), and ERCOT (−9%) in 2035.
- Industrial vs Residential Split: A 1 TWh industrial facility could save ~$7.8M annually by 2035, whereas an average residential customer (10,000 kWh/yr) saves ~$78 annually.
Forensic Strategic Key Judgments: Power Economics & Dispatch
Avoidance of 2030s Capital Replacement Cycle
The primary economic impact is avoiding a major capital-replacement cycle in the 2030s, preserving 68 GW of existing coal capacity through 2045 and reducing required additions of renewable and storage capacity.
Coal-Positive, Intermittently Gas-Negative
Power-sector coal use expands by +48% in 2035, displacing gas generation and reducing natural gas consumption by 1.6 Tcf (−8.9%), which temporarily lowers Henry Hub prices by 8%.
Shift in CCS Deployment Economics
CCS transitions from a mandatory regulatory compliance requirement to an optional tax-incentivized asset under IRC §45Q ($85/t), with EPA modeling a 66% decline in coal CCS deployment by 2035.
Delayed and Regionally Asymmetric Rate Relief
Retail rate impacts show a small national increase of +0.7% in 2030 before falling by −5.8% in 2035, with price cuts concentrated in PJM (−14%) and ERCOT (−9%) where fossil dispatch is high.
Delivered Coal Prices Rise
Rising domestic coal consumption drives delivered coal prices up +10% in 2035 and +27% in 2045, shifting a portion of avoided compliance costs to mine operators and rail carriers.
Economic Reductions Tied to Emissions Growth
Compliance cost reductions derive from keeping conventional fossil generation online, which increases annual power-sector emissions of CO₂ (+406 Mt in 2035), SO₂ (+375 kt), and NOx (+191 kt).
Open Official Record Gaps
- EPA Reference Case Fuel Assumptions: Details on underlying fuel price elasticities and long-term natural gas production curves in the updated Integrated Planning Model remain subject to future revisions.
- Actual §45Q Utilization Data: The volume of commercial power-sector carbon capture projects reaching final investment decision following the 2025 legislative changes remains undocumented.
- Utility Integrated Resource Plans (IRPs): The degree to which regulated utilities will formally adjust integrated resource plans to cancel scheduled coal retirements post-repeal has not yet been filed.
- Class VI Well Permitting Timelines: State and federal permitting turnaround times for deep geological saline injection sites required for large-scale power CCS projects remain uncertain.
Observable Watch Indicators
Pillar Three — Transatlantic carbon divergence and implications for Europe
Principal judgment
The strategic consequence for Europe is not that the United States has ceased to matter to global climate policy, but that the transatlantic economic relationship is moving toward a more pronounced asymmetry in the treatment of carbon costs, because the United States is weakening federal constraints on fossil-power emissions while the European Union is simultaneously tightening the integration between domestic carbon pricing and external trade through the EU Emissions Trading System and the Carbon Border Adjustment Mechanism. The resulting divergence is therefore regulatory, fiscal and industrial at the same time: European producers remain exposed to explicit carbon costs under the EU ETS, importers increasingly face embedded-emissions obligations under CBAM, and American producers can in principle benefit from lower domestic electricity-system compliance costs without facing an equivalent federal carbon price at source. CBAM Definitive Regime — European Commission — 2026
The most important institutional fact is that the EU system does not require regulatory symmetry with the United States in order to operate. Under the definitive CBAM regime, EU importers must declare the embedded emissions contained in covered goods and surrender the corresponding number of CBAM certificates, while the certificate price is tied to the EU ETS allowance price; a deduction is permitted only where the importer demonstrates that a carbon price has actually been paid in the country of origin. A weaker US federal climate regime therefore does not neutralise European carbon costs, but instead increases the importance of demonstrating actual product-level emissions and of proving any qualifying carbon payment made under a state or foreign system. CBAM Definitive Regime — European Commission — 2026
The resulting industrial question is consequently not whether Europe “imports American deregulation”, because it does not, but whether lower US energy-system compliance costs improve the competitiveness of US producers precisely as European producers begin to receive progressively less protection through free EU ETS allocation. That tension becomes more important after 2026 because the ETS Directive reduces the free-allocation factor for CBAM sectors from 100% through 2025 to 97.5% in 2026, 95% in 2027, 90% in 2028, 77.5% in 2029, 51.5% in 2030, 39% in 2031, 26.5% in 2032 and 14% in 2033, before the CBAM-linked free-allocation mechanism disappears from 2034. Directive (EU) 2023/959 — European Union
The transatlantic divergence operates through carbon cost, electricity cost and product carbon intensity
Three separate price mechanisms have to be distinguished if the European implications are to be understood correctly.
The first is the direct carbon cost incurred by European producers covered by the EU ETS, under which industrial and power installations must surrender allowances against verified emissions, subject to the specific free-allocation rules applicable to industrial sectors. The second is the indirect carbon cost transmitted through electricity prices, because fossil generation must acquire allowances for covered emissions and marginal electricity prices can consequently incorporate part of that carbon cost. The third is the border-carbon cost imposed on imports through CBAM, which attempts to place covered imported goods under a carbon-cost discipline broadly corresponding to the EU domestic framework.
A US producer can therefore enjoy an energy-cost advantage without receiving a formal CBAM exemption. If an American steel, aluminium, fertiliser, cement or hydrogen producer purchases electricity from a system in which federal power-sector CO₂ compliance costs have been reduced, its production cost can fall even though its EU importer subsequently faces a CBAM obligation based on embedded emissions. The border mechanism can offset part of the carbon-pricing asymmetry, but it does not necessarily replicate every cost experienced by the European producer, because EU competitiveness depends not only on the nominal carbon price but also on energy prices, free allocation, grid charges, taxes, financing costs, technology choice and product-specific emissions intensity.
The four principal transatlantic carbon-cost channels
| Channel | European producer | US producer exporting to Europe | Main transmission mechanism |
|---|---|---|---|
| Domestic carbon price | EU ETS obligation for covered emissions | No equivalent federal economy-wide ETS/carbon tax | Direct production cost |
| Power-sector carbon constraint | Power generation subject to EU ETS | Federal power-sector GHG performance constraints materially weaker after September 2026 | Electricity and fuel cost |
| Border adjustment | Not applicable to EU domestic production | CBAM applies to covered imports | Embedded-emissions charge |
| Free allocation | Declines progressively for CBAM sectors from 2026 | Not relevant unless recognised foreign carbon payment exists | Carbon-leakage mitigation |
Sources: Directive (EU) 2023/959 — European Union ; CBAM Definitive Regime — European Commission
The critical analytical point is that CBAM is designed to equalise the carbon-price component associated with embedded emissions, not every difference in industrial policy, electricity-system regulation or energy cost between the EU and a third country. A US producer could therefore still retain a competitive advantage arising from lower power prices even after the CBAM carbon adjustment is paid, while a particularly low-carbon American installation could experience a much smaller border cost than a high-carbon competitor located in the same country.
CBAM has entered the phase in which carbon data becomes a trade instrument rather than merely an environmental disclosure
The definitive CBAM regime began on 1 January 2026, replacing the transitional reporting phase and requiring authorised CBAM declarants to move toward financial settlement through certificate surrender. The Commission states that certificate prices in 2026 are calculated using the quarterly average auction price of EU ETS allowances, moving to a weekly average from 2027, while importers may deduct a carbon price already paid in the country of origin if they can prove the payment. CBAM Definitive Regime — European Commission — 2026
The strategic consequence is that emissions information becomes part of customs and trade administration. For covered products, the economic relevance of a tonne of CO₂ no longer depends solely on environmental regulation at the place of production; it becomes part of the customs value chain because the importer must establish how much carbon was embedded in the imported good and what carbon price, if any, had already been paid.
Core EU CBAM sectors in the definitive regime
| Covered sector | Why electricity-system carbon intensity matters | Principal transatlantic exposure |
|---|---|---|
| Iron and steel | Electric arc furnaces and upstream processes consume substantial electricity; blast-furnace routes remain carbon-intensive | US steel and downstream trade |
| Aluminium | Primary aluminium is highly electricity-intensive | Strong sensitivity to power carbon intensity |
| Cement | Process emissions dominate, but electricity remains relevant | Smaller direct US-EU trade volumes than metals, but high embedded carbon |
| Fertilisers | Natural gas and process emissions are major cost drivers | Strong linkage to gas and hydrogen economics |
| Hydrogen | Carbon intensity determined by production pathway and electricity/gas source | Potentially major future transatlantic trade |
| Electricity | Direct carbon content of imported electricity | Limited direct US-EU relevance because no physical interconnection |
Source: CBAM Definitive Regime — European Commission
The American rollback therefore creates the most direct European exposure where cheaper or more carbon-intensive US electricity changes the embedded emissions of goods that subsequently enter the EU market. The mechanism is particularly important for aluminium, hydrogen and electrically intensive steelmaking because the carbon intensity of electricity can materially affect the product-level CBAM calculation.
The decline in EU free allocation is what makes the divergence increasingly consequential after 2026
The interaction between CBAM and free allocation is central because EU industrial producers historically received free allowances to reduce the risk that carbon pricing would shift production outside Europe. That protection is now being progressively withdrawn for sectors covered by CBAM.
Under the revised ETS Directive, the CBAM factor applicable to free allocation falls gradually from 97.5% in 2026 to zero after 2033. The scale of that transition accelerates sharply around 2029–2031, because the factor drops from 90% in 2028 to 77.5% in 2029 and to only 51.5% in 2030. Directive (EU) 2023/959 — European Union
EU CBAM free-allocation phase-down
| Year | CBAM factor applied to free allocation | Approximate share phased out relative to 100% factor |
|---|---|---|
| 2025 | 100% | 0% |
| 2026 | 97.5% | 2.5% |
| 2027 | 95% | 5% |
| 2028 | 90% | 10% |
| 2029 | 77.5% | 22.5% |
| 2030 | 51.5% | 48.5% |
| 2031 | 39% | 61% |
| 2032 | 26.5% | 73.5% |
| 2033 | 14% | 86% |
| 2034 onward | 0% | 100% |
Source: Directive (EU) 2023/959 — European Union
The European competitiveness problem therefore becomes progressively more exposed to the actual carbon intensity of production. In 2026, only a small portion of the old free-allocation shield has disappeared; by 2030 almost half of the CBAM-sector factor has been removed, which materially increases the difference between efficient low-carbon European plants and high-emitting installations.
The same timetable strengthens the importance of border enforcement. If CBAM carbon-intensity verification is weak, default values are poorly calibrated or product-origin rules can be circumvented, European producers will lose free allocation faster than border adjustment protects them, creating a genuine carbon-leakage and competitiveness problem. Conversely, rigorous embedded-emissions verification strengthens the intended symmetry between domestic and imported carbon costs.
The US decision can therefore increase the value of carbon-efficiency differentiation inside Europe
A frequently overlooked consequence of transatlantic divergence is that it does not necessarily disadvantage every European producer equally. European installations with very low electricity-related carbon intensity can benefit from a widening difference between their product footprint and that of carbon-intensive foreign producers.
France represents the clearest example because the structure of its electricity system produces exceptionally low power-sector emissions. RTE reports that mainland French electricity generation reached 547.5 TWh in 2025, of which 521.1 TWh, or 95.2%, was low-carbon, while nuclear alone generated 373.0 TWh, equivalent to 68.1% of production. RTE calculates the greenhouse-gas intensity of French electricity generation at only 19.6 gCO₂e/kWh in 2025. Annual Electricity Review 2025 — RTE
Germany has a fundamentally different electricity-carbon profile. Destatis reports 438.2 TWh of domestic net grid injection in 2025, with 58.6% from renewable sources, but coal still supplied 96.8 TWh, or 22.1%, while natural gas supplied 70.6 TWh, or 16.1%. Renewables therefore dominate generation overall, but substantial fossil output remains embedded in the system. Stromerzeugung aus Photovoltaik und Erdgas erreicht 2025 neue Höchstwerte — Statistisches Bundesamt — Mar 2026
Italy occupies another distinct position because its system relies heavily on imported energy and thermoelectric generation while renewable capacity is expanding rapidly. Terna reports national electricity demand of 311.3 TWh in 2025, net domestic production of 268.4 TWh, thermoelectric generation of 153.1 TWh, photovoltaic output of 44.3 TWh, hydroelectric output of 41.4 TWh, wind output of 21.4 TWh, geothermal output of 5.3 TWh, and coal generation of only 3.0 TWh. Rapporto Mensile sul Sistema Elettrico — Dicembre 2025 — Terna
The United Kingdom, meanwhile, combines an independent carbon-pricing regime with a rapidly decarbonising power system. The Department for Energy Security and Net Zero reports that 73.3% of Great Britain’s generation came from clean-power technologies in 2025, while provisional electricity-supply emissions intensity fell to 104 gCO₂e/kWh, from 154 gCO₂e/kWh in 2022. DESNZ Annual Report 2025–26 — UK Government
Comparative electricity-system position relevant to industrial carbon intensity
| Country | Latest official electricity indicator | Fossil exposure most relevant to industrial carbon intensity | Strategic implication |
|---|---|---|---|
| France | 95.2% low-carbon; 19.6 gCO₂e/kWh in 2025 | Very limited fossil generation | Strong structural advantage for electricity-intensive low-carbon production |
| Germany | 58.6% renewable; coal 22.1%, gas 16.1% in 2025 | Material coal and gas generation remains | Carbon-intensity exposure remains significant despite high renewable share |
| Italy | 153.1 TWh thermoelectric production; 44.3 TWh solar; coal only 3.0 TWh | Gas-dominated thermal structure and imported electricity/energy | Exposure tied primarily to gas and imported-energy economics rather than coal |
| Great Britain | 73.3% clean-power share; 104 gCO₂e/kWh supply intensity in 2025 | Gas remains marginal fossil technology | Lower carbon intensity than fossil-heavy systems, but still materially above France |
Sources: RTE, Destatis, Terna and DESNZ official data.
These differences mean that a single “European competitiveness” narrative is analytically inadequate. France enters the transatlantic divergence with a much stronger low-carbon electricity position than Germany or Italy, while the UK operates outside the EU ETS but is constructing a parallel carbon-border architecture.
Germany faces the sharpest tension between industrial scale and carbon-cost exposure
Germany is the European country in this comparison with the most direct combination of large energy-intensive manufacturing, substantial residual fossil generation and major industrial trade exposure to the United States.
Destatis reported that Germany exported €2.5 billion of iron, steel and related goods to the United States in the first eight months of 2025, representing 6.2% of all German iron and steel exports, while aluminium exports to the United States amounted to €419 million, equivalent to 3.3% of Germany’s total aluminium exports. Exports of Iron and Steel Down 4.8% in the First Eight Months of 2025 — Destatis — Oct 2025
The significance of those figures extends beyond their absolute value because German producers compete with American firms both in the US market and in third markets. A US producer benefiting from lower prospective electricity-system compliance costs can therefore affect German industry through at least three channels: direct competition inside the US market, competition in other export markets, and competition from US goods imported into Europe.
Germany's domestic electricity structure compounds that pressure. Although renewables supplied 58.6% of generation in 2025, coal and gas together still accounted for 38.2% of net grid injection, meaning that domestic industrial electricity prices remain more exposed to fossil marginal pricing and carbon costs than in France. Stromerzeugung aus Photovoltaik und Erdgas erreicht 2025 neue Höchstwerte — Destatis
German exposure channels
| Exposure | Official baseline | Why US deregulation matters |
|---|---|---|
| Iron/steel exports to US | €2.5bn Jan–Aug 2025 | German producers compete against US domestic producers potentially facing lower power-system compliance costs |
| Aluminium exports to US | €419m Jan–Aug 2025 | Highly electricity-sensitive sector |
| Domestic coal generation | 96.8 TWh in 2025 | EU ETS carbon costs remain material |
| Domestic gas generation | 70.6 TWh in 2025 | Gas remains important in power-price formation |
| Renewable generation | 256.9 TWh in 2025 | Reduces carbon exposure but does not eliminate fossil marginal-price effects |
Sources: Destatis.
The central German problem is therefore not simply “high carbon prices”, but the coexistence of large-scale industrial production with a power system that has decarbonised substantially but still contains enough coal and gas for carbon pricing to remain economically relevant. The US rollback widens the policy gap precisely during the period in which German steel, chemicals, basic materials and advanced manufacturing are attempting to electrify production.
France enters the divergence from a structurally stronger electricity position
France's industrial exposure is qualitatively different because electricity-intensive manufacturing can draw on a power system with extraordinarily low carbon intensity by international standards. RTE reports that nuclear output reached 373 TWh in 2025, while fossil generation continued to fall and low-carbon production reached 521.1 TWh. 2025 Electricity Review — RTE
For sectors in which electricity consumption is a major determinant of product carbon intensity, this creates an important comparative advantage under CBAM because lower embedded emissions reduce exposure to carbon costs and strengthen the credibility of low-carbon industrial production. Aluminium processing, electro-intensive metallurgy, electric-arc steelmaking, hydrogen production and future synthetic-fuel chains can all benefit from this structure where electricity sourcing can be documented appropriately.
The French vulnerability lies elsewhere: European carbon policy affects industrial cost even when electricity itself is low-carbon because process emissions remain important in cement, chemicals, fertilisers and blast-furnace steelmaking, while the progressive reduction of free allocation increases the cost of emissions that cannot immediately be eliminated technologically.
France's 2025 power structure
| Source | Generation | Share |
|---|---|---|
| Nuclear | 373.0 TWh | 68.1% |
| Hydro | 62.4 TWh | 11.4% |
| Wind | 49.6 TWh | 9.1% |
| Solar | 32.9 TWh | 6.0% |
| Gas | 16.4 TWh | 3.0% |
| Coal | 0.7 TWh | 0.1% |
| Oil | 1.6 TWh | 0.3% |
| Total | 547.5 TWh | 100% |
Source: Annual Electricity Review 2025 — RTE
France therefore has a stronger structural defence against the American electricity-carbon divergence than Germany or Italy, provided that nuclear availability remains high and electricity prices transmit that low-carbon production advantage to industrial users.
Italy's exposure is driven less by coal than by gas, imports and industrial electricity costs
Italy's electricity system illustrates why a generic coal-centred interpretation of the US decision is insufficient for European analysis. Terna reports that coal generation fell another 13.5% in 2025 to only 2.975 TWh, while total thermoelectric generation increased 4.6% to 153.056 TWh and photovoltaic generation increased 25.1% to 44.290 TWh. Rapporto Mensile sul Sistema Elettrico — Dicembre 2025 — Terna
The implication is that Italy's relative carbon-cost position is determined primarily by gas-fired generation, imported electricity and rapidly expanding renewables, rather than by domestic coal. Terna reports that Italian electricity demand reached 311.324 TWh in 2025, while net domestic production totalled 268.420 TWh, meaning that cross-border electricity continued to play a material role in balancing the system. Rapporto Mensile sul Sistema Elettrico — Dicembre 2025 — Terna
Terna's own system analysis also highlights the structural dependence on external energy sources: its development planning documentation notes that much of Italian thermoelectric generation transforms imported fuel, especially gas, into electricity, while direct electricity imports constitute an additional external dependency. 2025 Development Plan — Terna
Italy's 2025 electricity structure
| Indicator | 2025 value |
|---|---|
| National electricity demand | 311.324 TWh |
| Net domestic generation | 268.420 TWh |
| Thermoelectric generation | 153.056 TWh |
| Solar generation | 44.290 TWh |
| Renewable hydro | 41.365 TWh |
| Wind | 21.363 TWh |
| Geothermal | 5.261 TWh |
| Coal | 2.975 TWh |
| Solar capacity at year-end | 43.513 GW |
| Wind capacity at year-end | 13.629 GW |
| New renewable capacity added during 2025 | 7.191 GW |
Sources: Terna electricity demand 2025 and December 2025 Monthly System Report.
For Italian manufacturing, the strategic risk is therefore the interaction between EU carbon pricing and comparatively high electricity-system dependence on gas and external energy supplies. Lower US electricity-system compliance costs matter because they can widen operating-cost differences for Italian steel processors, machinery producers, ceramics, chemicals, food-processing plants, data centres and other electricity-intensive activities, even where those industries themselves are not directly covered by CBAM.
The countervailing force is rapid renewable deployment. Terna reports 7.191 GW of renewable capacity additions in 2025, taking total renewable installed capacity to 83.529 GW, including 43.513 GW of solar. Terna electricity demand 2025
If that investment translates into lower wholesale prices, stronger grids and greater storage availability, Italy can narrow part of the electricity-cost asymmetry independently of US policy. Terna is planning more than €23 billion of grid investment for 2025–2034, together with expansion of transport and cross-border capacity, precisely because renewable capacity alone does not automatically translate into lower industrial power costs without adequate network infrastructure. Italian National Grid — Terna
The United Kingdom is building a parallel border-carbon regime rather than following the EU mechanically
The United Kingdom's exposure must be treated separately because Brexit removed it from the EU ETS and EU CBAM, but Britain established its own UK ETS in 2021 and is introducing its own CBAM from January 2027.
The UK ETS currently covers heavy industry, power generation, aviation and domestic maritime activity and accounts for approximately 25% of UK territorial emissions. One allowance represents one tonne of CO₂-equivalent greenhouse gas, and covered operators must surrender allowances corresponding to their emissions. UK Emissions Trading Scheme: Policy Overview — UK Government — Sep 2026
The British CBAM will begin on 1 January 2027, covering specified goods from the aluminium, cement, fertiliser, hydrogen, iron and steel sectors, while businesses importing at least £50,000 of covered goods over a 12-month period fall within the principal registration/liability framework. Carbon Border Adjustment Mechanism — HMRC — Sep 2026
The UK system expressly allows the CBAM liability to be reduced where the embodied emissions were already subject to a deductible carbon price abroad and the importer can provide evidence of that payment; the UK government states that qualifying foreign carbon pricing can include a tax, emissions trading system or another CBAM. Factsheet: Carbon Border Adjustment Mechanism — HMRC
EU and UK border-carbon architecture
| Feature | European Union | United Kingdom |
|---|---|---|
| Start of financial CBAM regime | 1 Jan 2026 | 1 Jan 2027 |
| Domestic carbon market | EU ETS | UK ETS |
| Covered core sectors | Cement, iron/steel, aluminium, fertilisers, electricity, hydrogen | Aluminium, cement, fertiliser, hydrogen, iron/steel |
| Electricity covered directly | Yes | No in current UK core list |
| Recognition of foreign carbon price | Yes | Yes |
| Carbon-price reference | EU ETS allowance price | UK domestic carbon-price basis |
| UK/EU free-allocation interaction | EU phase-down linked directly to CBAM | UK free-allocation rules being adjusted alongside UK CBAM |
Sources: European Commission and HMRC.
The UK system therefore creates a second major European border-carbon regime through which weaker US domestic carbon pricing can become commercially relevant. An American exporter entering Britain after 2027 will not receive an exemption simply because the United States lacks an equivalent federal carbon price; rather, the absence of a deductible US carbon payment potentially increases the residual UK CBAM liability where embodied emissions are substantial.
Britain has less carbon-intensive electricity than Germany or Italy, but more than France
The UK's domestic competitiveness position lies between France and the more fossil-dependent continental systems. DESNZ reports that the emissions intensity of Great Britain's electricity supply fell to a provisional 104 gCO₂e/kWh in 2025, compared with 107 g in 2024, 129 g in 2023 and 154 g in 2022, while 73.3% of GB generation came from clean-power technologies in 2025. DESNZ Annual Report 2025–26
The UK's carbon-price architecture is also becoming more institutionalised. The UK ETS Authority increased the auction reserve price from £22 to £28 from 8 April 2026, with future annual inflation adjustment beginning in 2027. UK ETS Policy Overview — UK Government
That does not mean UK industrial carbon costs are necessarily higher than EU equivalents at every point in time, because market allowance prices fluctuate independently, but it confirms that Britain is moving in the opposite institutional direction from the current US federal rollback: the UK is retaining a capped allowance system, expanding sectoral coverage and adding a border adjustment rather than removing the domestic carbon-price architecture.
The most important transatlantic competitiveness gap is not necessarily the headline carbon price
A common analytical error is to compare the EU ETS allowance price with zero in the United States and infer that the numerical difference represents the entire competitive disadvantage. That comparison is incomplete because actual industrial cost depends on:
| Cost variable | EU producer | US producer |
|---|---|---|
| Direct carbon allowance obligation | Material in covered sectors | No federal economy-wide equivalent |
| Free allowances | Declining for CBAM sectors | Not applicable federally |
| Electricity price | Country and region specific | State and market specific |
| Gas price | Often structurally higher than US Henry Hub-linked prices | Typically advantaged by domestic gas supply |
| Carbon-intensity of electricity | Extremely low in France; higher in Germany/Italy | Highly regional |
| Subsidies and tax credits | EU/national support programmes | Federal/state incentives including §45Q and other instruments |
| Border adjustment | Not applicable to EU domestic product | Applies when importing covered US goods into EU |
| Transport/logistics | Domestic/internal market | Atlantic freight cost |
| Tariffs/trade measures | Depends on product and current trade regime | Depends on reciprocal measures |
The actual transatlantic competitiveness result therefore depends on the sum of carbon, energy, capital, logistics and trade costs, not on the carbon-price differential alone.
This is particularly important because American electricity prices themselves are geographically fragmented. A low-cost US hydro or renewable region and a coal-heavy Midwestern region can have very different product emissions profiles, while a French nuclear-based installation and a German fossil-exposed installation can differ just as substantially within Europe.
Lower US federal carbon constraints can strengthen the relative attraction of American industrial investment even before CBAM is considered
The deeper industrial-policy concern is investment location rather than trade alone. When companies assess whether to locate a new data centre, steel plant, hydrogen facility, chemical complex or semiconductor plant in Europe or the United States, they evaluate long-duration electricity contracts, natural-gas prices, permitting timelines, tax incentives, network capacity and environmental compliance expenditure.
The September EPA rollback alters one component of that calculation by reducing the expected future compliance cost of fossil-fired electricity generation in the United States. If the result is greater availability of dispatchable generation or lower electricity prices in specific US regions, then American industrial sites can become relatively more attractive even before any product enters international trade.
CBAM does not fully neutralise that investment-location incentive because it applies only to specific imported goods and does not presently cover every manufactured product or service. A US data centre, semiconductor fabrication plant or many categories of downstream manufactured goods can therefore benefit from electricity-cost differences without facing an EU CBAM charge directly.
This is one reason why the transatlantic divergence can have consequences outside the sectors formally listed in the CBAM regulation.
Carbon leakage therefore has two distinct geometries
The first is import substitution, where EU production loses market share to imports produced under weaker carbon constraints; CBAM is explicitly designed to address that risk.
The second is investment leakage, where new industrial investment is located outside Europe because expected energy, carbon and regulatory costs are lower abroad. CBAM addresses this only indirectly, because its coverage is product-specific and does not compensate Europe for all factors influencing capital allocation.
The revised ETS Directive itself recognises the continuing carbon-leakage issue by linking the gradual reduction of free allocation to the CBAM phase-in rather than eliminating free allowances immediately. Directive (EU) 2023/959 — European Union
Two forms of leakage
| Type | Mechanism | CBAM effectiveness |
|---|---|---|
| Import leakage | Foreign high-carbon goods replace EU goods | Directly targeted |
| Production relocation | Existing EU production moves abroad | Partially addressed |
| New-investment diversion | Future capacity located abroad | Indirectly addressed only |
| Downstream substitution | Finished products made abroad using carbon-intensive inputs | Limited where product is outside CBAM scope |
The last category is particularly important because a carbon-intensive intermediate good can be processed into a downstream product not covered by CBAM, potentially shifting competitive pressure further down the value chain.
Germany is most exposed to downstream industrial spillovers
Germany's large automotive, machinery, electrical-equipment and engineering sectors make downstream effects particularly important because those industries purchase substantial quantities of steel, aluminium, chemicals and other carbon-intensive intermediates.
The US rollback can therefore affect German competitiveness even where the final German export itself falls outside CBAM. If US manufacturers acquire steel, aluminium or electricity at lower cost, they can incorporate those advantages into vehicles, machinery or capital goods that compete with German output globally.
Destatis' 2025 trade data show the depth of the existing industrial relationship: Germany's exports of iron and steel products to the US remained €2.5 billion in the first eight months of 2025 despite new US trade restrictions, while the United States still absorbed 6.2% of total German iron and steel exports. Exports of Iron and Steel Down 4.8% — Destatis — Oct 2025
That relationship means transatlantic carbon divergence intersects directly with trade-policy divergence, tariff exposure and industrial investment decisions rather than functioning as an isolated environmental-policy issue.
Italy's vulnerability lies in the cost position of medium- and high-energy manufacturing
Italy's industrial structure makes the issue particularly relevant for producers whose margins are sensitive to electricity and gas but whose final goods are not always directly covered by CBAM.
The Italian economy contains large concentrations of machinery, metals processing, ceramics, glass, food processing and specialised manufacturing that purchase electricity and gas rather than producing primary bulk commodities alone. The September US rollback therefore matters through comparative energy costs even where Italian firms never import a CBAM-covered American product.
Terna's 2025 data underline why energy-system reform is central to Italy's response: thermoelectric generation remained 153.1 TWh, while solar reached 44.3 TWh and total net generation 268.4 TWh. Rapporto Mensile sul Sistema Elettrico — Dicembre 2025 — Terna
Italy's competitive response therefore depends less on weakening European carbon policy than on reducing the structural cost of decarbonised electricity through grid reinforcement, renewable integration, storage, interconnection and more efficient gas-market exposure.
France has the strongest case for converting decarbonisation into industrial advantage
France's 19.6 gCO₂e/kWh electricity intensity creates the possibility of treating low-carbon electricity as an industrial asset rather than merely an environmental obligation. 2025 Electricity Review — RTE
If French industry can secure long-term access to competitive electricity prices, sectors such as low-carbon hydrogen, electrified metals production, data centres and advanced manufacturing can achieve both low embedded emissions and comparatively stable power supply.
The constraint is that low carbon intensity does not automatically produce low industrial electricity prices. Network charges, market design, nuclear-cost allocation, investment financing and contracts all determine whether the physical advantage of France's generation mix becomes an economic advantage for industrial consumers.
The US rollback therefore increases the strategic value of translating France's low-carbon generation into predictable industrial power contracts.
Britain faces a transitional competitiveness test in 2027
The UK faces a distinctive sequencing problem because its CBAM does not begin until January 2027, while the UK ETS is already operating and industrial free-allocation arrangements are being adjusted.
HMRC's policy summary states that the CBAM framework is now embedded in the Finance Act 2026, with secondary legislation progressively laid during 2026. CBAM Policy Summary — HMRC — Sep 2026
The UK therefore enters 2027 with two parallel objectives: maintaining a domestic carbon price sufficient to support decarbonisation while ensuring that foreign goods produced under weaker carbon constraints do not systematically undercut domestic producers.
The American rollback strengthens the importance of the second objective because US exporters may arrive in the British market having faced a materially weaker federal carbon constraint at the electricity-generation stage.
EU and UK carbon-border systems can potentially create a new transatlantic data divide
An important second-order effect concerns measurement standards. European and British border-carbon systems increasingly require verified embedded-emissions information, whereas the United States is simultaneously reconsidering parts of its federal greenhouse-gas reporting architecture.
The result could be a paradox in which American firms face fewer domestic federal reporting obligations but greater foreign commercial pressure to produce installation-level emissions data.
For large multinational producers this is manageable because firms can operate private monitoring, verification and lifecycle-accounting systems; for smaller exporters, however, the administrative burden can become material because foreign buyers may demand emissions information that is no longer generated through a standard federal reporting framework.
The consequence is that carbon-data quality itself becomes a competitiveness factor.
The strategic divergence is likely to widen through 2030 even without further US climate deregulation
The divergence built into existing European law becomes more pronounced automatically because the CBAM-linked free-allocation factor falls from 97.5% in 2026 to 51.5% in 2030, even if neither Washington nor Brussels adopts another major measure. Directive (EU) 2023/959 — European Union
That means the relative importance of actual carbon intensity rises year by year.
Transatlantic carbon-policy trajectory to 2030
| Year | EU CBAM free-allocation factor | EU border-carbon pressure | US federal power-sector GHG position after Sep 2026 |
|---|---|---|---|
| 2026 | 97.5% | Initial definitive phase | Major 2024 standards repealed |
| 2027 | 95% | Higher | UK CBAM also enters force |
| 2028 | 90% | Higher | Depends on litigation and any further EPA action |
| 2029 | 77.5% | Material acceleration | Structural divergence becomes more economically visible |
| 2030 | 51.5% | Nearly half of old CBAM-sector free-allocation factor removed | Any surviving US regulatory asymmetry becomes substantially more consequential |
Source for EU phase-down: Directive (EU) 2023/959
The policy tension will therefore not peak in 2026. The economically more important period is likely to be 2029–2031, when EU free allocation falls much more rapidly and investment decisions made today begin to determine the composition of industrial capacity on both sides of the Atlantic.
Key judgments
The American power-sector rollback creates a relative industrial advantage rather than an automatic absolute advantage, because lower federal compliance costs can improve US electricity economics but the magnitude depends on state, fuel mix, power market and product carbon intensity; European and UK border-carbon mechanisms can recover part of the carbon-price difference but cannot eliminate every difference in electricity, gas, financing or regulatory cost.
The EU response is structurally embedded in existing law rather than dependent on a new political decision, because the definitive CBAM regime is already operational and the free-allocation phase-down is already scheduled through 2034. CBAM Definitive Regime — European Commission Directive (EU) 2023/959 — European Union
France possesses the strongest electricity-carbon position among the four countries examined, with 95.2% low-carbon generation and an emissions intensity of 19.6 gCO₂e/kWh in 2025, creating a potentially significant advantage for electricity-intensive low-carbon production if that physical advantage is converted into competitive industrial power prices. 2025 Electricity Review — RTE
Germany faces the most difficult combination of scale and exposure because it remains a major industrial exporter while coal and gas supplied 38.2% of domestic net electricity generation in 2025, leaving carbon costs more deeply embedded in industrial electricity than in France. Destatis electricity generation 2025
Italy's principal vulnerability is not coal but the interaction between gas-fired generation, imported energy and industrial electricity costs, while rapid renewable growth and network expansion provide the main domestic counterweight. Terna electricity demand 2025
The United Kingdom is not converging toward the US approach: it continues to operate an ETS covering power and heavy industry and will introduce a CBAM in January 2027, thereby creating a second major European trade regime in which foreign carbon intensity and foreign carbon-price payments become commercially relevant. UK ETS Policy Overview UK Carbon Border Adjustment Mechanism
The most consequential medium-term issue is therefore industrial location rather than trade settlement alone: if US regions can offer abundant electricity, lower regulatory costs and attractive fiscal incentives while European producers face tightening carbon exposure, capital-intensive new industrial projects can shift geographically even where CBAM later neutralises part of the trade advantage.
What would change the assessment
The assessment would become materially more favourable to European competitiveness if EU and UK electricity prices converge downward toward US industrial power costs while preserving lower carbon intensity, because that would remove the principal non-CBAM component of the transatlantic cost differential.
The assessment would become more adverse if US federal deregulation produces sustained lower industrial electricity prices in coal- and gas-heavy regions while European ETS allowance costs rise and free allocation falls according to the scheduled CBAM trajectory.
A significant acceleration in French nuclear output, German renewable-plus-storage deployment, Italian grid integration or British low-carbon generation would weaken the transatlantic asymmetry by reducing the European power-cost component independently of carbon-border policy.
Conversely, weak CBAM enforcement, extensive reliance on default emissions values, data-quality problems or product-routing strategies that obscure high-carbon upstream production would materially weaken the effectiveness of the European border adjustment.
The most important trade indicator is not total EU-US trade but the evolution of US market share in iron and steel, aluminium, fertilisers, hydrogen and other energy-intensive value chains, together with investment announcements for new manufacturing capacity on either side of the Atlantic.
Open official record
The first unresolved official record is the actual 2026 CBAM certificate-price series and realised certificate surrender volumes, which will determine the effective financial burden on imports rather than merely the legal architecture of the regime.
The second is the country- and product-level distribution of actual CBAM liabilities on imports from the United States, because the mechanism depends on embedded emissions and deductible foreign carbon prices rather than on nationality alone.
The third is the realised impact of the progressive reduction in EU ETS free allocation after 2026, particularly in steel, aluminium, fertilisers, cement and hydrogen, where the theoretical protection of CBAM must be compared with actual production, investment and trade outcomes.
The fourth is the final operational methodology of the UK CBAM as it moves from legislation into live implementation on 1 January 2027, especially the calculation of sectoral rates, treatment of verified actual emissions and recognition of overseas carbon-price payments. CBAM Policy Summary — HMRC — Sep 2026
The fifth is the evolution of US state-level carbon pricing and facility-level carbon reporting, because a producer subject to a credible state carbon price can have a different EU or UK border-carbon treatment from a producer located in a state with no equivalent mechanism, meaning that “US carbon cost” will increasingly cease to be a single national variable.
Transatlantic Carbon Divergence and Implications for Europe: Trade Friction, Free Allocation Decay and Asymmetric Exposure
BLUF / Strategic Assessment: The Trump administration's dismantling of power-sector greenhouse-gas limits does not dismantle global or European carbon markets, but solidifies a structural, multi-speed transatlantic divergence. The European Union operates under an autonomous, legally binding trade-border architecture: Regulation (EU) 2023/956 entered its definitive financial phase on 1 January 2026, compelling importers of covered EITE goods (steel, aluminium, cement, fertilisers, hydrogen, electricity) to surrender CBAM certificates priced to the EU ETS. Because the U.S. lacks an explicit federal carbon price, American exporters receive zero Article 9 border deductions. Crucially, the competitive friction accelerates after 2026 as EU ETS free allocations for CBAM sectors decay rapidly under Directive (EU) 2023/959 (from 97.5% in 2026 down to 51.5% in 2030 and 0% by 2034). Exposure diverges across Europe: France (95.2% low-carbon electricity, 19.6 gCO₂e/kWh) leverages structural nuclear insulation; Germany (€2.5bn steel exports to the U.S., 38.2% residual coal/gas generation) faces acute industrial margin compression; Italy (153.1 TWh thermoelectric production) confronts gas-linked industrial tariff exposure; and the United Kingdom operates an independent UK ETS alongside its forthcoming 1 January 2027 CBAM.
EU Industrial Carbon Protection Decay: Free Allocation Factor (2025–2034)
EU CBAM Definitive Regime & Free Allocation Decay (Directive 2023/959)
Table 1: Comparative European Power-Sector Carbon Profiles & U.S. Exposure (2025/2026)
| Jurisdiction | Latest Official Generation Data | Grid Carbon Intensity | Primary Industrial Trade Exposure | Strategic Vulnerability / Stance |
|---|---|---|---|---|
| France | 547.5 TWh Output Nuclear: 373 TWh (68.1%), Low-carbon: 95.2% |
19.6 gCO₂e/kWh | Electro-intensive metallurgy, low-carbon aluminium, chemicals, and prospective green hydrogen. | Structural Insulator Demands strict CBAM enforcement |
| Germany | 438.2 TWh Grid Injection Renewables: 58.6%, Coal: 96.8 TWh (22.1%), Gas: 16.1% |
~340–380 gCO₂e/kWh | €2.5B steel and €419M aluminium exports to U.S. (Jan–Aug 2025); heavy machinery, automotive. | High Exposure Exposed to fossil-marginal prices |
| Italy | 311.3 TWh Demand Thermoelectric: 153.1 TWh, Solar: 44.3 TWh, Coal: 3.0 TWh |
~240–280 gCO₂e/kWh | Imported intermediate materials, specialized machinery, ceramics, glass, secondary steel fabrication. | Gas-Linked Drag High reliance on imported energy |
| United Kingdom | 73.3% Clean-Power Share Independent UK ETS; auction floor £28/t from Apr 2026 |
104 gCO₂e/kWh | Domestic heavy industry, steel, chemicals, fertiliser; preparing UK CBAM across 6 sectors for 2027. | Parallel Regime 2026 transition gap vulnerability |
Table 2: Statutory EU ETS Free Allocation Phase-Down for CBAM Sectors (2025–2034)
| Calendar Year | CBAM Factor Applied | Free Allocation Phased Out | CBAM Financial Status | Transatlantic Competitive Tension |
|---|---|---|---|---|
| 2025 | 100% | 0% | Transitional (Reporting only) | Baseline full protection for EU installations. |
| 2026 | 97.5% | 2.5% | Definitive (Certificates surrender) | Initial border fees; U.S. exporters pay full rate with zero credit. |
| 2027 | 95.0% | 5.0% | Definitive (Weekly pricing) | UK CBAM launches, establishing parallel British border rules. |
| 2028 | 90.0% | 10.0% | Definitive Full Operation | First notable exposure for marginal EU installations. |
| 2029 | 77.5% | 22.5% | Accelerated Phase-Down | Allocation cuts begin to outpace border protection. |
| 2030 | 51.5% | 48.5% | Allocation Cliff | Nearly half of free allocation removed; U.S. power savings widen cost gap. |
| 2031–2033 | 39.0% → 14.0% | 61.0% → 86.0% | Final Phase-Out Window | EU primary producers pay for nearly all domestic emissions. |
| 2034 onward | 0.0% | 100.0% | Zero Free Allowances | CBAM becomes the sole carbon-leakage mechanism for covered goods. |
Structural Pillars of Transatlantic Carbon Divergence
TWO LEAKAGE GEOMETRIES
IMPORT VS INVESTMENT- Import Substitution (Covered): CBAM assesses tariffs on raw and semi-finished materials (steel, aluminium, cement, fertilisers, hydrogen), offsetting embedded carbon price differentials at EU borders.
- Investment Diversion (Uncovered): CBAM does not cover finished machinery, consumer electronics, or data center services. Capital-intensive projects may locate in U.S. regions with lower regulatory compliance costs.
- Downstream Vulnerability: European manufacturers using EU-priced green steel face cost pressures against non-EU competitors exporting unadjusted finished goods.
FRANCE VS GERMANY PROFILES
19.6 VS 350 G/KWH- French Nuclear Asset: With 95.2% low-carbon generation and 19.6 gCO₂e/kWh grid intensity, France provides electro-intensive industry with low embedded emissions that limit CBAM exposure.
- German Fossil Marginality: Despite a 58.6% renewable share, 38.2% of German generation relies on coal (96.8 TWh) and gas (70.6 TWh), passing carbon costs into industrial power tariffs.
- Asymmetric Repercussions: U.S. power deregulation places more competitive pressure on German manufacturing exports than on French low-carbon production.
UK & ITALY PARALLELS
UK 2027 & TERNA GAS- UK CBAM Sequencing (2027): The UK operates its domestic ETS (auction reserve £28/t from April 2026) while implementing a CBAM on 1 January 2027, creating a 12-month window of potential exposure to unadjusted imports.
- Italian Grid Reliance: While domestic coal use dropped to 3.0 TWh in 2025, Italy relies on 153.1 TWh of thermoelectric generation (primarily gas) and imported power, leaving industrial margins sensitive to energy price shifts.
- Data Divide: UK and EU border adjustments require audited emissions disclosures, shifting data verification requirements onto importers as U.S. federal reporting requirements change.
Forensic Strategic Key Judgments: Transatlantic Divergence
Relative Advantage, Not Absolute Exemption
U.S. power deregulation can lower domestic electricity compliance costs, but does not provide an exemption from EU CBAM border adjustments on direct material exports entering Europe.
Zero Article 9 Offsets for U.S. Goods
Because the U.S. lacks an explicit federal carbon price, American exporters of covered goods face standard CBAM certificate surrender requirements without origin-country deductions.
Free Allocation Reduction Accelerates Post-2028
The primary competitiveness pressure emerges between 2029 and 2031, when EU free allocations fall from 90% to 51.5%, increasing domestic exposure to carbon pricing.
France Insulated by Low-Carbon Nuclear Baseload
With a grid emissions intensity of 19.6 gCO₂e/kWh and 95.2% low-carbon output in 2025, French electro-intensive manufacturing maintains low embedded emissions relative to fossil-heavy grids.
Germany Balances Trade Scale with Residual Fossil Costs
Exporting €2.5B in steel to the U.S. while relying on coal and gas for 38.2% of domestic generation leaves German heavy industry exposed to both U.S. competition and domestic carbon pricing.
Investment Diversion Across Uncovered Sectors
Because CBAM does not apply to finished manufactured products or computing infrastructure, lower U.S. energy compliance costs create incentives for data centers and finished goods to locate in the U.S.
Open Official Record Gaps
- Realized CBAM Certificate Prices: Published quarterly and weekly price trends for actual CBAM certificates purchased by EU importers in early definitive phases remain pending.
- Treatment of U.S. State-Level Systems: The European Commission has not issued formal guidance on whether allowance payments under California's Cap-and-Invest or RGGI qualify for Article 9 deductions.
- UK CBAM Sectoral Rate Rules: The detailed methodology for calculating embedded emissions and overseas deductions under the UK CBAM ahead of its 1 January 2027 start date remains under consultation.
- Downstream Product Leakage Evidence: Verified trade data quantifying capital or production relocation from Europe to the U.S. in finished manufacturing outside the CBAM scope is not yet established.


