



Scope: Brazil and the United States, with the Venezuela resource strategy used only where the verified official record establishes a relevant institutional comparison; principal period January–September 2026, with a five-year strategic horizon to September 2031.
Executive Summary / BLUF
The public record supports a narrower but more consequential conclusion than the proposition that Brazil is simply “next in line” for a U.S. resource seizure: Washington has constructed an unusually deep state-backed financial, commercial and industrial-security architecture around Brazil’s most strategically differentiated operating rare-earth asset, while Brazil has responded by creating a new sovereign screening regime capable of scrutinising future foreign control, foreign influence and strategic mineral-supply agreements.
USA Rare Earth completed its combination with Serra Verde on 3 September 2026, thirteen days before Brazil’s new Law No. 15,506 of 16 September 2026 entered into force. The transaction therefore predates the new screening system rather than remaining an acquisition awaiting approval. USA Rare Earth’s SEC filing confirms the completed merger, consisting of US$300 million in cash and 126,849,307 USAR shares.
The acquisition sits inside a much larger U.S. public-finance structure. The U.S. International Development Finance Corporation committed up to US$565 million to Serra Verde; the U.S. Department of War subsequently announced a US$750 million IBAS investment into the special-purpose vehicle supporting Serra Verde’s offtake, accompanied by a US$300 million Defense Logistics Agency purchase commitment and US$500 million of bank financing.
The commercial architecture is equally significant: official company filings describe an agreement committing 100% of Phase I production of neodymium, praseodymium, dysprosium and terbium-containing mixed rare-earth carbonate to a U.S.-backed special-purpose vehicle, with minimum price floors and a contractual duration extending until the earlier of delivery from 198 million metric tons of run-of-mine ore or twenty years after commercial operations commence.
Brazil’s policy response has fundamentally changed the legal environment for subsequent transactions. Law No. 15,506 and implementing Decree No. 13,118 empower the new CIMCE structure to scrutinise changes of corporate control, significant foreign participation or influence, international supply contracts affecting economic or geopolitical security, and transfers or encumbrances involving mineral rights.
What the verified official record does not yet establish is that Brazil has a settled legal basis for retrospectively annulling the already completed Serra Verde combination solely because the new regime was enacted afterwards. The decree preserves validly completed administrative acts in proceedings transferred to the new system, while neither the retrieved statute nor decree expressly states that completed pre-enactment corporate transactions automatically require retroactive re-authorisation.
The principal strategic judgment is therefore that Brazil is not simply an object of U.S. mineral acquisition policy; it has become a jurisdiction in which U.S. state capital, defence procurement, private ownership and long-duration offtake now confront a newly institutionalised Brazilian sovereignty and industrialisation policy. The resulting contest is more likely to concern the conditions governing production, export, processing, future ownership changes and domestic value addition than an uncomplicated reversal of the September transaction.
Brazil’s Rare-Earth Bargain Has Become a Test of Sovereignty, Not Ownership
Brazil’s dispute with the United States over Serra Verde is not fundamentally about who owns a mine; it is about who controls the industrial value created from minerals that remain constitutionally Brazilian. USA Rare Earth completed its acquisition of Serra Verde on 3 September 2026, thirteen days before Brazil enacted Law No. 15,506 and Decree No. 13,118, which created a new screening regime for foreign control, significant influence and strategic mineral-supply agreements. Washington, meanwhile, has already embedded the Goiás operation inside a state-supported supply architecture combining up to US$565 million of DFC financing, a US$750 million Department of War investment, a US$300 million Defense Logistics Agency purchase commitment and long-duration Phase I offtake. The immediate contest is therefore not over expropriation, but over whether Brazil can convert legal sovereignty into industrial bargaining power before the highest-value stages of the chain are locked abroad.
Washington has secured the flow, even without owning the resource
Brazil’s Constitution remains unambiguous: mineral resources belong to the Union, while authorised concessionaires own the product of lawful extraction. That distinction makes the political language of a foreign “resource grab” legally imprecise, because USA Rare Earth acquired Serra Verde as a corporate asset but did not acquire sovereign ownership of the Brazilian subsoil. Yet the commercial result is still strategically significant, because the Phase I supply structure gives a U.S.-backed vehicle access to 100% of the output containing neodymium, praseodymium, dysprosium and terbium, the four magnetic rare-earth elements at the centre of high-performance permanent-magnet supply.
The strength of the American position comes from the architecture surrounding that offtake. The U.S. International Development Finance Corporation authorised financing of up to US$565 million for Serra Verde, the Department of War announced a US$750 million IBAS investment into the purchasing structure on 24 August 2026, the Defense Logistics Agency added a US$300 million five-year purchase commitment, and a private bank committed up to US$500 million of revolving finance. The political relevance lies in the combination: capital risk, demand risk, liquidity risk and commodity-price risk are being reduced simultaneously rather than sequentially.
The price mechanism illustrates the point. Serra Verde disclosed contractual floor prices of US$110/kg for neodymium and praseodymium, US$575/kg for dysprosium and US$2,050/kg for terbium, with upside participation above the floor. These are not simply commercial protections; they make non-Chinese supply more financeable by reducing the probability that a weak price cycle kills production before downstream capacity is ready.
Brazil’s weakness is not geology but where the value chain stops
Brazil’s National Mining Agency reported 11.4 million tonnes of proved and probable rare-earth reserves for 2024, while the U.S. Geological Survey’s 2026 publication used a 21 million-tonne reserve estimate under a different methodology. Either measure places Brazil among the world’s major geological holders, but both conceal the more important industrial fact: Serra Verde was the country’s only commercial rare-earth operation at the time, and Brazil still lacked comparable scale in separation, metal production, alloys and permanent magnets.
Pela Ema’s strategic value is therefore disproportionate to its current volume. Serra Verde targets approximately 6,400 tonnes per year of rare-earth oxides by the end of 2027, and the deposit contains the four magnetic elements that matter most to high-performance NdFeB systems. Historical project documentation described 349 million tonnes of mineable reserves on a wet basis, an average 0.15% TREO grade and approximately 0.04% heavy rare-earth oxides, while the company has indicated a mine life of roughly 25 years.
The industrial asymmetry appears downstream. USA Rare Earth’s system links the Brazilian mine to operations and projects in the United States, United Kingdom and France: magnet production in Oklahoma, a planned 6,400-tonne-per-year magnet facility in South Carolina, metals and alloy capacity in the United Kingdom and France, and future U.S. mining and separation at Round Top in Texas. Brazil contributes the operating upstream asset; much of the announced higher-value transformation sits elsewhere. That is the economic core of the sovereignty dispute.
Brasília changed the rules after the acquisition had already closed
Law No. 15,506, enacted on 16 September 2026, did not prohibit foreign investment in mining. Instead, it created a much more consequential instrument: a screening system capable of reviewing direct and indirect control changes, significant foreign participation or influence, access to strategic geological information, international supply contracts affecting economic or geopolitical security, and transfers or encumbrances of mineral rights.
Decree No. 13,118 made that regime operational through the National Council for Industrialisation of Critical and Strategic Minerals, CIMCE. Its Executive Committee can approve a transaction, approve it subject to conditions, refuse homologation, open proceedings ex officio and impose precautionary or corrective measures. Defence, Foreign Affairs, Finance, Mines and Energy and industrial-policy authorities are represented in the structure, meaning that strategic-mineral transactions are no longer assessed solely through mining or competition law.
The change is substantial because it allows Brasília to examine control without relying on a majority-shareholding test alone. “Relevant participation” and “significant influence” are now legally meaningful categories, while international supply agreements themselves can become reviewable if they affect economic or geopolitical security. A future investor may therefore trigger scrutiny through board rights, financing covenants, exclusive offtake, veto powers or contractual dependence even without formal control.
Retroactivity is where Brazilian leverage meets constitutional limits
The timing of the Serra Verde acquisition matters more than the political rhetoric surrounding it. USA Rare Earth completed the transaction on 3 September 2026; Law No. 15,506 took effect on 16 September. The new statute contains no express clause automatically subjecting completed pre-enactment control transactions to retrospective homologation, while Brazil’s Constitution protects the perfected legal act, acquired rights and res judicata.
That does not make Serra Verde immune from future Brazilian regulation. It means that Brasília’s strongest legal tools are prospective rather than retrospective. Future ownership changes, contract amendments, Phase II expansion, financing arrangements, mining-title transfers, export obligations, traceability rules and public incentives can all create fresh regulatory hooks under the new regime. A future government could therefore alter the economics of the project without successfully cancelling the 3 September acquisition itself.
The distinction is critical. Reopening a completed acquisition solely because a later law imposed a different strategic standard would face a demanding constitutional challenge; conditioning a new expansion on domestic processing, traceability, local-content commitments or domestic supply stands on firmer legal ground because it regulates new or continuing conduct rather than erasing a perfected act.
Industrial policy gives Brazil leverage that ownership law alone never provided
Law No. 15,506 was designed to do more than screen capital. It authorised up to R$2 billion for the federal mineral guarantee fund, established mandatory contributions linked to innovation and financing mechanisms, and created fiscal credits of up to 20% of eligible expenditure for beneficiation and transformation, subject to annual ceilings of R$1 billion from 2030 through 2034. The policy can also make support conditional on Brazilian goods and services, domestic-market commitments and downstream investment.
This is where Brazil can change the negotiating balance without nationalisation. If future Serra Verde expansion requires federal approvals, fiscal support, financing or contractual modifications, Brasília can seek more separation, metallisation, alloy production or magnet manufacturing inside the country. The economic objective is not to prevent foreign capital from earning returns; it is to prevent Brazil from remaining an upstream supplier while the margins, patents, qualified labour and defence-industrial value migrate elsewhere.
Traceability strengthens that leverage. The new framework requires progressively denser information on origin, ownership chains, destination, processing degree, composition and beneficiaries. Once implemented, such data will allow the government to distinguish a diversified export chain from one in which strategic output becomes structurally dependent on a single foreign-controlled route.
Venezuela shows the same U.S. logic, but not the same legal risk
The Venezuelan oil arrangement announced by the White House in August 2026 demonstrates that Washington’s resource policy extends beyond rare earths. The administration described 100-year concessions covering 17 fields and approximately 65 billion barrels of proved reserves, a 35% Office of Strategic Capital interest in the corporate parent, U.S. rights to buy 20% of production at production cost and a right of first refusal over the remainder.
The parallel with Brazil lies in the mechanism: preferential access, public capital, long-duration rights and deliberate redirection of strategic resources toward U.S.-aligned supply. The difference lies in institutional durability. Brazil’s transaction exists within a functioning constitutional order, a competition authority, a mining regulator, a newly created strategic-screening body and judicial review. Venezuela’s arrangement carries a more fundamental sovereign-continuity risk because future disputes could reach the authority of the concession-granting institutions themselves.
Venezuela’s earlier petroleum nationalisations already produced years of ICSID litigation, including the Mobil and ConocoPhillips cases. Brazil, by contrast, has deliberately favoured investment-facilitation agreements rather than the conventional investor-State arbitration model and has no equivalent bilateral investment treaty with the United States in the dossier. Political risk therefore exists in both countries, but it will travel through different legal channels.
The next 24 months will decide whether this becomes partnership or litigation
By September 2028, the decisive evidence will not be campaign speeches but administrative acts. A stable Brazilian outcome would require CIMCE to develop predictable rules, CADE to resolve its examination of the acquisition and supply agreement without destabilising the transaction, and future expansion to proceed under conditions that increase domestic value creation. A negotiated Phase II that places more processing in Brazil would reduce political exposure because it would create industrial constituencies with an interest in continuity.
The opposite trajectory would begin if Brasília attempts to apply Law No. 15,506 retrospectively to completed ownership, if CIMCE seeks to reopen legacy contractual formation rather than regulate future conduct, if CADE imposes structural remedies or if future mineral-right decisions become instruments of political confrontation. Those steps would convert a difficult industrial negotiation into a constitutional and potentially international legal dispute.
The cost of inaction is therefore divided but not symmetrical. Brazil risks exporting strategic material while importing the highest-value technologies built from it; the United States risks mistaking contractual access for durable sovereignty-proof supply; Serra Verde risks being trapped between the two. Over the next 12–24 months, the government that moves first from rhetoric to enforceable industrial conditions will shape not only the future of one mine in Goiás but the commercial template for how Latin American critical minerals enter the U.S. security economy.
Navigational Index
Strategic asset and U.S. state-capital architecture
Why Serra Verde matters, how U.S. financing, ownership exposure, guaranteed demand and downstream industrial policy fit together, and where the Brazilian asset sits inside Washington’s wider non-Chinese rare-earth strategy.
Brazilian sovereignty, screening and industrial policy
What Brazil’s Constitution, Law No. 15,506 and Decree No. 13,118 actually permit; how the new CIMCE screening regime changes the rules for foreign capital; and why retroactivity remains the key unresolved legal issue.
Political-risk pathways and the hemispheric resource model
How Brazil differs legally and institutionally from Venezuela, where parallels in U.S. resource-security policy are genuine, where they are not, and what observable developments would determine whether Serra Verde becomes a stable cross-border supply arrangement or a prolonged sovereignty dispute.
Master Abstract
A strategic asset acquired before Brazil changed the rules
The Serra Verde transaction is important because it joins three characteristics that are rarely present simultaneously in a Western rare-earth project: current commercial production, meaningful exposure to heavy magnetic rare-earth elements and direct integration into a state-supported U.S. mine-to-magnet strategy. Serra Verde began commercial production at Pela Ema in Goiás in 2024, and the company states that the operation can supply neodymium, praseodymium, dysprosium and terbium, elements central to high-performance permanent magnets. U.S. Geological Survey data published in 2026 estimate Brazilian rare-earth mine production at approximately 2,000 tonnes REO equivalent in 2025 and national reserves at approximately 21 million tonnes, although Brazil’s own 2025 Mineral Summary used a lower 11.4 million-tonne proved-plus-probable reserve figure for 2024, reflecting differences in data vintage and reserve methodology that should not be combined as though they were identical measures.
The strategic distinction of Pela Ema lies less in Brazil’s aggregate geology than in the mine’s product mix and operational status. Serra Verde describes the operation as the first scaled producer outside Asia of the four principal magnetic rare-earth elements and projects annual output of approximately 6,400 tonnes of rare-earth oxides by the end of 2027; the earlier U.S. Geological Survey country review recorded an approximately 5,000-tonne-per-year full-ramp expectation, illustrating the project’s subsequent expansion assumptions rather than a contradiction in current realised production.
USA Rare Earth agreed to acquire Serra Verde in April 2026 and completed the combination on 3 September 2026. The relevant SEC record states that consideration consisted of US$300 million in cash plus 126,849,307 shares of USAR common stock. Before the acquisition closed, Serra Verde had already entered into a major DFC financing arrangement, while USA Rare Earth itself had secured separate U.S. Department of Commerce support of up to US$277 million in direct CHIPS incentives and US$1.3 billion in senior secured lending capacity for its U.S. mine-to-magnet projects. The result is not conventional foreign direct investment in isolation, but a corporate platform whose Brazilian upstream resource, U.S. mining project, American magnet capacity and European processing interests are tied to multiple U.S. public financing mechanisms.
Washington is securing supply through capital, demand and ownership rather than through a single instrument
The strongest evidence for an assertive American resource-security strategy is found not in rhetoric but in the cumulative structure of the transactions. DFC signed a US$565 million financing agreement for Serra Verde, and the company’s filings show that DFC received warrants associated with a 12% fully diluted equity interest in Serra Verde under specified transaction mechanics; those warrants were addressed at the closing of the merger.
A second layer is the Serra Verde offtake special-purpose vehicle. On 24 August 2026, the Department of War stated that its Economic Defense Unit, working with Industrial Base Policy, would provide a US$750 million investment through the Industrial Base Analysis and Sustainment program, while the Defense Logistics Agency would make a US$300 million purchase commitment and a money-center bank would provide US$500 million, creating a stated US$1.55 billion structure. The stated objective was to secure mixed rare-earth carbonate from Pela Ema for U.S. national-security and economic-security supply chains.
A third layer is the offtake itself. SEC filings describe purchase of 100% of Phase I production by US SIIE LLC, with guaranteed minimum prices for neodymium, praseodymium, dysprosium and terbium and mechanisms for sharing upside. The public filings describe a contractual term potentially extending to twenty years after the mine’s commercial-operation benchmark, whereas CADE’s May announcement characterised the arrangement as a 15-year supply agreement; that definitional difference should remain visible rather than be silently harmonised, because one source may be describing the commercial supply period while another reflects the underlying contractual termination provisions.
This architecture is analytically more important than the nationality of the acquiring company. It reduces several risks simultaneously: project-finance risk through public lending, commodity-price risk through floor pricing, demand risk through guaranteed purchases and geopolitical supply risk through control over a major non-Asian heavy-rare-earth source. It therefore resembles industrial mobilisation policy as much as ordinary mining investment.
Brazil answered with an investment-screening regime that did not exist when the deal was negotiated
Brazil’s constitutional baseline remains clear. Article 20 of the Constitution establishes mineral resources, including those in the subsoil, as assets of the Union; Article 176 distinguishes mineral deposits from ownership of the surface and provides that mining may be conducted through federal authorisation or concession by Brazilian nationals or companies constituted under Brazilian law with headquarters and administration in Brazil, while transfers of authorisations and concessions require prior consent from the granting authority. Foreign ultimate ownership was therefore not in itself constitutionally prohibited under the pre-existing framework.
The structural change came with Law No. 15,506 of 16 September 2026, which established the National Policy for Critical and Strategic Minerals and the National Council for Industrialisation of Critical and Strategic Minerals, or CIMCE. The statute expressly subjects the policy to principles of national sovereignty and public interest and creates a screening mechanism covering direct or indirect changes of control in companies holding relevant mineral rights, significant foreign participation or influence, access to strategically important geological information and international contracts capable of affecting Brazil’s economic or geopolitical security.
The implementing Decree No. 13,118, issued on the same date, makes the mechanism operational at institutional level. It authorises CIMCE to homologate changes of corporate control, international supply arrangements with strategic implications, significant foreign participation or influence, and alienation, assignment or encumbrance of relevant mining titles. Its Executive Committee can approve transactions without conditions, impose conditions, refuse homologation, open screening proceedings ex officio and adopt precautionary or corrective measures.
This is a substantial expansion of sovereign economic-screening capability, but its relationship with Serra Verde requires legal precision. The merger closed on 3 September, while the law entered into force on 16 September. The decree provides that administrative proceedings whose decision-making competence moves to CIMCE are transferred to the new secretariat but also states that acts validly performed are preserved. Neither the statute nor the decree retrieved in this assessment expressly declares that previously completed and legally effective corporate combinations become void merely because they would have required screening had they occurred later.
Accordingly, the new framework clearly strengthens Brazil’s leverage over future ownership changes, contract modifications, exports, mineral-right transactions, approvals, incentives and downstream industrial arrangements, while the proposition that it automatically provides a legal mechanism to reverse the 3 September merger remains unestablished on the official record reviewed here.
The Venezuela comparison is real at the level of U.S. statecraft, but not interchangeable in law
A comparison with Venezuela is analytically useful only if the substantial legal and institutional differences remain explicit. The White House announced on 31 August 2026 that Venezuelan interim authorities had granted North American Blue Energy Partners 100-year concessions covering 17 oil fields with approximately 65 billion barrels of proven reserves, while the company granted the U.S. government governance rights, a Department of War Office of Strategic Capital equity position and long-term U.S. offtake rights. Those are official U.S. claims about the arrangement and should not be treated as independent adjudication of the transaction’s validity under Venezuelan law.
The relevant parallel with Brazil is therefore one of policy mechanism rather than political status: in both cases the Trump administration has used or claimed state-financial instruments, privileged offtake, strategic-resource access and public-private structures to shift resource supply chains toward U.S.-aligned channels. The divergence is equally important. Brazil retains functioning constitutional, regulatory, judicial and competition institutions, its mining rights remain governed through Brazilian-law concessions and authorisations, and its Congress has just enacted a formal national screening regime. Venezuela’s current institutional and constitutional circumstances are fundamentally different and cannot be used as a template for predicting the enforceability or durability of the Brazilian arrangement.
The U.S. domestic-law architecture is itself heterogeneous. The Industrial Base Fund statute permits purchase commitments but states that such commitments generally may not extend more than ten years from the initial purchase, subject to specified statutory conditions; the Serra Verde arrangement is therefore structured through a special-purpose vehicle rather than described as a simple fifteen- or twenty-year direct Pentagon purchase contract.
The Office of Strategic Capital has a different statutory framework. The current text of 10 U.S.C. §149 expressly describes capital assistance principally through loans, loan guarantees and technical assistance rather than furnishing a general free-standing equity-investment mandate. That distinction is material when evaluating long-duration state equity arrangements announced elsewhere in U.S. resource strategy and is one reason why the exact statutory vehicle supporting each transaction matters more than the broad label “Pentagon investment.”
Key Evidence Table
| Indicator | Value/status | Reference date | Definition/scope | Issuer | Exact source |
|---|---|---|---|---|---|
| Serra Verde–USA Rare Earth combination | Completed | 3 Sep 2026 | Serra Verde merged into an indirect USAR subsidiary | USA Rare Earth / SEC | USA Rare Earth completion filing. |
| Transaction consideration | US$300m cash + 126,849,307 USAR shares | 3 Sep 2026 | Merger consideration before tax withholding and specified allocations | SEC | USA Rare Earth registration filing. |
| DFC facility for Serra Verde | Up to US$565m | 2026 | Long-term financing for optimisation and expansion of Pela Ema | U.S. DFC / SEC | DFC critical-minerals announcement and USAR filing. |
| Department of War SPV investment | US$750m | 24 Aug 2026 | IBAS-supported investment into US SIIE LLC structure | U.S. Department of War | Department of War release. |
| DLA purchase commitment | US$300m over five years | 24 Aug 2026 | Rare-earth product purchase commitment | Department of War / DLA | Department of War release. |
| Private-bank facility | US$500m | 24 Aug 2026 | Senior secured borrowing-base facility supporting SPV purchases | USAR filing | SEC exhibit. |
| Total announced SPV capitalisation | US$1.55bn | Aug 2026 | DoW + DLA + bank financing structure | DoW / USAR | Department of War and SEC disclosures. |
| Phase I offtake | 100% of Phase I production | 2026 | Nd, Pr, Dy and Tb-bearing mixed rare-earth carbonate | SEC | Serra Verde/USAR filing. |
| Brazilian rare-earth reserves, USGS vintage | 21 Mt | 2026 publication, 2025 estimate table | USGS world reserve methodology | USGS | Mineral Commodity Summaries 2026. |
| Brazilian proved + probable reserves, ANM vintage | 11.4 Mt | 2024 data | Brazilian ANM reserve classification | ANM | Sumário Mineral Brasileiro 2025. |
| Brazilian rare-earth mine output | 2,000 t REO equivalent | 2025 estimate | National mine production | USGS | Mineral Commodity Summaries 2026. |
| Serra Verde target output | 6,400 t/y REO by end-2027 | company target | Pela Ema planned annual production | Serra Verde | Serra Verde operations disclosure. |
| New Brazilian screening law | Law 15,506/2026 in force | 16 Sep 2026 | Critical and strategic minerals policy and screening system | Presidency of Brazil | Lei nº 15.506. |
| Screening implementing decree | Decree 13,118/2026 | 16 Sep 2026 | CIMCE structure, powers and procedures | Presidency of Brazil | Decreto nº 13.118. |
Competing Pathways
| Pathway | Diagnostic support | Disconfirming evidence | Indicators | Current standing |
|---|---|---|---|---|
| The existing Serra Verde structure survives substantially intact | Merger closed before Law 15,506 took effect; Brazilian Constitution permits mining by Brazilian-incorporated companies under federal authorisation; decree preserves validly completed administrative acts. | New screening powers extend to control, foreign influence and strategically sensitive supply contracts, giving Brazil substantial leverage over later actions. | CIMCE treatment of existing arrangements; ANM decisions; absence or presence of litigation; amendments to offtake terms. | Strongly supported as the current legal baseline, although not immune from future regulatory conditions. |
| Brazil leaves ownership intact but renegotiates economic substance | New law emphasises domestic processing, transformation, traceability, strategic security and national value addition; CIMCE can condition future screened transactions. | Existing contractual rights and pre-enactment corporate acts constrain arbitrary retrospective alteration. | Domestic separation/refining investment, local-processing requirements, export conditions, project eligibility decisions, renegotiated supply arrangements. | A credible medium-term pathway because it can increase Brazilian control without requiring cancellation of the merger. |
| The transaction or major elements are subjected to legal challenge | New policy expressly frames critical-mineral governance through sovereignty and public interest; foreign control and international supply agreements now fall within formal scrutiny. | No retrieved official instrument presently establishes automatic retroactive invalidity of the completed transaction. | STF proceedings, CIMCE ex-officio review, ANM title action, disputes over concession transfer, challenges to the offtake or DFC/SPV structure. | Legally possible as a dispute pathway, but the official record presently does not establish a completed governmental decision to unwind the merger. |
Principal Gaps and Watch Indicators
The most important unresolved issue is retroactivity. Law No. 15,506 and Decree No. 13,118 create powerful prospective screening authorities, but the official material retrieved in this assessment does not establish whether CIMCE will interpret those authorities as reaching corporate-control or supply arrangements completed before 16 September 2026, nor whether such an interpretation would survive judicial review. The first CIMCE decisions dealing with legacy agreements will therefore carry precedential weight well beyond Serra Verde.
A second gap concerns the final official disposition of CADE’s pre-closing administrative inquiry. CADE’s official May notice confirms that it opened an APAC to determine whether the merger and associated supply arrangements were concentrations requiring notification, but the official CADE page retrieved for this assessment records the opening rather than the final disposition. The completed SEC-recorded merger establishes that the transaction nevertheless closed on 3 September.
A third watchpoint is domestic value addition. Brazil’s new framework is explicitly constructed to encourage beneficiation, transformation, high-technology applications and local industrialisation rather than a model based solely on exporting mineral concentrate. Whether USAR locates separation, refining, metal-making or magnet-related capacity inside Brazil will therefore become a central indicator of whether the arrangement evolves into a bilateral industrial partnership or remains politically exposed as an export-oriented resource-security structure.
A fourth indicator is the implementation of the 100% Phase I offtake structure. The decisive questions are where material is separated, who ultimately receives the processed oxides and metals, how the floor-price mechanisms operate under future market conditions, and whether Brazilian authorities require domestic-market availability or downstream processing as a condition for later approvals or incentives.
A fifth indicator concerns U.S. public-law implementation. The Serra Verde architecture spans DFC lending, IBAS funding, DLA purchasing and a special-purpose vehicle, while USA Rare Earth separately receives CHIPS support from the Department of Commerce. Any congressional, appropriations, audit or judicial scrutiny of the statutory basis, duration or contingent liabilities associated with these mechanisms would affect the durability of the U.S. side of the arrangement even if Brazilian approvals remain stable.
Serra Verde Strategic-Control Architecture — September 2026
Brazilian sovereign layer
Union mineral ownershipFederal mining rights and ANM oversight
From 16 Sep 2026:
CIMCE screening of control, foreign influence and sensitive international supply arrangements.
Operating asset
Serra Verde / Pela Ema, GoiásCommercial production since 2024.
Magnetic rare-earth exposure includes Nd, Pr, Dy and Tb.
Company target: approximately 6,400 t/y REO by end-2027.
Capital and ownership layer
USA Rare EarthCombination closed 3 Sep 2026.
US$300m cash plus 126,849,307 USAR shares.
DFC facility: up to US$565m.
Security-of-supply layer
U.S.-backed SPVUS$750m DoW IBAS investment.
US$300m DLA purchase commitment.
US$500m bank facility.
100% Phase I offtake with price floors.
| Layer | Verified mechanism | Decision relevance |
|---|---|---|
| Brazil | Union ownership of mineral resources; new CIMCE screening regime | Brazil controls the legal framework governing mining rights, future corporate changes and strategic supply arrangements. |
| Serra Verde | Operating rare-earth mine producing magnetic rare-earth-bearing material | Provides a currently operating non-Asian source rather than a purely prospective deposit. |
| U.S. capital | DFC financing and USAR ownership | Reduces financing risk and embeds the asset in a wider mine-to-magnet platform. |
| U.S. demand | IBAS-backed SPV, DLA purchase commitment and 100% Phase I offtake | Reduces price and demand risk while directing supply toward a U.S.-aligned value chain. |
Sources: Constitution of Brazil, Art. 20 and Art. 176; Law No. 15,506/2026; Decree No. 13,118/2026; USA Rare Earth SEC filings; U.S. Department of War announcement of 24 August 2026; U.S. DFC disclosures. Monetary values are nominal U.S. dollars as announced by the respective issuers.
The evidence therefore supports a finding of strategic penetration through finance, ownership, offtake and industrial policy, but not the stronger proposition that the United States has acquired sovereign ownership of Brazil’s mineral resources. Under Brazil’s Constitution, the resources remain property of the Union, while the concessionaire owns the product of lawful extraction; the political and legal contest is consequently about who controls the operating company, where output is directed, where value is added and what conditions Brazil can impose on future decisions.
The most important change since the transaction was negotiated is that Brasília now possesses a dedicated institutional mechanism for answering those questions. Serra Verde therefore represents less the completion of a settled U.S. strategic acquisition than the opening case in a new Brazilian era of critical-mineral governance, in which previously permissive corporate-law and mining-law channels coexist with an explicit sovereign-security screening system. The durability of the U.S.-backed structure will depend not principally on campaign rhetoric but on how Brazil’s new authorities interpret legacy transactions, regulate future amendments and translate the statutory commitment to domestic industrialisation into enforceable conditions.
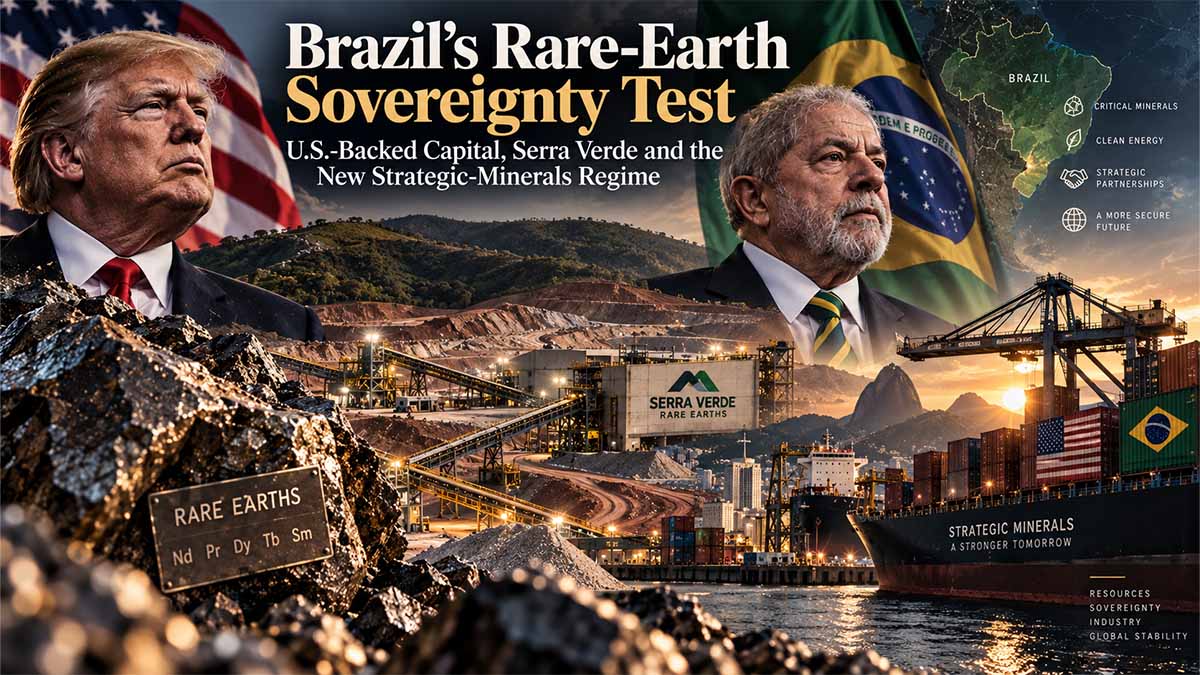
Brazil’s Rare-Earth Sovereignty Test: U.S.-Backed Capital, Serra Verde and the New Strategic-Minerals Regime
EXECUTIVE BLUF: USA Rare Earth completed its combination with Serra Verde on 3 September 2026 (for US$300M cash and 126,849,307 shares), exactly thirteen days before Brazil’s sweeping Law No. 15,506 and Decree No. 13,118 established the CIMCE screening regime on 16 September 2026. Backed by a US$1.55B SPV capitalisation (DoW IBAS, DLA, commercial bank debt) and a US$565M DFC facility, the structure commits 100% of Phase I magnetic carbonate (Nd, Pr, Dy, Tb) to U.S.-aligned defense supply chains for up to 20 years. Because the acquisition preceded enactment and the regulatory framework preserves validly completed administrative acts, Brasília lacks a clear statutory basis for retroactive annulment; the confrontation will manifest through domestic processing mandates, export licensing, environmental reviews, and conditional screening of subsequent corporate alterations.
Strategic Sovereign Stress & Exposure Index (Normalized 0–100 Scale)
U.S. State-Backed Capital Stack & Mine-to-Magnet Procurement
Primary Audited Evidence & Jurisprudential Baselines
VERIFIED DATASET: SEC • ANM • USGS • DIÁRIO OFICIAL DA UNIÃO| Parameter / Corporate Asset | Empirical Status / Value | Reference Date | Contractual / Regulatory Scope | Audited Issuer Source |
|---|---|---|---|---|
| USA Rare Earth – Serra Verde Merger | Completed Transaction | 3 Sep 2026 | Serra Verde merged into indirect USAR subsidiary; closed 13 days prior to Law 15,506. | SEC Form 8-K / USAR Filing |
| Merger Consideration Package | US$300M + 126.8M shares | 3 Sep 2026 | US$300M cash plus 126,849,307 shares of USAR common stock before tax withholdings. | SEC Registration Statement |
| DFC Project Financing Commitment | Up to US$565M | Pre-closing 2026 | Optimization and expansion of Pela Ema; includes 12% fully diluted equity warrants. | U.S. DFC / USAR Disclosures |
| DoW IBAS Defense Capital Allocation | US$750M Cash Injection | 24 Aug 2026 | Industrial Base Analysis and Sustainment award to US SIIE LLC for offtake financing. | U.S. Department of War Release |
| DLA Strategic Purchase Commitment | US$300M (5-Year Window) | 24 Aug 2026 | Defense Logistics Agency firm purchase obligation for critical magnetic REE carbonates. | Defense Logistics Agency / DoW |
| Private Money-Center Bank Facility | US$500M Borrowing Base | 24 Aug 2026 | Senior secured revolving facility underpinning aggregate US$1.55B SPV purchasing structure. | SEC Exhibit Filing |
| Pela Ema Phase I Offtake Lock | 100% Phase I Carbonate | 2026–2046 Horizon | All Nd, Pr, Dy, Tb mixed carbonate to US SIIE LLC; duration: 198 Mt ROM ore or 20 yrs. | SEC Offtake Contract Exhibit |
| Serra Verde Full-Ramp Production | 6,400 t/y REO Equivalent | By end-2027 | Target commercial capacity (USGS historical review baseline: 5,000 t/y). | Serra Verde Operations Report |
| Brazilian National REE Reserves | 21 Mt (USGS) / 11.4 Mt (ANM) | 2024–2026 Vintages | USGS estimates world reserves at 21 Mt; ANM certifies 11.4 Mt proved + probable. | USGS MCS 2026 / ANM Sumário |
| Brazilian REE Mine Output (2025) | 2,000 t REO Equivalent | 2025 Calendar Year | Realised domestic mine production following commercial startup of Pela Ema in 2024. | USGS Mineral Summaries 2026 |
Sovereign Screening, Governance & Comparative Jurisdictional Baselines
| Legal Instrument / Mechanism | Promulgation / Date | Core Mandate / Institutional Body | Operational Authority on Strategic Transactions | Jurisprudential Limit / Safeguard |
|---|---|---|---|---|
| Federal Constitution of Brazil | Articles 20 & 176 | Union Ownership of Subsoil Mineral Wealth | Concessionaire owns extracted product; concessions restricted to Brazilian-chartered firms. | Does not prohibit foreign indirect ownership of corporate equity. |
| Law No. 15,506 | 16 Sep 2026 | National Policy for Strategic Minerals | Creates screening mandate for foreign control, critical supply pacts, and mining title alienation. | Enacted 13 days after USAR–Serra Verde transaction closed. |
| Decree No. 13,118 | 16 Sep 2026 | CIMCE Operational Governance | Empowers Executive Committee to condition transactions, reject homologation, or open ex-officio reviews. | Expressly preserves validly executed past administrative acts. |
| CADE Antitrust Review | May 2026 Notice | Inquiry into Transaction Notification (APAC) | Scrutinised whether the merger and 15-year supply agreement constituted reportable concentration. | Merger proceeded to SEC-recorded closing on 3 September. |
| Venezuela Benchmark (NABEP) | 31 Aug 2026 | 100-Year Concession / DoW OSC Equity | U.S. statecraft: long-term offtake and governance rights over 65B barrels via executive fiat. | Non-interchangeable: Brazil maintains functioning judiciary & rule of law. |
Structural Transmission Vectors & Chokepoints
FORENSIC CROSS-VECTOR ANALYSISThe Temporal Shield
The transaction closed on 3 September 2026; Law No. 15,506 entered into force on 16 September. Decree No. 13,118 expressly protects validly completed past administrative acts. Under basic Brazilian constitutional principles of legal certainty (ato jurídico perfeito), retroactive voidance lacks positive statutory text.
Defense Capital Encirclement
The US$1.55B SPV (DoW IBAS, DLA, commercial bank) and US$565M DFC loan form a sovereign-backed buyer ring. Guaranteed floor prices and demand underwriting reduce market price exposure, transforming a commercial mine into an integrated asset of U.S. defense mobilization.
Export vs Beneficiation
Law 15,506 prioritizes domestic industrial transformation over raw concentrate extraction. The commitment of 100% of Phase I carbonate to the U.S. SPV clashes with CIMCE’s industrialisation mandate, creating a policy vector for export quotas or domestic processing requirements.
Institutional Divergence
Equating Brazil with Venezuela misreads structural legal reality. Venezuela’s 100-year concessions operate via interim executive fiat, whereas Brazil features a rigid subsoil ownership regime (CF Art. 20/176), an independent judiciary, and formal legislative scrutiny under CIMCE.
Forensic Strategic Key Judgments
ANALYTIC CONSENSUS • PROTOCOL BR-REE-2026USA Rare Earth closed the acquisition on 3 September 2026. Because Law No. 15,506 took effect on 16 September and Decree No. 13,118 preserves validly completed administrative acts, the merger stands as a legally consummated baseline.
The US$750M DoW IBAS injection, US$300M DLA purchase commitment, and US$565M DFC facility structure the Serra Verde offtake directly into the U.S. National Defense Stockpile, insulating the project from merchant price troughs.
The verified text of Law 15,506 and Decree 13,118 contains no explicit mechanism for retroactive cancellation of completed equity sales. Unilateral expropriation would provoke severe investor-state arbitration and constitutional challenges.
While ownership remains intact, CIMCE, ANM, and environmental agencies retain absolute authority over Phase II expansion licensing, water rights, mining concession transfers, and future corporate alterations.
Locking 100% of Pela Ema’s carbonate into U.S. export channels conflicts with Law 15,506’s statutory imperative to establish domestic separation, metal-making, and permanent magnet production within Brazil.
The equilibrium pathway is neither deal cancellation nor unconstrained export, but a renegotiated framework requiring USA Rare Earth to construct refining and separation facilities within Goiás in exchange for export permits.
Open Official Record Gaps
- CIMCE Jurisprudential Retroactivity: Absence of initial administrative rulings clarifying whether CIMCE will attempt to review pre-enactment contracts or limit scrutiny to prospective modifications.
- CADE Administrative Disposition: The official public registry records the May 2026 opening of the APAC inquiry into the merger and supply contracts, but does not provide a published final clearance decree.
- Contractual Term Discrepancy: Company SEC filings cite a supply term lasting until the earlier of 198 Mt ROM ore or 20 years, whereas CADE notices describe a 15-year supply agreement.
- U.S. Defense Statutory Scrutiny: Lack of published legal audits regarding 10 U.S.C. §149 equity constraints versus IBAS grant structures within the US SIIE LLC special-purpose vehicle.
Observable Watch Indicators
Strategic Asset and U.S. State-Capital Architecture
Principal judgment
Serra Verde matters to Washington not primarily because Brazil possesses a very large geological endowment of rare earths, but because Pela Ema is already producing material containing the four magnetic rare-earth elements most relevant to the permanent-magnet chain — neodymium, praseodymium, dysprosium and terbium — at a moment when much of the alternative Western project pipeline remains under development, financing, permitting or commissioning; the strategic value therefore lies in the conjunction of operating production, heavy-rare-earth content, expansion potential, comparatively straightforward ionic-clay mineralisation, long mine life and immediate integration into an American-controlled mine-to-magnet industrial platform, rather than in reserve size alone. The official Brazilian mineral assessment published in 2026 identifies Serra Verde as Brazil’s only commercial rare-earth operation at that point and explicitly describes the national challenge as moving beyond mining and concentrates into oxide separation, metals, alloys and permanent magnets, while USA Rare Earth’s SEC disclosures show that the acquisition is intended to connect the Brazilian upstream operation with separation, metallisation and magnet-manufacturing assets in the United States, United Kingdom and France. CETEM — Geopolítica e desenvolvimento tecnológico para a cadeia produtiva de terras raras no Brasil — 2026 USA Rare Earth — Form 10-Q, quarter ended 30 June 2026 — SEC
The resulting structure goes materially beyond a conventional foreign acquisition because distinct arms of the U.S. government are simultaneously supporting the upstream asset, underwriting the purchaser’s downstream industrial system and helping capitalise a vehicle that is contractually positioned to purchase Serra Verde’s Phase I magnetic rare-earth output; the official record therefore supports describing Serra Verde as an example of state-supported supply-chain integration, although it does not support describing Brazil’s mineral resources themselves as having been transferred to U.S. sovereign ownership. DFC financing supports the Brazilian mine, Department of War capital supports the offtake vehicle, the Defense Logistics Agency provides committed demand, the Department of Commerce finances American processing and magnet capacity, and private debt is inserted alongside public capital, creating an interconnected structure in which geological supply, project finance, commodity-price protection, working capital, processing capacity and end-market industrialisation are progressively de-risked by different instruments. U.S. Department of War — Department of War Announces a $750 Million Investment as Part of a $1.55 Billion Initiative to Secure Critical Rare-Earth Elements From Serra Verde — 24 Aug 2026 U.S. International Development Finance Corporation — DFC Highlights Landmark Critical Minerals Investments — 2026 U.S. Department of Commerce/NIST — CHIPS Program Finalizes Definitive Agreement With USA Rare Earth — 3 Jun 2026
Why Pela Ema occupies a disproportionately important position
Brazil’s national geological importance and Serra Verde’s corporate importance must be kept analytically separate, because national reserve statistics describe a much wider resource universe than the mineral inventory that can presently enter a commercial supply chain; Brazil’s National Mining Agency reported 11.4 million tonnes of proved and probable rare-earth reserves for 2024, equivalent to roughly 13.9% of the world total used in that Brazilian official comparison, but it simultaneously recorded that commercial beneficiated production remained embryonic and had only recently begun at Serra Verde in Minaçu, Goiás. The strategic asymmetry is therefore striking: Brazil possesses a globally significant geological position, yet its currently operating commercial rare-earth chain remains concentrated in one project, magnifying the significance of whichever industrial system captures Pela Ema’s output while competing Brazilian projects remain under development. ANM — Sumário Mineral Brasileiro 2025: Terras Raras
The deposit also differs technically from many conventional hard-rock rare-earth developments because Pela Ema consists of rare-earth ions adsorbed in weathered clays, with Serra Verde describing the ore as shallow, soft and comparatively amenable to lower-intensity mining, while the project’s environmental documentation records a historical mine plan based on 349 million tonnes of mineable reserves on a wet basis, an average 0.15% TREO grade, approximately 0.04% heavy rare-earth oxides, an average mineralised thickness of approximately five metres and a planned operating period of about 22 years in the underlying environmental design; current corporate disclosures, based on subsequent optimisation and reserve work, refer to an approximately 25-year mine life, so the two figures should be understood as different project vintages rather than treated as interchangeable estimates. DFC environmental repository — Relatório de Impacto Ambiental, Mineração de Terras Raras em Minaçu Goiás Serra Verde — Our Operation
| Pela Ema strategic parameter | Verified figure/status | Why it matters strategically | Evidence |
|---|---|---|---|
| Commercial production | Began in early 2024 | Removes much of the development-time risk inherent in pre-production projects | USA Rare Earth / SEC closing disclosure |
| End-2026 targeted run-rate | About 4,000 tpa TREO | Establishes intermediate ramp-up before full Phase I optimisation | USA Rare Earth / SEC |
| Phase I targeted average output | About 6,400 tpa TREO | Establishes commercially meaningful non-Asian supply | Serra Verde operations disclosure |
| Phase I full target timing | End 2027 | Aligns the Brazilian mine with expansion of U.S. processing and magnet capacity | Serra Verde / SEC |
| Possible Phase II | Potentially doubles run-of-mine production before 2030 | Creates optionality for materially larger strategic supply | Serra Verde |
| Magnetic elements in offtake | Nd, Pr, Dy, Tb | Covers all four principal magnetic rare-earth elements | SEC offtake disclosure |
| Earlier environmental-plan reserve | 349 Mt mineable reserve, wet basis | Indicates the physical scale of the orebody underlying long-duration operation | DFC-hosted RIMA |
| Historical average TREO grade | 0.15% | Low-grade bulk resource made viable by deposit geometry and processing characteristics | DFC-hosted RIMA |
| Historical average HREO grade | 0.04% | Heavy elements provide much of the strategic value despite lower volumetric abundance | DFC-hosted RIMA |
| Process-water recirculation | About 90%, company filing | Reduces freshwater intensity, although it does not eliminate environmental obligations | USA Rare Earth / SEC |
| Serra Verde workforce | About 350 employees plus roughly 260 contractors at end-2025 | Demonstrates an already functioning industrial operation rather than a prospective concession | USA Rare Earth / SEC |
The heavy elements are particularly consequential because dysprosium and terbium are normally used in much smaller quantities than neodymium and praseodymium but perform technically important functions in high-performance NdFeB magnet systems where elevated temperature resistance and coercivity are required; this means tonnage alone understates the geopolitical value of a mine capable of delivering those elements, particularly when downstream industries require secure supplies for aerospace, defence, semiconductors, advanced motors, robotics and other applications in which substitution or redesign can impose significant performance and qualification costs. The U.S. Department of Commerce’s own industrial programme identifies dysprosium and terbium among the critical materials to be processed through USA Rare Earth’s U.S. platform, while the company’s SEC filing identifies Pela Ema as the only mine outside Asia then capable, in its assessment, of supplying all four magnetic elements at scale. NIST — USA Rare Earth Texas project USA Rare Earth — Form 10-Q
The capital structure is designed to remove several risks simultaneously
DFC’s involvement begins at the mine level and is more substantial than an ordinary political endorsement, because the agency’s Board first approved US$465 million for the Pela Ema project and subsequently increased authorised financing to US$565 million, while expressly approving an equity-related instrument through warrants under its statutory equity authority; the official Board resolution therefore demonstrates that Washington’s involvement was intentionally structured to combine debt financing with potential equity exposure rather than simply provide development assistance. The facility supports optimisation of the existing mine, operating expenditures, refinancing and reserve accounts, and USA Rare Earth’s filing records an initial US$325 million drawdown on 6 March 2026, with the facility expected to extend to a 15-year term upon satisfaction of relevant conditions connected to the offtake framework. DFC Board Resolution BDR(26)01 USA Rare Earth / SEC transaction disclosure
The original DFC public-information documentation is also useful because it reveals the economic-development logic used to justify the transaction before the later geopolitical structure was fully assembled: DFC described the project as an improvement and optimisation programme for an existing brownfield operation, initially costed at approximately US$628 million, and cited an external market study suggesting that Pela Ema could account for approximately 10% of global heavy-rare-earth ore supply over its lifetime, although that figure is a project-study estimate rather than an observed market share and should therefore not be presented as current production. DFC — Board Notational Vote Notification, August 12 2025
The second risk-removal layer is the offtake agreement, which converts uncertain future sales into a long-duration take-or-pay structure covering 100% of Phase I output of Nd, Pr, Dy and Tb, meaning that the buyer carries a contractual purchase obligation subject to the agreement’s terms rather than leaving Serra Verde wholly exposed to spot-market demand; the SEC disclosure records termination at the earlier of delivery of material derived from 198 million tonnes of run-of-mine ore or twenty years after commercial operations commence, while other corporate and Brazilian competition-authority descriptions characterise the commercial arrangement as a 15-year agreement, a difference that appears to arise from how the operative commercial term and contractual outer termination mechanism are described and therefore should remain visible in any institutional assessment. SEC — Serra Verde offtake disclosure CADE — Cade apura acordos de combinação e de fornecimento em terras raras
Offtake price architecture
| Magnetic element | Contractual floor price disclosed by Serra Verde | Indicative non-China spot cited by company in Apr 2026 presentation | Difference above floor in cited snapshot | Strategic function of floor | Source |
|---|---|---|---|---|---|
| Neodymium | US$110/kg | ~US$140/kg | ~US$30/kg | Protects minimum upstream revenue while preserving market upside | SEC investor material |
| Praseodymium | US$110/kg | ~US$140/kg | ~US$30/kg | Reduces exposure to depressed market pricing | SEC investor material |
| Dysprosium | US$575/kg | ~US$1,100/kg | ~US$525/kg | Supports production of a scarce heavy-magnet input | SEC investor material |
| Terbium | US$2,050/kg | ~US$4,000/kg | ~US$1,950/kg | Provides unusually strong revenue protection for a high-value HREE | SEC investor material |
These comparison prices are not official government price benchmarks and should therefore be treated as company-presented April 2026 market observations rather than durable valuation assumptions, but the floor levels themselves are disclosed contractual terms and demonstrate the economic mechanism clearly: Washington is not only attempting to secure physical tonnage, it is helping create a pricing architecture intended to make non-Chinese production commercially sustainable even when market prices weaken, while Serra Verde retains exposure to a share of stronger prices. USA Rare Earth’s presentation states that the producer receives 70% of the excess of the relevant non-China index above the floor after separation costs, giving the contract characteristics of both downside insurance and upside sharing rather than a fixed-price procurement agreement. USA Rare Earth — SEC-filed transaction presentation
The distinction matters because one of the persistent economic problems in strategic-mineral diversification is that a new Western mine or separator must finance long-lived capital assets while competing against a market in which price signals can be volatile and where incumbent Asian capacity already benefits from infrastructure, scale, industrial clustering and downstream integration; a guaranteed floor does not eliminate operating, geological or execution risk, but it substantially changes bankability because project lenders and investors gain greater visibility over minimum revenue conditions. Serra Verde explicitly states that the take-or-pay mechanism and floors are intended to correct price signals that had constrained non-Asian heavy-rare-earth development, while the Department of War describes the transaction in national-security terms as establishing a secure supply chain. Serra Verde — SEC-filed release of 24 Aug 2026 Department of War — 24 Aug 2026
The US$1.55 billion SPV turns procurement into industrial policy
The offtake buyer, US SIIE LLC, is strategically important because it separates the purchase-and-financing architecture from the mining company itself and permits several sources of capital to converge inside one vehicle; on 24 August 2026 the Department of War announced a US$750 million IBAS investment in the SPV, the Defense Logistics Agency added a US$300 million purchase commitment, and a money-center bank committed up to US$500 million through a senior secured borrowing-base facility, bringing announced capitalisation and associated commitments to US$1.55 billion. Department of War — 24 Aug 2026 USA Rare Earth — Form 8-K exhibits, 24 Aug 2026
| US SIIE financing component | Amount | Instrument/function | Principal risk addressed | Official record |
|---|---|---|---|---|
| Department of War / IBAS | US$750m | Investment in SPV | Capitalisation and strategic purchasing capacity | Department of War |
| Defense Logistics Agency | US$300m | Five-year purchase commitment | Creates public-sector demand support | Department of War |
| Institutional bank | Up to US$500m | Senior secured borrowing-base revolving facility | Working capital for product purchases | USA Rare Earth SEC filing |
| Total announced structure | US$1.55bn | Public-private purchasing and financing platform | Combines capital, liquidity and demand | Department of War |
The architecture is therefore designed to solve a different problem at each stage: the DFC facility finances and optimises Brazilian production; the take-or-pay agreement protects Serra Verde against insufficient demand; the price floors mitigate downside commodity-price risk; the bank revolving facility provides the SPV with liquidity to purchase physical product; the DLA commitment introduces direct U.S. public-sector demand; and downstream CHIPS financing expands the American ability eventually to convert separated rare-earth material into metals, alloys and permanent magnets. This layering explains why examining any one programme in isolation understates the scale of U.S. state involvement, because the government is acting simultaneously as lender, potential equity participant, strategic investor, procurement counterparty and industrial-policy financier through legally distinct institutions. DFC Board Resolution Department of War NIST/CHIPS
Government exposure extends beyond Serra Verde itself
The U.S. government’s economic exposure to USA Rare Earth extends beyond the Brazilian asset because the Department of Commerce signed a definitive CHIPS agreement on 3 June 2026 providing up to US$277 million in direct incentives and up to US$1.3 billion in federally supported senior lending for the Round Top, Stillwater and Blacksburg projects, with Commerce also obtaining approximately 16.1 million USAR shares and a warrant covering another approximately 17.6 million shares under the arrangement. These instruments mean that the federal government’s interests are not limited to securing Brazilian mineral output; it is also financially exposed to the success of the U.S. corporate platform into which Serra Verde has been absorbed. NIST — CHIPS Program Finalizes Definitive Agreement With USA Rare Earth For Up To $1.6 Billion
The distinction between government investment in the mine, government investment in the SPV and government exposure to USA Rare Earth equity is important because they should not be collapsed into one ownership percentage: DFC approved warrants connected to Serra Verde, Commerce acquired or is entitled to acquire USAR securities under the CHIPS arrangement, and the Department of War invested in the offtake SPV, while each position has different legal rights, counterparties, valuation mechanics and statutory foundations. The documentary record therefore supports the broader conclusion that the United States has built multiple financial claims around the chain, but it does not support describing these separate instruments as one single federal equity stake in Serra Verde without qualification. DFC Board Resolution BDR(26)01 NIST/CHIPS definitive award Department of War SPV announcement
Public-sector support surrounding the combined platform
| Institution | Verified commitment or exposure | Target | Economic function |
|---|---|---|---|
| U.S. DFC | Up to US$565m debt plus authorised warrants | Pela Ema / Serra Verde | Mine optimisation, refinancing and expansion |
| Department of War / IBAS | US$750m | US SIIE SPV | Capitalises strategic offtake platform |
| Defense Logistics Agency | US$300m | SPV/product procurement | Creates guaranteed demand over five years |
| Department of Commerce / CHIPS | Up to US$277m direct funding | USAR U.S. projects | Industrial expansion |
| Department of Commerce-backed lending | Up to US$1.3bn | USAR U.S. projects | Long-duration project financing |
| Department of Commerce | Approx. 16.1m USAR shares + warrant for ~17.6m shares | USA Rare Earth | Equity-linked public participation |
| Private institutional bank | Up to US$500m | US SIIE | Revolving working capital |
| Private PIPE investors announced Jan 2026 | US$1.5bn | USA Rare Earth | Corporate expansion capital |
Sources: DFC, Department of War, NIST/Department of Commerce, and USA Rare Earth SEC disclosure.
These figures should not be summed mechanically into a supposed single “government investment total,” because they contain different instruments, beneficiaries and contingent commitments and because some facilities represent maximum authorised amounts rather than cash already disbursed; analytically, their significance lies instead in the breadth of the support architecture, which spans upstream extraction, commodity purchasing, liquidity, processing, metals, alloys and magnet manufacturing. The result is an industrial-policy system designed to reduce sequential investment risks that would otherwise be borne independently by miners, separators, metal makers and magnet producers. NIST — CHIPS final agreement DFC — Serra Verde financing
Serra Verde fills an immediate gap while Round Top remains a future asset
The acquisition is especially important because USA Rare Earth’s flagship Round Top deposit in Texas had not yet reached commercial production when Serra Verde was acquired, whereas Pela Ema was already shipping material; the Brazilian operation therefore provides current upstream feedstock, operating knowledge and near-term cash-generation potential while the U.S. mine continues through engineering and development. According to Commerce’s project documentation, Round Top is intended to support the extraction and processing of twelve critical and strategic minerals, while USA Rare Earth’s SEC filings expected commercial development later in the decade, making Serra Verde a bridge between the company’s present downstream ambitions and the future domestic U.S. mine. NIST — USA Rare Earth Texas project USA Rare Earth — Form 10-Q
This timing mismatch is strategically important because a vertically integrated magnet chain cannot be made operational merely by building a magnet factory: material has to move through mining, concentration, chemical separation into individual oxides, reduction or conversion into metals, alloy formation and strip casting before magnet fabrication, and each missing stage can become a bottleneck. Serra Verde therefore contributes something that Round Top could not yet supply in 2026 — commercial upstream material — while USA Rare Earth’s existing and planned assets supply or seek to supply the downstream transformations that Brazil itself still lacks at industrial scale. CETEM — Brazilian rare-earth-chain assessment USA Rare Earth — 2025 Form 10-K
From Minaçu to magnets: the emerging transatlantic chain
| Stage | Location | Operating/planned capacity or status | Function in combined chain | Official/company filing |
|---|---|---|---|---|
| Mining + concentration | Minaçu, Goiás, Brazil | Operating; Phase I targeted ~6,400 tpa TREO | Immediate Nd-Pr-Dy-Tb-bearing MREC source | SEC |
| Mining + future separation | Round Top, Texas | Development; company presentation cited ~4,300 tpa average REO output | Future U.S. heavy-REE source | SEC investor material |
| Separation demonstration | Wheat Ridge, Colorado | Operating demonstration facility from Jun 2026 | Tests Round Top, third-party MREC and recycling flowsheets | SEC 10-Q |
| Metals/alloys/strip casting | Cheshire, United Kingdom | Operating; SEC presentation cited up to 7,500 tpa potential capacity | Converts separated oxides into magnet feedstock | SEC presentation |
| Metals/alloys | Lacq, France | Planned expansion; earlier filing described 3,750 tpa plant plan | European metallisation and alloy node | SEC Q1 filing |
| Magnet manufacturing | Stillwater, Oklahoma | First production line commissioned Mar 2026 | Initial U.S. NdFeB manufacturing | SEC |
| Magnet + metal production | Blacksburg, South Carolina | Target 6,400 tpa magnets + 5,000 tpa metals/alloys | Major U.S. scale-up | SEC |
| Combined U.S. magnet target | Stillwater + Blacksburg | About 10,000 tpa NdFeB | Downstream anchor of U.S. mine-to-magnet strategy | NIST |
| Combined U.S. metal/alloy target | Stillwater + Blacksburg | About 10,000 tpa | Domestic feedstock for magnet manufacture | NIST |
The table also reveals a strategically important asymmetry for Brazil: the mine is Brazilian, but most of the currently announced higher-value transformation architecture is located abroad, particularly in the United States, United Kingdom and France, while the Brazilian project produces mixed rare-earth carbonate rather than separated oxides, metals, alloys or magnets. Brazil’s own official 2026 assessment identifies precisely this structural weakness, stating that the country remains concentrated in mining and concentrates and faces the challenge of advancing into separation, metal production, alloys and permanent magnets; the policy dispute surrounding Serra Verde is therefore not merely about ownership of an orebody, but about whether Brazil becomes an integrated technological producer or remains principally the upstream supplier to an industrial chain whose highest-value stages are external. CETEM — Geopolítica e desenvolvimento tecnológico para a cadeia produtiva de terras raras no Brasil
That distinction becomes even more consequential under the offtake because the buyer is contractually positioned to acquire the magnetic elements produced in Phase I and then resell the material to processors serving downstream markets; in other words, physical extraction takes place in Goiás, but the contractual architecture determines the direction in which the contained strategic elements enter the international processing system. The agreement does not, on the public record, require every kilogram eventually to be consumed by the U.S. military, and the SEC filing expressly contemplates resale to processors serving multiple end markets, so the defensible conclusion is that the arrangement secures U.S.-aligned control over the commercial route of the material, not that all Pela Ema production becomes direct Pentagon inventory. SEC — offtake disclosure
The industrial logic is diversification from China, not simple mineral accumulation
Washington’s strategy is best understood as an attempt to construct an alternative industrial ecosystem rather than simply accumulate mineral reserves, because rare-earth security depends less on geological abundance than on the capability to perform the successive chemical and metallurgical transformations that convert low-value concentrates into specification-grade materials. Commerce’s CHIPS award explicitly connects USA Rare Earth’s heavy-rare-earth production, metal and alloy facilities and 10,000-tpa NdFeB magnet objective to semiconductor, economic-security and national-security requirements, while the Department of War’s Serra Verde announcement describes the Brazilian transaction as an instrument for securing an alternative supply chain. NIST — CHIPS final award Department of War — Serra Verde investment
The acquisition therefore improves the American strategy in at least four distinct ways that should not be conflated: it supplies current feedstock before Round Top is operational; it supplies heavy magnetic elements, particularly Dy and Tb, that are strategically harder to diversify; it creates cash flow and commercial operating experience inside the combined company while U.S. assets are scaled; and it enlarges the feedstock pool available to processing and metallisation facilities being built in allied jurisdictions. USA Rare Earth consequently described the transaction as creating active capability across mining, processing, separation, metallisation and magnet making across three continents, and CADE independently recorded that the proposed multinational system involved eight operations in Brazil, the United States, France and the United Kingdom. USA Rare Earth — closing announcement filed with SEC CADE — 11 May 2026
Financial scale changes Serra Verde’s strategic position
Corporate projections filed with the SEC illustrate why Pela Ema can become more than a raw-material appendage within USA Rare Earth’s balance sheet, although such projections remain management forecasts rather than realised results: the April transaction presentation projected approximately US$550–650 million of annualised run-rate EBITDA by the end of 2027 for Serra Verde under an illustrative assumption of separated-oxide sales, using approximately 4,400 tonnes per year of TREO after lanthanum removal, an illustrative average basket price of approximately US$190/kg, and specified exchange-rate assumptions. The same presentation described approximately US$3.2 billion of pro-forma liquidity for the combined platform and projected around US$1.8 billion of annualised EBITDA by the end of 2030, but these forward-looking figures depend on production ramp-up, processing success, price assumptions, exchange rates and downstream execution and therefore should not be presented as verified future earnings. USA Rare Earth — SEC-filed April 2026 presentation
| Company forecast metric | Company-stated figure | Required qualification |
|---|---|---|
| Phase I TREO output | ~6,400 tpa | Target after optimisation, not current realised annual output |
| TREO after lanthanum removal used in EBITDA case | ~4,400 tpa | Company modelling assumption |
| Illustrative basket price | ~US$190/kg | Based on cited Dec 2025 external projections, not guaranteed market price |
| Serra Verde end-2027 run-rate EBITDA | US$550–650m | Forward-looking company projection |
| Combined company end-2030 annualised EBITDA | ~US$1.8bn | Forward-looking company projection |
| Pro-forma liquidity cited at transaction announcement | >US$3.2bn | Includes cash and access to milestone-dependent facilities |
Source: USA Rare Earth — SEC-filed transaction materials, April 2026.
The significance of those forecasts is not that they guarantee extraordinary profitability, but that the federal support architecture is directed toward turning a volatile mining project into a bankable industrial feedstock platform whose output is protected by contractual floors and connected to subsidised downstream capacity; this reduces the probability that weak spot prices alone will prevent expansion and gives the combined company stronger incentives to accelerate Phase I optimisation and potentially Phase II development. Serra Verde — April 2026 combination announcement
The Brazilian economic footprint is material but remains upstream-heavy
An official MME-supported 2026 study illustrates the scale of Minaçu’s potential local dependence on the project and provides an additional reason why the transaction has become politically important: its case study estimated approximately R$94.7 million of mineral production value for 2025 under the dataset used, compared with approximately R$484.3 million at the study’s assumed full-production case of 5,000 tonnes, while corresponding CFEM mineral royalties would rise from around R$1.89 million to approximately R$9.69 million; it also estimated that the project’s workforce represented a significant share of local formal employment. These figures are scenario calculations contained in an official-government-supported strategy study rather than audited Serra Verde financial statements, but they demonstrate the extent to which a nationally strategic mineral project can simultaneously become a locally important employer, royalty source and export generator. MME-supported Apoio à preparação da Estratégia Nacional de Terras Raras — 2026
| Minaçu impact variable in official strategy study | 2025 case | Study full-production case |
|---|---|---|
| Production assumption | 100 t | 5,000 t |
| Estimated production value | R$94.717m | R$484.250m |
| Estimated CFEM at 2% | R$1.894m | R$9.685m |
| Estimated municipal-revenue impact | 0.5% | 2.6% |
| Mineral exports cited for 2025 | US$12m / approx. R$66m | Not calculated in table |
Source: Brazilian Ministry of Mines and Energy-supported rare-earth strategy study — 2026.
The same study explicitly identifies the Serra Verde transaction as a concrete illustration of the strategic dilemma confronting Brazil: an operating Brazilian resource can receive foreign capital, guaranteed demand and access to an international industrial platform while the higher-value transformation stages migrate or remain abroad, thereby creating genuine economic benefits for the mine and host municipality but raising a separate national question about technological capture and domestic value addition. The relevant policy tension is therefore not adequately described as “foreign investment versus sovereignty”; it is more precisely a negotiation over which segments of the value chain Brazil retains, what technologies are internalised, what portion of output remains available to Brazilian industry, and how much downstream industrial capability develops domestically before long-term supply commitments become structurally entrenched. MME-supported national rare-earth strategy study
What the structure secures for the United States — and what it does not
The United States has gained a highly advantaged strategic position around Pela Ema because an American-listed company owns the operating platform, U.S. public finance underwrites important portions of the mine and downstream chain, and a U.S.-backed SPV possesses long-duration rights to the principal magnetic elements produced during Phase I; taken together, those instruments materially reduce the possibility that the mine’s output simply enters an open commodity market without any preferential U.S.-aligned commercial architecture. SEC — closing announcement SEC — offtake agreement
What Washington has not acquired is Brazilian sovereignty over the subsoil, an unrestricted legal entitlement to every future expansion of the mine, automatic ownership of Phase II output, or a contractual guarantee that all resulting rare-earth products will be processed exclusively in the United States; the available documents describe a Phase I offtake for defined magnetic elements and contemplate resale to processors and end markets, while future expansions, product forms, Brazilian regulatory decisions and downstream investment geography remain economically and legally consequential variables. This distinction is essential because the strategic architecture is powerful precisely because it uses ownership, capital and contracts within Brazil’s legal system rather than replacing that legal system. SEC — Serra Verde offtake terms CADE — rare-earth agreements investigation
Net assessment
The evidence supports the judgment that Serra Verde has become a strategic hinge asset in the U.S. attempt to build a non-Chinese heavy-rare-earth and permanent-magnet chain because it supplies an operating upstream source at precisely the point where the American system remains incomplete in separation, metals and magnets; the importance of the transaction therefore lies less in the monetary purchase price than in the fact that an already producing Brazilian mine has been inserted into an industrial platform whose financing, demand support, equity exposure and downstream capital expenditure are being underwritten through several arms of the U.S. government. DFC — Serra Verde investment NIST — USA Rare Earth CHIPS award Department of War — US SIIE
The deeper strategic contest consequently concerns industrial geography rather than simple mine ownership: if Pela Ema supplies concentrate while separation, metallisation, alloy production and magnet manufacture expand predominantly in the United States and allied European locations, Brazil will participate economically but capture a smaller share of the technological and industrial rents created by its mineral endowment; if, by contrast, Brasília succeeds in using regulatory approvals, incentives, infrastructure, financing and future expansion decisions to establish domestic separation and downstream manufacturing, the same foreign-capital structure could evolve into a more balanced bilateral industrial system rather than an upstream-export model. Brazil’s own 2026 technical assessment identifies this value-chain deficit as a central national weakness, making downstream localisation the most important economic indicator to follow after the acquisition itself. CETEM — Brazilian rare-earth value-chain assessment
Key judgments
Serra Verde’s strategic scarcity derives from readiness as much as geology. Many deposits can eventually produce rare earths, but Pela Ema is already operating and contains Nd, Pr, Dy and Tb, giving Washington access to physical material during the period in which Round Top and several downstream U.S. facilities remain in development. USA Rare Earth — SEC 10-Q
The U.S. structure is deliberately multi-instrumental. DFC debt and warrants, IBAS investment, DLA procurement, CHIPS grants and federal lending, government-linked equity exposure, private bank liquidity and a take-or-pay contract each address a different commercial vulnerability, collectively creating a level of supply-chain de-risking that a normal foreign mining acquisition would not possess. DFC Board Resolution Department of War NIST
Price floors are strategically as important as ownership. By insulating the producer against part of the downside associated with volatile rare-earth markets, the offtake increases the probability that a non-Asian heavy-rare-earth operation can remain commercially viable and expand even when market signals would otherwise discourage investment. SEC — offtake price disclosure
The decisive vulnerability for Brazil is the midstream and downstream gap. Official Brazilian analysis confirms that the country still lacks a mature domestic chain for separation, metals, alloys and permanent magnets at the scale implied by its resource endowment, while USA Rare Earth’s announced architecture places much of that value creation in the United States, United Kingdom and France. CETEM — 2026 assessment
The U.S. position is strong but not equivalent to sovereign ownership of the resource. Brazil continues to control the mining jurisdiction and the regulatory conditions under which production, concession rights, expansion, industrial policy and subsequent corporate decisions occur, while the U.S.-backed parties hold corporate, financial and contractual rights whose durability depends on that legal environment. CADE — official investigation record
What would change the assessment
The assessment would strengthen toward deeper U.S.-centred integration if Serra Verde Phase II were placed under a comparable long-duration U.S.-backed offtake, if material volumes began flowing systematically from Goiás into U.S. separation and magnet facilities, if additional Brazilian rare-earth assets were acquired by the same platform, or if U.S. agencies expanded procurement guarantees beyond the present structure; by contrast, the assessment would shift toward a more balanced Brazil–U.S. industrial partnership if significant oxide separation, metallisation, alloy or permanent-magnet capacity were committed inside Brazil and if future offtake agreements preserved substantial domestic industrial access. SEC — existing Phase I agreement CETEM — Brazilian downstream-policy challenge
A separate reassessment would be required if the announced U.S. downstream timetable materially slips, because the entire integration thesis assumes that mine output can ultimately be matched with non-Chinese separation, metallisation and magnet capacity; Stillwater has entered initial production, Blacksburg is targeted for commissioning beginning in 2028, Round Top remains a development project, and the European facilities are themselves at different stages of operation and expansion, meaning that the platform is strategically coherent but not yet fully mature across every production stage. USA Rare Earth — Q2 2026 Form 10-Q NIST — CHIPS award
Open official record
The most important records still required for a fully audited long-term assessment are the final complete financing schedules governing US SIIE, including detailed economic and governance rights attached to the Department of War investment; the unredacted commercial provisions governing resale destinations and separation arrangements for Serra Verde material; realised 2026 production and recovery data from the mine; the final disposition of CADE’s administrative procedure concerning the merger and supply arrangement; confirmed downstream destinations of the first deliveries under the new offtake; and any binding Phase II financing or supply arrangements, because these documents would establish how much strategic control derives from ownership and financing and how much derives from the actual physical routing of Brazilian rare-earth material. CADE — APAC announcement Department of War — announced SPV structure
Strategic Asset & U.S. State-Capital Architecture: Constructing the Non-Chinese Rare-Earth Hinge
EXECUTIVE BLUF: Washington's strategic capture of Serra Verde's Pela Ema operation in Minaçu, Goiás, is anchored in immediate operational readiness rather than aggregate geological endowment. While Brazil holds 11.4 Mt of proved plus probable reserves (13.9% of global reserves per ANM 2025), Pela Ema represents its only operating commercial mine, targeting 6,400 tpa TREO by end-2027 and uniquely yielding all four critical permanent-magnet elements (Nd, Pr, Dy, Tb). To insulate this critical upstream source while Round Top (Texas) develops, the U.S. state has deployed a layered multi-agency financing system: a US$565M DFC debt-and-warrant facility, a US$1.55B SPV (US SIIE LLC) backed by US$750M DoW IBAS capital, a US$300M DLA 5-year purchase commitment, and contractual floor prices guaranteeing 100% Phase I offtake for up to 20 years. This leaves Brazil facing a structural dilemma: exporting unseparated carbonate while high-value metallisation, oxide separation, and magnet capacity expand across the U.S., UK, and France.
Capital Allocation & Strategic Value Concentration Indices (0–100 Normalized Scale)
U.S. Multi-Agency Financing: Synchronizing Upstream, SPV & Downstream Assets
Primary Audited Evidence & Infrastructure Parameters
AUDITED SOURCES: SEC • DFC BDR(26)01 • DOW • NIST • CETEM 2026| Operational / Financial Metric | Audited Parameter Value | Reference Window | Contractual / Engineering Definition | Exact Source |
|---|---|---|---|---|
| Pela Ema Commercial Startup | Active Operation | Early 2024 | First commercial ionic clay REE producer outside Asia. | SEC Form 10-Q / USAR |
| Phase I Design Capacity | ~6,400 tpa TREO | By end-2027 | Target full ramp (intermediate run-rate: ~4,000 tpa by end-2026). | Serra Verde Disclosures |
| Take-or-Pay Phase I Scope | 100% Phase I MREC | 20-Year / 198 Mt ROM | Exclusive purchase of Nd, Pr, Dy, Tb mixed rare-earth carbonate. | SEC Offtake Agreement |
| DFC Total Approved Facility | Up to US$565M | Approved 2026 | Long-term debt + 12% fully diluted equity warrants; US$325M initial draw. | DFC Resolution BDR(26)01 |
| DoW IBAS Direct Capital | US$750M Cash Injection | 24 Aug 2026 | Capitalisation of US SIIE LLC offtake vehicle under defense authorities. | U.S. Department of War |
| DLA Guaranteed Demand | US$300M Commitment | 5-Year Term | Direct defense-logistics purchase commitment for refined carbonates. | Defense Logistics Agency |
| NIST/CHIPS Award to USAR | US$277M Direct + US$1.3B Debt | 3 Jun 2026 | Definitive funding for Round Top, Stillwater, and Blacksburg facilities. | NIST / Dept of Commerce |
| RIMA Environmental Reserve Base | 349 Mt (Wet Basis) | Historical EIA/RIMA | 0.15% TREO, 0.04% HREO, ~5m ore thickness, 90% water recirculation. | DFC RIMA Repository |
Contractual Floor Price Architecture & Market Upside Sharing
| Critical Magnetic Element | Contract Floor Price | Apr 2026 Non-China Spot | Floor Spread Premium | Upside Mechanism / Strategic Function |
|---|---|---|---|---|
| Neodymium (Nd) | US$110 / kg | ~US$140 / kg | +US$30 / kg (+27%) | Producer receives 70% of index excess above floor after separation costs. |
| Praseodymium (Pr) | US$110 / kg | ~US$140 / kg | +US$30 / kg (+27%) | Provides revenue floor stability during predatory market dumping episodes. |
| Dysprosium (Dy) | US$575 / kg | ~US$1,100 / kg | +US$525 / kg (+91%) | Heavy REE thermal stabiliser; secures project debt service under extreme pricing pressure. |
| Terbium (Tb) | US$2,050 / kg | ~US$4,000 / kg | +US$1,950 / kg (+95%) | High-coercivity military magnet alloy; guarantees long-term margin generation. |
Transatlantic Production Nodes & Midstream Chokepoints
INDUSTRIAL DECONSTRUCTIONMinaçu, Goiás (Brazil)
Operational ionic clay mining and beneficiation producing unseparated mixed rare-earth carbonate (MREC). Operates with ~350 direct employees, ~260 contractors, and 90% water recirculation, but lacks in-country separation infrastructure.
Wheat Ridge & Round Top (USA)
Demonstration separation plant in Colorado commissioned June 2026 to refine flowsheet designs. Round Top (Texas) targets ~4,300 tpa commercial REO separation late-decade, relying on Serra Verde for intermediate carbonate feed.
Cheshire (UK) & Lacq (FR)
Cheshire operates up to 7,500 tpa metal/alloy and strip-casting capacity. Planned Lacq expansion (3,750 tpa) provides European midstream conversion, ensuring separated oxides are transformed into master alloys outside China.
Stillwater & Blacksburg (USA)
Stillwater (Oklahoma) line commissioned March 2026. Blacksburg (South Carolina) targets 6,400 tpa NdFeB magnets plus 5,000 tpa alloys, achieving an aggregate U.S. domestic capacity of ~10,000 tpa magnets under CHIPS funding.
Forensic Strategic Key Judgments
ANALYTIC PROTOCOL • STATE-CAPITAL REE-2026Serra Verde matters not due to Brazilian reserve size alone, but because Pela Ema is actively producing Nd, Pr, Dy, and Tb while alternative Western hard-rock assets remain trapped in permitting and financing delays.
Washington is acting across five distinct roles: senior lender (DFC), equity-linked participant (DFC warrants, Commerce USAR shares), strategic buyer (DoW IBAS), procurement guarantor (DLA), and industrial subsidiser (CHIPS).
Contractual floor prices (Nd/Pr US$110/kg, Dy US$575/kg, Tb US$2,050/kg) pair with a 70% non-China index upside share to guarantee project bankability against predatory commodity price collapses.
CETEM 2026 analysis confirms Brazil remains restricted to mining and unseparated concentrates. Higher-value chemical separation, metallisation, and magnet fabrication are systematically sited in the U.S. and allied European nodes.
The U.S. has not seized Brazilian subsoil assets. Through US SIIE LLC's 20-year take-or-pay contract, Washington establishes preferential legal control over the international commercial destination of the extracted material.
Minaçu benefits locally via employment and CFEM mining royalties (projected at R$9.7M at full production per MME), but the Brazilian federation captures minimal technological rent without domestic industrialisation mandates.
Open Official Record Gaps
- US SIIE Operating & Resale Terms: Absence of unredacted governance agreements defining downstream processing destinations and third-party commercial margins for MREC acquired by the SPV.
- CADE Final Clearance Decree: The public register records the May 2026 APAC notification inquiry, but the final antitrust clearance text remains unpublished in the official repository.
- Realised 2026 Mine Recovery Data: Lack of certified quarterly metallurgical recovery rates for Dy and Tb from Pela Ema's commercial ion-exchange elution circuits.
- Phase II Financing Encumbrance: Unconfirmed whether Phase II expansion (doubling ROM throughput) is subject to right-of-first-refusal covenants by US SIIE or remains open to Brazilian state financing.
Observable Strategic Watch Indicators
Brazilian Sovereignty, Screening and Industrial Policy
Principal judgment
Brazil’s new critical-minerals regime represents a structural change in the legal treatment of strategic mining assets because it moves the country from a system in which foreign capital could generally acquire control of Brazilian mining companies, subject principally to ordinary corporate, competition and mining-title rules, toward a dedicated national-security and industrial-policy screening architecture capable of examining changes of corporate control, significant foreign participation or influence, access to strategic geological information, international supply agreements with possible geopolitical consequences, and transfers or encumbrances of mineral titles; however, the new framework does not establish an automatic statutory power to confiscate, cancel or retrospectively invalidate every foreign-controlled transaction concluded before 16 September 2026, and the absence of an explicit retroactivity provision is the central legal constraint on any attempt to reopen an already consummated acquisition solely because the political or strategic assessment of that transaction has subsequently changed. Brazil’s constitutional protections for the perfected legal act, acquired rights and judicial review, combined with the new law’s own express commitment to regulatory stability, legal certainty and predictability, mean that any retrospective intervention would require a more specific legal theory than the simple proposition that the transaction would now be screened differently under the new regime.
The significance of Law No. 15,506 of 16 September 2026 is therefore not that Brazil suddenly prohibited foreign ownership of critical-mineral companies, because it did not; the more consequential innovation is that foreign ownership and international supply commitments can now be subjected to an explicit sovereign-interest test when they involve designated critical or strategic minerals, thereby giving the federal executive a legal mechanism to attach conditions, require monitoring, refuse homologation or initiate screening ex officio in circumstances where earlier law had no comparable dedicated critical-minerals review system. The implementing Decree No. 13,118 of 16 September 2026 operationalises that authority through the National Council for Industrialisation of Critical and Strategic Minerals, or CIMCE, whose Executive Committee can approve an operation without conditions, approve it subject to conditions, refuse homologation, adopt precautionary measures, initiate screening on its own initiative and impose preventive or corrective measures, while the Plenary establishes policy criteria and the Secretariat performs the technical instruction of individual cases.
The legal result is a system much closer to strategic investment screening than to traditional mining regulation alone, although Brazil has constructed it through sector-specific mineral legislation rather than through a general economy-wide foreign-investment review mechanism. Its practical reach will depend on forthcoming CIMCE resolutions, thresholds and precedents, because several legally decisive expressions contained in the statute — including “participação relevante”, “influência significativa” and conditions capable of affecting “segurança econômica ou geopolítica” — remain broad statutory concepts rather than fully quantified thresholds in the legislation and decree currently in force.
The constitutional baseline preserves sovereignty without excluding foreign capital
Brazilian constitutional law begins from a distinction that is essential to any assessment of foreign control over mining assets: the mineral resource belongs to the Union, while the concessionaire owns the product lawfully extracted from the mine. Article 176 of the Constitution states that mineral deposits and other mineral resources constitute property distinct from the ownership of the surface and belong to the Union, while guaranteeing the concessionaire ownership of the product of mining; research and extraction require federal authorisation or concession and must be undertaken in the national interest by Brazilians or by companies incorporated under Brazilian law with headquarters and administration in Brazil.
This constitutional architecture means that foreign investors can control a Brazilian mining company without acquiring sovereign title to the minerals in situ. The legal entity holding the mineral rights must satisfy Brazilian incorporation, headquarters and administration requirements, but foreign capital is not generally prohibited from owning or controlling that company; the National Mining Agency explicitly confirms that foreign investors may establish Brazilian subsidiaries, acquire participation or control in existing Brazilian mining companies or participate through joint ventures, subject to Brazilian law.
That distinction matters because the sovereignty debate surrounding critical minerals is often framed too broadly. A transaction transferring shares in a Brazilian mining company does not transfer constitutional ownership of the underlying mineral resource itself, whereas a transfer or assignment of a mining authorisation or concession engages a separate legal layer because Article 176, paragraph 3, expressly states that mining authorisations and concessions cannot be assigned or transferred, wholly or partly, without prior approval of the granting authority.
The pre-September 2026 framework therefore already gave Brazil sovereign control over who could lawfully exploit the resource, but it did not subject every foreign acquisition of a Brazilian company holding critical-mineral rights to a separate national-security assessment. Law No. 15,506 adds that missing layer by making ownership structure, foreign influence and strategic supply contracts themselves objects of federal screening rather than leaving the relevant analysis dispersed among corporate law, mining-title law and competition regulation.
| Legal layer | Position before Law 15,506 | Position after Law 15,506 | Practical effect |
|---|---|---|---|
| Ownership of minerals in situ | Belongs to the Union | Unchanged | Foreign shareholders do not acquire sovereign ownership of the resource |
| Ownership of mined product | Belongs to lawful concessionaire | Unchanged | Commercial ownership begins after lawful extraction |
| Foreign ownership of mining company | Generally permitted through Brazilian-incorporated company | Still permitted | No general statutory ban on foreign capital |
| Transfer of mineral title | Requires prior consent of granting authority | Still required, plus CIMCE screening where covered | Adds strategic-security review |
| Corporate change of control | No dedicated critical-mineral sovereign screening mechanism | Subject to CIMCE homologation where covered | Foreign acquisitions now receive a strategic review layer |
| Significant foreign participation/influence | No dedicated mineral-specific screening test | Subject to homologation | Minority influence can become reviewable even without formal control |
| International supply agreements | Governed principally by contract, mining and competition law | Can be screened where economic or geopolitical security is implicated | Long-term offtake becomes a sovereign-policy issue |
| Access to strategic geological information | Governed through existing mining/data rules | Explicitly subject to screening where foreign entities are involved | Geological intelligence becomes an object of national-security policy |
Sources: Constitution of Brazil, Article 176; Law No. 15,506, Article 3; ANM guidance on foreign participation.
Law 15,506 converts critical minerals into a formal sovereignty category
The most consequential provision in the new statute is Article 3, paragraph 2, because it expressly subordinates the regulated activities to the principles of national sovereignty and supremacy of the public interest and establishes the legal basis for a screening mechanism operated through CIMCE and ANM. Four categories of transaction are expressly named: direct or indirect changes in corporate control of companies holding critical- or strategic-mineral rights; access to strategic geological information or relevant foreign participation or significant influence; international agreements or partnerships involving supply of covered minerals where the terms may affect Brazil’s economic or geopolitical security; and sale, assignment or encumbrance of mining titles granted by the Union.
The breadth of these categories is significant because they do not depend exclusively on majority ownership. A foreign investor can fall within the regime through “relevant participation” or “significant influence”, expressions that in corporate and regulatory practice can extend below formal control where governance rights, vetoes, board representation, financing structures or contractual dependencies provide material influence over strategic decisions, although Law No. 15,506 and Decree No. 13,118 do not yet prescribe a universal numerical percentage that automatically defines those concepts. This leaves substantial interpretive authority to future CIMCE normative acts and case decisions, which will determine whether the Brazilian system develops bright-line thresholds or a more discretionary substantive-control test.
The international-contract limb is potentially even broader because it captures agreements that affect economic or geopolitical security without requiring a transfer of shares. A long-duration offtake agreement could therefore become reviewable even if corporate ownership remains unchanged, particularly where the contract directs a large proportion of Brazilian production toward one external buyer, incorporates minimum-price or exclusive-purchase provisions, constrains domestic availability or creates long-term dependence on a foreign government-supported financing structure. The statute does not provide a closed list of prohibited contractual features, which means that future administrative practice will determine what combination of duration, volume, buyer concentration, destination, financing and strategic end use crosses the statutory threshold.
CIMCE is not merely advisory
The implementing decree confirms that CIMCE has operational decision-making authority rather than merely an advisory or policy-coordination role. Article 3 authorises it to homologate changes of corporate control, strategic international supply contracts, significant foreign participation or influence, access to strategic geological information and transfers or encumbrances of mineral rights, while Articles 4 through 14 establish a three-part internal structure separating policy formation, individual case decisions and technical instruction.
The Plenary is responsible for policy orientation, strategic planning and rulemaking, while the Executive Committee decides concrete transactions and the Executive Secretariat receives applications, coordinates technical submissions, consolidates evidence and prepares the files on which decisions are based. The separation is legally significant because Law No. 15,506 itself requires institutional segregation between policy formation and individual transaction review, an attempt to reduce the risk that strategic political priorities automatically become case decisions without an administrative record.
The Executive Committee contains representatives of the Ministry of Development, Industry, Trade and Services, Casa Civil, Science and Technology, Defence, Finance, Mines and Energy and Foreign Affairs, embedding economic, defence, industrial, fiscal, geological and diplomatic considerations directly into individual screening decisions. ANM can participate where its competencies are relevant but does not have a vote in the Executive Committee under the decree, although its technical opinion may be required as part of the evidentiary record.
| CIMCE body | Principal composition/function | Authority relevant to foreign investment |
|---|---|---|
| Plenary | Senior ministerial policy body | Establishes strategic criteria and general rules |
| Executive Committee | Seven federal institutions including Defence, Foreign Affairs, Finance, Mines and Energy and Industry | Decides individual screening cases |
| Executive Secretariat | Technical-administrative structure housed within MDIC | Receives filings, coordinates evidence, drafts conclusions |
| ANM | Mining regulator participating where competence is engaged | Supplies regulatory expertise and executes mining-law functions |
| AGU and other agencies | Can be invited where relevant | Provides legal or specialist input |
The composition shows why the new system differs from ordinary mining administration: national defence and foreign policy are now institutionally embedded in the review of critical-mineral transactions rather than appearing only through exceptional political intervention.
The Executive Committee can condition or refuse a transaction
The decree gives the Executive Committee four possible outcomes when examining a screened operation: a determination of non-incidence, unconditional homologation, conditional homologation or refusal of homologation. It can also impose monitoring obligations and accompanying measures, reopen or revise decisions under applicable law, and determine consequences for non-compliance.
This conditional-authorisation authority is likely to become the most important practical instrument of the regime because it allows Brazil to influence transactions without imposing a blanket prohibition on foreign capital. Conditions could conceivably concern governance rights, disclosure, access to geological data, continuity of domestic supply, downstream processing, transfer of technology, domestic availability, reporting, or restrictions on subsequent transfer, although the decree does not itself enumerate a definitive menu of remedies and any future conditions would have to remain within statutory authority, proportionality requirements and the specific administrative record of the case.
The committee also possesses precautionary authority, allowing it to adopt measures necessary to preserve the usefulness of a final decision, and can initiate screening procedures ex officio rather than waiting for the parties to submit a voluntary filing. This is a material enforcement power because it prevents parties from assuming that silence or non-notification automatically insulates an operation from scrutiny where the administration considers it to fall within the law.
| Executive Committee decision | Meaning | Likely consequence |
|---|---|---|
| Non-incidence | Operation falls outside screening rules | Transaction proceeds without CIMCE substantive approval |
| Unconditional homologation | No strategic objection identified | Transaction proceeds as submitted |
| Conditional homologation | Approval subject to obligations | Parties must comply with imposed safeguards |
| Non-homologation | Strategic approval refused | Transaction or covered act cannot lawfully proceed in approved form |
| Precautionary measure | Temporary action pending final decision | Can preserve status quo or prevent irreversible effects |
| Ex officio screening | Review initiated by government | Eliminates dependence on voluntary submission |
| Monitoring obligation | Continuing compliance requirements | Allows post-decision supervision |
| Corrective measure | Remedy for identified non-compliance | Can require modification or remediation |
Source: Decree No. 13,118, Article 10.
The new regime is not a general anti-foreign-investment statute
The law simultaneously strengthens sovereign screening and expressly preserves Brazil’s interest in attracting investment, which is important because it prevents the legislation from being accurately characterised as a simple nationalisation or exclusion statute. Article 3 requires implementation according to regulatory stability, legal certainty and predictability, while Articles 4 and 5 support national and international partnerships, official financing, international promotion of investment opportunities and participation in global markets.
The structure therefore creates a dual mandate: the government is expected both to attract foreign capital and to prevent strategic dependence that could undermine economic, technological or geopolitical security. This tension will have to be resolved through screening criteria rather than through a general nationality rule, because the law does not say that American, Chinese, European or other foreign investors are prohibited from acquiring critical-mineral projects simply because they are foreign.
The ANM itself had already clarified in April 2026, before passage of the new law, that foreign interest in Brazilian minerals should be understood within global supply-chain diversification and that Brazilian sovereignty remains protected because mineral resources belong to the Union, extraction depends on Brazilian authorisation, regulation is exercised by Brazilian institutions and foreign investment remains subject to national law.
Brazil has also created industrial leverage that extends beyond ownership screening
The most important change in Law No. 15,506 is not limited to reviewing investors because the statute also gives the state several economic-policy mechanisms capable of altering how mineral value chains are organised inside Brazil. Article 8 authorises future regulatory instruments connected to exports, including technical parameters, domestic value-add commitments, preferential treatment for projects that internalise important production stages, and mandatory disclosure of destination, final beneficiary, corporate chain, processing level, mineralogical composition and economic use of exported strategic minerals.
This provision creates a potential policy bridge between national-security screening and industrial localisation. Even where an existing foreign-controlled mining project remains legally protected, Brazil can prospectively influence the economics of later production and expansion through eligibility for public incentives, export conditions, project prioritisation, domestic-processing requirements and access to government financing, provided that implementing measures remain consistent with constitutional guarantees, statutory authority and applicable trade obligations.
The law also creates the Federal Programme for Beneficiation and Transformation of Critical and Strategic Minerals, under which eligibility can be made conditional on minimum use of Brazilian goods and services, commitments to make a share of production available to the domestic market, capital and operating expenditure requirements and other obligations linked to the objectives of the national policy.
Industrial-policy instruments created or reinforced by Law 15,506
| Instrument | Statutory mechanism | Quantitative parameter | Strategic purpose |
|---|---|---|---|
| FGAM | Federal mineral guarantee fund | Union authorised to contribute up to R$2bn | Reduce financing risk |
| Mandatory PD&I contribution | Percentage of net operating revenue from relevant mineral activities | 0.3% for first six years | Build domestic technological capability |
| Mandatory FGAM contribution | Percentage of relevant operating revenue | 0.2% for first six years | Capitalise risk-mitigation system |
| Later PD&I obligation | After six-year initial period | 0.5% | Maintain innovation funding |
| PFMCE credit | Fiscal support for beneficiation/transformation | Up to 20% of eligible expenditure | Move value creation downstream |
| Annual fiscal-credit ceiling | 2030–2034 | R$1bn per year | Support industrialisation |
| Domestic supply commitment | Possible PFMCE condition | No fixed statutory percentage yet | Protect Brazilian industrial access |
| Local-content requirement | Possible PFMCE condition | To be set by regulation | Build national industrial base |
| Export-related value-add commitments | Regulatory authority created by Article 8 | Thresholds not yet fixed | Discourage purely extractive export model |
| National project register | Mandatory CNPMCE registration | No monetary threshold | Centralise strategic project oversight |
Sources: Law No. 15,506, Articles 8–18 and 28.
The economic scale of these measures is significant. The Union is authorised to subscribe up to R$2 billion into FGAM, while fiscal credits for processing and transformation can reach R$1 billion annually from 2030 through 2034, producing a statutory maximum envelope of R$5 billion over that period before considering other financial instruments; the credits may equal up to 20% of eligible expenditure, directly favouring downstream processing rather than extraction alone.
The industrial-policy philosophy is therefore considerably broader than investment screening. Brazil is attempting simultaneously to regulate ownership, influence exports, create domestic technological capabilities, support financing, increase beneficiation, build traceability and preserve domestic access to strategic materials.
Traceability transforms mineral policy into transaction-level oversight
Law No. 15,506 creates a mandatory national traceability system covering the critical-mineral chain, and this mechanism could become particularly important for long-term foreign supply contracts because it requires recordability of material composition, quantity, origin, environmental impact, licensing, mineral title, responsible entity and extraction source; the statute further requires the compulsory registration of transactions and agents across the chain and allows technical systems capable of ensuring auditability and data integrity.
This is not simply an environmental certification measure. In strategic terms, traceability can provide the state with granular visibility over where covered material originates, who acquires it, how it moves through the chain and which commercial entities participate in the transaction, thereby improving enforcement capacity over future supply commitments and enabling government authorities to detect patterns of concentration or destination dependence that would otherwise be visible only through company reporting.
The obligation is therefore complementary to screening: screening reviews the legal structure of ownership and strategic contracts, while traceability increases visibility over their execution.
The legal protection of prior transactions is substantial but not absolute
The most important question for any already consummated transaction is temporal application. Article 51 of Law No. 15,506 states that the law entered into force on the date of publication, 16 September 2026, and contains no express clause declaring previously completed corporate-control transactions automatically subject to retrospective homologation.
Brazil’s Constitution directly protects the acquired right, perfected legal act and res judicata under Article 5, XXXVI, while Article 6 of the Law of Introduction to Brazilian Law provides that legislation has immediate and general effect but must respect the perfected legal act, acquired rights and final judgments, defining a perfected legal act as one already completed according to the law in force when it occurred.
These protections create a significant barrier against treating Law No. 15,506 as though it automatically invalidated a corporate transaction that had been validly completed under the earlier legal framework. The stronger legal distinction is between retroactive invalidation of a completed act and prospective regulation of continuing activities arising from that act, because the latter is generally easier for the state to justify where ongoing mining, exports, concession rights, corporate reorganisations, future financing, title transfers or contract amendments continue to require regulatory interaction after the new law enters into force.
Temporal application framework
| Legal situation | Exposure to new regime | Principal legal reasoning |
|---|---|---|
| Acquisition completed before 16 Sep 2026 | Retrospective review legally contested | Protection of perfected legal act and absence of express retroactivity |
| Acquisition signed before but closing after 16 Sep 2026 | Stronger case for screening | Change of control occurs after law enters into force |
| Future amendment to old acquisition structure | Potentially screenable | New legal act occurs under current law |
| Future transfer of mining title | Clearly within new framework | Article 3 expressly covers title transfer/encumbrance |
| New foreign financing conveying significant influence | Potentially screenable | Relevant participation/influence expressly covered |
| New strategic offtake agreement | Clearly within screening universe where statutory security test is met | International supply contracts expressly covered |
| Existing contract continuing after 16 Sep 2026 | Prospective regulation possible, retrospective annulment uncertain | Ongoing conduct differs legally from undoing completed formation |
| Future Phase II or expansion agreement | Strong screening exposure | New project decision and possibly new contractual structure |
| Export reporting and traceability obligations | Prospectively applicable once regulated | Continuing commercial activity after entry into force |
The distinction between a perfected transaction and continuing regulatory obligations is therefore the decisive legal issue. Ownership acquired before the law’s effective date may be constitutionally protected as a completed act, while subsequent exercises of rights connected to that ownership can still be governed by new laws of general and prospective application.
Decree 13,118 itself contains an important transition safeguard
The implementing decree strengthens the legal-certainty argument because Article 21 states that pending administrative proceedings whose decision-making competence transfers to CIMCE are to be forwarded to the new Executive Secretariat, while expressly preserving acts validly performed, documents produced, elapsed deadlines and procedural guarantees.
This transition clause does not resolve the retroactivity issue completely, because it concerns administrative proceedings rather than every private corporate transaction, but it demonstrates that the decree was drafted on the assumption that pre-existing legally valid acts should not simply be erased by institutional transfer to the new regime.
It also prevents the new authority from automatically restarting procedural clocks or disregarding administrative steps completed before 16 September, which will matter in any case where mining-title, competition or other federal proceedings were already under way when CIMCE acquired competence.
Retroactivity would require a specific legal theory
A future Brazilian administration seeking to revisit a pre-enactment transaction would therefore need to establish something more legally specific than a subsequent change in strategic preference. Several pathways are conceivable in principle, but they are analytically distinct and should not be conflated.
One pathway would be to argue that the transaction was never valid under the law applicable at the time, for example because a required mining-title consent, competition filing or other mandatory authorisation was absent; such a case would not rely on retroactive application of Law No. 15,506 but on pre-existing law.
A second pathway would be to identify a new post-16 September act — such as a contract amendment, title transfer, new financing arrangement, restructuring or expanded foreign influence — and subject that act to CIMCE screening without reopening the original acquisition itself.
A third pathway would be to regulate continuing conduct prospectively by imposing general export, traceability, domestic-processing or reporting requirements applicable to all covered projects under the new legislation.
A fourth pathway would be to argue that an existing international supply arrangement itself constitutes a continuing legal relationship whose post-enactment performance is subject to new sovereign-security regulation; this would raise substantially more complex questions about contractual rights, legitimate expectations, proportionality and compensation and would likely be more vulnerable to administrative or judicial challenge than prospective regulation of clearly new conduct.
The legal strength of these pathways differs materially, which is why the phrase “Brazil can reverse the deal under the new law” is too categorical on the presently available public record.
Administrative discretion is constrained by Brazilian public-law principles
Even where CIMCE has jurisdiction, it does not possess unlimited discretion. Federal administrative decision-making remains governed by Law No. 9,784, which requires legality, purpose, motivation, reasonableness, proportionality, due process, legal certainty, public interest and efficiency, and specifically prohibits imposing obligations or restrictions greater than those strictly necessary to achieve the public objective.
Administrative decisions affecting rights must state the factual and legal grounds supporting them, and decisions that annul, revoke, suspend or validate administrative acts require explicit, clear and coherent reasoning.
Decree No. 13,118 reinforces those safeguards by requiring Executive Committee decisions to be based on the evidentiary record prepared by the Secretariat and by requiring publication of decisions and identification of voting members, subject to legally protected confidentiality.
This creates several reviewable questions in any contested screening decision: whether CIMCE had statutory competence; whether the transaction actually fell within a screened category; whether the evidence established a genuine economic or geopolitical security concern; whether conditions were proportionate; whether similarly situated investors were treated consistently; and whether the reasoning was sufficiently documented.
Judicial review remains available
Article 5, XXXV of the Constitution provides that the law cannot exclude from judicial consideration an injury or threat to a right, meaning that CIMCE’s decisions remain subject to judicial review even though the executive possesses broad policy discretion in strategic minerals.
A company denied homologation or subjected to restrictive conditions could therefore challenge the decision on grounds including lack of competence, defective procedure, insufficient reasoning, disproportionality, improper retroactivity or violation of constitutional protections, while the government could defend the measure by invoking national sovereignty, public interest, national defence and the express statutory language of Law No. 15,506. The eventual jurisprudence will be decisive because the statute is only days old and no mature body of judicial interpretation yet exists.
CADE and CIMCE perform different functions
Brazil’s competition authority and the new critical-minerals council should not be treated as substitutes for one another. CADE opened an administrative procedure in May 2026 to determine whether the Serra Verde–USA Rare Earth business combination and associated supply arrangement constituted concentrations requiring notification and, if so, whether competition effects required review.
CIMCE’s mandate is different: its inquiry is not principally whether competition in a relevant market is substantially harmed, but whether foreign control, influence or international supply arrangements affect national sovereignty, economic security, geopolitical security or strategic industrial development.
| Authority | Core question | Legal focus |
|---|---|---|
| CADE | Does the transaction create a reviewable concentration and harm competition? | Antitrust and market structure |
| ANM | Are mineral rights, concessions and mining obligations legally compliant? | Mining regulation |
| CIMCE | Does the transaction or agreement affect strategic, economic or geopolitical security? | Sovereignty and industrial policy |
| Environmental authorities | Are environmental licensing obligations satisfied? | Environmental legality |
| Judiciary | Are administrative acts lawful and constitutional? | Judicial control |
The same transaction can therefore pass competition review and still encounter strategic screening, or receive CIMCE approval while remaining subject to mining-title or environmental obligations.
The regime reaches minority influence as well as formal takeovers
One of the most consequential innovations is the explicit reference to significant influence, because it means that future foreign investors cannot safely assume that staying below a majority shareholding threshold will necessarily remove them from the screening regime.
In practical terms, influence can be conveyed through board appointments, veto rights, reserved matters, financing covenants, exclusive purchase rights, pre-emption arrangements, technological dependence, information rights or contractual control over output, even where legal share ownership remains below 50%; however, no official CIMCE threshold currently defines which of those rights will be sufficient, so this remains one of the most important areas for forthcoming regulation.
This ambiguity gives the state flexibility but also creates a legal-certainty problem, which the Plenary will need to address through transparent criteria if Brazil wants to preserve the investment-attraction commitment contained in the same statute.
The law can shape supply contracts without nationalising production
The specific inclusion of international mineral-supply agreements in the screening system is particularly important because strategic control over a mine can be achieved economically without owning the mine itself. A buyer that possesses long-term rights to most or all output, guaranteed prices, financing links and contractual influence can affect the destination of strategic minerals even without majority equity ownership.
Law No. 15,506 therefore recognises economic dependence as a sovereignty issue rather than treating ownership percentage as the only relevant variable.
For future transactions, this gives Brazil the ability to examine several dimensions simultaneously:
| Contract characteristic | Potential screening relevance |
|---|---|
| Very long duration | Can lock strategic output into one foreign system |
| 100% or near-total output commitment | Can reduce domestic availability |
| Foreign-government-backed purchaser | Adds geopolitical dimension |
| Guaranteed floor pricing | Can strengthen dependence while improving project bankability |
| Exclusive processing destination | Can externalise downstream value addition |
| Buyer veto or approval rights | Can create significant influence |
| Financing tied to supply | Can integrate capital dependence with commercial control |
| Restriction on alternative buyers | Can narrow sovereign flexibility |
| Technology-transfer provisions | Can mitigate strategic concern |
| Domestic-market reservation | Can mitigate supply-security concern |
| Brazilian beneficiation commitments | Can reduce industrial-policy risk |
The important point is that Law No. 15,506 does not automatically prohibit any of these features; instead, it creates a mechanism through which government can assess their cumulative strategic effect.
The new industrial policy can alter bargaining power even without reopening old ownership
The strongest prospective Brazilian leverage may therefore come not from attempting to undo completed transactions but from controlling the environment in which future expansion occurs. Project eligibility for state support, domestic-processing incentives, export-related value-add requirements, mandatory traceability, future mineral-title transactions and access to priority status can all influence the economics of a foreign-controlled project.
This matters because mining projects require continuous regulatory interaction over decades; ownership may be fixed at one point in time, but expansions, financing rounds, new processing facilities, concession amendments, infrastructure, environmental approvals and new supply arrangements create repeated decision points at which the new regime can apply prospectively.
For Brazil, this is legally more defensible and economically more versatile than attempting to treat pre-existing foreign ownership as inherently unlawful.
Legislative timing should not be overstated
The parliamentary record shows that the underlying PL 2780/2024 was not created in September 2026 in response to one transaction; it originated earlier, passed the Chamber, reached the Senate in May 2026, was placed on the Senate agenda in late August, approved by the Senate on 2 September 2026, forwarded to the Presidency on 4 September, and sanctioned as Law No. 15,506 on 16 September 2026.
The timing nevertheless became strategically important because the final Senate approval occurred immediately before the closing of the Serra Verde combination on 3 September, but the official legislative record currently available does not by itself establish that Congress enacted the law specifically to annul that transaction. The safer documentary conclusion is that the legislation was already moving through Congress and reached final enactment during the same period in which foreign control and offtake of Brazilian rare-earth production became a much more politically salient issue.
That distinction matters because legislative chronology can demonstrate overlap but does not independently prove motive.
The new regime also creates a data-state around critical minerals
The National Register of Critical and Strategic Mineral Projects, or CNPMCE, is compulsory for projects implemented in Brazil and will consolidate data received from federal, state, municipal and district authorities into a public database integrated with SIGMINE; projects must be registered and CIMCE-authorised to benefit from policy incentives.
Combined with mandatory traceability, corporate-chain disclosure, destination reporting and beneficial-recipient information for exports, this creates a much denser information environment than existed previously.
| Data requirement | Strategic value to government |
|---|---|
| Corporate chain | Identifies ultimate foreign control |
| Final beneficiary | Reveals economic recipient |
| Export destination | Detects geographic concentration |
| Processing degree | Measures domestic value capture |
| Mineralogical composition | Tracks strategic content |
| Economic use | Links output to sensitive sectors |
| Transaction registration | Reconstructs supply-chain flows |
| Licence and mineral title | Links commercial activity to regulatory rights |
This information architecture may ultimately matter as much as formal veto authority because strategic screening depends on visibility; governments cannot effectively regulate foreign influence if ownership chains, contractual destinations and downstream processing arrangements remain opaque.
The strongest unresolved legal issues
Several questions remain open because the law and decree establish the framework but leave important thresholds and procedures to later regulation or precedent.
The first is the definition of “relevant participation”, because no general percentage is specified.
The second is “significant influence”, which could potentially capture financing or contractual rights below formal control but remains undefined.
The third is the threshold for determining when an international supply agreement affects economic or geopolitical security, which is the central substantive test for long-term offtake review.
The fourth is the treatment of contracts signed before 16 September but performed afterwards, particularly whether continuing deliveries are merely execution of a protected perfected contract or a continuing regulated activity subject to new prospective obligations.
The fifth is the scope of permissible conditional remedies, because the decree authorises conditions but does not yet provide a closed list of acceptable mitigation measures.
The sixth is the relationship between CIMCE decisions and already valid ANM mineral rights, especially where screening concerns a corporate shareholder rather than the concession itself.
The seventh is whether future CIMCE practice will differentiate among foreign sovereign investors, state-owned enterprises, private investors and government-backed financing structures.
The eighth is the extent to which export-related value-add conditions will be implemented and whether they will operate through incentives, regulatory approvals or mandatory commitments.
Retroactivity: current legal assessment
On the public record available as of 20 September 2026, the balance of legal evidence supports the conclusion that Law No. 15,506 applies immediately to new acts and continuing regulated conduct after 16 September, but does not expressly invalidate perfected transactions completed under prior law.
That conclusion is reinforced by four elements: the Constitution protects perfected legal acts; the Law of Introduction to Brazilian Law repeats that protection; the statute itself invokes legal certainty and predictability; and Decree No. 13,118 preserves validly completed procedural acts when jurisdiction moves to CIMCE.
It would therefore be legally inaccurate to state at this stage that the new law automatically empowers the executive to cancel a completed acquisition simply because it would now require homologation.
It would be equally inaccurate to conclude that a pre-existing transaction is immune from all future Brazilian regulation, because new corporate restructurings, title transfers, financing arrangements, contract modifications, exports, expansions, traceability obligations and project incentives can all create fresh jurisdictional hooks under the new regime.
Scenario matrix for an already completed foreign-controlled critical-mineral asset
| Government action | Legal difficulty | Principal basis | Main vulnerability |
|---|---|---|---|
| Apply reporting and traceability rules prospectively | Low to moderate | Continuing regulated activity | Proportionality and implementing-regulation issues |
| Screen future change of control | Low | Express statutory authority | Threshold definition |
| Screen future title transfer | Low | Express statutory authority | Mining-law procedure |
| Screen new offtake agreement | Low to moderate | Article 3 supply-contract authority | Security threshold must be justified |
| Condition future public incentives on domestic processing | Low | PFMCE and Article 8 | Must comply with implementing rules |
| Screen material amendment of legacy agreement | Moderate | New legal act after effective date | Whether amendment is sufficiently substantive |
| Regulate post-enactment performance of legacy contract | Moderate to high | Continuing public-interest regulation | Contractual rights, legal certainty, proportionality |
| Reopen completed acquisition solely under new law | High | Would require retrospective application | Constitution Art. 5 XXXVI and LINDB Art. 6 |
| Annul completed acquisition for defect existing under old law | Depends on evidence | Pre-existing legal violation | Government must prove original illegality |
| Expropriate or confiscate asset | Very high and legally distinct | Separate constitutional/statutory framework required | Compensation, due process, constitutional litigation |
This matrix explains why Brazil possesses considerable leverage without possessing unlimited retroactive authority.
Net assessment
Brazil has not closed the door to foreign capital; it has changed the constitutional and regulatory environment in which foreign capital obtains influence over strategic minerals. The core innovation is the shift from national ownership of the resource plus ordinary mining regulation to national ownership plus strategic screening of the corporate and contractual mechanisms that determine who controls production, information, financing and destination.
The state now possesses a sophisticated set of tools that can distinguish between beneficial foreign investment and strategic dependence rather than treating both as legally identical. CIMCE can examine the investor, the corporate structure, the supply contract and the mineral title; the industrial-policy provisions can influence domestic processing; the traceability system can follow material through the chain; and fiscal and financial incentives can reward projects that retain more value in Brazil.
The strongest legal limitation remains retroactivity. An attempt to apply the new regime automatically to invalidate a completed pre-16 September acquisition would confront constitutional and statutory protections that are materially stronger than the political argument for revisiting the transaction, whereas prospective regulation of future expansions, contract amendments, title changes, supply arrangements and industrial-policy benefits stands on considerably firmer legal ground.
The resulting balance is strategically important: Brazil now has far greater power to shape what happens next than it necessarily has to erase what has already happened.
Key judgments
Foreign ownership remains lawful, but it is no longer strategically neutral. Brazilian-incorporated mining companies may remain foreign controlled, yet control changes and significant foreign influence over critical-mineral assets can now be subjected to sovereign screening.
CIMCE is an approval authority, not merely a policy forum. It can approve, condition, refuse, monitor and initiate screening of covered transactions.
Supply contracts are now strategic-security instruments under Brazilian law. Long-duration international offtakes can be reviewed independently of corporate ownership where their terms affect economic or geopolitical security.
Industrial policy is inseparable from sovereignty policy. The statute provides up to R$2 billion for FGAM participation, up to 20% fiscal credits for eligible downstream expenditure, R$1 billion annual credit ceilings from 2030 to 2034 and possible conditions concerning domestic supply and local content.
Retroactivity remains the decisive unresolved legal constraint. No retrieved statutory provision automatically subjects completed pre-16 September control transactions to retrospective cancellation, while constitutional and general legal rules protect perfected legal acts.
The more defensible Brazilian strategy is prospective leverage rather than retroactive nullification. Future ownership changes, title transactions, expansions, new contracts, export obligations, incentives and downstream industrial commitments provide stronger legal hooks than reopening a consummated transaction solely under a later-enacted statute.
What would change the assessment
The legal assessment would change materially if CIMCE publishes a regulation expressly requiring notification of pre-existing transactions or legacy supply contracts, because such a measure would immediately create a justiciable dispute over statutory authority and constitutional retroactivity.
It would also change if the federal government identifies a defect under pre-existing mining, competition, corporate or administrative law, because a challenge based on original illegality would be legally different from a challenge based on retrospective application of Law No. 15,506.
A first CIMCE precedent involving a legacy foreign-controlled asset would be highly consequential because it would reveal how the government interprets “significant influence”, “relevant participation” and “economic or geopolitical security”.
Judicial review by the Federal Supreme Court or another competent federal court would become especially important if a company challenges conditional homologation, retroactive screening or restrictions on a pre-existing contract, because current statutory language alone does not resolve those constitutional boundaries.
Open official record
The most important missing official instruments are CIMCE’s internal rules, substantive screening thresholds, definitions of relevant participation and significant influence, procedural deadlines, filing obligations, confidentiality rules, penalty schedule for screening violations, criteria for economic and geopolitical security, methodology for conditional approvals, treatment of legacy contracts, implementation of Article 8 export-related requirements and the first published case precedents.
Until those instruments exist, the architecture of Brazilian strategic screening is legally established, but its operational boundaries remain only partially defined.
Brazilian Sovereignty, Screening & Industrial Policy: Constitutional Limits of Strategic Asset Oversight
EXECUTIVE BLUF: Law No. 15,506 and implementing Decree No. 13,118 (promulgated 16 September 2026) mark a structural shift in Brazilian administrative law, erecting a multi-ministerial screening mechanism under CIMCE to review corporate control, minority foreign influence, international offtakes, and mineral title transfers. However, the statute contains zero express retroactivity provisions. Bound by constitutional protections for perfected legal acts (ato jurídico perfeito, Art. 5, XXXVI) and LINDB Art. 6, Brasília cannot automatically unwind transactions consummated prior to 16 September (such as the 3 September USA Rare Earth–Serra Verde closing). Instead, Brazilian leverage shifts toward prospective operational controls: mandatory traceability, up to R$5B in downstream PFMCE fiscal credits (2030–2034), R$2B in FGAM guarantees, export value-add mandates, and screening subsequent expansions or corporate modifications.
Regulatory Rigidity & Enforcement Viability Indices (0–100 Scale)
CIMCE Statutory Architecture: National Security Screening of Critical Minerals
Primary Audited Evidence & Jurisprudential Baselines
VERIFIED TEXTS: CF/88 • LEI 15.506/2026 • DEC 13.118/2026 • LINDB| Legal / Operational Domain | Regime Prior to 16 Sep 2026 | Regime Under Law No. 15,506 | Practical Administrative Impact | Statutory / Legal Basis |
|---|---|---|---|---|
| Ownership of In-Situ Minerals | Belongs exclusively to the Union | Unchanged (Property of Union) | Foreign capital acquires corporate equity, never sovereign subsoil title. | CF/88 Art. 20, IX & Art. 176 |
| Ownership of Extracted Product | Concessionaire owns extracted ore | Unchanged (Concessionaire Property) | Commercial ownership commences after lawful extraction; subject to export rules. | CF/88 Art. 176, caput |
| Foreign Corporate Control | Permitted via Brazilian-chartered entity | Subject to CIMCE Homologation | Direct/indirect M&A requires prior security approval; no general nationality ban. | Law 15,506 Art. 3, §2, I |
| Minority Influence & Veto Rights | No mineral-specific screening | Screenable if "Significant Influence" | Board seats, vetoes, and financing covenants can trigger review without 51% control. | Law 15,506 Art. 3, §2, II |
| International Supply Agreements | Governed by commercial contract / CADE | Screenable for Geopolitical Security | Offtake pacts committing high-volume strategic ores abroad subject to federal review. | Law 15,506 Art. 3, §2, III |
| Transfer of Mining Concessions | ANM consent required (CF Art. 176, §3) | Dual Consent: ANM + CIMCE | Title assignment, encumbrance, or pledge requires security clearance. | Law 15,506 Art. 3, §2, IV |
| Geological Intelligence Access | Standard CPRM/ANM reporting rules | Regulated Sovereign Data Asset | Access to strategic subsoil data by foreign entities subject to national-security audit. | Law 15,506 Art. 3, §2, II |
Statutory Industrial Policy Levers, Financing Quotas & Fiscal Windows
| Policy Instrument | Statutory Mechanism | Quantitative Parameter | Temporal Window | Strategic Industrial Purpose |
|---|---|---|---|---|
| FGAM Mineral Guarantee Fund | Federal credit de-risking equity pool | Up to R$2.0 Billion | Immediate deployment | Mitigates credit and project-finance risk for domestic critical-mineral processing plants. |
| PFMCE Transformation Credit | Direct fiscal credit for domestic Capex | Up to 20% Eligible Capex | Horizon to 2034 | Subsidises industrial separation, metal reduction, and permanent-magnet fabrication. |
| PFMCE Annual Fiscal Cap | National treasury budgetary allocation | R$1.0B/yr (R$5.0B Max) | 2030–2034 Period | Underwrites commercial downstream transformation, offsetting competitive Asian scale advantages. |
| Mandatory PD&I Contribution | Levy on net operating mineral revenue | 0.3% (Initial) → 0.5% | Y1–Y6, then post-Y6 | Forces concessionaires to finance domestic technological R&D (CETEM, universities). |
| Mandatory FGAM Levy | Concessionaire operational contribution | 0.2% Net Mineral Revenue | Initial 6-year phase | Sustains national mineral guarantee reserves without permanent federal treasury transfers. |
Structural Transmission Vectors & Chokepoints
JURISPRUDENTIAL VECTOR DECONSTRUCTIONConstitutional Non-Retroactivity
CF Art. 5, XXXVI and LINDB Art. 6 establish absolute protection for perfected legal acts (atos jurídicos perfeitos). Because the merger closed on 3 September and Law 15,506 entered into force on 16 September, retroactive nullification would breach constitutional due process.
Continuing Conduct Jurisdiction
While completed acquisitions cannot be arbitrarily reopened, post-enactment operations, exports, and concession interactions fall under prospective jurisdiction. CIMCE can condition Phase II expansion permits, water usage, and environmental licences on local refining obligations.
Supply-Contract Geopolitics
Article 3, §2, III grants authority over international supply pacts threatening economic or geopolitical security. The 20-year commitment of 100% Phase I carbonate to a U.S. defense-backed vehicle (US SIIE LLC) creates statutory justification for federal export reviews.
Traceability as Surveillance
Mandatory registration within CNPMCE and transaction-level digital traceability convert raw mining logs into sovereign intelligence. Concessionaires must disclose corporate chains, beneficial owners, and physical mineral destinations, curbing opaque transfer pricing.
Forensic Strategic Key Judgments
ANALYTIC CONSENSUS • PROTOCOL SOV-BR-2026Law No. 15,506 removes critical minerals from standard corporate/concession law, establishing a dedicated national-security screening regime over ownership, minority influence, and international offtakes.
Neither Law 15,506 nor Decree 13,118 contains retroactive mandates. Article 5, XXXVI of the Constitution and LINDB Art. 6 protect perfected pre-enactment acquisitions, barring automatic cancellation.
CIMCE is an executive approval council, not an advisory panel. Its Executive Committee can approve, condition, or block transactions, initiate ex-officio reviews, and enforce preventative measures.
The framework establishes that control over a mine can occur via long-duration offtakes without majority equity ownership. Multi-year exclusive export contracts are now reviewable for geopolitical risk.
Brasília’s real leverage lies in conditioning future Phase II expansion licenses, export clearances, and access to the R$5B PFMCE fiscal credit pool on commitments to establish in-country chemical refining.
CIMCE decisions remain subject to judicial review under CF Art. 5, XXXV. Disproportionate or unmotivated restrictions risk invalidation under federal administrative due process requirements.
Open Official Record Gaps
- Statutory Threshold Definitions: Absence of published administrative regulations defining quantified percentage thresholds for "relevant participation" and "significant influence."
- Geopolitical Security Criteria: Lack of codified rubrics determining what volume or duration benchmarks trigger offtake intervention under Art. 3, §2, III.
- Treatment of Legacy Contracts: Unresolved administrative posture regarding whether continuous post-enactment export shipments constitute protected performance of a perfected contract.
- Article 8 Export Regulations: Forthcoming decrees establishing specific domestic value-add benchmarks, minimum in-country processing quotas, and export notification schedules.
Observable Strategic Watch Indicators
Political-Risk Pathways and the Hemispheric Resource Model
Principal judgment
Brazil and Venezuela are being drawn into the same broad U.S. strategic-resource doctrine, but the durability of the resulting arrangements cannot be assessed through a single “Latin American resource acquisition” model because the two transactions rest on radically different institutional foundations, legal histories and mechanisms of state authority; the genuine common denominator is Washington’s attempt to convert access to strategically important natural resources into long-duration, U.S.-aligned supply through combinations of government capital, contractual offtake, governance rights and industrial-policy intervention, whereas the principal difference is that the Brazilian arrangement operates inside a comparatively dense constitutional, regulatory, competition and judicial framework whose institutions remain capable of constraining both the foreign investor and the Brazilian executive, while the Venezuelan arrangement described by Washington depends on a post-crisis political and hydrocarbons architecture whose domestic legal validity cannot be independently established from the controlling Venezuelan record retrieved for this assessment. The White House itself describes the Venezuelan transaction as granting an American-linked operator 100-year concessions over seventeen fields containing approximately 65 billion barrels of proved reserves, accompanied by a 35% Office of Strategic Capital equity interest, guaranteed U.S. rights to purchase 20% of production at production cost, a right of first refusal over the remaining 80%, U.S. veto authority over board appointments and a requirement that a majority of directors be U.S. citizens; those propositions are verified as official U.S. statements about the deal, but they are not equivalent to independent verification that each provision is valid and enforceable under Venezuelan constitutional and hydrocarbons law.
Brazil consequently presents a different type of political risk from Venezuela: the dominant Brazilian risk is institutional contestation over the permissible scope of regulation, control, future expansion and supply-chain localisation, while the Venezuelan risk is more fundamental because future contestation can reach the legitimacy of the concession-granting authority, the domestic validity of the concession architecture, the treatment of foreign control, the relationship between new hydrocarbons legislation and earlier constitutional principles, and the enforceability of contractual protections after another political transition. The Brazilian dispute, if it intensifies, is therefore more likely to develop through administrative proceedings, competition review, statutory interpretation and judicial litigation; the Venezuelan dispute possesses a considerably stronger pathway toward sovereign repudiation, international arbitration, asset-enforcement proceedings and disputes over recognition of governmental authority, a pattern for which Venezuela’s earlier hydrocarbons nationalisations have already created extensive arbitral precedent.
The central strategic implication is that physical access is not equivalent to secure access. Washington can finance a mine, obtain a long-term supply contract or acquire extensive rights in an oil company, but the durability of those arrangements depends upon host-state legal authority, regulatory continuity, commercial legitimacy, domestic political acceptance and the statutory competence of the U.S. agencies providing capital; resource-security arrangements that are economically attractive but institutionally fragile can shift risk rather than eliminate it, substituting dependence on a foreign producer with dependence on contested contracts, political continuity and litigation outcomes.
One U.S. doctrine, two fundamentally different host-state systems
The most defensible comparison begins with the stated U.S. policy rather than with assumptions about motive, because Washington’s own official documents now describe critical-mineral and energy supply as national-security questions rather than ordinary commodity procurement. In January 2026 the President accepted a Commerce Department finding that processed critical-mineral imports threatened U.S. national security and noted that the United States was 100% net-import reliant for twelve critical minerals and at least 50% reliant for another twenty-nine, while a July executive order directed defence supply chains increasingly toward domestic and allied sources and sharply restricted future waivers for covered foreign-origin materials beginning in 2027.
This policy establishes the strategic context in which both Brazil and Venezuela are relevant: neither arrangement should be analysed merely as a commercial investment because the U.S. government itself identifies resource access, processing capacity and geographic diversification as defence-industrial objectives. The July 2026 presidential determination further declared recoverable critical minerals and materials to be industrial resources necessary for national defence and authorised action under the Defense Production Act, reinforcing the conclusion that mineral policy has been incorporated into the broader U.S. national-security system.
The host-country side is considerably less uniform. Brazil’s National Mining Agency states explicitly that Brazilian mineral resources remain property of the Union, that exploitation requires Brazilian authorisation, that regulatory authority remains national and that foreign investment remains subject to Brazilian law; the government therefore frames foreign strategic-mineral investment as compatible with sovereignty provided that the constitutional and regulatory system continues to control exploitation.
The Brazilian government’s new policy goes further by describing sovereignty, domestic beneficiation and industrialisation as express objectives of the critical-minerals regime enacted on 16 September, while the official Senate record shows that the legislation originated as PL 2780/2024, passed the Senate on 2 September 2026, reached the Presidency on 4 September and became Law No. 15,506 on 16 September, confirming that Brazil’s institutional response was constructed through ordinary bicameral legislation rather than through an emergency executive instrument directed at one company.
The Venezuelan transaction, by contrast, is described principally through the White House’s own account, which states that “interim authorities” granted NABEP 100-year concessions and that the concessions operate under a new hydrocarbons law adopted with U.S. support. Because the controlling Venezuelan legislative instrument and corresponding judicial interpretation could not be independently verified from an accessible official Venezuelan repository in the current research session, the legal validity of the concession structure under Venezuelan domestic law must remain an open record rather than being inferred from the U.S. description.
Comparative institutional architecture
| Dimension | Brazil | Venezuela arrangement described by Washington | Political-risk consequence |
|---|---|---|---|
| Sovereign resource ownership | Constitutionally vested in the Union | Domestic controlling rule requires separate Venezuelan verification | Brazilian sovereign title is institutionally clear; Venezuelan concession validity remains more dependent on the underlying domestic legal record |
| Foreign corporate participation | Permitted through Brazilian-law entities, now subject to strategic screening in covered cases | White House describes extensive foreign governance and economic rights | Brazil regulates foreign control without prohibiting it; Venezuela raises more fundamental questions concerning concession and governance validity |
| Transaction scrutiny | CADE, ANM, CIMCE and judiciary have distinct competencies | U.S. account emphasises interim authorities and new hydrocarbons framework | Brazil offers multiple institutional review points before or after strategic disputes |
| Competition authority | Independent statutory role through CADE | No comparable verified transaction-specific record retrieved | Brazil has an additional institutional constraint unrelated to political sovereignty |
| Dedicated strategic screening | Effective from 16 Sep 2026 | Not established from verified Venezuelan controlling text | Brazil has created an explicit mechanism rather than relying exclusively on political intervention |
| Judicial review | Constitutionally available | Formal court system exists, but controlling treatment of this concession has not been verified | Brazilian adverse action is more likely to be judicialised domestically |
| Government-change risk | Primarily implementation, regulation and litigation risk | Can extend to authority, concession validity and repudiation | Venezuela carries a deeper sovereign-continuity layer |
| Historic investment disputes | Brazil’s investment model emphasises prevention and State-to-State mechanisms | Venezuela has extensive ICSID history tied to expropriation disputes | Venezuela has more direct historical precedent for high-value sovereign asset litigation |
| Current ICSID Convention position | Brazil does not appear on the Convention signatory list used by ICSID | Venezuela denounced Convention effective 25 Jul 2012 | Dispute routes depend heavily on corporate structuring, treaty availability and contract clauses rather than simple host nationality |
| Public U.S. policy rationale | Secure non-adversarial mineral chains | Secure hemispheric oil control and exclude rival influence | Strategic objective converges even though legal vehicles differ |
Sources include Brazil’s mining regulator, Brazil’s legislative record, the White House’s Venezuelan transaction description and ICSID’s record of Venezuela’s denunciation.
The genuine hemispheric parallel is control over resource flows rather than territorial ownership
The strongest substantive parallel between the Brazilian and Venezuelan arrangements is not formal ownership of subsoil resources but control over the route by which those resources enter the international market. In Brazil, the key mechanism is a long-duration supply arrangement directing Phase I magnetic rare-earth output into a U.S.-backed purchasing structure; in Venezuela, according to the White House, the United States obtained a guaranteed right to purchase 20% of production at production cost and a right of first refusal over the remaining 80%, alongside board-level governance rights.
This distinction matters because modern resource security is increasingly built through contractual and financial architecture rather than sovereign annexation or direct state ownership of the resource itself. A government does not need formal title to an orebody or oil reservoir if it can influence capital formation, control the purchasing vehicle, secure preferential offtake, constrain alternative destinations, embed its companies downstream and establish governance rights over the entity commercialising production.
The mechanisms therefore differ in degree rather than category:
| Mechanism | Brazil rare-earth structure | Venezuela oil structure as described by White House | Strategic effect |
|---|---|---|---|
| Host-country subsoil ownership transferred to U.S. | No | White House does not claim transfer of Venezuelan sovereign title to subsurface reserves | Not required to achieve supply influence |
| Private operating company | Yes | Yes | Separates sovereign resource ownership from commercial operation |
| U.S. government financial involvement | Yes | Yes | Aligns public security policy with private project economics |
| Long-term resource access | Yes | Yes | Reduces spot-market exposure |
| Preferential U.S. offtake | Strong Phase I commitment | 20% guaranteed plus right of first refusal on remainder, according to White House | Directs resource flows |
| Government governance rights | Indirect and instrument-specific | Explicit board veto and citizenship requirements claimed by White House | Venezuela model creates deeper direct governance intervention |
| Government equity-like exposure | Multiple U.S. instruments around company/SPV | White House claims OSC receives 35% of corporate parent | Creates financial alignment with resource output |
| Domestic processing localisation in host country | Central Brazilian policy question | White House emphasises U.S. rigs, infrastructure and refineries | Both structures risk host-country concern over external value capture |
| Rival-state displacement objective | Explicit U.S. critical-mineral diversification policy | White House explicitly identifies Chinese and Russian displacement | Strong policy convergence |
The White House’s Venezuelan announcement is unusually explicit in describing geopolitical displacement as an objective, stating that many fields had previously involved Russian or Chinese operators and presenting the agreement as part of a strategy to reorient hemispheric resource flows toward the United States; that language is evidence of the U.S. administration’s stated policy, not independent proof of the conduct attributed to every previous operator.
The critical-minerals policy uses less territorially charged language but points toward the same supply-security objective: the July 2026 defence order requires stronger qualification of domestic and partner-nation critical-material sources and more comprehensive supply-chain mapping, while the January proclamation identifies import concentration and processing dependence as national-security vulnerabilities.
Brazil’s political risk is rule-intensive rather than authority-intensive
The defining feature of Brazilian risk is that several independent or semi-independent legal processes can affect the economics of the arrangement without requiring the federal government to repudiate the transaction outright. CADE has already demonstrated this institutional complexity by opening an administrative procedure specifically examining both the corporate combination and the fifteen-year supply agreement, while explicitly cautioning that initiation of the procedure did not itself establish a competition violation.
The new CIMCE system adds a different review dimension concerned with strategic security and industrial policy, while ANM remains responsible for mineral-right administration and the judiciary retains authority to review administrative legality. The result is a political-risk environment in which adverse outcomes can emerge incrementally through different legal channels rather than through one sovereign decision.
That produces five distinct Brazilian risk pathways.
Regulatory accretion
The first is regulatory accretion, in which ownership remains untouched but the economic environment changes because new traceability requirements, export information obligations, domestic-processing incentives, approval requirements or strategic conditions progressively increase compliance costs or alter the optimal destination of production.
This pathway can materially change project economics while remaining consistent with the continued legal existence of the foreign-owned company.
Conditional expansion
The second is conditional expansion, under which future project phases, new supply contracts, financing arrangements, corporate restructuring or mining-title modifications become bargaining points through which Brazil can demand domestic value addition or strategic safeguards.
The political importance of this pathway is that it requires no retrospective invalidation of the existing transaction; it uses future approvals to renegotiate the industrial balance prospectively.
Competition-law intervention
The third is competition intervention, where CADE determines that the combination of vertical integration, ownership and exclusive supply arrangements requires notification, remedies or another competition response. The authority’s May announcement confirms that it was examining whether the combination and supply contract constituted reportable concentration acts and whether competitive effects warranted further action.
Competition law is politically important precisely because it provides a non-sovereignty basis for modifying economic arrangements, meaning that intervention need not depend upon a government asserting national-security exceptionalism.
Administrative strategic review
The fourth is strategic screening of later conduct, where CIMCE applies the new law to a future amendment, ownership change, supply agreement or significant foreign influence arrangement.
This pathway is likely to generate disputes over statutory interpretation rather than over the existence of the Brazilian state’s authority itself.
Judicial escalation
The fifth is judicial escalation, in which an affected company challenges a regulatory or screening measure as retroactive, disproportionate, insufficiently reasoned or outside statutory competence.
Brazil’s institutional risk is therefore not necessarily low; instead, it is comparatively legible, because companies can identify regulators, statutory competencies, administrative procedures and judicial forums even when outcomes remain uncertain.
Venezuela presents a different sovereign-continuity problem
Venezuela’s historical investment-dispute record demonstrates how political decisions over hydrocarbons can become long-duration international legal disputes. ICSID records show that the Mobil/Venezuela proceeding concerned an oil and gas enterprise and resulted in an award in October 2014, while the ConocoPhillips proceedings concerning Venezuelan oil interests generated merits, quantum, rectification and annulment proceedings extending for years.
Those historical cases do not prove that the 2026 transaction will be repudiated, nor do they establish that present Venezuelan law is identical to the legal framework involved in earlier nationalisations; they do, however, demonstrate a concrete historical mechanism through which a change in state hydrocarbons policy can migrate from domestic intervention to international arbitration and then into prolonged enforcement proceedings.
Venezuela’s denunciation of the ICSID Convention took effect on 25 July 2012, meaning that any future dispute arising from a new 2026 transaction cannot simply be assumed to enjoy the same ICSID jurisdictional pathway that was available to qualifying earlier investors; the exact dispute mechanism would depend upon the investor’s nationality and corporate structure, applicable investment treaties, contractual arbitration provisions, governing law, waiver provisions and the continuing legal effect of any relevant instruments.
This is an important distinction because statements that a future Venezuelan government “would go to ICSID” are legally overbroad: ICSID jurisdiction requires a qualifying basis of consent and jurisdiction, while Venezuela’s withdrawal changed the Convention framework for new investments after 2012.
Past Venezuelan disputes establish enforcement risk, not merely arbitration risk
International arbitration is only one stage of sovereign investment conflict. ICSID’s own enforcement analysis records litigation surrounding the Mobil Cerro Negro award in U.S. courts and explains that enforcement against a foreign sovereign remains subject to the procedural requirements of the U.S. Foreign Sovereign Immunities Act, demonstrating that even a successful award can generate separate disputes over jurisdiction, service and sovereign assets.
The political-risk lesson is therefore wider than the possibility of expropriation: a contract can survive long enough to produce an award but still fail to provide investors with immediate economic recovery if enforcement assets are difficult to identify, sovereign immunity limits execution or multiple creditors compete for the same external assets.
For a 100-year hydrocarbons concession, this temporal mismatch is substantial because the legal and political environment will almost certainly change repeatedly over a century, while contractual enforcement mechanisms operate only after a dispute arises and cannot recreate the operational certainty of uninterrupted access to physical production.
The duration mismatch is itself a material political-risk variable
A 100-year oil concession necessarily extends across many electoral cycles, administrations, constitutional debates, fiscal crises, commodity cycles and technological transitions, while a fifteen- or twenty-year mineral offtake similarly outlasts the political leadership that negotiated it.
Duration increases economic attractiveness because it improves supply visibility and permits capital recovery, but it also increases political-risk exposure because future governments inherit commitments they did not negotiate.
Duration versus institutional risk
| Contract characteristic | Strategic benefit | Political-risk cost |
|---|---|---|
| Long concession period | Supports capital-intensive investment | Increases exposure to future political and constitutional change |
| Long offtake term | Reduces demand uncertainty | Creates future sovereignty and market-flexibility concerns |
| Guaranteed minimum price | Improves bankability | Can become politically controversial if market conditions move sharply |
| Government-backed buyer | Reduces counterparty risk | Politicises commercial relationship |
| Foreign-government governance rights | Protects foreign strategic interest | Raises host-country sovereignty sensitivity |
| U.S.-law contractual provisions | Improves predictability for U.S. counterparty | Does not automatically defeat mandatory host-state public law |
| Vertical integration | Increases supply reliability | Can trigger competition and domestic-value concerns |
| Exclusivity | Strengthens security of supply | Reduces host-state flexibility |
The fundamental legal point is that governing-law clauses cannot by themselves eliminate host-state public law. A contract governed by U.S. law can determine the rights and obligations between contracting parties, but it cannot automatically create mineral or hydrocarbons authority that the host government lacked under its constitution or mandatory legislation, nor can a U.S. court itself compel a sovereign foreign regulator to maintain a concession if the underlying public-law authority is successfully challenged.
This distinction is especially important for Venezuela because the White House specifically emphasises that the U.S. government agreement with NABEP is governed by U.S. law and subject to U.S. courts; that provision may strengthen contractual enforceability among the U.S.-side parties, but it does not by itself answer whether Venezuelan authorities possessed valid domestic authority to grant every concession and governance right described in the announcement.
U.S. public-law risk is different in Brazil and Venezuela
Host-country political risk is only half of the durability equation because both structures depend upon U.S. agencies whose statutory mandates are not identical.
The Office of Strategic Capital is established under 10 U.S.C. §149, and the statute currently authorises capital assistance expressly through mechanisms including loans and loan guarantees when appropriations are provided; the retrieved statutory language does not establish a general free-standing authority for OSC to acquire ordinary corporate equity.
This creates a significant legal question around the White House’s assertion that OSC received a 35% equity stake in the parent of the Venezuelan operator, because the public description of the transaction must be reconciled with the statutory authority under which the interest was accepted or held. The official record retrieved here does not supply that complete legal bridge, and the discrepancy therefore belongs in the open record rather than being resolved through inference.
The Brazilian rare-earth architecture involves a different Department of War programme and special-purpose vehicle rather than relying solely on OSC, but its long-duration purchase features must similarly be understood against statutory limitations applying to industrial-base procurement. U.S. law governing certain strategic-material purchases authorises unusual terms but generally limits purchase commitments to periods not extending more than ten years from the date on which the commitment was initially made, creating an obvious reason why long-horizon commercial structures may be routed through specially designed entities rather than a simple direct federal purchase commitment.
U.S. statutory-risk comparison
| Issue | Brazil structure | Venezuela structure | Risk implication |
|---|---|---|---|
| Principal defence mechanism identified publicly | IBAS/SPV and DLA procurement | OSC equity position claimed by White House | Different statutes govern ostensibly similar strategic objectives |
| Government equity issue | Located across distinct company/SPV instruments | White House claims direct 35% OSC interest in parent | Venezuela raises the sharper statutory-authority question |
| Long-term supply rights | Commercial structure longer than direct federal purchase horizon | 100-year concession plus long-duration U.S. rights | Both exceed normal political and appropriations horizons |
| Congressional dependency | Appropriations and programme authority remain relevant | OSC statutory scope and appropriations remain relevant | Future Congress can alter the U.S. institutional side without changing host-country law |
| Executive-policy dependency | High | High | Presidential policy can accelerate transactions but cannot permanently bind future congressional legislation |
| Direct sovereign governance rights | More limited/indirect | Extensive rights claimed by White House | Venezuela structure carries greater public-law novelty |
This does not establish that either U.S. arrangement is unlawful; it establishes that the durability of each depends upon the precise statutory instrument, appropriations authority and contractual implementation rather than simply upon a presidential announcement.
Congressional change is a separate political-risk pathway
A resource arrangement intended to survive multiple U.S. administrations must also survive multiple Congresses. Congress can modify appropriations, amend statutory authority, impose reporting requirements, limit agency programmes, prohibit particular transactions or investigate whether agencies exceeded existing authority.
This is particularly relevant where commitments extend longer than the statutory life of the programme or the ordinary appropriations cycle.
For investors, therefore, “U.S. government backed” does not mean “politically immutable”; it means that political risk is partly transferred from commodity markets and private financing to the continuity of federal statutory and appropriations support.
The most durable structures are those capable of surviving even if subsequent federal policy becomes less interventionist because the underlying mine, processor or oil operator remains commercially viable without continued extraordinary public support.
Brazil has a bilateral-management channel that Venezuela lacks in equivalent form
Brazil and the United States continue to maintain formal channels for economic engagement even amid disagreement. On 31 August 2026, Brazil’s Foreign Ministry and MDIC announced the resumption of ministerial trade dialogue with the United States over recent Section 301 measures, with both sides agreeing to continued technical negotiations, while Brazil explicitly stated that it sought an agreement based on dialogue and national sovereignty.
Separately, Brazil’s Ministry of Mines and Energy hosted U.S. congressional representatives in May 2026 specifically to discuss cooperation on critical and strategic minerals, rare earths and energy transition, demonstrating that mineral policy is not occurring solely through corporate transactions but also through formal intergovernmental engagement.
This matters for political-risk management because diplomatic channels permit disputed issues to be converted into negotiated industrial-policy packages, technical cooperation or revised investment conditions before they become litigation.
Brazil’s institutional posture therefore contains both resistance and cooperation: the government has strengthened sovereign screening while maintaining mineral dialogue with Washington.
That combination makes a negotiated recalibration more institutionally plausible than a binary choice between passive acceptance and outright cancellation.
Brazil’s investment-treaty structure also changes investor leverage
Brazil deliberately developed the Agreement on Cooperation and Facilitation of Investments, or ACFI, as an alternative to older investment treaties centred on investor–State arbitration. The Brazilian government describes the model as focusing on risk mitigation, institutional governance and dispute prevention while preserving regulatory policy space, and its current list of ACFI partners does not include the United States.
This is highly relevant to a U.S. investor assessing political risk in Brazil because it means that the existence of a U.S.-controlled Brazilian asset does not, merely by virtue of U.S. ownership, create a standard Brazil–United States bilateral investment treaty with conventional investor–State arbitration rights.
Any international arbitral protection would therefore depend on the precise corporate structure, contracts, applicable treaties involving intermediate holding companies, arbitration clauses and other jurisdictional facts.
The risk profile is consequently different from the assumption that every adverse Brazilian regulatory act automatically creates a treaty claim enforceable through ICSID.
Venezuela’s arbitration history makes corporate structuring decisive
Earlier Venezuelan petroleum investors frequently relied on treaty structures involving jurisdictions such as the Netherlands, as reflected in the ICSID Mobil case, where the invoked instruments included the Netherlands–Venezuela bilateral investment treaty as well as Venezuelan investment law.
That history demonstrates why the corporate architecture of the 2026 concession holder matters considerably: future dispute rights will depend not only on the nominally American character of the operator but on where holding entities are incorporated, which investment treaties remain effective, whether consent to arbitration exists, and what dispute provisions appear in the concession and associated contracts.
None of those questions can safely be answered merely from the White House fact sheet.
Political legitimacy and legal authority must be separated
The Venezuelan arrangement carries an additional risk because international and domestic debates about the legitimacy of the authority granting a concession are conceptually separate from the commercial merits of the concession itself.
A government can offer economically attractive terms while future political actors challenge whether the authority that granted them had the constitutional competence or political legitimacy to bind the state for a century.
Conversely, a politically contested government may still undertake legally valid acts if the competent domestic institutions recognise its authority.
The relevant analytical question is therefore not whether commentators call the interim authorities “legitimate” or “illegitimate”, but whether controlling Venezuelan constitutional, hydrocarbons and public-law instruments validly authorised the specific concession and whether the bodies exercising those powers were recognised by the institutions whose decisions will govern enforcement.
The current official record retrieved for this assessment is insufficient to close that question.
The domestic-benefit test will determine much of the Brazilian political trajectory
Resource agreements become politically more durable when domestic constituencies can identify benefits that extend beyond royalties and extraction.
Brazil’s September legislation explicitly prioritises domestic processing and industrial value addition, and the Senate’s official account states that up to R$7 billion of government incentives and funding mechanisms are contemplated for processing and transformation projects; the political durability of foreign ownership is therefore increasingly linked to whether the investment contributes to Brazilian technological and industrial capabilities rather than functioning only as an export channel.
This creates a concrete stability mechanism.
If future investment expands Brazilian separation, refining, materials science, recycling or magnet production, the transaction develops domestic industrial stakeholders whose interests favour continuity.
If the operation remains predominantly extractive while high-value processing migrates abroad, future governments and legislators have a stronger political incentive to seek revised terms.
The relevant political-risk variable is therefore not simply ownership nationality but distribution of value across the chain.
Political risk should be measured through observable institutional actions rather than campaign rhetoric
Election periods increase public attention to sovereignty and foreign control, but campaign statements are weaker evidence than administrative acts, legislation, regulatory filings and judicial proceedings.
The correct indicators are therefore behavioural.
Brazilian stability indicators
| Indicator | Direction toward stability | Direction toward dispute |
|---|---|---|
| CIMCE treatment of legacy transactions | Express prospective-only interpretation | Attempted retroactive homologation or reopening |
| CADE proceeding | Closure without structural remedies | Mandatory notification, remedies or enforcement action |
| ANM status | Routine regulatory administration | Challenge to mineral-title transfer or compliance |
| Phase II treatment | Approval with negotiated conditions | Refusal tied to strategic ownership or offtake concerns |
| Domestic processing | New Brazilian separation/metallisation investment | Continued exclusive external processing |
| Offtake amendment | Brazil-compatible domestic allocation provisions | Expanded exclusivity without domestic-access safeguards |
| Federal dialogue with U.S. | Regular technical negotiations | Suspension of mineral cooperation |
| Judicial activity | No major challenge | Federal litigation over screening or contract rights |
| Legislative activity | Stable implementation rules | New legislation specifically targeting legacy transactions |
| Traceability implementation | Routine compliance | Enforcement focused on destination or beneficial ownership |
Venezuelan stability indicators
| Indicator | Direction toward stability | Direction toward dispute |
|---|---|---|
| Publication of controlling hydrocarbons law | Clear authority supporting concession model | Constitutional inconsistency or unclear delegation |
| Legislative ratification/oversight | Broad institutional confirmation | Challenge to authority of grantor |
| Production investment | Physical capital deployment and rising output | Capital delay pending political clarification |
| Tax and royalty flows | Regular payments under transparent rules | Dispute over fiscal terms |
| Opposition/legal posture | Acceptance of continuity subject to regulation | Formal commitment to review or annul concessions |
| Judicial posture | Domestic courts recognise concessions | Constitutional or administrative challenge |
| Corporate governance | Stable board and audit arrangements | Conflict over U.S. veto/governance rights |
| International recognition | Broad recognition of contracting authorities | Competing claims over governmental authority |
| Arbitration provisions | Clear and enforceable dispute forum | Ambiguity over consent or governing instrument |
| U.S. statutory treatment | Clear congressional basis for OSC rights | Congressional or judicial challenge to equity authority |
These indicators permit political risk to be monitored without making an electoral prediction.
Four principal Brazilian pathways through 2031
The verified record supports four genuinely distinct pathways rather than a fabricated probability model.
Institutional accommodation
Under this pathway, the completed ownership structure remains intact while Brazil and the U.S.-aligned investor adapt future expansion to the new legal regime; CIMCE applies prospectively, domestic processing increases, CADE resolves its competition questions without requiring fundamental restructuring and the two governments use existing bilateral dialogue to manage strategic concerns.
The principal confirming indicators would be Brazilian downstream investment, negotiated domestic-market access, uncontroversial Phase II approvals and absence of retrospective administrative action.
This pathway would convert the dispute from a sovereignty controversy into a managed industrial partnership.
Regulatory rebalancing
Under a second pathway, Brazil does not attack existing ownership but uses CIMCE, export policy, fiscal incentives, traceability and future project approvals to shift more value creation into Brazil.
This would increase compliance and capital costs for the investor but could increase long-run political durability if Brazilian industrial benefits grow.
The decisive indicator would be conditional approval of new expansions or agreements requiring processing, technology development or domestic supply commitments.
Judicialised sovereignty dispute
A third pathway begins if Brazilian authorities interpret the new law as reaching legacy contractual structures or if another pre-existing legal issue becomes the basis for intervention.
The investor could then seek domestic judicial review, producing uncertainty without necessarily interrupting current mining.
The key indicators would be ex officio CIMCE proceedings concerning pre-16 September conduct, injunction applications, disputes over perfected legal acts and federal-court rulings on temporal application.
Structural rupture
The most disruptive pathway would require Brazil to move beyond prospective regulation and attempt cancellation, forced restructuring or another measure substantially depriving the investor of existing rights.
Nothing in the verified official record currently establishes that Brazil has adopted such a policy.
If it occurred, the dispute would shift from regulatory adjustment toward compensation, constitutional litigation and potentially contractual or international dispute-resolution mechanisms depending on the corporate and treaty structure.
Four principal Venezuelan pathways through 2031
Consolidated concession regime
The arrangement stabilises if domestic institutions validate the new hydrocarbons framework, large-scale investment is deployed, production expands, tax and royalty payments become economically important and successive political institutions treat the concessions as state commitments rather than commitments of one administration.
The strongest evidence would be domestic legislative and judicial confirmation rather than U.S. political statements.
Renegotiated continuity
A future Venezuelan authority could preserve foreign investment while renegotiating unusually long concession duration, governance rights, tax terms or U.S. offtake privileges.
Historically, resource-nationalist governments need not eliminate private investment entirely; they can instead alter fiscal or control arrangements.
This pathway would preserve production while reducing some of Washington’s preferential rights.
Sovereign challenge and arbitration
A future authority could dispute the validity of the concession or foreign governance provisions, leading to contract termination, expropriation claims or arbitration.
Venezuela’s historical ICSID cases demonstrate that hydrocarbons interventions can produce disputes lasting well beyond the original political decision.
Fragmented enforcement
The most legally complex pathway arises if concession validity, governmental recognition, ownership of foreign assets and creditor rights become simultaneously contested.
In that environment, a nominal contractual victory may not restore production control, and award enforcement could migrate across multiple jurisdictions.
Historical enforcement litigation involving Venezuelan arbitral awards demonstrates that sovereign-immunity and asset-identification issues can remain consequential after liability has already been determined.
Comparative political-risk matrix
| Risk category | Brazil | Venezuela | Relative analytical significance |
|---|---|---|---|
| Constitutional ownership dispute | Low regarding Union ownership; higher over regulatory reach | Potentially material depending on verified hydrocarbons framework | Greater Venezuelan uncertainty |
| Retroactive regulation | Central legal issue | Potentially secondary to concession-validity issue | Brazil-specific core risk |
| Competition review | Active, formal institutional pathway | No equivalent transaction-specific record verified | Greater Brazilian procedural complexity |
| Foreign-government equity controversy | Indirect/multi-instrument | Direct 35% OSC stake claimed | Greater Venezuelan sensitivity |
| Contract duration risk | 15–20-year commercial horizon | 100-year concession horizon | Much greater Venezuela temporal exposure |
| Host-state institutional continuity | High relative to region | More contested in current circumstances | Key differentiator |
| International arbitration history | Limited Brazilian model of investor-State arbitration | Extensive petroleum-related arbitral history | Greater Venezuela precedent |
| Domestic judiciary role | Central | Formally relevant but present concession treatment unverified | Brazil provides clearer domestic legal pathway |
| Resource-nationalism sensitivity | Significant | Historically very high | Material in both, structurally deeper in Venezuela |
| Domestic value-add politics | Central | Also relevant but oil infrastructure differs structurally | Particularly important to Brazilian stability |
| U.S. statutory-authority risk | IBAS/DLA programme design | OSC equity authority question | Sharper in Venezuela |
| Bilateral diplomatic management | Established and active | Relationship embedded in political transition framework | Brazil offers more conventional diplomatic de-risking |
| Physical operational continuity | Current mining can continue during many legal disputes | Field investment more exposed to concession legitimacy | Greater Venezuela operational sensitivity |
| Enforcement risk | Primarily Brazilian courts/contractual pathways | Potential international award and sovereign-asset enforcement | Greater Venezuela enforcement complexity |
The “hemispheric resource model” is real, but it is not yet a single legal model
The evidence supports describing an emerging U.S. hemispheric resource strategy, but not a uniform legal template.
Its recurring components are visible:
First, strategic resources are explicitly recast as national-security assets. U.S. presidential actions in 2026 connect critical minerals directly to defence resilience, import dependence and allied supply chains.
Second, private companies remain the operating vehicles while public institutions alter their economics. Government lending, equity-like interests, guaranteed procurement and policy-backed offtake reduce risks that private markets would otherwise bear.
Third, the objective extends beyond acquiring raw material and toward determining where resource flows travel. Preferential purchasing rights, long-term contracts and downstream industrial capacity are central elements of the model.
Fourth, the model seeks to reduce the role of strategic competitors. The Venezuelan White House announcement explicitly frames the transaction as reducing Chinese and Russian influence, while U.S. critical-mineral policy repeatedly emphasises trusted domestic and partner sources.
Fifth, legal architecture is transaction-specific rather than standardised. Brazil uses DFC, IBAS, DLA, corporate ownership and an SPV; Venezuela is described as using OSC equity, concessions, direct governance rights and State Department offtake.
This final point is the model’s principal weakness because strategic replication without legal standardisation produces different statutory vulnerabilities in each transaction.
The most important political risk is misalignment of time horizons
The physical life of a mine or oil field is measured in decades, while political mandates, agency appropriations, commodity cycles and regulatory priorities change much faster.
That mismatch creates a structural requirement for legitimacy that goes beyond the government in power when a deal is signed.
A genuinely secure supply arrangement must therefore satisfy at least four durability tests:
| Durability test | Question |
|---|---|
| Host-law test | Was the agreement validly authorised under controlling domestic law? |
| Political-legitimacy test | Does the arrangement generate sufficient domestic benefit to survive government change? |
| U.S.-authority test | Does the federal agency possess durable statutory authority for its role? |
| Commercial-independence test | Can the project remain economically viable if extraordinary political support diminishes? |
Brazil currently performs comparatively strongly on the first test because its institutional and mining-law architecture is clearer, while its main challenge is the second test: whether the distribution of industrial benefits remains politically acceptable.
Venezuela presents greater uncertainty on the first and second tests because the controlling domestic legal foundation of the newly announced concession arrangement has not yet been independently verified through the official record retrieved here.
Both transactions require scrutiny under the third test because U.S. agency authority differs by programme.
Neither transaction can be considered strategically secure merely because the current executive branch supports it.
What would make Serra Verde politically durable
The Serra Verde arrangement becomes structurally more durable if five developments occur simultaneously: Brazilian authorities confirm that the completed ownership transaction is not subject to retrospective reopening solely under Law No. 15,506; CADE resolves its procedure without remedies that undermine the core commercial structure; future expansions are homologated under transparent CIMCE rules; meaningful downstream processing or technology capability is established inside Brazil; and bilateral U.S.–Brazil mineral cooperation survives broader trade disagreements.
Each of those conditions addresses a different political-risk layer.
Legal certainty protects existing capital.
Competition clearance protects market structure.
CIMCE precedent protects future expansion.
Industrial localisation creates a domestic constituency for continuity.
Diplomatic cooperation reduces the probability that commercial disputes become instruments of wider bilateral confrontation.
The Brazilian government’s continuing engagement with U.S. officials on critical minerals and its August resumption of broader trade dialogue demonstrate that strategic competition and bilateral negotiation are currently proceeding simultaneously rather than as mutually exclusive alternatives.
What would turn Serra Verde into a prolonged sovereignty dispute
The opposite pathway would require an accumulation of institutional conflicts rather than one political statement.
The most significant escalation indicators would be an attempted retrospective CIMCE review of the completed transaction; a CADE decision requiring major structural remedies; an ANM challenge affecting the underlying mineral rights; legislation aimed expressly at reopening legacy critical-mineral transactions; refusal of later project phases because of foreign control; restrictions specifically directed at the existing offtake rather than generally applicable export rules; federal litigation over acquired rights; or a breakdown of bilateral mineral dialogue.
The critical point is that none of these indicators should be inferred from rhetoric alone.
A sovereignty dispute becomes operationally significant when it moves into acts of state capable of changing rights, approvals, physical flows or project economics.
Early-warning dashboard
| Indicator | Current verified status | Escalation threshold | Analytical meaning |
|---|---|---|---|
| Law 15,506 | In force since 16 Sep 2026 | CIMCE applies it to legacy transaction formation | Retroactivity dispute moves from theoretical to concrete |
| CIMCE precedent | New institution; mature precedents unavailable | First legacy foreign-control review | Defines practical reach |
| CADE | APAC opened 11 May 2026 | Mandatory notification/remedy proceeding | Competition risk becomes material |
| ANM | Resource sovereignty remains formally under Brazilian law | Mineral-right challenge connected to control | Moves dispute into core licence layer |
| Brazil–U.S. mineral dialogue | Active as of May 2026 | Formal suspension | Signals geopolitical rather than technical management |
| Brazil–U.S. trade dialogue | Resumed 31 Aug 2026 despite tariff dispute | Breakdown accompanied by resource countermeasures | Potential cross-domain escalation |
| Domestic downstream investment | Policy priority | Major processing project cancelled or redirected abroad | Weakens Brazilian domestic-benefit case |
| Phase II | Future development opportunity | Approval conditioned on ownership/offtake restructuring | Tests practical bargaining power |
| U.S. IBAS/DLA structure | Announced and operationally relevant | Congressional restriction or audit challenge | U.S.-side durability concern |
| Venezuelan concession law | U.S. says new hydrocarbons law supports deal | Domestic official text/judgment contradicts concession authority | Fundamental host-law risk |
| OSC equity authority | White House says 35% stake | Congressional/judicial challenge to statutory authority | U.S. public-law risk |
| Venezuelan political recognition | Transition described by U.S. administration | Competing authority rejects concession | Sovereign-continuity risk |
| Venezuelan field investment | Up to US$100bn announced by operator according to White House | Major capital withheld pending legal clarity | Market signal of perceived risk |
Decision thresholds
A commercially stable Brazilian arrangement should be considered established only after CIMCE demonstrates through actual precedent that its approach to legacy transactions is prospective and rule-based, while future project phases continue to obtain authorisations and downstream investment develops without major litigation.
A managed sovereignty renegotiation should be identified when Brazil uses new approvals or incentives to alter future value-chain geography without challenging completed ownership.
A material legal dispute begins when a federal authority issues an administrative act capable of changing existing rights rather than merely announcing policy preferences.
A structural sovereignty confrontation should be reserved for circumstances in which the government seeks cancellation, compulsory restructuring, loss of existing mineral rights or substantial deprivation of contractual rights.
For Venezuela, a stable concession regime requires more than physical production; it requires authoritative domestic validation of the hydrocarbons framework, continuity of contractual rights across political institutions and credible enforceability of dispute provisions.
A sovereign-repudiation pathway should be identified only when a competent Venezuelan authority formally challenges the concessions or underlying legislation, rather than when opposition actors merely criticise them.
These thresholds are intentionally institutional because they separate observable state conduct from political narrative.
Principal gaps capable of changing the judgment
The most consequential Brazilian gap is the absence of mature CIMCE implementing precedent, because the statute identifies the transactions subject to strategic review but operational practice will determine the real threshold for foreign influence, strategic supply dependence and legacy arrangements.
The second Brazilian gap is the final status of CADE’s APAC. The authority confirmed in May that it was investigating whether the business combination and fifteen-year supply agreement constituted reportable concentration acts, but the retrieved official record used here does not yet provide a final published determination.
The largest Venezuelan gap is more fundamental: the controlling domestic text of the new hydrocarbons law and authoritative Venezuelan documentation establishing the precise legal basis, concession approval procedure and compatibility of the announced foreign governance rights with domestic public law were not verifiable through the official Venezuelan sources retrieved during this assessment.
The largest U.S. gap concerns the legal vehicle through which OSC is said by the White House to hold a 35% equity position in the Venezuelan operator’s parent, because 10 U.S.C. §149, as retrieved on 18 September 2026, expressly establishes OSC lending and loan-guarantee powers but does not itself provide an obvious general equity-acquisition authority matching the White House description.
Until that bridge is documented, the Venezuelan structure contains a material unresolved U.S. statutory question.
Net assessment
The evidence supports a hemispheric U.S. resource-security strategy, but it does not support treating Brazil and Venezuela as equivalent cases.
Brazil represents a contest over how far a sovereign state can regulate the industrial consequences of a foreign-controlled strategic asset within a functioning and newly strengthened legal framework.
Venezuela represents a more foundational contest over whether a politically exceptional hydrocarbons arrangement granting extraordinary long-duration concessions and foreign governance rights can acquire sufficient domestic legal and political legitimacy to survive future governmental change.
The parallel is strongest at the U.S. policy level: Washington is increasingly using public capital, preferential procurement, contractual offtake and corporate governance to secure strategically important resources and reduce exposure to rival supply chains.
The divergence is strongest at the host-country institutional level.
Brazil’s capacity to challenge or rebalance Serra Verde is constrained by its own constitutional protections, regulators, administrative law and judiciary, but those same constraints make any agreed arrangement more durable once the relevant institutions have accepted it.
Venezuela offers potentially deeper U.S. contractual control but correspondingly greater sovereign-continuity exposure because the arrangement’s durability depends upon a political and legal settlement that the retrieved official record does not yet establish as institutionally consolidated.
The paradox is therefore significant: the more aggressive resource-control architecture can be the less secure one if its legal authority and political legitimacy are weaker.
For Serra Verde, the decisive question over the next five years is not whether Brazil can physically prevent rare-earth material from entering a U.S.-aligned chain, because the existing commercial architecture already gives that chain substantial access; the decisive question is whether Brazil can use its new regulatory regime to convert foreign control into domestic industrialisation without crossing the constitutional boundary between prospective strategic regulation and retrospective impairment of perfected rights.
If that balance is achieved, Serra Verde can evolve into a durable cross-border strategic supply arrangement.
If Brazilian authorities attempt retroactive restructuring while U.S. institutions defend a long-duration supply architecture as strategically indispensable, the mine can instead become the first major test of whether the Trump administration’s hemispheric resource-security doctrine can survive the domestic sovereignty institutions of a large democratic resource state.
Key judgments
The Brazilian and Venezuelan arrangements belong to the same U.S. strategic-resource policy family but not to the same legal model. The common mechanisms are preferential access, state-supported capital, supply-chain redirection and reduction of exposure to geopolitical competitors, while host-country law and institutional capacity differ fundamentally.
Brazilian political risk is primarily institutional and regulatory rather than existential to state authority. CADE, ANM, CIMCE and the judiciary provide distinct pathways through which disagreement can be processed, creating complexity but also predictability.
Venezuelan political risk is structurally deeper because concession authority, political continuity and future sovereign acceptance are potentially contestable at the same time. Earlier ICSID petroleum cases show that Venezuelan hydrocarbons disputes can survive for years after the initial state intervention and migrate into enforcement litigation.
The White House’s claim that OSC holds 35% of the Venezuelan operator’s parent raises an unresolved statutory issue that requires further official documentation. The current text of 10 U.S.C. §149 clearly identifies OSC loan and loan-guarantee authority but does not, in the retrieved text, independently establish the general equity authority necessary to validate the precise structure described by the White House.
U.S.-law governing clauses do not eliminate host-state sovereignty risk. They can govern contractual disputes among consenting parties, but they cannot substitute for valid constitutional and statutory authority in the state where the natural resource is located.
Brazil’s strongest leverage lies in future approvals rather than retrospective cancellation. Phase expansions, new supply contracts, mineral-title transactions, processing incentives and domestic-value commitments provide repeated prospective points of influence without requiring reopening of perfected pre-enactment acts.
The political durability of Serra Verde will depend heavily on domestic industrial value creation. Brazil’s new policy expressly seeks processing and transformation rather than a purely extractive export model, and the Senate described the programme as containing up to R$7 billion in associated public support mechanisms.
Election outcomes should not themselves be treated as forecasts of contract continuity or repudiation. The decisive evidence will be enacted legislation, CIMCE decisions, CADE action, ANM decisions, judicial rulings, signed amendments and actual capital allocation after any political transition.
What would change the assessment
The assessment would move materially toward greater Serra Verde stability if Brazil publishes CIMCE rules explicitly protecting completed pre-law transactions from retrospective homologation, CADE closes its procedure without disruptive remedies, Phase II or equivalent expansion receives approval under the new system and substantial downstream investment is announced inside Brazil.
It would move toward managed rebalancing if Brazil conditions future expansion on domestic processing, Brazilian supply availability or technology transfer while leaving completed ownership untouched.
It would move toward a high-intensity sovereignty dispute if CIMCE, ANM or another federal authority attempts to cancel or restructure existing rights created before 16 September solely by applying the new policy retrospectively, particularly if such action generates federal-court proceedings.
The Venezuela comparison would become materially stronger if authoritative Venezuelan legal documents confirm the complete concession architecture claimed by Washington and demonstrate broad domestic institutional ratification of the 100-year model.
It would weaken substantially if Venezuelan courts, legislators or successor authorities formally challenge the competence of the grantor or the legality of the foreign governance provisions.
The U.S.-side assessment would change if Congress provides explicit statutory authority for OSC equity participation matching the Venezuelan structure, because that would remove one of the most important current legal uncertainties; conversely, congressional, audit or judicial findings that OSC exceeded its authority would materially weaken the supposed century-long durability of the arrangement.
Open official record
The records most capable of changing this assessment are the complete Venezuelan hydrocarbons law governing the August 2026 concessions; the official concession instruments for the seventeen fields; any Venezuelan legislative ratification or constitutional review of those concessions; the operative NABEP ownership and governance documentation; the statutory instrument authorising OSC to hold the announced 35% equity interest; complete U.S. appropriations documentation supporting that position; the final CADE decision concerning Serra Verde and its supply agreement; the first CIMCE rules and case decisions involving legacy foreign-controlled assets; any Phase II Serra Verde submission; and any Brazilian administrative or judicial determination addressing whether the new critical-minerals regime can affect contractual performance arising from transactions completed before 16 September 2026.
Until those records are available, the most defensible conclusion is that Serra Verde presents a serious but governable political-risk problem, while the Venezuelan oil structure presents a substantially more fundamental sovereign-continuity problem; the common U.S. strategic doctrine is clearer than the durability of either transaction, and the legal systems of the host countries rather than the scale of the resource endowment will determine whether the strategy produces secure supply or merely long-lived disputes.
Political-Risk Pathways & the Hemispheric Resource Model: Institutionalized Governance vs. Sovereign Continuity Exposure
EXECUTIVE BLUF: While Washington's hemispheric resource doctrine unites critical minerals in Brazil (Serra Verde) and hydrocarbons in Venezuela (NABEP) under an overarching objective to displace strategic adversaries through public capital and preferential offtake, the legal durability of these structures diverges fundamentally. Brazil's political risk is rule-intensive and institutionalised: governed by clear Union subsoil ownership (CF Art. 176), multi-layered administrative review (CADE, ANM, CIMCE under Law No. 15,506), and constitutional protections against retroactivity (Art. 5, XXXVI). By contrast, the Venezuelan architecture claimed by the White House—granting 100-year concessions across 17 fields (~65B bbls), a 35% Office of Strategic Capital (OSC) equity stake, and board vetoes—rests on post-crisis political arrangements whose domestic statutory validity remains unverified. Brazil’s friction will manifest through domestic industrialisation mandates and prospective licensing leverage; Venezuela faces structural sovereign-continuity risk, expropriation litigation, and enforcement friction.
Comparative Sovereign Risk & Institutional Durability Indices (0–100 Scale)
Contrasting Host-State Legal Continuity: Administrative Process vs. Sovereign Repudiation
Comparative Institutional Architecture & Strategic Parameters
VERIFIED OFFICIAL SOURCES: WHITE HOUSE • SENADO FEDERAL • ICSID • 10 U.S.C. §149| Structural Dimension | Brazil: Serra Verde Architecture | Venezuela: NABEP Architecture (U.S. Claim) | Comparative Political-Risk Consequence | Primary Statutory Authority |
|---|---|---|---|---|
| Subsoil Resource Ownership | Constitutionally vested in the Union | Controlling domestic rule unverified | Brazil maintains clear subsoil separation; Venezuela leaves concession validity legally vulnerable. | CF/88 Art. 20/176 vs. WH Release |
| Foreign Control Mechanism | Corporate M&A via Brazilian subsidiary | 100-year concession + board vetoes | Brazil screens foreign control under CIMCE; Venezuela claims extensive sovereign board rights. | Law 15,506 vs. WH Fact Sheet |
| U.S. Equity-Like Position | DFC warrants (12% diluted Serra Verde) | 35% OSC equity stake in parent | DFC warrants have explicit statutory basis; OSC equity lacks general mandate under 10 U.S.C. §149. | DFC BDR(26)01 vs. 10 U.S.C. §149 |
| Contractual Supply Term | 198 Mt ROM ore or 20 years | 100-Year Concession Horizon | A century-long commitment guarantees exposure to future constitutional and fiscal transitions. | SEC Offtake vs. WH Announcement |
| Preferential Offtake Terms | 100% Phase I carbonate at floor prices | 20% at cost; ROFR on remaining 80% | Both direct physical resource flows to the U.S., but Venezuela enforces statutory cost-recovery pricing. | US SIIE SPV vs. White House Release |
| ICSID Convention Posture | Non-signatory (ACFI dispute model) | Denounced (Effective 25 Jul 2012) | Neither provides simple ICSID access; disputes depend on intermediate holding treaty routes. | ICSID Official Status Ledgers |
| Domestic Governance Channel | CADE, ANM, CIMCE & STF Judiciary | Interim executive authorities | Brazil offers institutional due process; Venezuela carries existential sovereign continuity risk. | Law 15,506 / LINDB / Brazilian CPC |
U.S. Strategic Financial Vehicles: Statutory Scope & Appropriations Exposure
| Agency / Programme | Deployed Mechanism | Statutory Horizon / Mandate | Controlling Statutory Text | Unresolved Public-Law Risk |
|---|---|---|---|---|
| U.S. DFC (Serra Verde) | US$565M debt + 12% equity warrants | BUILD Act of 2018 (22 U.S.C. §9601) | Explicit statutory authority for loans and equity-like instruments in critical assets. | Low: Fully compliant with bilateral development finance mandate. |
| DoW IBAS (US SIIE SPV) | US$750M SPV equity capitalization | 10 U.S.C. §2508 (IBAS Authorities) | Procurement commitments generally capped at 10 years; routed via private SPV. | Moderate: SPV structure required to circumvent direct 10-year procurement cap. |
| DLA Procurement (Serra Verde) | US$300M 5-year purchase commitment | Strategic & Critical Materials Stock Piling Act | Authorised stockpile procurement supporting National Defense Stockpile requirements. | Low: Standard statutory procurement authorities. |
| DoW OSC (Venezuela NABEP) | 35% direct corporate parent equity | 10 U.S.C. §149 (Capital Assistance) | Text expressly establishes loans and loan guarantees; lacks free-standing equity mandate. | Critical: High exposure to congressional audit or judicial challenge under U.S. law. |
Strategic Divergence Vectors & Risk Dynamics
COMPARATIVE VECTOR DECONSTRUCTIONThe Legality Paradox
Physical resource access does not guarantee legal durability. Washington can underwrite mines and secure long-term offtakes, but contracts cannot override host-state public law. An aggressive control structure backed by interim fiat is structurally more fragile than a regulated asset in an established constitutional state.
Temporal Mismatch & Repudiation
A 100-year concession (Venezuela) spans dozens of electoral and constitutional cycles, multiplying political repudiation risk. A 15-to-20 year mineral offtake (Brazil) carries significant duration exposure, but operates within standard commercial life cycles, allowing periodic renegotiation.
The Enforcement Labyrinth
ICSID historical precedent (Mobil, ConocoPhillips) proves that securing arbitral awards against Venezuela initiates multi-decade enforcement battles under the U.S. Foreign Sovereign Immunities Act (FSIA). Brazil's non-ICSID domestic framework routes conflicts directly into predictable federal court proceedings.
Domestic Industrial Rents
Political stability requires local economic retention beyond raw royalties. Brazil’s Law 15,506 incentivises in-country oxide separation via R$5B in fiscal credits. Venezuela’s model of exporting unrefined crude to U.S. refineries re-creates historical resource-enclave vulnerabilities.
Forensic Strategic Key Judgments
ANALYTIC CONSENSUS • PROTOCOL HEM-RES-2026Washington seeks to secure hemispheric resource routes and displace rival powers in both jurisdictions. However, Brazil's dense constitutional framework makes it fundamentally non-interchangeable with post-crisis Venezuela.
NABEP's 100-year concession, cost-recovery offtake, and U.S. board vetoes depend on interim authority. Without broad domestic judicial and legislative validation, the structure invites repudiation by successor regimes.
The White House's assertion of a 35% OSC equity stake in the Venezuelan operator's parent conflicts with statutory text limiting OSC to loans and loan guarantees, creating acute congressional audit risk.
Specifying U.S. court jurisdiction over bilateral contracts governs inter-party disputes, but cannot compel foreign regulators to maintain concessions if host-state constitutional authorities find them invalid.
Serra Verde faces prospective regulatory pressure: CADE antitrust scrutiny, CIMCE export conditions, and environmental licensing. However, constitutional guarantees shield completed ownership from arbitrary expropriation.
Serra Verde achieves long-term durability if the U.S. sponsor commits to establishing oxide separation and metallisation inside Goiás, aligning foreign capital with Brazilian statutory industrial policy.
Open Official Record Gaps
- Controlling Venezuelan Hydrocarbons Statute: Absence of the verified domestic legislative text governing the August 2026 concession grants and establishing their constitutional conformity.
- 10 U.S.C. §149 Equity Mandate: Lack of published legal opinions or congressional amendments explaining the statutory basis for the Office of Strategic Capital's 35% equity acquisition in NABEP.
- CADE Final Antitrust Ruling: The public registry records the May 2026 APAC inquiry, but lacks a published final administrative decree resolving competition concerns over Serra Verde's 15-year supply pact.
- CIMCE Legacy Jurisprudence: Absence of initial administrative rulings clarifying whether CIMCE will attempt ex-officio reviews of pre-enactment contracts or restrict scrutiny to prospective amendments.


