



Scope: This report reconstructs the Italian fiscal position from the official statistical and institutional record, examines the September 2026 revision of the 2025 national accounts, establishes the precise status of Italy under the European excessive-deficit procedure, separates statistical measurement from political interpretation, and subsequently documents the fiscal and institutional position of the principal European economies individually rather than treating Europe as a single fiscal system.
Executive Summary / BLUF
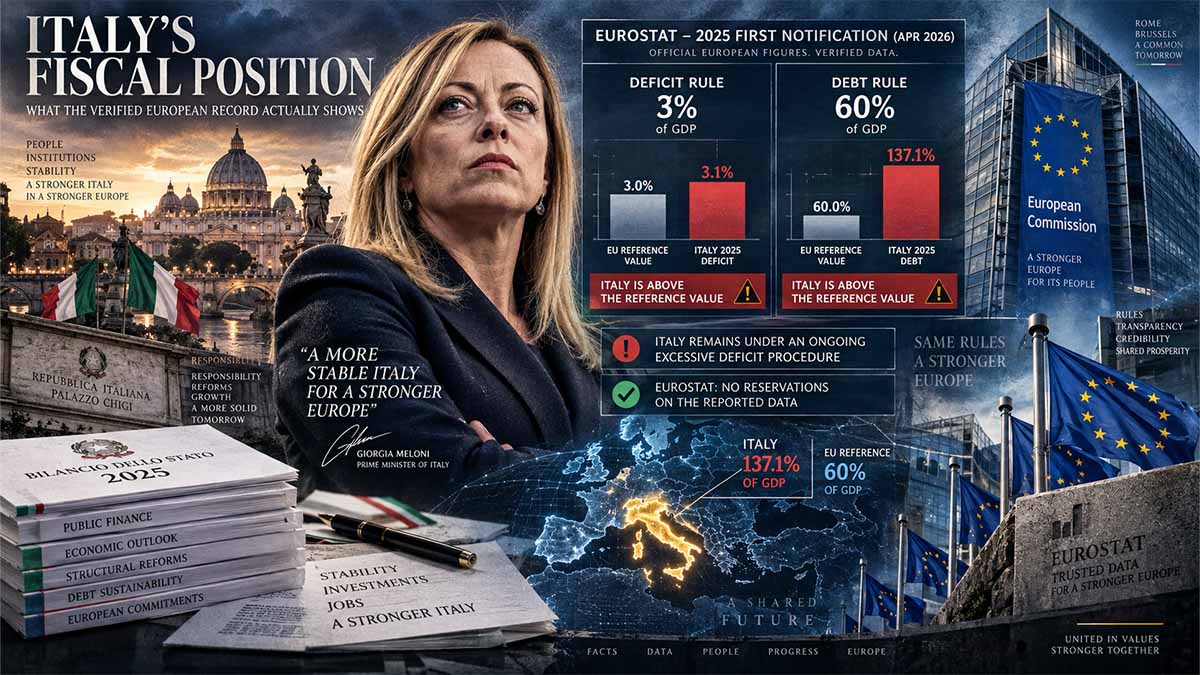
Italy’s public-finance position at 23 September 2026 contains two facts that must be held together rather than politically selected according to convenience: the fiscal correction since 2023 has been substantial, but the officially recorded 2025 general-government deficit remains 3.1% of GDP, meaning that the statistical conditions for closing the excessive-deficit procedure on the basis of the 2025 outcome have not yet been established.
ISTAT’s 22 September 2026 national-accounts revision did not simply worsen the Italian macroeconomic picture. It increased nominal GDP for 2025 by €6.954 billion, from the March vintage to €2.265003 trillion, revised real GDP growth for 2024 from 0.8% to 1.1%, revised 2025 growth from 0.5% to 0.6%, confirmed a primary surplus of 0.8% of GDP, and recorded a tax burden of 42.9% of GDP. The deficit ratio nevertheless remained at 3.1%.
The central statistical issue is therefore not whether ISTAT revised the accounts—national accounts are routinely revised as more complete information becomes available—but whether the underlying methodological choices, classification decisions and revisions are technically justified and applied consistently. ISTAT itself describes the September exercise as the ordinary revision of the 2024–2025 national accounts, incorporating information acquired after March 2026 together with methodological and source changes introduced in response to Eurostat reservations concerning gross national income statistics.
Italy remains under the EU excessive-deficit procedure opened on 26 July 2024, originally on the basis of the 2023 fiscal imbalance. The Council subsequently established a correction deadline of 2026 and required Italy to limit nominal net-expenditure growth to 1.3% in 2025 and 1.6% in 2026. The official European record therefore distinguishes between an unsuccessful possibility of closing the procedure earlier on the strength of 2025 data and the legally operative correction timetable, which continues to point to 2026.
The European Commission’s Spring 2026 forecast projected Italy’s deficit declining from 3.1% of GDP in 2025 to 2.9% in both 2026 and 2027, while projecting debt rising from 137.1% in 2025 to 138.5% in 2026 and 139.2% in 2027. Those projections were produced before the September ISTAT revision and must therefore be treated as a separate forecast vintage rather than silently merged with the newer historical accounts.
The proposition that the Meloni government is facing deliberate institutional pressure cannot be treated as an established fact solely from the fiscal statistics. It is a political hypothesis requiring separate evidence concerning institutional conduct, departures from normal statistical practice, inconsistent treatment, procedural discrimination or documented political intervention. The present official record proves the fiscal and procedural facts; it does not by itself establish the motive of the actors involved.
The Italian Fiscal File
What ISTAT actually changed on 22 September
The starting point must be the source itself rather than the political reaction to it. On 22 September 2026, ISTAT published its revised national accounts for 2010–2025 and explicitly described the exercise as an ordinary revision covering 2024 and 2025, undertaken to incorporate information received after the March 2026 release and methodological improvements connected with Eurostat scrutiny of the gross national income calculations used in determining EU own resources.
The revision increased 2025 GDP at current market prices to €2,265.003 billion, an upward adjustment of €6.954 billion compared with the March estimate, while 2024 nominal GDP was revised upward by €8.564 billion. These are material adjustments because every ratio expressed relative to GDP—including deficit, debt, expenditure, revenue and tax burden—is mechanically affected by changes in the denominator even when the underlying cash or accrual amount changes by less.
The revised real-economy data were also stronger than the earlier vintage. ISTAT now estimates real GDP growth of 1.1% in 2024 and 0.6% in 2025, with 2025 domestic demand excluding inventories contributing 1.6 percentage points, net exports subtracting 0.7 points and inventories subtracting 0.3 points. Value added increased by 0.8% in agriculture, 0.4% in industry excluding construction, 2.6% in construction and 0.3% in services.
Those figures matter because the September release cannot accurately be characterised as an across-the-board deterioration of Italy’s economic position. The revision simultaneously produced stronger recorded nominal GDP, stronger 2024 growth, slightly stronger 2025 growth and a still-positive primary balance, while leaving the headline deficit above the Treaty reference level.
The deficit remained at 3.1%
ISTAT states that general-government net borrowing remained 3.1% of GDP in 2025, unchanged at the published one-decimal level from the April estimate. The primary balance improved from +0.5% of GDP in 2024 to +0.8% in 2025, while interest expenditure increased by 2.0% in nominal terms.
This distinction is essential to understanding the structure of Italy’s accounts. A country can simultaneously register a primary surplus and an overall deficit because debt-service expenditure remains substantial. The European Commission estimated Italian interest expenditure at approximately 3.9% of GDP in 2025, meaning that the interest burden absorbed the primary surplus and generated the negative overall balance.
For institutional analysis, this is far more informative than treating 3.1% as an isolated political number. The Italian state was not, in 2025, running a primary deficit; its current fiscal constraint was strongly influenced by the cost of servicing the accumulated debt stock.
The primary surplus is a substantive fiscal fact
The return to a 0.8% primary surplus constitutes one of the most important elements of the 2025 accounts because it identifies the balance of government revenues and non-interest expenditure before financing costs.
The Commission’s May assessment attributes the strengthening of the primary balance principally to increased current revenues, including higher social-security contributions following the restructuring of the labour tax wedge, continued growth in personal-income-tax receipts, higher taxation of financial assets and VAT revenues, while public investment remained elevated because of Recovery and Resilience Facility implementation and other investment programmes.
A government-grade reading therefore has to distinguish three layers: the primary fiscal position, which improved; the overall deficit, which remained above the 3% reference value; and the debt trajectory, which remains difficult because accumulated debt and interest expenditure continue to condition the accounts.
The tax burden reached 42.9%
ISTAT records the 2025 fiscal burden at 42.9% of GDP, an increase of 0.7 percentage points compared with 2024.
This figure must be stated precisely. It establishes that the aggregate ratio of taxation and compulsory social contributions to GDP increased; it does not, without further decomposition, demonstrate that every category of household or business experienced an equivalent rise in statutory taxation, nor does it identify which government decision explains each part of the increase.
A later chapter should therefore disaggregate the movement by personal income taxation, corporate taxation, VAT and indirect taxation, social-security contributions, property and financial taxation, one-off measures and changes generated by nominal income and employment growth before drawing a political conclusion concerning the distribution of the tax burden.
The Debt Question Is Separate from the Deficit Question
Italy’s fiscal analysis becomes misleading if debt and deficit are treated as synonyms. The deficit measures the flow generated during a period, whereas public debt represents the accumulated stock of liabilities subject to the European Maastricht definition.
The Commission recorded gross public debt at 137.1% of GDP in 2025 and projected it at 138.5% in 2026 and 139.2% in 2027 under its May 2026 forecast assumptions.
The Commission attributes the prospective increase not merely to new budget deficits but also to an unfavourable interest-growth differential and stock-flow adjustments associated with housing-renovation tax credits whose impact on the deficit was recognised in earlier years but whose cash financing continues to affect debt.
This mechanism requires close attention because it means that a deficit below 3% would not automatically produce an immediate decline in the debt ratio. Italy’s medium-term fiscal challenge is therefore not reducible to crossing the 3% boundary: it involves maintaining sufficient primary balances and economic growth to offset interest costs and debt-increasing stock-flow effects.
What the European Procedure Actually Requires
Why Italy entered the procedure
The Council of the European Union opened an excessive-deficit procedure for Italy on 26 July 2024, following the Commission’s proposal and on the basis of the fiscal situation recorded for 2023. The Council’s current official description states that the 2023 deficit relevant when the procedure was opened amounted to 7.4% of GDP under the statistical vintage used for that decision.
The historical number appearing in the legal and procedural record must not be silently replaced with later statistical revisions, because the decision was taken on the information available at the time. Revised historical data and the figures that legally triggered a past decision are related but analytically distinct.
The deadline established for Italy is 2026
On 21 January 2025, the Council recommended that Italy bring the excessive-deficit situation to an end by 2026 and required nominal growth in net expenditure not to exceed 1.3% in 2025 and 1.6% in 2026.
This point is decisive for interpreting the events of September 2026. A 2025 deficit remaining at 3.1% means that the conditions for using that year as the basis for an earlier closure have not been established, but the formal Council recommendation itself did not require Italy to complete the correction in 2025.
The relevant institutional test therefore concerns the 2026 fiscal position and the durability of the correction, not simply whether the 2025 unrounded ratio could have passed marginally below the reference value.
Italy’s procedure was not formally escalated after the 2025 outcome
A Council document from June 2026 records that, following the Commission’s assessment of effective action of 3 June 2026, the excessive-deficit procedure for Italy was held in abeyance. That institutional wording indicates continuation of surveillance without a finding at that stage that Italy had failed to take effective corrective action.
This is important because three different states of the procedure must not be confused: an EDP can remain open; it can be intensified following a finding of insufficient effective action; or it can be abrogated after the excessive deficit has been corrected in a durable manner. Italy remained in the first category at the relevant point of the 2026 procedure.
The 3% Threshold: Law, Statistics and Rounding
The 3% reference value originates from the European fiscal framework and is not an informal Commission preference. The excessive-deficit mechanism uses the government deficit-to-GDP ratio together with the broader requirements of the Stability and Growth Pact to determine whether an excessive deficit exists and whether it has been durably corrected.
The Council itself states explicitly that deficit-based excessive-deficit procedures are opened when a member state records a government deficit above the 3% of GDP Treaty reference value.
The debate concerning values such as 3.073%, 3.079% or 2.94% belongs to the statistical implementation of that reference value and therefore requires extreme precision. The operative legal reference remains 3%; whether a particular underlying unrounded estimate is reported as 3.0 or 3.1, and what precision Eurostat requires before concluding that the criterion has been durably satisfied, is a separate statistical matter.
The supplied newspaper text states that an underlying figure around 2.94% would have been needed to generate a published 2.9% and remove ambiguity over the threshold. That proposition should not be transformed into the claim that EU law contains a separate 2.94% threshold unless the exact Commission, Eurostat or parliamentary record establishing the relevant statistical convention is retrieved.
The Meloni–ISTAT Dispute Must Be Analysed Separately from the Accounts
The political dispute surrounding ISTAT does not alter the numerical data and therefore belongs in a separate evidentiary layer.
There are at least three questions requiring independent examination.
The first is whether the September revision was methodologically unusual. ISTAT’s own documentation describes it as an ordinary revision and explains that it incorporated newly available information and methodological adaptations connected with Eurostat’s GNI reservations.
The second is whether the revisions displayed a systematic direction capable of indicating institutional bias. The current release itself does not support a simple directional interpretation because some important changes were favourable to the government’s fiscal and economic narrative: nominal GDP increased, 2024 real growth increased materially and 2025 growth was also revised upward.
The third is whether the government’s criticism identifies a genuine technical disagreement concerning the treatment of particular transactions, classifications or national-account methodologies. That question cannot be answered by political statements alone and requires examination of ISTAT’s methodological note, Eurostat reservations, earlier national-account vintages and any formal correspondence or parliamentary testimony concerning the disputed calculations.
Accordingly, neither of the two politically convenient conclusions is presently acceptable as a substitute for evidence: it is not established merely from the deficit outcome that ISTAT acted politically against the government, and it is equally insufficient simply to state that every methodological choice must therefore be beyond scrutiny.
The Central Fiscal Question for 2026
The next decisive question is whether the government can achieve a deficit below 3% in 2026 while maintaining the correction sufficiently durably for the Council to close the procedure.
The European Commission’s Spring 2026 forecast projected a deficit of 2.9% in 2026 and 2.9% in 2027, following 3.1% in 2025.
The same forecast, however, projected weak real GDP growth of 0.5% in 2026, inflation of 3.2%, unemployment of 5.7% and debt reaching 138.5% of GDP, meaning that deficit correction was expected to occur in an environment of subdued growth and a rising debt ratio.
The September ISTAT revision subsequently changed the historical baseline by lifting 2025 growth to 0.6% and nominal GDP to €2.265 trillion. Those revised historical values will have to be incorporated into the next Commission and Eurostat assessments rather than mechanically combined with the older May forecast.
Energy, Defence and Fiscal Flexibility
The fiscal treatment of higher defence and energy-security expenditure requires a separate analytical chapter because at least three instruments are frequently mixed together in political discussion: actual defence expenditure, SAFE borrowing and the national escape clause under the reformed fiscal framework.
They are not the same mechanism.
Fiscal flexibility can modify the way expenditure is assessed against a government’s net-expenditure path, but it does not abolish the national-accounting treatment of expenditure and financing. Therefore, any claim that certain expenditure simply “does not count” must specify what calculation it does not count toward: net-expenditure compliance, headline deficit, debt, or another fiscal indicator.
The same discipline applies to EU borrowing instruments: receipt of an EU-backed loan creates financing capacity, but the expenditure and resulting national liabilities must still be analysed under the appropriate accounting rules.
This subject requires a dedicated reconstruction from the relevant Commission decisions, Council acts and Italian budget documents before any aggregate figure is assigned to Italy.
The European Fiscal Landscape: Individual Country Files
The European fiscal picture must be reconstructed country by country because the decisive variables are not limited to the headline deficit: the official record also contains the nominal size of the deficit, government revenue and expenditure, debt stock, growth, inflation, labour-market conditions, projected fiscal trajectory and, where applicable, the legally operative excessive-deficit procedure and net-expenditure path. For the EU states examined below, the common 2025 statistical baseline is Eurostat’s first EDP notification of 22 April 2026, compiled under ESA 2010 from national submissions; Eurostat explicitly stated that it had no reservations on the data reported by Member States and made no amendments to those reported figures, while the next scheduled EDP notification is 21 October 2026. Eurostat — Provision of deficit and debt data for 2025, first notification, 22 April 2026
France
France entered 2026 with a fiscal imbalance that remained structurally large notwithstanding the reduction of the 2025 deficit from the previous year’s level. Eurostat records 2025 nominal GDP of €2.994733 trillion, a general-government deficit of €152.511 billion, equal to 5.1% of GDP, total government expenditure of 57.2% of GDP, total government revenue of 52.1%, and Maastricht gross debt of €3.460465 trillion, equivalent to 115.6% of GDP. The corresponding 2024 deficit had been 5.8% and debt 112.6%, so the 2025 accounts combine a lower annual deficit with a further increase in the public-debt ratio. Eurostat — France, 2022–2025 deficit, expenditure, revenue and debt data
The European Commission’s 21 May 2026 Spring Forecast records real GDP growth of 0.8% in 2025, inflation of 0.9%, unemployment of 7.7%, and projects growth of 0.8% in 2026 and 1.1% in 2027; under unchanged-policy assumptions, the Commission projects the government deficit remaining at 5.1% of GDP in 2026 before increasing to 5.7% in 2027, with debt rising to 118.1% in 2026 and 120.2% in 2027. The Commission identifies sizeable primary deficits as the principal mechanism behind the continuing debt increase and also points to weak domestic demand, energy-price pressure and higher defence-related activity as material macro-fiscal elements. European Commission — Economic forecast for France, 21 May 2026
France has been under an excessive-deficit procedure since 26 July 2024, when the Council acted on the 5.5% deficit recorded for 2023 under the then-applicable statistical vintage. The Council recommendation adopted on 21 January 2025 requires France to end the excessive-deficit situation by 2029 and limits nominal net-expenditure growth to 0.8% in 2025, 1.2% in each year from 2026 through 2028, and 1.1% in 2029. These figures constitute the operative corrective trajectory and should not be confused with the headline deficit itself, because the reformed framework monitors compliance primarily through the agreed net-expenditure path. Council of the European Union — Ongoing excessive-deficit procedure for France
Germany
Germany’s 2025 general-government accounts show nominal GDP of €4.469910 trillion, a deficit of €119.147 billion, or 2.7% of GDP, government expenditure of 50.5% of GDP, government revenue of 47.9%, and Maastricht debt of €2.838239 trillion, or 63.5% of GDP. The deficit ratio was unchanged from 2024, whereas the debt ratio rose from 62.2% to 63.5%. Eurostat — Germany, 2022–2025 deficit, expenditure, revenue and debt data
The Commission’s May 2026 forecast places Germany’s 2025 real GDP growth at only 0.2%, after the preceding period of economic weakness, with inflation at 2.3% and unemployment at 3.8%. It forecasts growth of 0.6% in 2026 and 0.9% in 2027, while the fiscal balance deteriorates to -3.7% of GDP in 2026 and -4.1% in 2027 and debt increases to 65.8% and 68.0% respectively. The Commission attributes the prospective fiscal expansion principally to higher defence expenditure, public investment and tax-relief measures, together with implementation of the 2025 reform of Germany’s constitutional fiscal framework. European Commission — Economic forecast for Germany, 21 May 2026
Germany is not currently subject to a deficit-based excessive-deficit procedure, but that fact does not remove it from EU fiscal surveillance because all member states operate under national medium-term fiscal-structural plans and Council-endorsed net-expenditure paths under the reformed Stability and Growth Pact. The significance of Germany’s projected deficit above 3% in 2026–2027 will therefore depend on the actual outturn, the applicable flexibility provisions and subsequent Commission and Council assessments rather than on the forecast alone. Council of the European Union — Excessive-deficit procedure and EU fiscal rules
Spain
Spain’s 2025 accounts record GDP of €1.687152 trillion, a general-government deficit of €40.330 billion, or 2.4% of GDP, expenditure of 45.3% of GDP, revenue of 42.9%, and Maastricht debt of €1.698225 trillion, equivalent to 100.7% of GDP. The same Eurostat series shows the deficit declining from 4.6% in 2022 to 3.3% in 2023, 3.2% in 2024 and 2.4% in 2025, while the debt ratio declined from 109.3% in 2022 to 100.7% in 2025. Eurostat — Spain, 2022–2025 deficit, expenditure, revenue and debt data
The Commission records real GDP growth of 2.8% in 2025, inflation of 2.7%, unemployment of 10.5% and a current-account surplus of 2.8% of GDP. Its May 2026 forecast projects growth of 2.4% in 2026 and 1.9% in 2027, a deficit of 2.4% in 2026 and 2.0% in 2027, and debt falling to 99.6% and 98.9% of GDP. The Commission identifies domestic demand, employment growth, inward migration, private consumption and Recovery and Resilience Plan-supported investment as major drivers of activity, while higher energy prices and international uncertainty remain downside pressures. European Commission — Economic forecast for Spain, 21 May 2026
Spain is not currently listed by the Council among the member states subject to an active deficit-based EDP. Its surveillance therefore operates through the preventive architecture of the reformed fiscal framework, including its medium-term fiscal-structural plan and net-expenditure trajectory. Council of the European Union — Current excessive-deficit procedures
Austria
Austria’s 2025 national accounts show GDP of €512.813 billion, a deficit of €21.464 billion, equal to 4.2% of GDP, general-government expenditure of 55.2% of GDP, revenue of 51.0%, and gross Maastricht debt of €418.078 billion, or 81.5% of GDP. The fiscal deterioration preceded 2025: Eurostat records a deficit of 2.6% in 2023 followed by 4.6% in 2024 and 4.2% in 2025, while the debt ratio increased from 77.8% in 2023 to 80.0% in 2024 and 81.5% in 2025. Eurostat — Austria, 2022–2025 deficit, expenditure, revenue and debt data
The Commission records 2025 growth of 0.6%, inflation of 3.6% and unemployment of 5.7%; it forecasts GDP growth of 0.6% in 2026 and 0.9% in 2027, deficits of 4.1% in both years, and debt rising to 83.4% in 2026 and 84.9% in 2027. The Austrian fiscal trajectory therefore remains one of continuing debt accumulation under subdued growth, notwithstanding the consolidation measures embedded in current policy. European Commission — Economic forecast for Austria, 21 May 2026
The Council opened an excessive-deficit procedure against Austria on 8 July 2025, on the basis of the 4.7% 2024 deficit figure used in the Council decision, and established 2028 as the deadline for ending the excessive deficit. The corrective path limits nominal net-expenditure growth to 2.6% in 2025, 2.2% in 2026, 2.2% in 2027 and 2.0% in 2028. Council of the European Union — Austria excessive-deficit procedure
Sweden
Sweden’s 2025 accounts record GDP of SEK 6.570039 trillion, a deficit of SEK 84.717 billion, or 1.3% of GDP, general-government expenditure of 49.9% of GDP, revenue of 48.6%, and Maastricht debt of SEK 2.305401 trillion, equivalent to 35.1% of GDP. Eurostat — Sweden, 2022–2025 deficit, expenditure, revenue and debt data
The Commission records 2025 GDP growth of 1.5%, inflation of 2.6% and unemployment of 8.8%. Its May 2026 forecast projects growth of 1.8% in 2026 and 2.2% in 2027, while the deficit increases to 2.8% in 2026 before easing to 2.5% in 2027, and gross debt rises from 35.1% in 2025 to 36.6% in 2026 and 37.7% in 2027. The Commission attributes much of the prospective fiscal expansion to tax reductions and materially higher expenditure, particularly defence spending, rather than to an existing excessive-deficit correction programme. European Commission — Economic forecast for Sweden, 21 May 2026
Sweden is not under an excessive-deficit procedure, but its projected expansionary fiscal stance remains within ordinary EU surveillance through the preventive arm of the fiscal framework. Council of the European Union — EU fiscal surveillance and current EDPs
Poland
Poland’s 2025 public accounts show GDP of PLN 3.912673 trillion, a general-government deficit of PLN 283.969 billion, equivalent to 7.3% of GDP, government expenditure of 50.9% of GDP, revenue of 43.6%, and Maastricht debt of PLN 2.335153 trillion, or 59.7% of GDP. The fiscal series shows the deficit widening from 3.4% in 2022 to 5.2% in 2023, 6.4% in 2024 and 7.3% in 2025, while debt increased from 48.8% to 59.7% of GDP over the same period. Eurostat — Poland, 2022–2025 deficit, expenditure, revenue and debt data
The Commission records real GDP growth of 3.6% in 2025, inflation of 3.3%, unemployment of 3.1%, and a current-account deficit of 0.7% of GDP. Its May forecast projects growth of 3.5% in 2026 and 2.8% in 2027, while the deficit narrows only gradually to 6.5% and 6.3%, and debt rises to 64.5% and 68.3% of GDP. The Commission explicitly identifies military-equipment deliveries, public-sector wages and social benefits as major contributors to the 2025 deficit increase and expects EU-funded investment and defence expenditure to remain important components of domestic demand. European Commission — Economic forecast for Poland, 21 May 2026
Poland entered the EDP on 26 July 2024, following a 2023 deficit of 5.1% in the statistical vintage used for the decision. The Council requires Poland to end the excessive-deficit situation by 2028, with nominal net-expenditure growth limited to 6.3% in 2025, 4.4% in 2026, 4.0% in 2027 and 3.5% in 2028. Council of the European Union — Poland excessive-deficit procedure
Romania
Romania’s 2025 fiscal accounts record GDP of RON 1.916405 trillion, a deficit of RON 151.063 billion, or 7.9% of GDP, government expenditure of 43.3% of GDP, revenue of only 35.4%, and Maastricht debt of RON 1.137324 trillion, equivalent to 59.3% of GDP. The underlying fiscal deterioration is visible in the multi-year series: deficits amounted to 6.5% of GDP in 2022, 6.6% in 2023, 9.3% in 2024 and 7.9% in 2025, while the debt ratio increased from 48.1% to 59.3%. Eurostat — Romania, 2022–2025 deficit, expenditure, revenue and debt data
The Commission records 2025 growth of 0.7%, inflation of 6.8%, unemployment of 6.1% and a current-account deficit of 7.9% of GDP. It projects near-stagnation at 0.1% growth in 2026, followed by 2.3% in 2027, while the government deficit declines to 6.2% in 2026 and 5.8% in 2027, debt rises to 61.6% and 63.4%, and inflation reaches 7.0% in 2026 before moderating. Fiscal consolidation, high energy-price inflation and falling real disposable income are identified by the Commission as major restraints on domestic consumption. European Commission — Economic forecast for Romania, 21 May 2026
Romania’s EDP is institutionally distinct because it has been open since 3 April 2020. The Council concluded in July 2024 that the procedure should remain open, and on 20 June 2025 formally determined that Romania had not taken effective action in response to the previous recommendations. A revised recommendation adopted on 8 July 2025 requires correction by 2030 and limits nominal net-expenditure growth to 2.8% in 2025, 2.6% in 2026, 4.6% in 2027, 4.4% in 2028, 4.2% in 2029 and 4.0% in 2030. Council of the European Union — Romania excessive-deficit procedure and revised corrective path
United Kingdom
The United Kingdom must be analysed on its own institutional definitions because it is outside the EU Stability and Growth Pact and is therefore not subject to an EU excessive-deficit procedure. Its principal domestic fiscal measures are public sector net borrowing, the current budget balance, public sector net debt and public sector net financial liabilities, rather than the EDP indicators used by EU institutions.
The Office for National Statistics initially estimated borrowing in the financial year ending March 2026 at £132.0 billion and subsequently revised it to £129.0 billion as improved central-government data became available. The first estimate represented 4.3% of GDP; ONS subsequently reported that central-government receipts had risen strongly during the year, including increases in Income Tax, VAT, Corporation Tax and compulsory social contributions after the April 2025 change in employer National Insurance contributions. ONS — Public sector finances, UK: April 2026, revision of FY 2025/26 borrowing
At the end of March 2026, ONS initially estimated public-sector net debt excluding public-sector banks at 93.8% of GDP, or approximately £2.911 trillion, and public-sector net financial liabilities at 83.3% of GDP; ONS subsequently revised the March debt stock upward by £6.4 billion to £2.9172 trillion as Bank of England and Network Rail information was updated. These revisions illustrate why the UK data must be treated by statistical vintage rather than represented as immutable point estimates. ONS — Public sector finances, UK: March 2026 ONS — April 2026 revisions to public-sector debt
By June 2026, public-sector net debt was provisionally estimated at £2.9899 trillion, or 94.9% of GDP, while public-sector net financial liabilities stood at 84.5% of GDP. The UK government’s legislated fiscal rules require the current budget to be in surplus and public-sector net financial liabilities to be falling as a share of GDP by financial year 2029/30. These are domestic UK fiscal tests and must not be substituted for the EU’s 3% deficit and 60% debt reference values. ONS — Public sector finances, UK: June 2026
Belgium
Belgium recorded 2025 GDP of €642.015 billion, a deficit of €33.220 billion, or 5.2% of GDP, government expenditure of 54.2% of GDP, revenue of 49.0%, and gross public debt of €692.461 billion, equivalent to 107.9% of GDP. Eurostat — Belgium, 2022–2025 deficit, revenue, expenditure and debt data
The Commission’s May 2026 forecast records 2025 GDP growth of 1.0%, inflation of 3.0% and unemployment of 6.2%, while projecting deficits of 5.2% in 2026 and 5.4% in 2027 and debt of 110.5% and 112.8% respectively. The Commission identifies higher defence expenditure and increasing interest costs as material pressures on the later fiscal trajectory. European Commission — Economic forecast for Belgium, 21 May 2026
Belgium’s EDP was opened in July 2024; after an initial recommendation targeting correction by 2027, the Council adopted a revised recommendation on 20 June 2025 extending the correction deadline to 2029, with net-expenditure growth limits of 3.6% in 2025, 2.5% in 2026, 2.5% in 2027, 2.1% in 2028 and 2.1% in 2029. Council of the European Union — Belgium excessive-deficit procedure
Finland
Finland recorded 2025 GDP of €280.570 billion, a deficit of €9.613 billion, or 3.4% of GDP, government expenditure of 57.5% of GDP, revenue of 54.1%, and Maastricht debt of €248.433 billion, equivalent to 88.5% of GDP. Debt had risen from 74.0% of GDP in 2022 to 88.5% by 2025. Eurostat — Finland, 2022–2025 deficit, revenue, expenditure and debt data
The Commission records GDP growth of only 0.2% in 2025 and forecasts growth of 0.8% in 2026 and 1.4% in 2027, but expects the deficit to widen to 4.5% and 4.6% while debt increases to 91.2% and 93.1%. Among the expenditure pressures specifically identified by the Commission are the large delivery of F-35 aircraft, rising interest payments and public-sector wage agreements. European Commission — Economic forecast for Finland, 21 May 2026
The Council opened Finland’s EDP on 20 January 2026, following a 4.4% deficit in 2024 and the fiscal projections available at the time, and established cumulative nominal net-expenditure growth limits of 2.5% in 2026, 4.1% in 2027 and 5.9% in 2028. Council of the European Union — Finland excessive-deficit procedure
Hungary
Hungary’s 2025 accounts record GDP of HUF 87.046 trillion, a deficit of HUF 4.059 trillion, or 4.7% of GDP, government expenditure of 47.3% of GDP, revenue of 42.6%, and public debt of HUF 64.912 trillion, equivalent to 74.6% of GDP. Eurostat — Hungary, 2022–2025 deficit, revenue, expenditure and debt data
The Commission records 2025 GDP growth of 0.5% and inflation of 4.4%, while forecasting growth of 1.8% in 2026 and 2.1% in 2027. It expects the deficit to increase sharply to 6.2% in 2026 and remain at 5.8% in 2027, with debt rising to 75.1% and 76.8% of GDP, attributing the deterioration to deficit-increasing measures introduced in late 2025 and early 2026. European Commission — Economic forecast for Hungary, 21 May 2026
Hungary has been in an EDP since 26 July 2024, following the 6.7% 2023 deficit used in that decision, and the Council requires correction by 2026, with nominal net-expenditure growth limited to 4.3% in 2025 and 4.0% in 2026. Council of the European Union — Hungary excessive-deficit procedure
Slovakia
Slovakia recorded 2025 GDP of €136.754 billion, a deficit of €6.086 billion, or 4.5% of GDP, expenditure of 47.9% of GDP, revenue of 43.5%, and gross debt of €83.957 billion, equivalent to 61.4% of GDP. Eurostat — Slovakia, 2022–2025 deficit, revenue, expenditure and debt data
The Commission records 0.8% GDP growth in 2025, inflation of 4.2% and unemployment of 5.4%; it forecasts growth remaining at 0.8% in 2026 before reaching 1.5% in 2027, while the deficit rises from 4.5% to 4.6% and 5.4% and debt increases to 63.7% and 66.9%. Fiscal consolidation is expected to restrain private consumption, while EU funds continue to support investment. European Commission — Economic forecast for Slovakia, 21 May 2026
Slovakia entered the EDP on 26 July 2024, following the 4.9% 2023 deficit used for the Council decision. Its corrective net-expenditure limits are 3.8% in 2025, 0.9% in 2026 and 1.6% in 2027. Council of the European Union — Slovakia excessive-deficit procedure
Bulgaria
Bulgaria’s 2025 accounts show GDP of €116.018 billion, a deficit of €4.113 billion, or 3.5% of GDP, public expenditure of 41.7% of GDP, revenue of 38.1%, and debt of €34.635 billion, equivalent to 29.9% of GDP. Eurostat — Bulgaria, 2022–2025 deficit, revenue, expenditure and debt data
The Commission’s May forecast records 3.1% GDP growth in 2025 and projects 2.5% in 2026 and 2.2% in 2027, but it expects the general-government deficit to increase from 3.5% in 2025 to 4.1% in 2026 and 4.3% in 2027, while debt rises from 29.9% to 32.3% and 35.5%. Social expenditure and public-sector wages are identified as important contributors to the fiscal deterioration. European Commission — Economic forecast for Bulgaria, 21 May 2026
On 10 July 2026, the Council opened an EDP against Bulgaria on the basis of a projected 4.1% deficit in 2026 and an expected continued breach in 2027. Bulgaria was required to present effective measures by 15 October 2026, while cumulative nominal net-expenditure growth must not exceed 4.2% in 2026, 7.7% in 2027, 11.4% in 2028 and 15.0% in 2029. Council of the European Union — Bulgaria excessive-deficit procedure, 10 July 2026
Malta: A Completed EDP Case
Malta provides an important procedural case because its excessive-deficit procedure has already been formally terminated. Eurostat records 2025 GDP of €24.577 billion, a deficit of €545 million, or 2.2% of GDP, government expenditure of 37.0%, revenue of 34.8%, and public debt of €11.397 billion, or 46.4% of GDP. The deficit had fallen from 5.3% in 2022 to 4.4% in 2023, 3.4% in 2024 and 2.2% in 2025. Eurostat — Malta, 2022–2025 deficit, revenue, expenditure and debt data
The Commission forecasts Malta’s deficit remaining below the Treaty reference value at 2.2% in 2026 and 2.1% in 2027, while real GDP is projected to expand by 3.7% and 3.6% and debt remain around 46% of GDP. European Commission — Economic forecast for Malta, 21 May 2026
On 12 June 2026, the Council formally abrogated Malta’s excessive-deficit procedure, concluding that the deficit had been successfully and durably reduced below 3% of GDP. This is procedurally important because it documents the evidentiary standard used by the Council when closing an EDP: the issue is not merely the observation of a single sub-3% figure but the conclusion that the correction is sufficiently durable under the applicable forecast and fiscal path. Council of the European Union — Closure of Malta’s excessive-deficit procedure, 12 June 2026
Institutional Reading of the European Record
As of 23 September 2026, the Council’s public record shows active excessive-deficit procedures for Austria, Belgium, Bulgaria, Finland, France, Italy, Hungary, Poland, Slovakia and Romania, with different opening dates, expenditure paths and correction horizons determined through individual Council decisions and recommendations. Malta’s procedure was terminated in June 2026 after the Council concluded that the correction was durable. Council of the European Union — Current EDP status and timeline, last reviewed 10 July 2026
The statistical layer must be kept separate from that legal layer. Eurostat’s April 2026 notification reports the actual 2025 deficit, revenue, expenditure and Maastricht-debt data under ESA 2010, whereas the Commission’s 21 May 2026 forecasts estimate 2026–2027 developments under stated policy and macroeconomic assumptions, and Council EDP decisions determine the legally operative corrective trajectory. A 2025 outturn, a 2026 forecast and an EDP deadline are consequently three different categories of evidence and must never be merged into a single number or political assertion. Eurostat — EDP methodology and 2025 statistical notification Council of the European Union — Excessive-deficit procedure framework
For the Italian investigation, these country files should therefore be used as independent institutional records, not as a league table and not as evidence that one state’s fiscal choices excuse or condemn another’s. The analytically relevant question is whether the same statistical definitions, procedural tests, durability requirements, net-expenditure rules, flexibility mechanisms and evidentiary standards have been applied consistently to the individual national cases; establishing that requires document-level examination of the relevant Commission assessments and Council decisions rather than political inference from headline deficit percentages alone.
What Is Established at This Stage
The September 2026 ISTAT revision establishes that Italy produced €2.265 trillion of nominal GDP in 2025, real GDP growth of 0.6%, a general-government deficit of 3.1% of GDP, a primary surplus of 0.8%, and a tax burden of 42.9% of GDP.
The European institutional record establishes that Italy remains within an excessive-deficit procedure whose formal correction deadline is 2026, not 2025, and whose current corrective path limits nominal net-expenditure growth to the Council-prescribed rates.
The Commission’s May 2026 forecast establishes that, under the assumptions prevailing at that time, Italy was expected to move below the 3% deficit reference value in 2026 while its debt ratio continued to increase.
The official record therefore supports describing Italy as undergoing a substantial fiscal adjustment that is not yet institutionally complete, rather than reducing the situation either to a political accusation against the government or to a claim that no fiscal problem remains.
What requires further investigation is the more politically consequential question: whether the statistical, institutional and fiscal treatment applied to Italy during this adjustment has followed normal European practice consistently, or whether identifiable departures, asymmetries or institutional decisions exist that would support the proposition of deliberate pressure on the government. That question must be established document by document rather than assumed at the beginning of the investigation.
Principal Gaps and Watch Indicators
The first critical record is the next harmonised Eurostat excessive-deficit notification incorporating the revised Italian national accounts, because it will provide the authoritative European statistical treatment of the September ISTAT revisions.
The second is the complete technical documentation behind the movement of the underlying 2025 deficit numerator and denominator, including the precise transactions responsible for the revision from the spring estimates.
The third is the Commission’s next effective-action assessment of Italy under the EDP, because the institutional significance of 2025 cannot be separated from the Council’s formal 2026 correction deadline.
The fourth is the Italian government’s updated fiscal plan and budget documentation, which will determine how the government proposes to reconcile deficit reduction, tax policy, defence expenditure, energy measures, investment and debt service.
The fifth is the technical record concerning ISTAT–Eurostat interaction, particularly any reservations, methodological correspondence or classification disputes capable of establishing whether the September revisions were routine implementation of European statistical rules or involved contested judgments with material fiscal consequences.
The sixth is the full decomposition of the increase in Italy’s fiscal burden to 42.9%, without which political claims concerning “higher taxes” remain too aggregated for government-level analysis.
Italy’s Fiscal Test Has Moved Beyond the 3% Deficit
Italy is approaching the point at which success under Europe’s excessive-deficit procedure will cease to be the hardest fiscal problem. The Government’s 2026 baseline puts the deficit at 2.9% of GDP, while the European Commission also projects 2.9% in both 2026 and 2027; yet the same Commission forecast places public debt at 138.5% of GDP in 2026 and 139.2% in 2027. European Commission The contradiction is the policy story: Rome can cross below the Treaty deficit threshold while its sovereign balance sheet continues to deteriorate. The next fiscal phase will therefore be decided not by one decimal point, but by whether primary surpluses, nominal growth and investment can outrun interest costs, demographic expenditure and the end of the Recovery and Resilience Facility.
Falling below 3% will not make the debt turn
Italy’s 2025 accounts already show why deficit and debt have diverged. The general-government deficit remained 3.1% of GDP, but the primary balance returned to a surplus of 0.8%, meaning that the state collected more than it spent before interest. Interest expenditure, however, amounted to roughly €87 billion in the detailed 2025 account, while Maastricht debt exceeded €3.09 trillion. ISTAT Banca d’Italia
The debt stock increased by substantially more than the annual deficit because the cash borrowing requirement reached €109.2 billion, Treasury liquid assets increased by €14.7 billion, and another approximately €4.6 billion reflected issuance discounts, inflation-linked revaluation, exchange-rate effects and related adjustments. Banca d’Italia This is the mechanism that matters after 2026: even a compliant headline deficit does not guarantee a declining debt ratio when stock-flow adjustments and debt service continue to work in the opposite direction.
The real constraint is becoming the cost of carrying €3 trillion of debt
Italy’s average residual public-debt maturity stood at approximately 7.9 years at end-2025, which protects the Treasury from an immediate repricing of the entire stock but spreads the impact of higher yields across several budget years. At the same time, the share of government debt held by Banca d’Italia fell from 21.6% at end-2024 to 18.5% at end-2025, increasing the proportion that must ultimately be absorbed by other investors as Eurosystem holdings decline. Banca d’Italia
The European Commission expects Italian interest expenditure to rise by about 0.3 percentage points of GDP in 2026, citing higher yields and the effect of inflation-linked securities. European Commission This creates a delayed refinancing problem rather than a sudden funding crisis: debt issued during the low-rate period expires gradually, while replacement securities embed a different cost structure. The result is that fiscal adjustment must continue even after the excessive-deficit procedure has ceased to dominate political debate.
Rome’s original debt path is already harder to reach
The Government’s earlier Medium-Term Fiscal-Structural Plan assumed debt of 137.8% of GDP in 2026, 137.5% in 2027, 136.4% in 2028, 134.9% in 2029 and 133.9% in 2030. That trajectory depended on a structural primary balance strengthening from 0.6% in 2026 to 2.7% by 2030. Ministry of Economy and Finance
The Commission’s May 2026 forecast now places debt at 139.2% in 2027, 1.7 percentage points above the level embedded in that earlier plan. European Commission Even if Italy subsequently achieved exactly the annual debt reductions assumed in the original path, mechanically re-basing those reductions from the higher 2027 starting point would leave debt around 135.6% in 2030, rather than 133.9%. The gap is not a forecast; it is arithmetic, and it shows how difficult lost debt-ratio ground is to recover.
The end of the RRF creates the next investment test
Italy’s amended Recovery and Resilience Plan is worth approximately €194.4 billion, including about €71.8 billion in non-repayable support and €122.6 billion in loans. European Commission In 2026, RRF-supported investment remains one of the few strong domestic supports to an economy for which the Commission projects only 0.5% real growth; from 2027, the Commission expects the phase-out of RRF projects to reduce capital expenditure. European Commission
That creates a fiscal choice more difficult than simply preserving the existing spending level. Replacing EU-financed investment with nationally financed investment would increase pressure on the budget; allowing productive investment to fall sharply would weaken the growth denominator needed to reduce a debt ratio close to 140% of GDP. The quality of post-PNRR spending therefore becomes part of sovereign-debt management, not merely industrial policy.
Defence is arriving just as demographic costs rise
Italy’s ordinary 2026 Defence budget is approximately €32.4 billion, while the formal State budget allocates roughly €30.5 billion to Mission 5, Defence and territorial security. Ministero della Difesa These accounting definitions are not identical to NATO expenditure, but the direction of travel is clear: the Alliance’s 2025 Hague commitment requires members to move toward 5% of GDP by 2035, including at least 3.5% for core defence and up to 1.5% for wider security-related expenditure. NATO
At the same time, the European Commission’s Ageing Report projects Italian gross public pension expenditure rising from 15.6% of GDP in 2022 to 16.6% in 2030, before reaching approximately 17.3% in 2036. European Commission ISTAT’s August 2026 demographic projections place the resident population at 58.7 million in 2030, with the natural balance around −353,000 and the share aged 85 or over rising to 4.4%. ISTAT Defence and ageing are therefore beginning to compete for the same structural fiscal space.
The European procedure is not the final constraint
Italy’s excessive-deficit procedure was opened on 26 July 2024, and the Council set 2026 as the correction deadline, with net-expenditure growth capped at 1.3% in 2025 and 1.6% in 2026. Council of the European Union The Commission’s 3 June 2026 effective-action assessment did not escalate the case; Italy’s procedure was held in abeyance, indicating recognised corrective action while the legal procedure remained open. European Commission
That institutional position matters because it strips away one politically convenient explanation. The verified record does not show Italy being subjected, at this stage, to the most severe branch of the EU enforcement mechanism. The harder constraint is domestic arithmetic: once the deficit has been corrected, the Government still has to produce a debt decline under weaker growth, higher interest expenditure and increasing structural spending commitments.
The next 24 months will determine whether correction becomes sustainability
Between late 2026 and 2028, three numbers will matter more than the political symbolism of the 3% threshold: the primary surplus, the debt peak and the level of public investment after the RRF. If the deficit remains around 2.9%, stock-flow adjustments fade and the primary balance strengthens, Italy can begin converting fiscal compliance into debt reduction; if debt continues rising beyond the Commission’s 139.2% of GDP forecast for 2027, the cost of adjustment moves into the following budget cycles. European Commission
The cost of inaction would not fall on one institution. The Treasury would absorb higher refinancing expenditure; ministries would compete with pensions and defence for a narrower discretionary budget; businesses would face weaker infrastructure and investment support if capital expenditure is compressed; and taxpayers would ultimately finance a larger interest burden if stronger nominal growth fails to emerge. By 2028, Italy will therefore be judged less by whether it escaped one European procedure than by whether it used that exit to place the €3 trillion sovereign balance sheet on a credible downward path.
INDEX
Italy’s fiscal system: accounts, taxation, expenditure and sovereign debt
A forensic reconstruction of Italy’s general-government accounts from the underlying cash and accrual flows rather than from the headline deficit alone, covering GDP, revenues, taxation and social contributions, current and capital expenditure, primary balance, interest expenditure, borrowing requirement, Maastricht debt, Treasury liquidity, debt ownership, maturity structure, stock-flow adjustments and the statistical revisions that altered the 2025 accounts.
Statistical governance, European fiscal law and Italy’s excessive-deficit procedure
A complete institutional reconstruction of the production and validation of Italian fiscal statistics through ISTAT, Banca d’Italia, Eurostat and the Ministry of Economy and Finance, followed by the legal architecture of the Stability and Growth Pact, the 3% and 60% reference values, net-expenditure rules, debt-sustainability requirements, Italy’s EDP from 2024 onward, the 2026 correction deadline, statistical revisions, defence and energy flexibility, SAFE financing and the conditions legally required for closure of the procedure.
European sovereign fiscal files
Individual, non-ranked fiscal dossiers for France, Germany, Spain, Austria, Sweden, Poland, Romania, the United Kingdom, Belgium, Finland, Hungary, Slovakia, Bulgaria and Malta, examining the same core variables—deficit, debt, revenues, expenditure, interest costs, growth, taxation, structural pressures, fiscal rules and institutional surveillance—without using one national case as rhetorical justification or condemnation of another.
Institutional consistency and the political-pressure question
A documentary audit of whether statistical definitions, accounting classifications, fiscal-rule interpretations, effective-action assessments, escape clauses, expenditure constraints and EDP closure requirements have been applied consistently, followed separately by an evidence-based examination of the proposition that the Italian government has faced deliberate institutional or political pressure, with motive never inferred from fiscal outcomes alone.
Italy 2026–2030: sustainability, scenarios and final institutional assessment
A forward assessment integrating nominal and real growth, inflation, primary balances, interest rates, refinancing requirements, debt maturity, defence commitments, post-PNRR investment, demographic expenditure pressures and stock-flow adjustments, followed by transparent fiscal scenarios, observable warning indicators, unresolved official records and a final government-level assessment.
Chapter 1 — Italy’s Fiscal Accounts Beneath the 3.1% Deficit
Principal judgment
Italy’s 3.1% general-government deficit for 2025 cannot be interpreted correctly as a stand-alone measure of fiscal performance, because the same public accounts show a positive primary balance, a large debt-service burden, total revenues exceeding €1 trillion, public expenditure above €1.15 trillion, debt increasing by substantially more than the accounting deficit, and a material difference between the accrual-based deficit used under European fiscal rules and the cash borrowing requirement that actually contributed to the increase in government debt.
The latest official statistical vintage published by ISTAT on 22 September 2026 places 2025 nominal GDP at €2.265003 trillion, €6.954 billion above the March estimate, while general-government net borrowing was revised to €69.736 billion, still equal to 3.1% of GDP at one-decimal precision. The same release confirms a primary surplus of 0.8% of GDP, a tax burden of 42.9%, real GDP growth of 0.6%, gross fixed-capital formation growth of 3.9%, final consumption growth of 1.0%, export growth of 1.7% and import growth of 4.2%. [ISTAT, Conti economici nazionali – Anni 2010-2025, 22 September 2026] Official ISTAT national accounts release
These figures establish that the Italian fiscal adjustment in 2025 occurred through a combination of stronger revenues, a restored primary surplus and still substantial interest expenditure, rather than through elimination of the underlying borrowing requirement. That distinction becomes critical once the general-government deficit is reconciled with the €128.6 billion increase in Maastricht debt between end-2024 and end-2025, because the difference cannot be understood without examining cash financing, Treasury liquidity and other stock-flow adjustments. [Banca d’Italia, Stime del debito e del fabbisogno delle Amministrazioni pubbliche per l’anno 2025, 16 February 2026] Official Banca d’Italia debt and borrowing requirement release
The 2025 fiscal account: the complete operating picture
The most useful starting point is not the deficit ratio but the consolidated economic account of the general-government sector, because this identifies the flows that generated the final balance. ISTAT’s April 2026 parliamentary evidence, based on the then-current 2025 national-account vintage, placed total revenues at €1.085928 trillion and total expenditure at €1.155309 trillion, producing net borrowing of €69.381 billion; the September revision subsequently adjusted net borrowing to €69.736 billion and nominal GDP to €2.265003 trillion while leaving the published deficit ratio at 3.1%. The April table therefore remains useful for the detailed composition of the account but must be labelled as the earlier fiscal vintage rather than silently combined with the September aggregate. [ISTAT, Esame del Documento di finanza pubblica 2026, April 2026] Official ISTAT parliamentary evidence on the 2026 Public Finance Document
Consolidated Italian general-government account — detailed 2025 operating structure
| Fiscal component | 2025 amount | Function in the account | Official source |
|---|---|---|---|
| Market and own-account production | €52.505 bn | Government output sold or produced for own use | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Direct taxes | €346.040 bn | Personal, corporate and other direct taxation recorded in national accounts | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Indirect taxes | €317.491 bn | VAT, excises and other production/import taxes | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Actual social contributions | €301.423 bn | Compulsory social-security contributions | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Imputed social contributions | €4.453 bn | National-account imputed contribution flows | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Other current revenue | €48.249 bn | Property income, transfers and miscellaneous current receipts | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Total current revenue | €1,070.161 bn | Recurring government revenue before capital receipts | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Capital taxes | €3.106 bn | Non-recurring capital levies | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Other capital revenue | €12.661 bn | Capital transfers and other capital receipts | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Total revenue | €1,085.928 bn | Total consolidated government receipts | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Compensation of public employees | €203.842 bn | Wages and employer social costs | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Intermediate consumption | €132.956 bn | Goods and services purchased for government operations | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Social transfers in kind purchased on market | €52.980 bn | Market-provided social goods and services financed by government | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Cash social benefits | €459.198 bn | Pensions and other monetary social transfers | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Other current expenditure | €85.278 bn | Subsidies, transfers and other current items | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Current expenditure excluding interest | €934.254 bn | Primary current expenditure | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Interest expenditure | €87.146 bn | Accrual interest on government liabilities under ESA rules | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Total current expenditure | €1,021.400 bn | Current primary expenditure plus interest | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Gross fixed capital formation | €86.716 bn | Direct public investment | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Investment grants | €37.839 bn | Capital transfers supporting investment by other sectors | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Other capital expenditure | €9.354 bn | Remaining capital transactions | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Total capital expenditure | €133.909 bn | Aggregate capital-side expenditure | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Total expenditure | €1,155.309 bn | Consolidated government expenditure | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Primary balance | +€17.765 bn | Revenue minus expenditure excluding interest | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Net borrowing | −€69.381 bn | ESA general-government deficit, April vintage | [ISTAT, DFP 2026 parliamentary evidence] Official source |
| Revised net borrowing | −€69.736 bn | September 2026 revised national-accounts vintage | [ISTAT, National Accounts, Sep 2026] Official September revision |
The table reveals an important structural fact that disappears in political debate about whether the final ratio is 3.0 or 3.1: interest expenditure alone was approximately €87 billion, exceeding the entire headline deficit. Without that interest burden, the general-government sector was in surplus on the primary definition used by ISTAT. [ISTAT, Esame del Documento di finanza pubblica 2026] Official ISTAT fiscal account
The September release confirms this structural result even after the national-account revision: the primary balance remained +0.8% of GDP, while interest expenditure increased by 2.0% in nominal terms compared with 2024. [ISTAT, Conti economici nazionali – Anni 2010-2025] Official September 2026 ISTAT release
From primary surplus to headline deficit
The arithmetic of the Italian account can therefore be reconstructed directly.
Using the April fiscal account, the primary balance was approximately +€17.8 billion, while interest expenditure was approximately €87.1 billion; the difference produced net borrowing of approximately €69.4 billion. [ISTAT, Esame del Documento di finanza pubblica 2026] Official source
Fiscal balance bridge
| Accounting stage | Amount | Interpretation | Source |
|---|---|---|---|
| Government revenue | €1,085.928 bn | Total consolidated receipts | [ISTAT] Official table |
| Primary expenditure | €1,068.163 bn | Total expenditure excluding interest, calculated from ISTAT totals | [ISTAT inputs] Official table |
| Primary balance | +€17.765 bn | Fiscal position before debt-service cost | [ISTAT] Official table |
| Interest expenditure | −€87.146 bn | Debt-service expenditure | [ISTAT] Official table |
| Net borrowing, April vintage | −€69.381 bn | ESA general-government deficit | [ISTAT] Official April EDP vintage |
| Net borrowing, September vintage | −€69.736 bn | Revised ESA deficit | [ISTAT] Official September revision |
ISTAT’s April Maastricht notification independently confirmed that 2025 interest expenditure was 3.9% of GDP, unchanged as a share of GDP from 2024, and clarified that under the applicable accounting rules the interest measure does not include the impact of swap operations. [ISTAT, Notifica dell’indebitamento netto e del debito delle Amministrazioni Pubbliche secondo il trattato di Maastricht – Anni 2022/2025] Official Maastricht notification
This means that almost four percentage points of Italian GDP were absorbed by interest on accumulated government liabilities in 2025. The state could therefore operate a primary surplus and still record a deficit above the Treaty reference value because the fiscal system inherited a debt stock exceeding €3 trillion.
Revenue growth, not expenditure compression alone, drove the adjustment
The fiscal correction between 2024 and 2025 cannot be described simply as an expenditure-cutting programme because the official accounts show substantial revenue growth. In the March vintage, ISTAT estimated total government revenues had increased by 4.5% year on year, with current revenues rising by 4.1%; the strongest increase occurred in social contributions, which rose by 10.0%, partly because of the termination of employee contribution exemptions. [ISTAT, Pil e indebitamento delle AP – Anni 2023-2025, 2 March 2026] Official March 2026 fiscal account
Main revenue dynamics in the original 2025 fiscal account
| Revenue category | 2025 amount | 2025 annual change | Fiscal significance | Official source |
|---|---|---|---|---|
| Direct taxes | €346.040 bn | +0.7% | Large but relatively stable direct-tax base | [ISTAT] Official fiscal tables |
| Indirect taxes | €317.491 bn | +2.5% | VAT, excises and production/import taxation | [ISTAT] Official fiscal tables |
| Social contributions | approximately €305.9 bn including actual and imputed contributions | Actual contribution flows were a principal growth component | Strong contribution from labour-market and contribution-policy effects | [ISTAT] Official fiscal tables |
| Other current revenues | €48.249 bn | +6.5% in the March account | Additional contribution to current receipts | [ISTAT] Official March release |
| Total current revenue | €1,070.161 bn | +4.1% | Main source of improvement in current balance | [ISTAT] Official fiscal tables |
The composition is important because it changes the political interpretation of the fiscal consolidation. The improvement in the deficit was not generated exclusively by discretionary reductions in government spending; a substantial part came through the revenue side, particularly the expansion of compulsory social contributions and other tax receipts.
That revenue effect also explains why the fiscal burden rose. The September national accounts revised the 2025 tax burden to 42.9% of GDP, an increase of 0.7 percentage points over 2024. [ISTAT, Conti economici nazionali – Anni 2010-2025] Official September release
The earlier April DFP vintage had placed the ratio at 43.1%, illustrating why statistical vintage must always be printed beside politically sensitive fiscal numbers. [ISTAT, Esame del Documento di finanza pubblica 2026] Official April fiscal table
Evolution of the tax burden across official vintages
| Reference | 2025 tax burden | Status | Official source |
|---|---|---|---|
| April 2026 fiscal-account vintage | 43.1% of GDP | Earlier provisional estimate | [ISTAT] April DFP evidence |
| September 2026 revised national accounts | 42.9% of GDP | Latest official national-account vintage | [ISTAT] September revision |
| Revision | −0.2 percentage points | Change between statistical vintages, not a tax-policy decision | Calculated from the two official ISTAT releases above |
The revision itself demonstrates why national-account updates cannot automatically be interpreted politically: the September exercise simultaneously left the deficit at 3.1%, raised measured GDP, increased measured real growth and reduced the previously estimated tax burden from 43.1% to 42.9%.
Expenditure remained structurally large even as the deficit fell
The 2025 fiscal adjustment did not result from a collapse in government activity. The April detailed account places total expenditure at €1.155 trillion, including €934.3 billion of current expenditure excluding interest, €87.1 billion of interest expenditure and €133.9 billion of capital expenditure. [ISTAT, Esame del Documento di finanza pubblica 2026] Official fiscal tables
Cash social benefits alone reached €459.2 billion, making them the largest individual expenditure block in the consolidated account; public-employee compensation amounted to €203.8 billion, intermediate consumption to €133.0 billion, and gross fixed capital formation to €86.7 billion. [ISTAT, Esame del Documento di finanza pubblica 2026] Official fiscal tables
Structural expenditure blocks
| Expenditure block | 2025 amount | Share of the fiscal mechanism | Official source |
|---|---|---|---|
| Cash social benefits | €459.198 bn | Largest structural current expenditure component | [ISTAT] Source |
| Public-sector employee compensation | €203.842 bn | Government wage bill and associated labour costs | [ISTAT] Source |
| Intermediate consumption | €132.956 bn | Goods and services used by public administrations | [ISTAT] Source |
| Purchased social transfers in kind | €52.980 bn | Market services delivered to households through government financing | [ISTAT] Source |
| Interest | €87.146 bn | Cost of servicing the sovereign liability stock | [ISTAT] Source |
| Gross fixed investment | €86.716 bn | Direct public capital formation | [ISTAT] Source |
| Investment grants | €37.839 bn | Capital support to investment outside direct government production | [ISTAT] Source |
This expenditure architecture matters for future fiscal adjustment because the politically discretionary share of the budget is smaller than the headline €1.15 trillion total might suggest. Social transfers, public employment, interest and essential public-service consumption account for a large share of recurring spending, while investment cuts can improve short-term cash balances at the cost of reducing future productive capacity. The composition of adjustment therefore matters at least as much as its aggregate size.
Why debt increased by much more than the deficit
The most important accounting distinction in the entire Italian fiscal file is the difference between net borrowing under ESA national accounts and the cash borrowing requirement that feeds directly into financing needs.
ISTAT’s 2025 net borrowing was approximately €69.7 billion, whereas Banca d’Italia calculated the cash borrowing requirement of general government at €109.2 billion. At the same time, the Maastricht debt stock increased from €2.9669 trillion at end-2024 to approximately €3.0955 trillion at end-2025, an increase of roughly €128.6 billion in the initial Banca d’Italia estimate. [Banca d’Italia, Stime del debito e del fabbisogno delle Amministrazioni pubbliche per l’anno 2025] Official Banca d’Italia release
The difference is explicitly explained by Banca d’Italia. The increase in debt reflected €109.2 billion of government borrowing requirement, an increase of €14.7 billion in Treasury liquid assets, taking Treasury liquidity to €52.4 billion, and approximately €4.6 billion generated by issuance and redemption discounts or premiums, revaluation of inflation-linked securities and exchange-rate changes. [Banca d’Italia, 16 February 2026] Official debt reconciliation
Reconciliation of the 2025 debt increase
| Driver of debt change | Amount | Accounting meaning | Official source |
|---|---|---|---|
| General-government cash borrowing requirement | €109.2 bn | Cash financing requirement generated during 2025 | [Banca d’Italia] Official release |
| Increase in Treasury liquid assets | €14.7 bn | Borrowing undertaken but retained as liquid Treasury resources | [Banca d’Italia] Official release |
| Discounts/premiums, inflation-linked revaluation and exchange-rate effects | €4.6 bn | Valuation and issuance effects affecting debt independently of the deficit | [Banca d’Italia] Official release |
| Approximate increase in gross debt | €128.5 bn | Sum of the principal identified drivers | Calculated from Banca d’Italia official components |
| End-2024 debt | €2,966.9 bn | Opening Maastricht debt stock | [Banca d’Italia] Official release |
| End-2025 debt | €3,095.5 bn initial Banca d’Italia estimate | Closing debt stock | [Banca d’Italia] Official release |
| Eurostat/April EDP debt | €3,095.888 bn | Harmonised Maastricht notification figure | [Eurostat] Official April 2026 EDP notification |
Eurostat’s April harmonised EDP notification subsequently placed Italian debt at €3.095888 trillion, or 137.1% of GDP. [Eurostat, Provision of deficit and debt data for 2025 – first notification, 22 April 2026] Official Eurostat notification
This reconciliation is essential because the often-repeated assumption that “a €69 billion deficit should increase debt by €69 billion” is incorrect. The deficit is an accrual-based national-account measure, while debt is a balance-sheet stock influenced by cash financing and financial transactions not captured one-for-one in the deficit.
Central government generated virtually the entire increase in debt
Banca d’Italia’s sectoral decomposition shows that consolidated central-government debt increased by €132.0 billion in 2025 to €3.0163 trillion, while consolidated local-government debt actually declined by €3.4 billion to €79.1 billion; social-security institutions remained broadly unchanged. [Banca d’Italia, 16 February 2026] Official subsector decomposition
Debt by government subsector
| Government subsector | 2025 position/change | Institutional significance | Official source |
|---|---|---|---|
| Central government | €3.0163 tn debt; +€132.0 bn in 2025 | Dominant source of sovereign-debt accumulation | [Banca d’Italia] Official release |
| Local government | €79.1 bn debt; −€3.4 bn | Local administrations reduced consolidated debt | [Banca d’Italia] Official release |
| Social-security institutions | Broadly stable | Negligible contribution to annual debt-stock increase | [Banca d’Italia] Official release |
This means that any serious discussion of Italian debt sustainability must focus predominantly on central-government financing operations, Treasury issuance and the national fiscal balance rather than attributing the 2025 debt expansion principally to municipal or regional borrowing.
Debt maturity and central-bank holdings changed the financing environment
The debt stock is not adequately described by its €3.1 trillion headline amount because refinancing risk depends on when liabilities mature and who holds them.
Banca d’Italia reports that the average residual maturity of Italian general-government debt remained approximately 7.9 years at end-2025, essentially unchanged from the end of 2024. [Banca d’Italia, 16 February 2026] Official maturity data
At the same time, the proportion of debt held by Banca d’Italia declined from 21.6% at end-2024 to 18.5% at end-2025. [Banca d’Italia, 16 February 2026] Official debt-holder data
This decline is economically significant because a smaller central-bank share means a larger proportion of the sovereign financing requirement must ultimately be absorbed by other domestic and international investors as Eurosystem portfolios run down through quantitative-tightening mechanisms. The average maturity of 7.9 years prevents the entire stock from repricing immediately when market rates change, but it also means that higher or lower yields pass gradually into the effective interest bill as existing securities mature and are refinanced.
The September GDP revision changed the denominator materially
ISTAT’s September national-account revision increased 2025 nominal GDP from the €2.258049 trillion estimate published in March to €2.265003 trillion, an upward revision of €6.954 billion. [ISTAT, March 2026 GDP release] Original March estimate [ISTAT, September 2026 revision] Revised September estimate
The revision was not restricted to nominal GDP. Real growth for 2025 increased from 0.5% to 0.6%, while the estimated 2024 real-growth rate increased from 0.8% to 1.1%. [ISTAT, September 2026] Official revision
March–September 2026 revision of the 2025 economic baseline
| Indicator | March 2026 estimate | September 2026 revision | Change | Official sources |
|---|---|---|---|---|
| Nominal GDP | €2,258.049 bn | €2,265.003 bn | +€6.954 bn | [ISTAT March] March release [ISTAT September] September release |
| 2025 real GDP growth | 0.5% | 0.6% | +0.1 pp | [ISTAT] September revision |
| 2024 real GDP growth | 0.8% | 1.1% | +0.3 pp | [ISTAT] September revision |
| 2025 deficit | about €69.4 bn | €69.736 bn | Slight upward revision | [ISTAT April/September] September revision |
| Deficit/GDP | 3.1% | 3.1% | No change at one decimal | [ISTAT] September revision |
| Tax burden | 43.1% April vintage | 42.9% | −0.2 pp | [ISTAT April] April evidence [ISTAT September] September revision |
The methodological explanation supplied by ISTAT is also material. The Institute states that the September exercise incorporated both the normal revision caused by information acquired after March and methodological and source innovations introduced in response to reservations raised by Eurostat concerning gross national income data used for EU own-resource calculations. [ISTAT, Conti economici nazionali – Anni 2010-2025] Official methodological explanation
That statement neither proves nor disproves any allegation of political pressure; it establishes the documented statistical reason for the revision. A political-pressure hypothesis requires a different evidentiary test, addressed later in the dossier through the institutional-consistency chapter.
Eurostat validation: what was actually transmitted to Europe
For the April 2026 Excessive Deficit Procedure notification, Eurostat reported Italian GDP of €2.258049 trillion, net borrowing of €69.381 billion, government expenditure equal to 51.2% of GDP, government revenue of 48.1%, and Maastricht debt of €3.095888 trillion, or 137.1% of GDP. [Eurostat, Provision of deficit and debt data for 2025 – first notification, 22 April 2026] Official Eurostat EDP notification
Italy: April 2026 EDP notification
| Indicator | 2022 | 2023 | 2024 | 2025 | Official source |
|---|---|---|---|---|---|
| GDP at market prices | €1,998.073 bn | €2,142.744 bn | €2,202.031 bn | €2,258.049 bn | [Eurostat] Official EDP table |
| Net borrowing | −€161.869 bn | −€152.867 bn | −€73.779 bn | −€69.381 bn | [Eurostat] Official EDP table |
| Net borrowing / GDP | −8.1% | −7.1% | −3.4% | −3.1% | [Eurostat] Official EDP table |
| Government expenditure / GDP | 54.9% | 53.6% | 50.4% | 51.2% | [Eurostat] Official EDP table |
| Government revenue / GDP | 46.8% | 46.5% | 47.0% | 48.1% | [Eurostat] Official EDP table |
| Maastricht debt | €2,764.481 bn | €2,869.976 bn | €2,967.004 bn | €3,095.888 bn | [Eurostat] Official EDP table |
| Debt / GDP | 138.4% | 133.9% | 134.7% | 137.1% | [Eurostat] Official EDP table |
| Intergovernmental lending | €44.122 bn | €43.037 bn | €41.503 bn | €40.206 bn | [Eurostat] Official EDP table |
Eurostat also explains that under Regulation (EC) No 479/2009 it can express a formal reservation when it has doubts about the quality of national EDP data and can amend reported figures where there is evidence that they fail the requirements of accounting compliance, completeness, reliability, timeliness or consistency. [Eurostat, EDP methodological notes] Official Eurostat EDP release and methodological notes
That mechanism becomes important for the subsequent governance analysis because it provides an observable test: if Eurostat had formally reserved or amended Italy’s transmitted fiscal data, that would constitute an identifiable institutional event requiring examination. The existence or absence of such interventions must be established from the notification record rather than inferred from political statements.
The first quarter of 2026 cannot be read as the annual deficit
ISTAT reported that the general-government deficit in Q1 2026 was 7.8% of quarterly GDP, compared with 8.4% in Q1 2025, while the primary balance was −4.4% of GDP, compared with −4.7% a year earlier, and the current balance was −2.9%, compared with −3.3%. [ISTAT, Conto trimestrale delle Amministrazioni pubbliche – I trimestre 2026, 1 July 2026] Official Q1 2026 release
These quarterly ratios must not be interpreted as forecasts for the annual 2026 deficit because public revenue and expenditure are highly seasonal, tax collections and transfers are distributed unevenly throughout the year, and the first-quarter government balance is structurally much more negative than the annual balance. Their analytical value lies instead in year-on-year comparison with the same quarter.
Q1 fiscal signal
| Indicator | Q1 2025 | Q1 2026 | Direction | Official source |
|---|---|---|---|---|
| Net borrowing / GDP | −8.4% | −7.8% | Improvement of 0.6 pp | [ISTAT] Q1 2026 release |
| Primary balance / GDP | −4.7% | −4.4% | Improvement of 0.3 pp | [ISTAT] Q1 2026 release |
| Current balance / GDP | −3.3% | −2.9% | Improvement of 0.4 pp | [ISTAT] Q1 2026 release |
The first-quarter figures therefore provide an early indication that the year-on-year government balance had improved, but they do not yet establish the full-year 2026 result on which the EDP question ultimately depends.
Net assessment of the Italian fiscal mechanics
The underlying Italian account is considerably more complex than the headline proposition that the deficit “remains above 3%.” The official data establish simultaneously that Italy entered 2026 with a positive primary fiscal position, an annual interest burden close to €87 billion, total government revenue above €1.08 trillion, expenditure above €1.15 trillion, Maastricht debt above €3.09 trillion, a €109.2 billion cash borrowing requirement, Treasury liquidity of €52.4 billion, average debt maturity of 7.9 years, and a declining share of sovereign liabilities held by Banca d’Italia. [ISTAT fiscal accounts] Official ISTAT fiscal evidence [Banca d’Italia debt reconciliation] Official Banca d’Italia release
The fiscal correction is therefore real but incomplete: the state generated more revenue than primary expenditure, yet accumulated additional debt because interest costs, the cash borrowing requirement, Treasury-liquidity accumulation and valuation or issuance effects remained substantial. The September national-account revision improved several dimensions of the recorded macroeconomic baseline—including GDP, growth and the measured tax burden—while slightly increasing the nominal deficit, leaving the published deficit ratio unchanged at 3.1%. [ISTAT, 22 September 2026] Official revised national accounts
The decisive analytical implication is that the political and institutional controversy cannot be resolved by looking at the 3.1% number in isolation. The underlying evidence has to be separated into at least four distinct layers: the ESA deficit, the primary fiscal balance, the cash borrowing requirement and the change in Maastricht debt; only after those layers have been reconciled can the subsequent chapters determine what part of Italy’s fiscal constraint results from current policy, what part derives from inherited sovereign liabilities, what part reflects accounting and statistical revisions, and what part arises from the European fiscal framework itself.
Italy’s 2025 Public Accounts Beneath the 3.1% Deficit
The headline deficit conceals four different fiscal layers: the primary balance, interest expenditure, the cash borrowing requirement and the resulting change in Maastricht debt. Values below preserve the statistical vintage and accounting definition used by the issuing institution.
Core 2025 fiscal position
How a primary surplus became a €69.7 billion deficit
Largest 2025 expenditure blocks
Why debt rose by substantially more than the ESA deficit
| Debt-change component | 2025 value | Accounting meaning |
|---|---|---|
| General-government cash borrowing requirement | €109.2 bn | Cash financing requirement generated during the year. |
| Increase in Treasury liquid assets | €14.7 bn | Additional borrowing retained in Treasury liquidity rather than immediately spent. |
| Discounts, premiums, inflation-linked revaluation and FX effects | €4.6 bn | Financial and valuation effects affecting the debt stock independently of the ESA deficit. |
| Approximate identified debt increase | €128.5 bn | Sum of the principal Banca d’Italia reconciliation components. |
| End-2024 Maastricht debt | €2.967 tn | Opening consolidated general-government debt stock. |
| End-2025 Maastricht debt | €3.096 tn | Harmonised Eurostat April 2026 EDP figure. |
Central government drove the increase in public debt
September 2026 revision of the 2025 baseline
| Indicator | Earlier vintage | September 2026 | Revision |
|---|---|---|---|
| Nominal GDP | €2.258049 tn | €2.265003 tn | +€6.954 bn |
| 2025 real GDP growth | 0.5% | 0.6% | +0.1 pp |
| 2024 real GDP growth | 0.8% | 1.1% | +0.3 pp |
| 2025 deficit | ≈ €69.4 bn | €69.736 bn | Slight upward revision |
| Deficit / GDP | 3.1% | 3.1% | No change at one decimal |
| Tax burden | 43.1% | 42.9% | −0.2 pp |
April 2026 Eurostat EDP statistical baseline
| Indicator | 2022 | 2023 | 2024 | 2025 |
|---|---|---|---|---|
| GDP at market prices | €1.998 tn | €2.143 tn | €2.202 tn | €2.258 tn |
| Net borrowing | −€161.9 bn | −€152.9 bn | −€73.8 bn | −€69.4 bn |
| Net borrowing / GDP | −8.1% | −7.1% | −3.4% | −3.1% |
| Government expenditure / GDP | 54.9% | 53.6% | 50.4% | 51.2% |
| Government revenue / GDP | 46.8% | 46.5% | 47.0% | 48.1% |
| Maastricht debt | €2.764 tn | €2.870 tn | €2.967 tn | €3.096 tn |
| Debt / GDP | 138.4% | 133.9% | 134.7% | 137.1% |
Early 2026 fiscal signal
Institutional reading
Chapter 2 — Statistical Governance, European Fiscal Law and Italy’s Excessive-Deficit Procedure
Principal judgment
Italy’s fiscal surveillance cannot be understood by treating the 3% deficit reference value as a stand-alone rule administered directly by Brussels, because the operative system is a multi-stage institutional architecture in which national authorities first construct the statistical record, Eurostat verifies the quality and methodological conformity of the excessive-deficit data, the European Commission performs the legal and economic assessment required by the Treaties and secondary legislation, and the Council of the European Union takes the principal formal decisions establishing, maintaining, modifying or terminating an excessive-deficit procedure.
The post-2024 framework adds a second layer that is particularly important for Italy: annual growth in nationally financed net expenditure has become the central operational control variable, while debt sustainability, the 3% deficit reference value, the 60% debt reference value, the debt-sustainability safeguard and the deficit-resilience safeguard determine the longer-term fiscal trajectory. Regulation (EU) 2024/1263 defines net expenditure as government expenditure excluding interest expenditure, discretionary revenue measures, expenditure on EU programmes fully matched by EU revenue, national co-financing of EU-funded programmes, cyclical unemployment expenditure and one-off or temporary measures.
For Italy, the Council-endorsed medium-term fiscal-structural plan establishes annual net-expenditure growth of 1.3% in 2025, 1.6% in 2026, 1.9% in 2027, 1.7% in 2028, 1.5% in 2029, 1.1% in 2030 and 1.2% in 2031, corresponding to average growth of 1.5% across the seven-year adjustment period. The plan was built around an extended adjustment horizon because Italy coupled the fiscal path with reforms and investments judged sufficient to justify extending the standard adjustment period.
Italy’s excessive-deficit procedure was formally opened on 26 July 2024, the Council subsequently required correction by 2026, and the Commission’s effective-action assessment of 3 June 2026 resulted in the procedure being held in abeyance rather than stepped up, meaning that the procedure remains open but no escalation was triggered at that assessment point.
The institutional distinction is fundamental: remaining under an EDP is not the same as being found to have failed to take effective action, and neither is equivalent to the imposition of a financial sanction. The Commission describes effective-action assessment as the stage at which an EDP can either be put on hold or intensified depending on compliance with the Council recommendation.
Who actually produces Italy’s fiscal statistics
Four institutional layers must be separated because they perform different functions and possess different legal responsibilities.
Institutional production and validation chain
| Institution | Primary role in Italian fiscal surveillance | What it actually controls | What it does not independently determine | Official record |
|---|---|---|---|---|
| ISTAT | Compiles the national accounts and identifies the institutional units belonging to the Italian general-government sector under ESA rules | GDP, general-government non-financial accounts, deficit, national-account classifications, sector perimeter and revisions | Does not determine whether the Council opens or closes an EDP | Eurostat requires each state to compile EDP statistics under ESA 2010 and publish an EDP inventory describing sources and procedures. |
| Banca d’Italia | Calculates the Maastricht debt and produces detailed public-finance financial statistics under the European statistical framework | Government debt stock, debt instruments, financial accounts, borrowing requirement and related financial data | Does not independently define the national-account deficit or decide EDP legal status | Banca d’Italia states that it calculates Maastricht debt according to European statistical rules and Regulation 479/2009. |
| Ministero dell’Economia e delle Finanze | Constructs the national fiscal strategy, forecasts and medium-term fiscal-structural plan and executes Treasury financing | Budget policy, fiscal measures, net-expenditure commitments, debt-management strategy, national forecasts | Does not have unilateral authority to validate ESA deficit and debt data for European surveillance | Italy’s official 2025–2029 medium-term fiscal-structural plan sets the expenditure path and fiscal projections submitted under the reformed EU framework. |
| Eurostat | Assesses the quality and methodological conformity of EDP statistics transmitted by Member States on behalf of the Commission | ESA methodology, quality checks, consistency, reservations, amendments and publication of harmonised EDP data | Does not prepare Italy’s budget and does not decide the political correction path | Eurostat states that it has sole competence over the methodology underlying EDP statistics and assesses compliance, completeness, reliability, timeliness and consistency. |
| European Commission | Assesses compliance with EU fiscal rules, produces forecasts, reference trajectories and effective-action assessments | Legal-economic assessment, debt-sustainability analysis, recommendations and surveillance | Does not itself adopt the final Council recommendation ending or maintaining an EDP | The Commission maintains the official EDP dossier and effective-action assessments for Italy. |
| Council of the European Union | Adopts the principal formal decisions and recommendations under Article 126 TFEU | Existence of excessive deficit, correction deadline, recommended expenditure path and eventual abrogation | Does not compile the underlying national statistics | Italy’s procedure was opened by Council decision on 26 July 2024 and its corrective recommendation adopted on 21 January 2025. |
This architecture means that ISTAT does not decide whether Italy remains under European fiscal surveillance, just as Eurostat does not decide Italy’s tax rates and the Council does not construct Italy’s GDP series. Each institutional stage can affect the final result, but through a legally differentiated function.
The EDP statistical production cycle
Regulation 479/2009 requires Member States to report EDP information to Eurostat twice each year, at the end of March and at the end of September. Eurostat subsequently publishes the harmonised notification tables in April and October after completing its verification process.
This biannual process is the reason an EDP number should never be presented as though it were an immutable accounting fact established once and forever. Eurostat explicitly states that EDP data are revised when necessary in accordance with national-account principles and that Member States can revise previously transmitted years when updated source information, methodological changes or corrected errors require it.
European EDP statistical cycle
| Stage | Normal timing | Institution primarily responsible | Output | Official basis |
|---|---|---|---|---|
| National compilation | Continuous | ISTAT / Banca d’Italia and other national reporting authorities | ESA government accounts and Maastricht debt | ESA 2010 and national EDP inventory. |
| Spring EDP transmission | By end-March | Member State | EDP notification tables | Regulation 479/2009. |
| Spring verification | Approximately three weeks | Eurostat | Cross-checking, methodological assessment, possible reservations/amendments | Eurostat quality-assurance procedure. |
| Spring publication | April | Eurostat | Harmonised deficit/debt data | EDP notification publication framework. |
| Autumn EDP transmission | By end-September | Member State | Revised notification | Regulation 479/2009. |
| Autumn verification | Approximately three weeks | Eurostat | Updated validation and quality assessment | Eurostat revision and verification policy. |
| Autumn publication | October | Eurostat | Second harmonised EDP vintage | Eurostat EDP notification process. |
Eurostat’s quality controls are substantially more detailed than a simple check of the final deficit ratio. According to Eurostat’s own description, its review covers compliance with ESA accounting rules, completeness of the general-government perimeter, reliability and consistency of the statistical data, sustainability of compilation processes, internal controls, external audit evidence and reconciliation between the deficit and changes in debt.
Eurostat also uses quarterly government accounts as an early-warning mechanism, examines the translation from national working balances into ESA deficit figures, conducts regular EDP dialogue visits and can organise methodological visits when significant questions arise.
Reservations and amendments are the observable test of a statistical dispute
The European system contains formal instruments for dealing with concerns over national data quality. A reservation is issued when Eurostat has doubts about the quality of reported EDP data, whereas Eurostat can amend national figures when evidence demonstrates that submitted data fail requirements concerning accounting compliance, completeness, reliability, timeliness or consistency.
This distinction is institutionally important for evaluating allegations concerning Italy because it creates a documented test rather than requiring speculation.
Formal Eurostat intervention mechanisms
| Mechanism | Trigger | Consequence | Evidentiary significance | Official source |
|---|---|---|---|---|
| Routine validation | Normal spring/autumn transmission | Statistics accepted or questions resolved during verification | Ordinary statistical governance | Eurostat quality assurance. |
| Bilateral methodological advice | Specific transaction or classification issue | Eurostat provides guidance on ESA treatment | Does not itself demonstrate misconduct or political intervention | Eurostat methodology framework. |
| EDP dialogue visit | Periodic or issue-specific review | Compilation systems and source data examined | Enhanced technical scrutiny | Eurostat quality assurance. |
| Formal reservation | Eurostat has doubts about reported-data quality | Reservation published with the EDP notification | Public evidence of unresolved statistical concern | Regulation 479/2009 mechanism described by Eurostat. |
| Eurostat amendment | Evidence demonstrates failure to meet statistical quality requirements | Eurostat substitutes amended actual data and publishes justification | Strongest routine statistical intervention short of misreporting proceedings | Eurostat EDP framework. |
| Investigation of deliberate misreporting | Serious evidence of deliberate misreporting or severe negligence | Can ultimately support sanctions | Exceptional mechanism | Eurostat notes its investigative and sanction-recommendation powers under Regulation 1173/2011. |
For the April 2026 notification, the question therefore is not whether political actors objected to a number but whether Eurostat formally reserved, amended or otherwise qualified Italy’s transmitted data. The distinction will become decisive in the later institutional-consistency chapter because a documented Eurostat intervention would have substantially greater evidentiary value than political disagreement alone.
The legal structure begins with Article 126 and Protocol No. 12
The excessive-deficit architecture ultimately rests on Article 126 of the Treaty on the Functioning of the European Union and Protocol No. 12, while the detailed statistical machinery is implemented through Regulation 479/2009 and the accounting concepts of ESA 2010. Eurostat lists these instruments as the core legal basis for government-finance and EDP statistics.
The familiar 3% deficit and 60% debt ratios are reference values, but the post-2024 framework does not operate as a mechanical system in which crossing either number automatically determines the entire fiscal path. The revised governance architecture combines the Treaty thresholds with country-specific debt-sustainability analysis and expenditure trajectories.
Core legal architecture governing Italy
| Instrument | Function | Material rule for Italy | Official source |
|---|---|---|---|
| Article 126 TFEU + Protocol No. 12 | Treaty-level excessive-deficit framework | 3% government-deficit and 60% government-debt reference values | Eurostat identifies Article 126 and Protocol No. 12 as the Treaty basis of EDP statistics. |
| Regulation (EC) 479/2009 | Statistical reporting and quality framework | National deficit/debt data transmitted twice annually; Eurostat verifies quality | Eurostat legislation and notification framework. |
| Regulation (EU) 549/2013 — ESA 2010 | European national-account system | Defines government sector, transactions, accrual treatment and accounting concepts | Eurostat methodology. |
| Regulation (EU) 2024/1263 | Reformed preventive arm and medium-term surveillance | Net expenditure becomes central operational indicator; country-specific adjustment plans | EUR-Lex regulation text. |
| Regulation (EU) 2024/1264 | Reform of the corrective arm | Revises operation of the EDP | The Council’s 2025 recommendations identify Regulation 2024/1264 as the amendment to Regulation 1467/97. |
| Directive (EU) 2024/1265 | National budgetary-framework requirements | Strengthens domestic medium-term budgetary governance | Identified in the reformed fiscal-governance legal package. |
| Italy’s Council-endorsed medium-term plan | Country-specific fiscal path | Seven-year adjustment with defined annual net-expenditure ceilings | Council Recommendation of 21 January 2025. |
What “net expenditure” actually means
The operational expenditure variable is deliberately narrower than total government expenditure. Regulation 2024/1263 defines net expenditure by removing items that governments either do not directly control in the short term or that the framework intends not to penalise mechanically.
Composition of the EU net-expenditure indicator
| Item | Treatment in net expenditure | Reason in the legal architecture | Official basis |
|---|---|---|---|
| Ordinary government expenditure | Included | Core nationally financed expenditure controlled through the fiscal path | Regulation 2024/1263. |
| Interest expenditure | Excluded | Interest costs are not treated as discretionary expenditure under this indicator | Regulation 2024/1263 Article 2 definition. |
| Discretionary revenue measures | Netted out | Prevents expenditure control being circumvented or distorted by revenue-policy changes | Regulation 2024/1263. |
| EU programme expenditure fully matched by EU revenue | Excluded | Expenditure financed externally by Union resources | Regulation 2024/1263. |
| National co-financing of EU programmes | Excluded | Protects co-financed investment from direct expenditure-path constraint | Regulation 2024/1263. |
| Cyclical unemployment-benefit expenditure | Excluded | Prevents automatic stabilisers from mechanically creating deviations during downturns | Regulation 2024/1263. |
| One-off and temporary measures | Excluded | Path focuses on underlying rather than exceptional expenditure | Regulation 2024/1263. |
Consequently, the statement that Italy must limit expenditure growth to a certain percentage does not mean that total nominal public expenditure may increase by only that amount, because the monitored aggregate is the specifically defined net-expenditure measure.
Italy’s seven-year fiscal path
Italy requested an extended adjustment horizon supported by reforms and investments, producing a seven-year fiscal adjustment running through 2031. The Council’s recommendation states that average annual net-expenditure growth is planned at 1.5% over 2025–2031.
Council-endorsed Italian net-expenditure path
| Year | Annual permitted net-expenditure growth | Cumulative change from 2023 base | Status in plan | Official source |
|---|---|---|---|---|
| 2024 | −1.9% | −1.9% | Pre-adjustment/base transition | Council Recommendation. |
| 2025 | +1.3% | −0.7% | EDP correction year | Council Recommendation. |
| 2026 | +1.6% | +0.9% | Formal EDP correction deadline | Council Recommendation and EDP recommendation. |
| 2027 | +1.9% | +2.8% | Extended adjustment | Council Recommendation. |
| 2028 | +1.7% | +4.6% | Extended adjustment | Council Recommendation. |
| 2029 | +1.5% | +6.2% | End of formal plan period | Council Recommendation. |
| 2030 | +1.1% | +7.4% | Extended adjustment | Council Recommendation. |
| 2031 | +1.2% | +8.7% | End of seven-year adjustment | Council Recommendation. |
| Average 2025–2031 | 1.5% annually | — | Seven-year adjustment average | Council Recommendation. |
The difference between the EDP correction deadline of 2026 and the fiscal-adjustment horizon to 2031 is therefore not contradictory. The first refers to bringing the excessive deficit below the Treaty threshold on a durable basis; the second refers to the broader debt-sustainability adjustment encoded in Italy’s medium-term expenditure trajectory.
The original debt path behind Italy’s plan
Italy’s 2024 medium-term fiscal-structural plan did not assume that debt would immediately decline when the deficit returned below 3%. Instead, the MEF plan projected debt increasing from 135.8% of GDP in 2024 to 136.9% in 2025 and 137.8% in 2026, before declining to 137.5% in 2027, 136.4% in 2028 and 134.9% in 2029.
Fiscal path originally embedded in Italy’s medium-term plan
| Indicator | 2024 | 2025 | 2026 | 2027 | 2028 | 2029 | Official source |
|---|---|---|---|---|---|---|---|
| Net borrowing / GDP | −3.8% | −3.3% | −2.8% | −2.6% | −2.3% | −1.8% | MEF Medium-Term Fiscal-Structural Plan. |
| Primary balance / GDP | +0.1% | +0.6% | +1.1% | +1.5% | +1.9% | +2.4% | MEF plan. |
| Interest expenditure / GDP | 3.9% | 3.9% | 3.9% | 4.1% | 4.2% | 4.2% | MEF plan. |
| Gross debt / GDP | 135.8% | 136.9% | 137.8% | 137.5% | 136.4% | 134.9% | MEF plan. |
| Stock-flow adjustment contribution | 1.0 pp | 2.2 pp | 2.2 pp | 0.6 pp | 0.4 pp | 0.2 pp | MEF plan. |
These are planning assumptions from the 2024 plan rather than the latest statistical outturns. They matter because they demonstrate that the original approved trajectory already envisaged debt increasing temporarily while Italy corrected the headline deficit, principally because debt dynamics depend on interest expenditure, nominal growth and stock-flow adjustments rather than solely on the current-year deficit.
The debt-sustainability safeguard
The reformed fiscal framework contains an explicit debt-sustainability safeguard. Article 7 of Regulation 2024/1263 requires the reference trajectory to ensure an average annual decline in the projected debt ratio of at least 1 percentage point of GDP when debt exceeds 90% of GDP, and 0.5 percentage points when debt lies between 60% and 90%.
For states already subject to an excessive-deficit procedure, however, the calculation of this average decline begins from the later of the year preceding the start of the reference trajectory or the year in which the EDP is projected to be abrogated.
This provision explains why the legal framework does not require Italy’s debt ratio to fall by one percentage point immediately in 2025 or 2026 merely because Italy’s debt exceeds 90% of GDP. The sequencing of the EDP and the subsequent debt-sustainability path is written into the regulation itself.
The deficit-resilience safeguard
Article 8 of Regulation 2024/1263 adds a second safety mechanism requiring continued adjustment, where necessary, until a member state establishes a structural fiscal margin of 1.5% of GDP below the 3% deficit reference value. The required annual structural-primary-balance improvement is normally 0.4 percentage points of GDP, reduced to 0.25 percentage points where the adjustment period has been extended.
This means that 3% is not the eventual medium-term destination of the preventive framework. Crossing below 3% addresses the immediate excessive-deficit criterion, whereas the resilience safeguard is designed to create sufficient structural distance from that threshold so that ordinary economic fluctuations do not immediately push the country back into excessive deficit.
Italy’s excessive-deficit procedure: documentary chronology
The current EDP is not an informal surveillance arrangement; its principal steps are publicly documented by the Commission.
Italy’s EDP timeline
| Date | Institutional act | Legal/procedural consequence | Official source |
|---|---|---|---|
| 19 June 2024 | Commission fiscal assessment preceding the Article 126 process | Italy’s fiscal position assessed against Treaty criteria | Commission EDP dossier. |
| 8 July 2024 | Commission proposal for Council decision on existence of excessive deficit | Formal proposal to open EDP | Commission Italy EDP record. |
| 26 July 2024 | Council decision under Article 126(6) | EDP formally opened | Commission and Council records. |
| 26 November 2024 | Commission recommendation for corrective Council recommendation | Proposed adjustment path | Commission EDP dossier. |
| 21 January 2025 | Council recommendation under Article 126(7) | Italy required to end excessive deficit by 2026; net-expenditure ceilings 1.3% in 2025 and 1.6% in 2026 | Council EDP record. |
| 30 April 2025 | Italy’s first Annual Progress Report under new framework | Reports action taken and implementation of medium-term plan | Commission dossier. |
| 16 November 2025 | Italy reports action through Draft Budgetary Plan | Updated implementation information | Commission dossier. |
| 30 April 2026 | Italy submits 2026 Annual Progress Report | Formal report on compliance with net-expenditure path and reforms | Commission 2026 assessment. |
| 3 June 2026 | Commission effective-action assessment | EDP held in abeyance, not stepped up | Commission assessment. |
| 22 September 2026 | ISTAT revises 2025 national accounts | Updated national statistical baseline; does not itself close or escalate EDP | The legal procedure continues through Commission/Council decisions rather than an ISTAT release |
The procedural significance of “held in abeyance” is specific: the EDP remains legally open, but enforcement is not escalated because the Commission has concluded that effective action has been taken at the relevant assessment stage. The Commission’s general EDP guidance explicitly describes the effective-action test as determining whether a procedure is put on hold or stepped up.
What the June 2026 Commission assessment actually recorded
The Commission’s June 2026 assessment used the April Eurostat vintage, under which Italy’s deficit fell from 3.4% of GDP in 2024 to 3.1% in 2025, while the Commission Spring Forecast projected 2.9% in 2026 and 2.9% in 2027. The Commission also stated that the expected 2026 reduction reflected, among other factors, lower expenditure associated with housing-renovation tax credits, while public investment and tax revenues were expected to continue increasing.
The Commission further recorded that Italy had submitted its 2026 Annual Progress Report on 30 April 2026, covering adherence to the recommended maximum net-expenditure growth rates and implementation of the reforms and investments underpinning the extended adjustment period.
This is the operative evidence behind the decision not to escalate the procedure at that stage; it is not equivalent to an EDP closure because the Commission and Council still need to establish that the excessive deficit has actually been corrected in a durable manner.
What is required to close an excessive-deficit procedure
The Malta decision of 12 June 2026 provides a recent official example of the legal logic used to terminate a deficit-based EDP. The Council stated that Malta’s procedure was abrogated because the government deficit had been successfully and durably reduced below 3% of GDP.
The key word is therefore not merely “below” but durably.
Conditions relevant to EDP closure
| Requirement | Analytical meaning | Why it matters for Italy | Official support |
|---|---|---|---|
| Actual deficit corrected below 3% | Recorded deficit no longer exceeds Treaty reference value | A rounded 3.1% 2025 result does not satisfy this condition | Council EDP framework. |
| Correction considered durable | Forecasts must indicate that the breach will not immediately reappear | 2026 and subsequent fiscal trajectory therefore matter | Malta closure decision explicitly refers to successful and durable correction. |
| Effective action consistent with Council recommendation | Member State must follow the expenditure path and corrective measures | Italy’s June 2026 procedure was held in abeyance after effective-action assessment | Commission assessment. |
| Council decision required | Statistical publication alone does not terminate procedure | ISTAT or Eurostat data can establish the factual basis but cannot independently close Italy’s EDP | Commission Italy EDP dossier documents Article 126 Council steps. |
The legal consequence is that Italy cannot exit the EDP merely because a later statistical revision moves an underlying decimal fraction marginally below a threshold unless the Commission and Council determine that the correction satisfies the applicable legal and durability tests.
Defence flexibility: what the national escape clause actually does
The 2024 reform created a national escape clause under Article 26 of Regulation 2024/1263, allowing a Member State experiencing exceptional circumstances outside its control with a major impact on public finances to temporarily deviate from the Council-endorsed fiscal path, provided that medium-term fiscal sustainability is not endangered.
Following the change in the European security environment, Member States were invited to activate this mechanism for higher defence expenditure. The Council’s official record lists 18 states for which the defence national escape clause had been activated by 12 June 2026: Belgium, Bulgaria, Czechia, Croatia, Denmark, Estonia, Finland, Greece, Latvia, Lithuania, Poland, Portugal, Slovakia, Slovenia, Hungary, Germany, Austria and Spain. Italy is not on that list.
Defence national escape clause status as of 12 June 2026
| Issue | Verified position | Fiscal consequence | Official source |
|---|---|---|---|
| Legal basis | Article 26, Regulation 2024/1263 | Permits temporary deviation from Council fiscal path under exceptional circumstances | Commission escape-clause framework. |
| Number of states activated | 18 | Flexibility granted to those states within Council-defined limits | Council NEC record. |
| Italy activated? | No, according to the Council list current to 12 June 2026 | Italy cannot be assumed to benefit from the defence NEC merely because it is increasing defence expenditure | Council list. |
| Can Italy request later? | Commission documentation states Member States may still request activation until 2028 if Article 26 criteria are fulfilled | Potential future flexibility remains legally possible | Commission June 2026 Italy assessment. |
This corrects an important source of confusion: defence expenditure is not automatically excluded from Italy’s deficit or debt simply because the EU permits fiscal flexibility for defence. The national escape clause concerns deviation from the fiscal trajectory; it does not repeal ESA accounting.
Energy-security flexibility is an extension of fiscal-rule flexibility, not an accounting exemption
On 17 August 2026, the European Commission issued guidance concerning the possible extension of the national escape clause to energy-security measures, following the proposal announced in the June 2026 European Semester Spring Package. The guidance sets out the procedure through which Member States can request such flexibility, its treatment under EU fiscal surveillance and the monitoring of its use.
The mechanism therefore operates inside the fiscal-governance framework rather than outside national accounts. Expenditure qualifying for flexibility can receive different treatment when assessing compliance with a Council expenditure path, but that does not automatically eliminate the underlying expenditure from the ESA deficit or the associated financing from the debt stock.
Three accounting layers that must not be confused
| Mechanism | What changes | What does not automatically disappear | Official basis |
|---|---|---|---|
| Defence NEC | Permitted deviation from fiscal path for qualifying defence expenditure | ESA expenditure, headline deficit and debt accounting | Commission/Council NEC framework. |
| Energy-security extension | Potential fiscal-path flexibility for qualifying energy-security measures | National-account recording of expenditure and financing | Commission August 2026 guidance. |
| SAFE | Provides EU loans for defence investment | Borrower’s repayment obligation and underlying expenditure | SAFE Regulation 2025/1106. |
SAFE is borrowing, not deficit forgiveness
The Security Action for Europe — SAFE instrument was established by Council Regulation (EU) 2025/1106 and provides up to €150 billion in EU financial assistance in the form of loans for defence-related investment and procurement. The regulation is explicit that financial assistance takes the form of a loan granted by the Union to the Member State concerned.
SAFE is financed through the EU’s borrowing capacity, with the Union raising funds through EU bonds and on-lending them to participating Member States.
Italy’s maximum SAFE loan allocation approved in the February 2026 Council process is €14.9 billion, not €36 billion.
SAFE architecture relevant to Italy
| Variable | Verified value/status | Meaning | Official source |
|---|---|---|---|
| Total SAFE capacity | Up to €150 bn | EU-wide lending envelope | Council Regulation 2025/1106. |
| Instrument type | Loan | Repayable financial assistance, not a grant | Regulation Article 5. |
| EU funding mechanism | EU bond issuance | Union borrows, then lends to Member States | Council SAFE explanation. |
| Italy maximum approved loan | €14.9 bn | Maximum financing authorised for Italy under the relevant Council wave | Council February 2026 allocation. |
| €36 bn for Italy supported by the official SAFE allocation? | No | The official Council figure retrieved for Italy is €14.9 bn | Council allocation table. |
| Primary purpose | Defence industrial investment and common procurement | Supports defence capability financing | SAFE Regulation and Council explanation. |
The fiscal impact of SAFE therefore has to be decomposed into at least three questions: when the loan is disbursed, when eligible defence expenditure is recognised under ESA rules, and how the corresponding liability is treated in government debt statistics. It is analytically incorrect to treat the €14.9 billion facility as though it were €14.9 billion of fiscal space that disappears from deficit and debt accounting.
Why the 2025 deficit does not mechanically decide the 2026 procedure
The Council recommendation requires Italy to end its excessive deficit by 2026 and limits net-expenditure growth to 1.3% in 2025 and 1.6% in 2026.
The Commission’s June 2026 assessment subsequently concluded that effective action had been taken and held the procedure in abeyance.
Therefore, the analytical sequence is:
| Question | 2025/2026 status | Institutional significance | Source |
|---|---|---|---|
| Was Italy below 3% in the April 2026 statistical vintage for 2025? | No — 3.1% | Prevented closure based on that statistical outcome | Commission June assessment using Eurostat data. |
| Had Italy complied sufficiently with the corrective recommendation to avoid escalation? | Yes at the June effective-action assessment | EDP held in abeyance | Commission. |
| Is the legal correction deadline 2025? | No | Council recommendation sets 2026 | Council. |
| Was the EDP closed in June 2026? | No | Italy remained under an active procedure | Commission Italy EDP dossier. |
| Can a national statistical revision itself terminate the EDP? | No | Council action is required | Article 126 procedural record documented by Commission. |
| What would support eventual closure? | Deficit sustainably below 3% together with compliance with the corrective framework | Durability is material, not only a single observation | Council Malta closure precedent. |
This establishes a far more precise institutional description than the proposition that Italy either “passed” or “failed” a single 3% test in September 2026. The 2025 outcome matters, but it sits within a procedure whose formal correction deadline is 2026 and whose enforcement mechanism evaluates both actual fiscal results and adherence to the Council-directed expenditure trajectory.
What the 2026 statistical revision can change — and what it cannot
The September 2026 revision can materially change the historical and statistical inputs used in later surveillance because Eurostat’s EDP framework explicitly allows revisions as new source data or methodological information becomes available.
It cannot retrospectively erase the fact that the Council’s earlier decisions were taken on the statistical vintages available at the time, nor can an ISTAT revision itself repeal a Council decision.
The institutional sequence therefore requires four separate dates whenever a politically sensitive fiscal number is discussed:
Mandatory vintage control for government-level analysis
| Date type | Example | Why it must be stated |
|---|---|---|
| Economic reference year | 2025 | Identifies the fiscal period being measured |
| National publication date | 22 September 2026 | Identifies the ISTAT statistical vintage |
| Eurostat EDP validation/publication date | April or October notification | Identifies the harmonised European statistical vintage |
| Commission/Council decision date | e.g. 3 June 2026 effective-action assessment | Identifies the information legally available when the institutional decision was made |
Failure to separate these dates can create the false impression that a later statistical revision proves that an earlier institutional decision was incorrect when, in reality, the two actions may simply have been based on different vintages.
The real institutional pressure points for Italy
The legally consequential variables over the remainder of 2026 are therefore identifiable and measurable rather than rhetorical.
The first is the full-year 2026 deficit, because the Council correction deadline is 2026.
The second is net-expenditure compliance, because the Council requires Italian net expenditure to remain within the 1.6% growth ceiling for 2026.
The third is the October 2026 Eurostat EDP notification, because the autumn notification is the formal European statistical channel through which revised national data enter the harmonised EDP record.
The fourth is the next Commission effective-action and forecast assessment, because durability cannot be established from historical data alone.
The fifth is the debt-sustainability trajectory, particularly once the EDP is expected to be abrogated and the debt-sustainability safeguard becomes fully operative over the remaining adjustment horizon.
The sixth is any Italian decision to request the national escape clause, because Italy had not activated the defence clause as of the Council’s 12 June 2026 list, despite its access to SAFE financing.
Documentary distinction between surveillance, flexibility and financing
The institutional picture can be condensed into a single governance matrix.
| Instrument | Governing institution | Italy status as of 23 Sep 2026 | Fiscal purpose | Does it change headline ESA accounting automatically? | Official evidence |
|---|---|---|---|---|---|
| Treaty 3% deficit criterion | EU Treaties / Council procedure | Italy remained at 3.1% for 2025 in the latest national release | Identifies excessive-deficit condition | No; it is a criterion applied to the accounts | EU EDP legal framework. |
| 60% debt reference value | EU Treaties | Italy materially exceeds it | Debt-surveillance anchor | No | EU legal framework. |
| Net-expenditure path | Council-endorsed Italian plan | 1.3% 2025; 1.6% 2026; seven-year path to 2031 | Operational fiscal control | No; it is a surveillance variable | Council Recommendation. |
| EDP | Council / Commission | Open; held in abeyance after effective-action assessment | Correct excessive deficit | No; responds to statistical and forecast evidence | Commission Italy dossier. |
| Defence NEC | Council following request and Commission recommendation | Not activated for Italy as of 12 June 2026 | Temporary flexibility from expenditure path | No | Council NEC list. |
| Energy-security extension | Commission guidance / possible national request | Potential flexibility mechanism from Aug 2026 | Extend fiscal-path flexibility to qualifying energy-security measures | No | Commission guidance. |
| SAFE | EU borrowing and national loans | Italy allocation up to €14.9 bn | Defence investment financing | No | Council SAFE allocation and Regulation 2025/1106. |
Key judgments
Italy’s present fiscal surveillance is governed by two simultaneous but distinct systems: the corrective EDP, whose immediate objective is durable correction of the excessive deficit by 2026, and the longer medium-term expenditure/debt framework extending through 2031. Treating either system in isolation gives an incomplete account of Italy’s actual obligations.
The formal statistical record is produced nationally but is not simply accepted without review. Eurostat possesses explicit methodological authority, conducts biannual verification, can issue reservations, can amend figures and can investigate serious reporting failures.
The September 2026 ISTAT revision is therefore one stage of the statistical process rather than the final legal decision on Italy’s EDP. The revised national data must enter the relevant European statistical and surveillance cycles before their procedural implications are fully determined.
The Council did not require Italy to eliminate the excessive deficit by 2025; its formal correction deadline is 2026, while the net-expenditure path continues through 2031.
The Commission’s 3 June 2026 assessment did not escalate Italy’s procedure; it recorded effective action and held the EDP in abeyance.
Defence-related flexibility, energy-security flexibility and SAFE financing are three legally and economically different mechanisms. None should be described as automatically removing the corresponding expenditure from the headline deficit or debt.
Italy’s approved SAFE amount is €14.9 billion, while the broader SAFE instrument has an EU-wide ceiling of €150 billion in loans.
Italy had not activated the defence national escape clause according to the Council’s official list current to 12 June 2026, even though the regulatory framework leaves open the possibility of later activation subject to Article 26 conditions.
What would change the assessment
A formal Eurostat reservation or amendment concerning Italy’s revised EDP data would materially change the assessment of the statistical-governance question because it would constitute documented evidence of unresolved methodological disagreement rather than ordinary revision.
A Commission conclusion that Italy had not taken effective action would represent a materially different procedural state from the June 2026 position and could trigger escalation of the EDP.
A verified 2026 deficit sustainably below 3%, combined with compliant expenditure growth and forecasts showing the correction remains durable, would create the documentary basis for eventual abrogation of the procedure, subject to formal Commission and Council action.
An Italian request and Council activation of the national escape clause would change the relevant expenditure-compliance calculation but would not by itself change the ESA accounting treatment of deficit and debt.
A revision of Italy’s medium-term fiscal-structural plan, a material change in the agreed reform/investment package supporting the seven-year adjustment period, or a deterioration in debt sustainability sufficient to invalidate the assumptions underpinning the Council-endorsed path would require re-examination of the longer-term fiscal trajectory.
Open official record
The most important outstanding official records are the October 2026 Eurostat EDP notification incorporating the latest national-account revisions, the next Commission fiscal forecast based on the revised statistical baseline, the full-year 2026 fiscal outturn, any Italian request concerning the defence or energy-security escape clause, and any subsequent Commission effective-action assessment or Council decision concerning termination or continuation of the EDP.
The critical institutional test remains documentary rather than rhetorical: whether the statistical methodology, verification standards, expenditure-control rules, flexibility provisions and requirements for durable correction applied to Italy can be shown through official records to differ materially from the rules established by EU law or from their documented implementation. That question cannot be resolved by the 3.1% headline alone.
How Italy’s Fiscal Surveillance Actually Works
Italy’s fiscal position is produced, validated and governed through several distinct institutional layers. National statistical authorities construct the accounts, Eurostat verifies EDP quality and methodology, the European Commission performs the legal-economic assessment, and the Council adopts the principal formal decisions. The 3% deficit threshold is therefore only one element inside a broader system based increasingly on net expenditure, debt sustainability and country-specific adjustment paths.
Institutional chain of responsibility
Core legal architecture
What the EU actually monitors: net expenditure
| Fiscal item | Treatment | Institutional meaning |
|---|---|---|
| Ordinary nationally financed government expenditure | Included | Core expenditure subject to the country-specific path. |
| Interest expenditure | Excluded | Debt-service costs are excluded from the net-expenditure indicator. |
| Discretionary revenue measures | Netted out | Prevents expenditure-path interpretation being distorted by tax-policy changes. |
| EU programme expenditure fully matched by EU revenue | Excluded | EU-financed programme expenditure does not mechanically consume national fiscal space. |
| National co-financing of EU programmes | Excluded | Protects qualifying co-financed investment from direct expenditure-path restriction. |
| Cyclical unemployment expenditure | Excluded | Allows automatic stabilisers to operate during cyclical weakness. |
| One-off and temporary measures | Excluded | The indicator focuses on underlying expenditure dynamics. |
Italy’s Council-endorsed net-expenditure path
Bar length visualises annual permitted growth only and is not a risk score. The Council-endorsed average for 2025–2031 is approximately 1.5% per year.
Italy’s excessive-deficit procedure: documentary timeline
EDP status must not be confused with sanctions
Debt-sustainability and deficit-resilience safeguards
Defence, energy and SAFE: three different mechanisms
| Instrument | Italy status | What it changes | What it does not automatically remove |
|---|---|---|---|
| Defence national escape clause | Not activated for Italy on the Council list current to 12 Jun 2026 | Can permit temporary deviation from the expenditure path for qualifying defence spending. | ESA expenditure, headline deficit and debt accounting. |
| Energy-security flexibility | Guidance issued Aug 2026 | Provides a route for qualifying energy-security measures to receive fiscal-path flexibility. | National-account expenditure and financing entries. |
| SAFE | Italy allocation up to €14.9 bn | Provides EU-backed loans for eligible defence investment and procurement. | Repayment obligations and the underlying ESA treatment of expenditure. |
SAFE financing architecture
What is required for eventual EDP closure
Italy’s immediate institutional watchpoints
| Watchpoint | Why it matters | Current position |
|---|---|---|
| 2026 full-year deficit | The Council’s correction deadline is 2026. | Not yet final |
| 2026 net-expenditure growth | Italy’s Council ceiling is 1.6%. | Requires full-year assessment |
| Autumn 2026 Eurostat EDP notification | Integrates revised national fiscal data into the harmonised European record. | Pending |
| Next Commission effective-action assessment | Determines whether the EDP remains in abeyance, is intensified or moves toward closure. | Pending |
| Defence / energy escape clause decision | Would alter the fiscal-path compliance calculation for qualifying expenditure. | Italy defence NEC not activated on 12 Jun 2026 list |
| Debt-sustainability path | Becomes increasingly important after deficit correction and through the 2031 adjustment horizon. | Ongoing surveillance |
Institutional reading
Chapter 3 — European Sovereign Fiscal Files
Principal judgment
The European fiscal landscape in 2025–2027 is not governed by a single sovereign-finance pattern, because the same headline deficit can emerge from markedly different combinations of revenue capacity, expenditure commitments, debt stocks, interest exposure, defence programmes, social expenditure, economic growth and institutional adjustment requirements; consequently, each state must be reconstructed as an independent fiscal system rather than treated as evidence for or against the policy choices of another government.
The common statistical base used in this chapter is Eurostat’s 22 April 2026 first EDP notification for 2025, which applies ESA 2010 definitions to general-government revenue, expenditure, deficit and Maastricht debt and for which Eurostat explicitly reported no reservations and no amendments to the data supplied by Member States. Eurostat — Provision of deficit and debt data for 2025, first notification, 22 April 2026
Forward-looking numbers are kept strictly separate from those historical outturns and use the European Commission’s 21 May 2026 Spring Forecast, while EDP status and expenditure paths use Council decisions current to 10 July 2026. European Commission — Economic forecasts Council of the European Union — Excessive deficit procedure
France — large structural expenditure commitments and continuing primary imbalance
France entered 2026 with 2025 GDP of €2.994733 trillion, government expenditure equal to 57.2% of GDP, revenue equal to 52.1%, a deficit of €152.511 billion or 5.1% of GDP, and Maastricht debt of €3.460465 trillion or 115.6% of GDP. The significance of the French account lies not simply in the 5.1% deficit but in the coexistence of a very large public sector, revenue above half of GDP and an expenditure ratio still more than five percentage points above revenue. Eurostat — France 2025 general-government account
France — verified fiscal and macroeconomic record
| Indicator | 2025 actual | 2026 forecast | 2027 forecast | Official source |
|---|---|---|---|---|
| Real GDP growth | 0.8% | 0.8% | 1.1% | European Commission — France forecast, 21 May 2026 |
| Inflation | 0.9% | 2.4% | 1.8% | European Commission — France forecast |
| Unemployment | 7.7% | 8.3% | 8.7% | European Commission — France forecast |
| Government balance | −5.1% GDP | −5.1% | −5.7% | European Commission — France forecast |
| Gross debt | 115.6% GDP | 118.1% | 120.2% | European Commission — France forecast |
| Government expenditure | 57.2% GDP | — | — | Eurostat — 2025 EDP notification |
| Government revenue | 52.1% GDP | — | — | Eurostat — 2025 EDP notification |
| Nominal 2025 deficit | €152.511 bn | — | — | Eurostat — France fiscal data |
| Nominal debt | €3.460465 tn | — | — | Eurostat — France fiscal data |
The Commission identifies the continuing primary deficit as the principal force driving the French debt ratio upward and projects debt exceeding 120% of GDP by 2027 under unchanged policies. It also identifies higher defence activity and aeronautics as supportive of investment and exports, but these effects are insufficient in the current forecast to offset the underlying fiscal imbalance. European Commission — Economic forecast for France
France has been under an EDP since 26 July 2024; the Council requires correction by 2029 and caps nominal net-expenditure growth at 0.8% in 2025, 1.2% annually in 2026–2028 and 1.1% in 2029. Council — France EDP
The French fiscal file therefore combines high taxation and revenue mobilisation with still higher expenditure, a persistent primary imbalance and a debt ratio that the Commission expects to increase rather than stabilise during the immediate forecast horizon.
Germany — fiscal expansion after constitutional reform
Germany’s 2025 general-government account recorded GDP of €4.469910 trillion, expenditure of 50.5% of GDP, revenue of 47.9%, a deficit of €119.147 billion or 2.7% of GDP, and gross debt of €2.838239 trillion or 63.5% of GDP. Eurostat — Germany 2025 government-finance data
The important development is forward-looking rather than contained in the 2025 deficit itself. The Commission expects the implementation of Germany’s 2025 constitutional fiscal-framework reform, higher defence expenditure, increased public investment and tax-relief measures to raise the general-government deficit to 3.7% in 2026 and 4.1% in 2027. European Commission — Economic forecast for Germany
Germany — fiscal expansion profile
| Indicator | 2025 actual | 2026 forecast | 2027 forecast | Official source |
|---|---|---|---|---|
| GDP growth | 0.2% | 0.6% | 0.9% | European Commission — Germany forecast |
| Government balance | −2.7% | −3.7% | −4.1% | European Commission — Germany forecast |
| Government expenditure | 50.5% GDP | — | — | Eurostat — Germany fiscal account |
| Government revenue | 47.9% GDP | — | — | Eurostat — Germany fiscal account |
| Debt | €2.838239 tn / 63.5% GDP | Rising | Rising further | Eurostat European Commission — Germany |
Germany is not currently subject to a deficit-based EDP. Its immediate fiscal issue is instead the transition from a highly restrictive domestic borrowing architecture toward a more expansionary fiscal regime concentrated on infrastructure and defence while underlying economic growth remains weak. Council — Current EDP cases European Commission — Germany forecast
Spain — strong nominal revenue base and continuing debt reduction
Spain recorded €1.687152 trillion of GDP in 2025, expenditure of 45.3% of GDP, revenue of 42.9%, a deficit of €40.330 billion or 2.4% of GDP, and debt of €1.698225 trillion or 100.7% of GDP. Eurostat — Spain 2025 fiscal account
The debt ratio has moved from 109.3% in 2022 to 105.2% in 2023, 101.6% in 2024 and 100.7% in 2025, even though the nominal debt stock remained very large, illustrating the importance of nominal-GDP growth in debt-ratio dynamics. Eurostat — Spain debt series
Spain — fiscal and economic path
| Indicator | 2025 | 2026 forecast | 2027 forecast | Official source |
|---|---|---|---|---|
| GDP growth | 2.8% | 2.4% | 1.9% | European Commission — Spain forecast |
| Inflation | 2.7% | 3.0% | 2.5% | European Commission — Spain forecast |
| Unemployment | 10.5% | 9.9% | 9.6% | European Commission — Spain forecast |
| Deficit | 2.4% GDP | 2.4% | 2.0% | European Commission — Spain forecast |
| Debt | 100.7% GDP | 99.6% | 98.9% | European Commission — Spain forecast |
| Revenue | 42.9% GDP | — | — | Eurostat — Spain fiscal account |
| Expenditure | 45.3% GDP | — | — | Eurostat — Spain fiscal account |
The Commission identifies domestic demand, employment, inward migration and investment as the main engines supporting the Spanish fiscal denominator, while the current-account balance remains positive. European Commission — Spain forecast
Spain is not currently in an EDP and remains under the preventive architecture of the reformed Stability and Growth Pact. Council — EDP status
Austria — persistent expenditure gap and rising debt
Austria recorded €512.813 billion of GDP, expenditure of 55.2% of GDP, revenue of 51.0%, a deficit of €21.464 billion or 4.2% of GDP, and debt of €418.078 billion or 81.5% of GDP in 2025. Eurostat — Austria fiscal account
Austria — current fiscal trajectory
| Indicator | 2025 | 2026 forecast | 2027 forecast | Official source |
|---|---|---|---|---|
| GDP growth | 0.6% | 0.6% | 0.9% | European Commission — Austria forecast |
| Inflation | 3.6% | 3.0% | 2.5% | European Commission — Austria forecast |
| Deficit | 4.2% | 4.1% | 4.1% | European Commission — Austria forecast |
| Debt | 81.5% | 83.4% | 84.9% | European Commission — Austria forecast |
| Revenue | 51.0% GDP | — | — | Eurostat — Austria account |
| Expenditure | 55.2% GDP | — | — | Eurostat — Austria account |
Austria entered an EDP on 8 July 2025 and must correct it by 2028, with net-expenditure growth limited to 2.6% in 2025, 2.2% in 2026, 2.2% in 2027 and 2.0% in 2028. Council — Austria EDP
The fiscal challenge is therefore one of simultaneously narrowing a persistent revenue-expenditure gap and arresting a debt ratio that the Commission expects to continue rising through 2027.
Sweden — low sovereign leverage but deliberate fiscal expansion
Sweden recorded SEK 6.570039 trillion of GDP, expenditure of 49.9% of GDP, revenue of 48.6%, a deficit of SEK 84.717 billion or 1.3% of GDP, and government debt of SEK 2.305401 trillion or 35.1% of GDP. Eurostat — Sweden fiscal account
Sweden — fiscal expansion from a low debt base
| Indicator | 2025 | 2026 forecast | 2027 forecast | Official source |
|---|---|---|---|---|
| GDP growth | 1.5% | 1.8% | 2.2% | European Commission — Sweden |
| Inflation | 2.6% | 1.5% | 1.8% | European Commission — Sweden |
| Unemployment | 8.8% | 8.5% | 7.9% | European Commission — Sweden |
| Deficit | 1.3% | 2.8% | 2.5% | European Commission — Sweden |
| Debt | 35.1% | 36.6% | 37.7% | European Commission — Sweden |
The Commission attributes the expected widening of the deficit principally to tax reductions and increased public expenditure, particularly defence expenditure, rather than to a pre-existing EDP correction problem. European Commission — Sweden forecast
Sweden is not subject to an EDP. Council — Current EDP cases
Poland — defence, investment and rapid debt accumulation
Poland recorded PLN 3.912673 trillion of GDP, expenditure of 50.9% of GDP, revenue of 43.6%, a deficit of PLN 283.969 billion or 7.3% of GDP, and debt of PLN 2.335153 trillion or 59.7% of GDP. Eurostat — Poland fiscal account
The debt ratio increased from 48.8% in 2022 to 49.5% in 2023, 54.8% in 2024 and 59.7% in 2025, while the expenditure ratio rose from 43.2% to 50.9% over the same interval. Eurostat — Poland 2022–2025 fiscal series
Poland — fiscal expansion and correction path
| Indicator | 2025 | 2026 forecast | 2027 forecast | Official source |
|---|---|---|---|---|
| Growth | 3.6% | 3.5% | 2.8% | European Commission — Poland |
| Inflation | 3.3% | 3.6% | 2.9% | European Commission — Poland |
| Deficit | 7.3% | 6.5% | 6.3% | European Commission — Poland |
| Debt | 59.7% | 64.5% | 68.3% | European Commission — Poland |
The Commission identifies military-equipment deliveries, public-sector wages, social benefits and EU-supported investment as important components of the current fiscal and macroeconomic configuration. European Commission — Poland forecast
Poland must end its EDP by 2028, with net-expenditure growth limits of 6.3% in 2025, 4.4% in 2026, 4.0% in 2027 and 3.5% in 2028. Council — Poland EDP
Romania — the deepest revenue constraint among the examined sovereign files
Romania’s fiscal structure is distinguished by the scale of the gap between expenditure and revenue. In 2025 expenditure reached 43.3% of GDP while government revenue amounted to only 35.4%, producing a deficit of RON 151.063 billion or 7.9% of GDP. Debt reached RON 1.137324 trillion or 59.3% of GDP. Eurostat — Romania fiscal account
Romania — fiscal and macroeconomic path
| Indicator | 2025 | 2026 forecast | 2027 forecast | Official source |
|---|---|---|---|---|
| GDP growth | 0.7% | 0.1% | 2.3% | European Commission — Romania |
| Inflation | 6.8% | 7.0% | Lower thereafter | European Commission — Romania |
| Deficit | 7.9% | 6.2% | 5.8% | European Commission — Romania |
| Debt | 59.3% | 61.6% | about 63.3% | European Commission — Romania |
| Current-account deficit | 7.9% GDP | Declining | about 6.4% by horizon | European Commission — Romania |
Romania has been under an EDP since 3 April 2020; the Council formally concluded again in June 2025 that effective action had not been taken and revised the path in July 2025, requiring correction by 2030 and limiting nominal net-expenditure growth to 2.8% in 2025, 2.6% in 2026, 4.6% in 2027, 4.4% in 2028, 4.2% in 2029 and 4.0% in 2030. Council — Romania EDP
The Romanian fiscal problem is therefore not solely one of expenditure control; the official accounts expose a comparatively narrow revenue base relative to the size of government commitments, while inflation and fiscal consolidation simultaneously constrain household demand.
Belgium — high expenditure, high debt and an extended correction timetable
Belgium recorded €642.015 billion of GDP, expenditure of 54.2% of GDP, revenue of 49.0%, a deficit of €33.220 billion or 5.2% of GDP, and public debt of €692.461 billion or 107.9% of GDP. Eurostat — Belgium fiscal account
Belgium — fiscal outlook
| Indicator | 2025 | 2026 | 2027 | Official source |
|---|---|---|---|---|
| GDP growth | 1.0% | 0.7% | 0.9% | European Commission — Belgium |
| Inflation | 3.0% | 3.4% | 2.6% | European Commission — Belgium |
| Deficit | 5.2% | 5.2% | 5.4% | European Commission — Belgium |
| Debt | 107.9% | 110.5% | 112.8% | European Commission — Belgium |
The Commission identifies higher defence expenditure and increasing interest expenditure as contributors to the projected deterioration. European Commission — Belgium forecast
Belgium’s initial 2027 EDP correction deadline was subsequently revised to 2029, with net-expenditure growth ceilings of 3.6% in 2025, 2.5% in 2026, 2.5% in 2027, 2.1% in 2028 and 2.1% in 2029. Council — Belgium EDP
Finland — rapidly increasing debt and defence-investment pressure
Finland’s 2025 GDP amounted to €280.570 billion, while expenditure reached 57.5% of GDP, revenue 54.1%, the deficit €9.613 billion or 3.4%, and public debt €248.433 billion or 88.5% of GDP. Eurostat — Finland fiscal account
Debt increased from 74.0% of GDP in 2022 to 77.0% in 2023, 82.4% in 2024 and 88.5% in 2025, an unusually rapid movement over a short interval. Eurostat — Finland debt series
Finland — 2025–2027 fiscal outlook
| Indicator | 2025 | 2026 | 2027 | Official source |
|---|---|---|---|---|
| Growth | 0.2% | 0.8% | 1.4% | European Commission — Finland |
| Unemployment | 9.7% | 10.1% | 9.8% | European Commission — Finland |
| Deficit | 3.4% | 4.5% | 4.6% | European Commission — Finland |
| Debt | 88.5% | 91.2% | 93.1% | European Commission — Finland |
The Commission specifically identifies a significant increase in defence investment from 2026, including major military procurement, alongside weak economic growth and fiscal consolidation. European Commission — Finland forecast
The Council opened Finland’s EDP on 20 January 2026, imposing cumulative net-expenditure growth ceilings of 2.5% in 2026, 4.1% in 2027 and 5.9% in 2028. Council — Finland EDP
Hungary — renewed fiscal deterioration after partial correction
Hungary’s 2025 general-government account recorded GDP of HUF 87.046 trillion, expenditure of 47.3%, revenue of 42.6%, a deficit of HUF 4.059 trillion or 4.7% of GDP, and debt of HUF 64.912 trillion or 74.6% of GDP. Eurostat — Hungary fiscal account
Hungary — current forecast
| Indicator | 2025 | 2026 | 2027 | Official source |
|---|---|---|---|---|
| GDP growth | 0.5% | 1.8% | 2.1% | European Commission — Hungary |
| Inflation | 4.4% | 3.2% | 3.1% | European Commission — Hungary |
| Deficit | 4.7% | 6.2% | 5.8% | European Commission — Hungary |
| Debt | 74.6% | 75.1% | 76.8% | European Commission — Hungary |
The Commission attributes the forecast increase in the deficit to deficit-increasing measures introduced in late 2025 and early 2026. European Commission — Hungary forecast
Hungary’s EDP requires correction by 2026, with net-expenditure growth limited to 4.3% in 2025 and 4.0% in 2026. Council — Hungary EDP
Slovakia — consolidation constrained by weak domestic demand
Slovakia recorded €136.754 billion GDP, expenditure of 47.9%, revenue of 43.5%, a deficit of €6.086 billion or 4.5%, and public debt of €83.957 billion or 61.4% of GDP in 2025. Eurostat — Slovakia fiscal account
The Commission projects growth of only 0.8% in 2026 and 1.5% in 2027, with deficits of 4.6% and 5.4%, while fiscal consolidation suppresses domestic demand and EU resources support investment. European Commission — Slovakia forecast
Slovakia — fiscal record
| Indicator | 2025 | 2026 | 2027 | Official source |
|---|---|---|---|---|
| Growth | 0.8% | 0.8% | 1.5% | European Commission — Slovakia |
| Inflation | 4.2% | 4.3% | 3.2% | European Commission — Slovakia |
| Deficit | 4.5% | 4.6% | 5.4% | European Commission — Slovakia |
| 2025 debt | 61.4% GDP | Rising trajectory | Rising trajectory | Eurostat — Slovakia debt |
The EDP requires nominal net-expenditure growth of no more than 3.8% in 2025, 0.9% in 2026 and 1.6% in 2027. Council — Slovakia EDP
Bulgaria — low inherited debt but rapidly widening fiscal position
Bulgaria’s 2025 GDP reached €116.018 billion, expenditure was 41.7% of GDP, revenue 38.1%, the deficit €4.113 billion or 3.5%, and debt €34.635 billion or 29.9% of GDP. Eurostat — Bulgaria fiscal account
The debt ratio had been only 23.8% in 2024, meaning the increase to 29.9% in 2025 was substantial even though the absolute debt level remains comparatively limited. Eurostat — Bulgaria debt series
Bulgaria — fiscal outlook
| Indicator | 2025 | 2026 | 2027 | Official source |
|---|---|---|---|---|
| GDP growth | 3.1% | 2.5% | 2.2% | European Commission — Bulgaria |
| Inflation | 3.5% | 4.2% | 2.6% | European Commission — Bulgaria |
| Deficit | 3.5% | 4.1% | 4.3% | European Commission — Bulgaria |
| Debt | 29.9% | 32.3% | 35.5% | European Commission — Bulgaria |
The Commission attributes the forecast deterioration particularly to social expenditure and public-sector wages. European Commission — Bulgaria forecast
The Council opened an EDP on 10 July 2026, requiring Bulgaria to present corrective measures by 15 October 2026 and limiting cumulative net-expenditure growth to 4.2% in 2026, 7.7% in 2027, 11.4% in 2028 and 15.0% in 2029. Council — Bulgaria EDP
Malta — post-EDP fiscal position
Malta recorded €24.577 billion of GDP, expenditure of 37.0%, revenue of 34.8%, a deficit of €545 million or 2.2% of GDP, and public debt of €11.397 billion or 46.4% of GDP in 2025. Eurostat — Malta fiscal account
Malta — post-correction baseline
| Indicator | 2025 | 2026 | 2027 | Official source |
|---|---|---|---|---|
| GDP growth | 4.0% | 3.7% | 3.6% | European Commission — Malta |
| Inflation | 2.4% | 2.7% | 2.3% | European Commission — Malta |
| Deficit | 2.2% | 2.2% | 2.1% | European Commission — Malta |
| Debt | 46.4% | approximately stable | approximately stable | European Commission — Malta |
The Council formally closed Malta’s EDP on 12 June 2026 after concluding that the deficit had been reduced successfully and durably below 3% of GDP. Council — Malta EDP closure, 12 June 2026
The Maltese case is institutionally relevant because it demonstrates that EDP abrogation depends not merely on observing one sub-3% figure but on the Council accepting that the correction is durable.
United Kingdom — a different fiscal architecture outside the EU framework
The United Kingdom cannot be inserted mechanically into the ESA/EDP legal framework because its domestic fiscal surveillance is organised through the Office for Budget Responsibility, HM Treasury fiscal rules and ONS public-sector finance statistics rather than the EU Stability and Growth Pact.
ONS recorded £57.6 billion of public-sector net borrowing in the first three months of financial year 2026/27 to June 2026, equivalent to 1.9% of GDP for that year-to-date period; central-government receipts over the same three months amounted to £266.8 billion, while central-government expenditure reached £332.2 billion. Office for National Statistics — Public sector finances, UK: June 2026
At the end of June 2026, ONS estimated public-sector net debt excluding public-sector banks at £2.9899 trillion, equivalent to 94.9% of GDP, while the broader measure of public-sector net financial liabilities stood at £2.6625 trillion or 84.5% of GDP. ONS — Public sector finances, June 2026
United Kingdom — current public-finance indicators
| Indicator | Latest verified value | Reference period | Official source |
|---|---|---|---|
| Public-sector net borrowing | £16.0 bn | June 2026 | ONS — June 2026 public finances |
| FY-to-June borrowing | £57.6 bn | Apr–Jun 2026 | ONS — June 2026 public finances |
| FY-to-June central-government receipts | £266.8 bn | Apr–Jun 2026 | ONS — June 2026 public finances |
| FY-to-June central-government expenditure | £332.2 bn | Apr–Jun 2026 | ONS — June 2026 public finances |
| Central-government debt interest | £11.8 bn | June 2026 alone | ONS — June 2026 public finances |
| Public-sector net debt | £2.9899 tn | End-Jun 2026 | ONS — June 2026 public finances |
| Net debt / GDP | 94.9% | End-Jun 2026 | ONS — June 2026 public finances |
| Net financial liabilities | £2.6625 tn / 84.5% GDP | End-Jun 2026 | ONS — June 2026 public finances |
The June data also illustrate the particular sensitivity of the British public finances to inflation-linked debt: central-government interest expenditure of £11.8 billion in June 2026 was £5.3 billion lower than a year earlier largely because movements in the Retail Prices Index affect index-linked gilts. ONS — June 2026 public finances
The UK fiscal file therefore requires a balance-sheet and interest-rate analysis different from the EU EDP framework; a later assessment should not describe a UK fiscal rule breach as equivalent to an EU excessive-deficit finding because the legal institutions, fiscal aggregates and enforcement systems are different.
Sovereign fiscal map — verified 2025 accounting positions
The following table is not a ranking and should not be interpreted as one; it provides a single audit table of the fiscal identities used in the individual files, using the same Eurostat April 2026 vintage for EU states and therefore avoiding the mixture of different national statistical dates.
| State | Revenue % GDP | Expenditure % GDP | Balance % GDP | Debt % GDP | EDP status at 23 Sep 2026 | Official sources |
|---|---|---|---|---|---|---|
| France | 52.1 | 57.2 | −5.1 | 115.6 | Open; correction by 2029 | Eurostat · Council |
| Germany | 47.9 | 50.5 | −2.7 | 63.5 | No active deficit-based EDP | Eurostat · Council |
| Spain | 42.9 | 45.3 | −2.4 | 100.7 | No active deficit-based EDP | Eurostat |
| Austria | 51.0 | 55.2 | −4.2 | 81.5 | Open; correction by 2028 | Eurostat · Council |
| Sweden | 48.6 | 49.9 | −1.3 | 35.1 | No active deficit-based EDP | Eurostat |
| Poland | 43.6 | 50.9 | −7.3 | 59.7 | Open; correction by 2028 | Eurostat · Council |
| Romania | 35.4 | 43.3 | −7.9 | 59.3 | Open; correction by 2030 | Eurostat · Council |
| Belgium | 49.0 | 54.2 | −5.2 | 107.9 | Open; correction by 2029 | Eurostat · Council |
| Finland | 54.1 | 57.5 | −3.4 | 88.5 | Open | Eurostat · Council |
| Hungary | 42.6 | 47.3 | −4.7 | 74.6 | Open; correction by 2026 | Eurostat · Council |
| Slovakia | 43.5 | 47.9 | −4.5 | 61.4 | Open | Eurostat · Council |
| Bulgaria | 38.1 | 41.7 | −3.5 | 29.9 | Open from Jul 2026 | Eurostat · Council |
| Malta | 34.8 | 37.0 | −2.2 | 46.4 | Closed 12 Jun 2026 | Eurostat · Council |
Fiscal-pressure mechanisms identified by the official record
The sovereign files reveal several distinct mechanisms that must remain analytically separate.
Revenue-capacity pressure
Romania’s 35.4% revenue ratio, Bulgaria’s 38.1%, Poland’s 43.6% and France’s 52.1% are not merely different tax rates but different overall general-government revenue structures containing taxes, social contributions, property income and other receipts under ESA accounting. Eurostat — 2025 government revenue
Consequently, the fiscal adjustment required to close an identical deficit cannot be assumed to have the same economic incidence across countries: the policy choice between expenditure restraint, tax measures and stronger nominal growth depends on the underlying national revenue system.
Defence expenditure pressure
The Commission explicitly identifies defence expenditure as a material fiscal driver in Germany, Belgium, Sweden, Finland and Poland, while the strength of the mechanism differs across countries because Germany is expanding investment from a relatively moderate debt ratio, Finland is entering a period of rapidly increasing debt, Poland is simultaneously financing large defence commitments and running a substantial deficit, and Sweden is expanding from a much lower debt base. European Commission — Germany Belgium Sweden Finland Poland
Interest-cost pressure
The Commission explicitly identifies increasing interest expenditure as a fiscal pressure in Belgium, while the UK ONS data demonstrate the separate mechanism created by a large stock of inflation-linked sovereign securities, where monthly debt-service expenditure can move materially with RPI indexation. European Commission — Belgium ONS — UK public-sector finances
Growth-denominator pressure
The debt ratio depends not only on borrowing but also on nominal GDP. Spain’s debt ratio continued to decline despite a nominal debt stock above €1.69 trillion because economic growth and the denominator partly absorbed new borrowing, whereas Finland’s weak output performance combined with continuing deficits produces the opposite debt-ratio dynamic. Eurostat — Spain and Finland debt data European Commission — Spain Finland
Key judgments
The official 2025 accounts establish that the fiscal pressures affecting European governments arise from different combinations of spending, revenue, debt-service obligations and economic growth, rather than from a single continental fiscal condition.
France and Belgium enter the forecast period with simultaneously high expenditure ratios, high debt and substantial continuing deficits; Germany is moving toward fiscal expansion following a domestic constitutional-policy change; Spain is operating with a declining debt ratio supported by relatively strong growth; Austria remains under correction with debt still increasing; Sweden is deliberately increasing expenditure from a much lower sovereign-debt base; Poland combines strong real growth with very high defence and public-investment expenditure; Romania combines a very large fiscal deficit with a markedly lower general-government revenue ratio; Finland faces weak growth, accelerating debt and rising defence investment; and the United Kingdom operates under a separate fiscal architecture in which inflation-indexed debt creates a material additional channel of interest-cost volatility.
These findings do not establish that one national fiscal policy is superior to another, because the sovereign files differ in starting debt, demographic liabilities, tax systems, security requirements, economic cycles, currency arrangements and institutional rules. What they establish is the factual baseline required for the next analytical stage: testing whether European fiscal surveillance has treated materially different national situations according to the same legal and methodological framework.
What would change the assessment
The 21 October 2026 Eurostat EDP notification is the next major statistical event because it will update the harmonised national accounts used throughout this chapter and can revise the 2025 deficit, debt, revenue and expenditure series. Eurostat — EDP release timetable
The Commission’s next economic forecast will alter the forward fiscal trajectories where revised growth, energy prices, defence expenditure, interest costs or national budget measures differ materially from the assumptions used on 21 May 2026. European Commission — Economic forecasts
Any Council finding that a state has failed to take effective action, any revision of an EDP correction path, any activation of fiscal escape clauses or any closure of a procedure would change the institutional status recorded here and must therefore be incorporated by decision date rather than backdated into the 2025 statistical record.
Open official record
The next stage of the dossier requires the country-by-country retrieval of national budget laws, stability or medium-term fiscal plans, debt-management reports, tax-revenue accounts, pension expenditure, healthcare expenditure, defence appropriations and sovereign interest-cost projections for those states in which these variables are material to the institutional-consistency assessment.
Those records should be used in the subsequent chapter not to construct a political ranking, but to answer the more difficult question left open by the harmonised Eurostat and Commission data: whether the same European fiscal rules have produced institutionally consistent treatment when applied to sovereign systems with materially different debt structures, expenditure obligations, security burdens and adjustment capacities.
European Sovereign Fiscal Architecture
The fiscal position of each state is shown independently rather than as a ranking. Historical data use the Eurostat April 2026 EDP vintage, while forward values use the European Commission Spring 2026 forecast. The dashboard separates deficit, debt, revenue, expenditure, growth and institutional surveillance so that different sovereign systems are not collapsed into one indicator.
Common 2025 statistical baseline
| State | Revenue % GDP | Expenditure % GDP | Balance % GDP | Debt % GDP | Institutional status |
|---|---|---|---|---|---|
| France | 52.1% | 57.2% | −5.1% | 115.6% | EDP open · correction by 2029 |
| Germany | 47.9% | 50.5% | −2.7% | 63.5% | No active deficit-based EDP |
| Spain | 42.9% | 45.3% | −2.4% | 100.7% | No active deficit-based EDP |
| Austria | 51.0% | 55.2% | −4.2% | 81.5% | EDP open · correction by 2028 |
| Sweden | 48.6% | 49.9% | −1.3% | 35.1% | No active deficit-based EDP |
| Poland | 43.6% | 50.9% | −7.3% | 59.7% | EDP open · correction by 2028 |
| Romania | 35.4% | 43.3% | −7.9% | 59.3% | EDP open · correction by 2030 |
| Belgium | 49.0% | 54.2% | −5.2% | 107.9% | EDP open · correction by 2029 |
| Finland | 54.1% | 57.5% | −3.4% | 88.5% | EDP open |
| Hungary | 42.6% | 47.3% | −4.7% | 74.6% | EDP open · correction by 2026 |
| Slovakia | 43.5% | 47.9% | −4.5% | 61.4% | EDP open |
| Bulgaria | 38.1% | 41.7% | −3.5% | 29.9% | EDP opened July 2026 |
| Malta | 34.8% | 37.0% | −2.2% | 46.4% | EDP closed June 2026 |
France
France · Large structural expenditure and continuing primary imbalance
EDP open · 2029| Indicator | 2025 | 2026 forecast | 2027 forecast |
|---|---|---|---|
| Real GDP growth | 0.8% | 0.8% | 1.1% |
| Government balance | −5.1% | −5.1% | −5.7% |
| Debt | 115.6% | 118.1% | 120.2% |
| Unemployment | 7.7% | 8.3% | 8.7% |
Germany
Germany · Fiscal expansion after constitutional reform
No active deficit-based EDP| Indicator | 2025 | 2026 | 2027 |
|---|---|---|---|
| GDP growth | 0.2% | 0.6% | 0.9% |
| Government balance | −2.7% | −3.7% | −4.1% |
| Debt | 63.5% | 65.8% | 68.0% |
Spain
Spain · Growth-supported debt reduction
No active deficit-based EDP| Indicator | 2025 | 2026 | 2027 |
|---|---|---|---|
| GDP growth | 2.8% | 2.4% | 1.9% |
| Deficit | 2.4% | 2.4% | 2.0% |
| Debt | 100.7% | 99.6% | 98.9% |
| Unemployment | 10.5% | 9.9% | 9.6% |
Austria
Austria · Persistent expenditure gap and rising debt
EDP open · 2028| Indicator | 2025 | 2026 | 2027 |
|---|---|---|---|
| GDP growth | 0.6% | 0.6% | 0.9% |
| Deficit | 4.2% | 4.1% | 4.1% |
| Debt | 81.5% | 83.4% | 84.9% |
Sweden
Sweden · Fiscal expansion from a low debt base
No active deficit-based EDPPoland
Poland · Defence, investment and rapid debt accumulation
EDP open · 2028Romania
Romania · Revenue constraint and prolonged EDP
EDP open · 2030| Indicator | 2025 | 2026 | 2027 |
|---|---|---|---|
| GDP growth | 0.7% | 0.1% | 2.3% |
| Inflation | 6.8% | 7.0% | Lower thereafter |
| Deficit | 7.9% | 6.2% | 5.8% |
| Debt | 59.3% | 61.6% | ~63.3% |
Belgium
Belgium · High expenditure and rising debt
EDP open · 2029Finland
Finland · Rapid debt increase and defence-investment pressure
EDP openHungary
Hungary · Renewed fiscal deterioration
EDP open · 2026Slovakia
Slovakia · Consolidation under weak domestic demand
EDP openBulgaria
Bulgaria · Low inherited debt, widening fiscal deficit
EDP opened Jul 2026Malta
Malta · Post-EDP fiscal baseline
EDP closed Jun 2026United Kingdom · Different fiscal architecture
United Kingdom · Public-sector finance outside the EU EDP framework
Domestic fiscal rules| Indicator | Latest verified value | Reference period |
|---|---|---|
| Public-sector net borrowing | £16.0 bn | June 2026 |
| FY-to-June borrowing | £57.6 bn | Apr–Jun 2026 |
| Central-government receipts | £266.8 bn | Apr–Jun 2026 |
| Central-government expenditure | £332.2 bn | Apr–Jun 2026 |
| Public-sector net debt | £2.9899 tn | End-Jun 2026 |
| Net financial liabilities | £2.6625 tn | End-Jun 2026 |
Main fiscal-pressure mechanisms identified in the official record
Institutional reading
Chapter 4 — Institutional Consistency and the Political-Pressure Question
Principal judgment
The documentary record examined through 23 September 2026 establishes a system in which the legal trigger for deficit-based excessive-deficit procedures, the statistical methodology used to measure government deficit and debt, the formal mechanisms for evaluating effective action and the requirement that correction be durable are defined by common EU legislation and have been applied across governments of different political composition, fiscal structure and debt position; within that record, no official statistical reservation, Eurostat amendment, finding of data manipulation, Commission finding of discriminatory treatment, or Council document has been identified that establishes deliberate institutional pressure against the Italian government.
That conclusion does not establish that political pressure is impossible, nor does it immunise any Commission, Council, Eurostat or national statistical decision from scrutiny, because political pressure is a proposition concerning motive and conduct rather than a fiscal ratio; establishing it would require documentary evidence of selective methodological treatment, departure from common rules, inconsistent procedural thresholds, interference with statistical production, selective refusal of flexibility, unequal treatment in effective-action assessments, or communications demonstrating an intention to use fiscal governance politically.
The available official record instead provides several directly testable observations. Italy’s EDP was opened on 26 July 2024 under the same Council process that simultaneously opened procedures against Belgium, France, Hungary, Malta, Poland and Slovakia, while Romania’s existing procedure remained open. Eurostat’s first 2026 EDP notification subsequently stated that it had no reservations concerning the data reported by any Member State and made no amendments to the reported data, which is particularly significant because reservations and amendments are precisely the formal tools Eurostat uses when it doubts the quality or methodological conformity of national EDP statistics.
Italy’s procedure was also not escalated following the Commission’s effective-action assessment of 3 June 2026; the Commission recorded that the Italian EDP was held in abeyance, meaning that the procedure remained legally open but Italy was not found at that point to have failed to take effective action. By contrast, Romania was formally found by the Council in June 2025 not to have taken effective action, after which its corrective path was revised in July 2025.
The documentary question is therefore narrower and more demanding than the political argument: has Italy been subjected to fiscal-statistical treatment inconsistent with the rules and precedents applied elsewhere? On the present official record, specific differences in correction deadlines and permitted expenditure growth clearly exist, but those differences are explicitly embedded in country-specific medium-term plans, fiscal trajectories and Council recommendations rather than being presented as identical numerical obligations for every Member State.
The consistency test: what would constitute unequal treatment
A government-level audit cannot infer unequal treatment simply because two countries received different correction deadlines or different net-expenditure ceilings, because the reformed fiscal framework is explicitly country-specific; the relevant test is whether states in materially equivalent procedural circumstances were subjected to different legal standards, statistical definitions or evidentiary thresholds without a documented fiscal justification.
Documentary tests for institutional consistency
| Test | Consistent treatment would require | Evidence of possible inconsistency would require | Verified institutional basis |
|---|---|---|---|
| Statistical definition | ESA 2010 concepts applied to all Member States | A different definition of deficit, debt, sector perimeter or transaction timing applied selectively to Italy | Eurostat states that it has sole competence over EDP statistical methodology and verifies comparability. |
| Data-quality assessment | Same tests of compliance, completeness, reliability, timeliness and consistency | Italy subjected to a unique quality standard not imposed elsewhere | Eurostat’s quality-assurance system applies common criteria and permits reservations and amendments. |
| EDP opening | Deficit-based EDP opened when Treaty and secondary-law conditions are satisfied | Comparable breach ignored for another state without legal explanation | Council opened procedures against seven states simultaneously in July 2024 and later against Austria, Finland and Bulgaria when relevant conditions arose. |
| Correction deadline | Country-specific deadline justified by fiscal trajectory and medium-term plan | Different deadline without identifiable economic or procedural basis | Council states that recommendations contain country-specific paths aligned with medium-term fiscal-structural plans. |
| Effective-action assessment | Same legal test applied to implementation of Council recommendation | Italy escalated despite compliant action while equivalent non-compliance elsewhere was ignored | Italy was held in abeyance in June 2026; Romania was formally found not to have taken effective action in June 2025. |
| Closure | Correction must be successful and durable | One state allowed to exit on a temporary or non-durable correction while Italy is required to prove durability | Malta’s EDP was closed in June 2026 only after the Council concluded that its deficit had been successfully and durably reduced below 3%. |
| Statistical independence | National statistical authorities decide methods, timing and content independently | Evidence that political authorities instructed or altered statistical methodology or publication | Regulation 223/2009 requires professional independence and prohibits national statistical heads from taking government instructions. |
| Fiscal flexibility | Escape-clause requests assessed under Article 26 criteria | Comparable request accepted elsewhere but rejected for Italy on non-legal grounds | Defence NEC activation is a formal country-specific process; activation cannot be inferred automatically from defence expenditure. |
The central methodological consequence is that different outcomes are not themselves evidence of inconsistent treatment. Consistency concerns the rules and decision process, while outcomes can legitimately differ because the relevant fiscal conditions differ.
Statistical governance: the strongest institutional protection against political intervention
European statistical law is unusually explicit about political independence. Regulation (EC) No 223/2009 defines professional independence as the requirement that statistics be developed, produced and disseminated independently, including decisions concerning techniques, definitions, methodologies, sources, timing and content, and that these activities remain free from pressure by political or interest groups or by Union or national authorities.
The regulation goes further in Article 5a: heads of national statistical institutes have sole responsibility for decisions concerning statistical processes, methods, standards, procedures, publication content and publication timing, and are required to perform their statistical duties independently without seeking or receiving instructions from governments or other institutions.
This matters directly to the political-pressure question concerning ISTAT. A public criticism by a prime minister or minister is politically significant, but under the governing law it does not itself constitute evidence that the statistical result was manipulated; the relevant institutional test is whether the criticism translated into instructions, interference with methodology, alteration of timing, dismissal pressure inconsistent with professional criteria, or another action capable of compromising the legal independence of the statistical authority.
Statistical-independence safeguards relevant to Italy
| Safeguard | Legal requirement | Evidentiary implication for the political-pressure hypothesis | Official authority |
|---|---|---|---|
| Professional independence | Statistics must be produced free from political or governmental pressure | Political criticism alone does not establish statistical interference | Regulation 223/2009, Article 2. |
| Methodological autonomy | NSI head has sole responsibility for statistical methods and procedures | Evidence that a government dictated the methodology would be highly material | Regulation 223/2009, Article 5a. |
| Publication autonomy | NSI head controls timing and content of statistical releases | Government intervention in release timing or content would constitute a material governance issue | Regulation 223/2009, Article 5a. |
| Impartiality | Users must receive neutral statistical treatment | Selective presentation designed to favour or disadvantage a political actor would conflict with the governing principle | Regulation 223/2009, Article 2. |
| Objectivity | Statistics must be systematic, reliable, unbiased and transparent | Any allegation of bias must therefore be tested against methodology and source documentation | Regulation 223/2009, Article 2. |
| Eurostat methodological oversight | Eurostat has sole competence over EDP statistical methodology | Material national departures can be challenged through the European verification system | Eurostat data-quality framework. |
The regulatory framework therefore provides a concrete evidentiary standard: a serious allegation of institutional pressure on ISTAT should ultimately be capable of identifying a decision, communication, methodological departure, appointment intervention or publication interference inconsistent with these protections.
What Eurostat actually found in April 2026
The first harmonised EDP notification of 2026 is particularly important because Eurostat did not merely publish Member State numbers; it also explicitly disclosed its quality position.
Eurostat stated on 22 April 2026 that it had “no reservations on the data reported by Member States” and had made no amendments to the data reported by Member States.
Under Article 15 of Regulation 479/2009, Eurostat expresses a reservation when it has doubts concerning the quality of reported data and can amend actual data when evidence shows that national submissions fail the requirements of accounting compliance, completeness, reliability, timeliness or consistency.
April 2026 EDP quality-control outcome
| Quality-control instrument | Eurostat result | Meaning for Italy | Institutional significance |
|---|---|---|---|
| Formal reservation | None for Member States | Italy’s notified data were not formally qualified by Eurostat | No documented unresolved Eurostat quality objection at that notification. |
| Eurostat amendment | None | Eurostat did not substitute its own Italian deficit or debt figure | No documented statistical override in the April notification. |
| Common accounting basis | ESA 2010 | Italian data were published within the same accounting system as other EU states | Common statistical framework. |
| Next regular notification | 21 October 2026 | September ISTAT revisions enter a subsequent harmonisation cycle | Revision is part of the normal EDP statistical calendar. |
This does not prove that every underlying Italian statistical classification is beyond legitimate challenge, but it does establish that the formal European statistical authority had not, at that point, identified an unresolved quality defect requiring a reservation or an amendment.
Revisions are not unique to Italy
A key factual question in the political debate is whether repeated revisions of Italian national accounts should themselves be regarded as anomalous.
Eurostat’s own April 2026 documentation records significant revisions between the October 2025 and April 2026 EDP notifications across multiple Member States, including revisions caused by changes in accrual timing, updated source data and reclassification of transactions. Belgium’s deficit history was revised partly because of a change in the timing applied to VAT refunds; Estonia’s deficit data changed because of the timing applied to corporate-income-tax recording; Ireland’s recorded surplus changed as source data and accrual adjustments were updated; and Greece’s result changed following updated information from an extrabudgetary unit.
Examples of routine EDP revisions outside Italy
| State | Source of revision documented by Eurostat | Analytical implication | Official source |
|---|---|---|---|
| Belgium | Revised treatment of VAT-refund timing | Accrual conventions can materially alter historical deficit data | Eurostat revision note. |
| Estonia | Change in timing of corporate-income-tax recording | Fiscal series can move because the timing rule changes | Eurostat revision note. |
| Ireland | Updated source data and accrual adjustments | New information can revise previously published surplus figures | Eurostat revision note. |
| Greece | Updated data from an extrabudgetary government unit | Expanded or corrected source information changes the consolidated result | Eurostat revision note. |
| Italy | September 2026 national-accounts revision incorporating updated information and methodological changes | Must be assessed against the same revision-governance framework rather than presumed exceptional solely because the fiscal ratio is politically sensitive | The October EDP notification will provide the next harmonised European vintage. |
The existence of revision is therefore not a diagnostic indicator of political pressure by itself. The diagnostic question is whether the methodological basis of an Italian revision differs improperly from the revision principles applied elsewhere.
EDP opening: the legal trigger was applied across governments
On 26 July 2024, the Council adopted decisions establishing excessive deficits for Belgium, France, Hungary, Italy, Malta, Poland and Slovakia, while retaining Romania within its existing procedure because it had not taken effective corrective action.
The decisions involved governments across a wide range of political configurations. The procedure itself therefore cannot be characterised on the basis of this opening round as having been created or deployed exclusively against the Italian government.
July 2024 opening cohort
| State | Deficit underlying Council action | Procedural decision | Subsequent correction deadline | Official source |
|---|---|---|---|---|
| Belgium | 4.4% of GDP in 2023 | EDP opened 26 Jul 2024 | Initially 2027; later revised to 2029 | Council EDP record. |
| France | 5.5% | EDP opened 26 Jul 2024 | 2029 | Council EDP record. |
| Hungary | 6.7% | EDP opened 26 Jul 2024 | 2026 | Council EDP record. |
| Italy | 7.4% | EDP opened 26 Jul 2024 | 2026 | Council EDP record. |
| Malta | Deficit above Treaty reference | EDP opened Jul 2024 | Initially 2027; closed Jun 2026 | Council timeline. |
| Poland | 5.1% | EDP opened 26 Jul 2024 | 2028 | Council EDP record. |
| Slovakia | 4.9% | EDP opened 26 Jul 2024 | 2027 | Council EDP record. |
| Romania | Existing EDP from 2020 | Procedure remained open | Revised to 2030 | Council EDP record. |
The opening stage therefore provides no documentary evidence that Italy was singled out for entry into the corrective arm while states meeting the same procedural condition were systematically exempted.
Different correction deadlines are built into the framework
The strongest superficial argument for unequal treatment is that Italy was required to end its excessive deficit by 2026, while France received until 2029, Poland until 2028 and Romania until 2030. The official Council record confirms these differences but also states explicitly that each recommendation contains a country-specific corrective budgetary path and deadline aligned with the objectives contained in the Member State’s medium-term fiscal-structural plan.
Consequently, the deadlines cannot be treated as sanctions of different severity without examining the projected fiscal trajectory behind them.
Correction horizons adopted in January 2025
| State | Council correction deadline | 2025 net-expenditure ceiling | Later annual ceiling/path | Official source |
|---|---|---|---|---|
| Italy | 2026 | 1.3% | 1.6% in 2026 | Council recommendation. |
| France | 2029 | 0.8% | 1.2% in 2026–28; 1.1% in 2029 | Council recommendation. |
| Poland | 2028 | 6.3% | 4.4%, 4.0%, 3.5% through 2028 | Council recommendation. |
| Slovakia | 2027 | 3.8% | 0.9% in 2026; 1.6% in 2027 | Council recommendation. |
| Malta | 2027 initial recommendation | 6.0% | 5.8% in 2026 and 2027 | Council recommendation. |
| Romania | 2030 | 5.1% under Jan recommendation | Multi-year path subsequently revised after finding of no effective action | Council January recommendation and later revision. |
The figures demonstrate why a deadline cannot be interpreted independently from the permitted expenditure path. France received a much longer correction horizon but also an exceptionally restrictive net-expenditure growth ceiling of 0.8% in 2025, whereas Italy’s 2025 ceiling was 1.3%. Poland’s much higher permitted nominal expenditure growth reflects a different nominal-growth, inflation and fiscal trajectory rather than the absence of an EDP.
The documented structure therefore supports the conclusion that the framework is differentiated, but differentiation is not equivalent to discrimination.
Belgium demonstrates that deadlines can be revised
Belgium is especially relevant to the consistency audit because its correction deadline changed after the initial recommendation.
The Council initially required Belgium to end its excessive deficit by 2027, with nominal net-expenditure growth limited to 2.4% in 2025, 1.9% in 2026 and 2.0% in 2027. In June 2025, the Council adopted a revised recommendation extending the deadline to 2029 and revising the expenditure path to 3.6% in 2025, 2.5% in 2026, 2.5% in 2027, 2.1% in 2028 and 2.1% in 2029.
This establishes that correction deadlines are not immutable and can be modified through formal procedure when the underlying plan and institutional assessment change.
Belgium procedural revision
| Decision stage | Deadline | Net-expenditure path | Institutional observation | Source |
|---|---|---|---|---|
| January 2025 recommendation | 2027 | 2.4%, 1.9%, 2.0% | Initial corrective trajectory | Council. |
| June 2025 revised recommendation | 2029 | 3.6%, 2.5%, 2.5%, 2.1%, 2.1% | Formal revision of correction path | Council EDP record. |
For the Italian political-pressure hypothesis, Belgium creates a specific collection question: whether Italy has requested or qualified for an equivalent revision of its corrective horizon and, if so, how the Commission and Council responded. Without that documentary sequence, the mere existence of Belgium’s revised timetable is insufficient to establish unequal treatment.
Effective-action enforcement: Italy and Romania followed different procedural branches
The treatment of Italy in June 2026 and Romania in June–July 2025 provides one of the most useful tests of whether the corrective arm differentiates between compliance and non-compliance.
For Italy, the Commission’s 3 June 2026 assessment recorded that the excessive-deficit procedure was held in abeyance following the assessment of effective action.
For Romania, the Council formally concluded on 20 June 2025 that Romania had not taken effective action in response to previous recommendations, and on 8 July 2025 revised the corrective trajectory, requiring measures by 15 October 2025 and setting a new path extending to 2030.
Effective-action treatment
| State | Official assessment | Procedural consequence | What this establishes | Source |
|---|---|---|---|---|
| Italy | Effective action recognised in June 2026 assessment | EDP held in abeyance | Procedure remained open without escalation | Commission. |
| Romania | Council found no effective action in June 2025 | Corrective path revised and additional action demanded | Non-compliance produced a documented escalation | Council. |
| Malta | Correction judged successful and durable | EDP abrogated June 2026 | Successful correction produced closure | Council. |
This three-case sequence shows three distinct branches of the system operating in the official record: continued surveillance without escalation, escalation following insufficient action, and termination following durable correction.
Malta provides the clearest test of the closure standard
The Council closed Malta’s EDP on 12 June 2026, explicitly stating that the decision was warranted because Malta’s general-government deficit had been successfully and durably reduced below 3% of GDP.
The standard therefore contains two elements: the numerical deficit criterion and durability.
Documentary closure test
| Element | Malta | Italy as of 23 Sep 2026 | Evidentiary consequence |
|---|---|---|---|
| Actual deficit below 3% | Satisfied | 2025 latest national result remained 3.1% | Conditions not yet identical |
| Correction judged durable | Council concluded yes | Not yet formally established for Italian closure | Requires forward fiscal assessment |
| Formal Council action | EDP abrogated | No abrogation decision | Procedure legally remains open |
| Effective-action record | Consistent with closure | Italy held in abeyance | Different procedural stage |
This means that Malta does not provide evidence that Italy was denied an exit under identical conditions because the two countries were not at the same documented procedural stage at the relevant dates.
Austria and Finland demonstrate later entry into surveillance
The Council did not confine EDP opening to the July 2024 group.
Austria entered the procedure on 8 July 2025 after a recorded 4.7% deficit in 2024, with correction required by 2028 and net-expenditure limits of 2.6% in 2025 and 2.2% in each of 2026 and 2027 before 2.0% in 2028.
Finland entered the procedure on 20 January 2026 following a 4.4% deficit in 2024 and a planned 4.3% deficit for 2025, with the Council requiring corrective measures by 30 April 2026.
Bulgaria was subsequently placed in an EDP on 10 July 2026 because its deficit was projected at 4.1% in 2026 and expected to remain above 3% in 2027.
These later decisions are relevant because they show the procedure continuing to be applied as new qualifying fiscal situations emerged after Italy’s EDP had already been opened.
The debt criterion is not being enforced through an automatic 60% trigger
Another possible source of misunderstanding concerns the 60% debt reference value. Several EU states with debt materially above 60% are not in debt-based EDPs, including states whose deficit remained below the deficit trigger.
The Council explains that under the reformed framework, highly indebted countries that comply with their Council-set net-expenditure paths and place debt on a plausibly downward trajectory are not automatically placed in an excessive-deficit procedure solely because current debt exceeds 60%; compliance is assessed through the expenditure path and debt-sustainability framework.
This distinction is directly relevant to Italy. Italy’s high debt ratio materially affects its required medium-term adjustment, but the fact that countries such as Spain can remain outside a deficit-based EDP despite debt exceeding 60% does not by itself establish an exception granted to those countries: the deficit arm and the debt-sustainability arm operate through different legal tests.
Defence flexibility: differentiation is built into requests and eligibility
The defence national escape clause introduces another area in which superficial comparison can be misleading. Activation is not automatic and does not apply identically to every state merely because defence spending is increasing.
A consistency test therefore has to ask:
| Question | Required documentary evidence |
|---|---|
| Did Italy submit a formal request for activation? | Italian government submission and Commission/Council record |
| Did other states submit requests? | National requests and Council decisions |
| Were Article 26 eligibility conditions applied consistently? | Commission recommendations and Council acts |
| Was qualifying defence expenditure calculated using the same methodology? | Commission methodological guidance |
| Was any Italian request refused? | Formal refusal and reasons |
| Did another state in materially equivalent circumstances receive approval? | Comparative decision record |
Without a rejected Italian request, the fact that other states activated the clause cannot itself prove discriminatory refusal.
Statistical revisions and political interpretation must remain separate
One of the most important findings of this audit is that statistical revisions are an ordinary feature of the EDP system, while political interpretation of a revision is a separate activity.
Eurostat maintains country-specific EDP inventories describing the sources, methods and procedures used to compile government deficit and debt statistics, and every Member State is required under Article 9 of Regulation 479/2009 to maintain such an inventory.
These inventories create another documentary route for testing the Italian case: if the treatment of a transaction, sector boundary, tax credit, accrual adjustment or government entity differs between Italy and another state, the relevant question can be investigated directly through the national EDP inventories and Eurostat methodological decisions rather than through political commentary.
Audit of the political-pressure proposition
The proposition that the Meloni government has faced deliberate pressure can be decomposed into several separate hypotheses, each requiring a different class of evidence.
Evidence matrix
| Proposition | Evidence that would support it | Evidence currently identified in official record | Current documentary status |
|---|---|---|---|
| ISTAT was politically induced to worsen Italy’s fiscal result | Government, EU or third-party instruction affecting methodology, sources, timing or publication | No such official record identified in the sources examined; European law expressly protects statistical independence | Not established |
| Eurostat selectively altered Italian figures | Formal amendment applied selectively without equivalent methodological basis | April 2026 Eurostat notification records no amendments to Member State data | Not supported by April notification |
| Eurostat formally doubted Italian EDP data | Reservation concerning Italy | April notification records no reservations concerning Member State data | Not supported by April notification |
| Italy was placed under EDP while equivalent states were exempted | States satisfying equivalent deficit conditions but denied EDP without legal basis | July 2024 procedures opened simultaneously against seven states; later Austria, Finland and Bulgaria were added | Not established from opening decisions |
| Italy received an exceptionally punitive correction deadline | Evidence that the same fiscal trajectory elsewhere generated materially more favourable treatment without documented justification | Correction deadlines vary widely and Council states they align with country-specific plans | Requires deeper case matching; not established by deadline difference alone |
| Italy was escalated despite effective action | Commission/Council finding escalating procedure despite compliance | June 2026 assessment held Italy’s EDP in abeyance | Contradicted by current procedural record |
| Italy was denied EDP closure under conditions accepted elsewhere | Another state exited with same deficit/durability position | Malta exited only after Council judged correction successful and durable; Italy had not yet reached the same formal stage | Not established |
| Defence flexibility was denied selectively | Rejected Italian application under conditions equivalent to accepted applications | No such rejection identified in the official record reviewed here | Not established |
| Political criticism of ISTAT itself proves statistical bias | Political statements alone | Statistical independence rules require methodological evidence, not inference from criticism | Insufficient evidence |
The evidentiary status should therefore remain deliberately differentiated. Several hypotheses are not established, one is directly inconsistent with the current effective-action record, and others remain legitimate collection questions requiring specific documents.
Italy’s short correction horizon requires deeper examination, but not a presumption
Italy and Hungary were both assigned 2026 correction deadlines, whereas other states received later deadlines.
For Italy, a short correction horizon can plausibly reflect the fact that the fiscal trajectory submitted at the time already anticipated moving below 3% rapidly; in other words, a government projecting an earlier correction can receive an earlier formal deadline because the Council recommendation follows the Member State’s own medium-term path.
The Council’s January 2025 statement explicitly notes that the corrective paths were aligned with the objectives expressed in Member States’ medium-term fiscal-structural plans.
This is a critical institutional point: a 2026 deadline can be more demanding in time, but it can also reflect an official national forecast asserting that correction is achievable by that date. Determining whether Italy was pressured into accepting that path requires examination of the negotiation history between the MEF, Commission and Council, not inference from the deadline itself.
The 2.94% question requires special evidentiary discipline
The political controversy surrounding whether Italy effectively needed approximately 2.94% rather than exactly 3.00% to obtain a reported value safely below the reference threshold is fundamentally a question of statistical precision and rounding, not a change in the Treaty threshold.
The Treaty reference remains 3%. Any lower operational number produced by rounding conventions must therefore be presented as a statistical consequence of the precision required for a reported ratio below 3%, not as a secret alternative legal threshold.
The institutional-consistency test is straightforward: the same rounding and precision convention must apply to every state’s EDP data. Evidence of an Italy-specific convention would be highly material; absent such evidence, the issue is one of statistical representation rather than differential law.
The political environment can be contentious without proving institutional manipulation
The interaction between political authorities and independent statistical institutions can itself create institutional tension. Regulation 223/2009 is designed precisely because governments have strong political interests in statistical outcomes, particularly GDP, inflation, unemployment, deficit and debt.
The existence of public criticism of ISTAT by members of the Italian government therefore matters as part of the political environment, but the direction of causality must not be inverted: government dissatisfaction with an independent statistic is not evidence that the statistic was produced against the government for political reasons.
Equally, the legal independence of ISTAT does not prove that every technical decision is substantively correct. A classification can be challenged through methodology, source quality, ESA interpretation, consistency with comparable transactions and Eurostat precedent.
The appropriate governmental response to contested statistics is therefore an audit of methodology and consistency, not a presumption either of infallibility or of political manipulation.
Procedural treatment matrix
The official cases reviewed allow the operation of the EDP to be mapped without reducing them to fiscal rankings.
| Procedural condition | Documented case | EU response | Consistency implication |
|---|---|---|---|
| Excessive deficit identified | Italy, France, Belgium, Hungary, Malta, Poland, Slovakia in Jul 2024 | EDP opened | Same procedural instrument applied to multiple states. |
| Existing procedure with failure to correct | Romania | Procedure maintained and later escalated after no-effective-action finding | Enforcement mechanism demonstrably used. |
| New excessive deficit after 2024 | Austria | EDP opened Jul 2025 | Surveillance continued beyond initial cohort. |
| New excessive deficit after 2025 | Finland | EDP opened Jan 2026 | Trigger continued to be applied. |
| Projected persistent breach | Bulgaria | EDP opened Jul 2026 | Forward-looking persistence can support opening. |
| Effective action while deficit not yet corrected | Italy | Procedure held in abeyance | Compliance recognised without premature closure. |
| Durable correction | Malta | EDP closed Jun 2026 | Closure mechanism demonstrably available. |
| Changed fiscal plan/circumstances | Belgium | Recommendation and deadline revised | Adjustment path can be formally modified. |
The available procedural record therefore contains examples of opening, continuation, escalation, revision, abeyance and closure across different Member States, which is incompatible with a description of the system as one in which Italy alone is subject to active fiscal enforcement.
Where a genuine asymmetry could still exist
The absence of proof of deliberate pressure at this stage does not end the investigation. A serious consistency audit should now move below the headline procedural level and test transaction-specific and methodological decisions.
The potentially material areas include the national-account treatment of tax credits, particularly the timing and classification of transferable building-renovation credits; public-private transactions; capital injections; state guarantees; securitisations; EU-funded investment; defence procurement; concession liabilities; pension obligations; and the treatment of publicly controlled entities near the general-government perimeter.
The correct question in each case is not “was Italy treated harshly?” but:
Was an economically equivalent transaction classified differently in another Member State, and if so, was that difference supported by ESA rules or Eurostat methodological guidance?
That is the level at which a government-grade claim of unequal statistical treatment becomes provable or falsifiable.
A second possible asymmetry lies in forecast assumptions
The EDP framework uses not only realised statistics but Commission forecasts and debt-sustainability projections. Consequently, consistency must also be tested in assumptions concerning potential growth, interest rates, inflation, output gaps, ageing costs, fiscal multipliers and projected primary balances.
A systematic bias in these assumptions could affect the adjustment demanded from a country even if the accounting data themselves were perfectly accurate.
However, demonstrating such bias requires the same forecast methodology to be reconstructed across states and tested ex post against realised outcomes; differences in forecasts alone are not evidence of political pressure because economic structures and policy assumptions differ.
A third possible asymmetry lies in access to flexibility
Defence and energy-security flexibility could become more politically sensitive than the 3% threshold itself because different national expenditure needs are increasingly shaped by security policy.
A robust audit must therefore record for every state:
| Flexibility variable | Evidence required |
|---|---|
| Date of national request | Government/Commission record |
| Amount of expenditure claimed | National fiscal plan |
| Commission assessment | Recommendation or analytical document |
| Council decision | Formal legal act |
| Baseline defence expenditure | Harmonised definition |
| Maximum deviation | Council-approved amount or formula |
| Duration | Legal activation period |
| Impact on net-expenditure compliance | Commission calculation |
| Impact on ESA deficit | Separate national-account treatment |
| Impact on Maastricht debt | Debt-accounting treatment |
Only after those variables are available can an allegation of selective flexibility be evaluated rigorously.
Net assessment of institutional consistency
The official record currently supports five firm conclusions.
First, the statistical architecture is formally common: EDP figures are governed by ESA methodology, Regulation 479/2009 quality requirements and Eurostat verification, while professional independence of national statistical institutes is protected by Regulation 223/2009.
Second, the corrective procedure has demonstrably been applied to multiple governments, including Italy, France, Belgium, Hungary, Poland, Slovakia, Romania, Austria, Finland and Bulgaria at different points between 2020 and 2026.
Third, Italy has not, on the present official record, been subjected to the most severe procedural response available: its June 2026 effective-action assessment resulted in the EDP being held in abeyance rather than escalated, whereas Romania received a formal no-effective-action finding.
Fourth, Eurostat had neither reserved nor amended Italy’s data in the April 2026 harmonised EDP notification, because no reservations or amendments were applied to Member State submissions in that notification.
Fifth, different deadlines and expenditure paths do exist, sometimes substantially, but the Council expressly describes these paths as country-specific and connected to national medium-term fiscal-structural plans; consequently, those differences require economic and procedural explanation before they can be treated as evidence of political discrimination.
Assessment of the deliberate-pressure proposition
On the official documentary record presently verified, the proposition that the Meloni government is being subjected to deliberate fiscal or statistical pressure designed to disadvantage it politically remains unproven.
The record demonstrates political conflict, stringent fiscal constraints and significant institutional consequences arising from statistical thresholds, but those facts are not equivalent to evidence of discriminatory intent.
A stronger conclusion would require at least one of the following:
| Evidence capable of materially changing the judgment | Why it would matter |
|---|---|
| A document showing political instruction to ISTAT or Eurostat concerning the Italian result | Direct evidence of interference with statistical independence |
| An Italy-specific ESA classification inconsistent with an economically identical transaction elsewhere | Evidence of methodological asymmetry |
| A rejected Italian request for fiscal flexibility approved for another materially equivalent state | Evidence potentially relevant to unequal application |
| A Commission or Council internal/external document demonstrating political rather than fiscal criteria influenced Italy’s treatment | Direct evidence concerning motive |
| A formal Eurostat reservation or amendment applying an Italy-specific standard | Evidence of a concrete statistical dispute |
| A country with materially equivalent deficit, debt path, expenditure compliance and forecast durability being allowed to exit an EDP while Italy is denied exit | Strong evidence requiring institutional explanation |
| A demonstrated systematic forecast bias against Italy across repeated surveillance cycles | Evidence of asymmetric analytical treatment, if methodology cannot explain it |
None of these categories should be inferred from newspaper characterisation, government criticism, opposition claims or the political consequences of the fiscal data themselves.
What would change the assessment
The October 2026 Eurostat EDP notification will be the first major test following the September ISTAT revision because Eurostat will either accept the revised Italian submission without qualification, attach a reservation, amend data or publish methodological information capable of altering the present assessment. The April precedent contained neither reservations nor amendments.
Any newly published Eurostat methodological correspondence concerning Italy’s 2025 deficit, tax-credit classification or GDP revision would materially improve the evidentiary record because it would allow the statistical dispute to be evaluated directly rather than through political commentary.
The next Commission assessment of effective action will also be decisive. A transition from the June position of abeyance to a formal finding of insufficient action would require examination of the exact fiscal deviation underlying that change.
Likewise, any Italian request for defence or energy-security flexibility and its subsequent treatment should be examined against the treatment of equivalent applications by other Member States.
Open official record
The following records remain capable of materially changing the institutional-pressure assessment and should therefore be considered priority collection targets:
ISTAT–Eurostat methodological correspondence concerning the September 2026 national-account revisions, including any discussion of GNI reservations, government-sector classifications, tax credits and deficit reconciliation.
Eurostat’s October 2026 Italian EDP notification tables and supplementary notes, including any reservations, amendments or methodological explanations.
Commission working material supporting Italy’s 2026 effective-action assessment, particularly the calculations of observed and projected net-expenditure growth.
The negotiation record underlying Italy’s 2026 EDP deadline and seven-year medium-term adjustment horizon, insofar as it becomes publicly available.
Country-specific Commission documentation for Belgium’s revised correction deadline, allowing a direct test of why its horizon was extended and whether comparable mechanisms were available to Italy.
National escape-clause requests and Commission/Council decisions for defence and energy-security expenditure, including any future Italian request.
Eurostat EDP inventories and methodological advice for economically comparable transactions in France, Germany, Spain, Belgium and other relevant states, particularly transactions capable of affecting deficit timing or the general-government perimeter.
The present documentary record therefore supports continued scrutiny but not a predetermined conclusion: the European fiscal system is demonstrably differentiated, yet the verified evidence currently shows common statistical rules, multiple active EDPs, formal procedural branching according to compliance and durability, and no documented official finding that Italy’s data were manipulated or that Italy was subjected to an exceptional statistical standard.
Institutional Consistency and the Political-Pressure Question
This dashboard separates the legal and statistical consistency test from the political-pressure hypothesis. The central question is not whether Italy faced demanding fiscal constraints, but whether the rules, methodologies, deadlines, effective-action assessments, flexibility mechanisms and closure standards were applied differently to Italy without a documented fiscal or legal justification.
Current documentary assessment
What constitutes a valid consistency test
| Test | Consistent treatment requires | Possible evidence of asymmetry | Current documentary position |
|---|---|---|---|
| Statistical definition | Common ESA 2010 concepts | Italy-specific definition of deficit, debt or sector perimeter | Common methodology |
| Data-quality assessment | Same tests of completeness, reliability and consistency | Italy subjected to a unique standard | No reservation identified |
| EDP opening | Same legal trigger applied to qualifying states | Equivalent breach ignored elsewhere without explanation | Multiple states opened |
| Correction deadline | Country-specific path linked to fiscal trajectory | Different deadline without documented economic basis | Requires case matching |
| Effective action | Same test of compliance with Council recommendation | Italy escalated despite compliant action | No escalation in Jun 2026 |
| EDP closure | Deficit correction must be successful and durable | Other state exits under weaker durability standard | No such case established |
| Fiscal flexibility | Article 26 criteria applied consistently | Equivalent Italian request refused selectively | No rejection identified |
Statistical independence safeguards
Eurostat formal intervention mechanisms
| Mechanism | Trigger | Institutional effect | April 2026 Italy status |
|---|---|---|---|
| Routine validation | Normal EDP transmission | Methodological and consistency review | Completed |
| Formal reservation | Eurostat doubts data quality | Public qualification of national statistics | None |
| Eurostat amendment | Evidence of non-compliant national figures | Eurostat substitutes amended data | None |
| Methodological visit | Material unresolved technical issue | Enhanced investigation of national compilation | Case-dependent |
| Misreporting investigation | Serious evidence of deliberate misreporting or severe negligence | Potential sanction process | No such finding identified |
EDP opening was applied across multiple states
| State | Deficit underlying action | EDP decision | Correction horizon |
|---|---|---|---|
| Belgium | 4.4% GDP in 2023 | Opened 26 Jul 2024 | Later revised to 2029 |
| France | 5.5% | Opened 26 Jul 2024 | 2029 |
| Hungary | 6.7% | Opened 26 Jul 2024 | 2026 |
| Italy | 7.4% | Opened 26 Jul 2024 | 2026 |
| Poland | 5.1% | Opened 26 Jul 2024 | 2028 |
| Slovakia | 4.9% | Opened 26 Jul 2024 | 2027 |
| Romania | Existing EDP | Procedure continued | Revised to 2030 |
Correction horizons and expenditure paths
| State | Correction deadline | 2025 net-expenditure ceiling | Subsequent path |
|---|---|---|---|
| Italy | 2026 | 1.3% | 1.6% in 2026 |
| France | 2029 | 0.8% | 1.2% in 2026–2028; 1.1% in 2029 |
| Poland | 2028 | 6.3% | 4.4%, 4.0%, 3.5% |
| Slovakia | 2027 | 3.8% | 0.9% in 2026; 1.6% in 2027 |
| Malta | 2027 initial | 6.0% | 5.8% in 2026–2027 |
Effective-action branches of the system
Statistical revisions are not unique to Italy
| State | Documented revision source | Institutional meaning |
|---|---|---|
| Belgium | Revision of VAT-refund timing | Accrual conventions can materially change historical deficit data. |
| Estonia | Timing of corporate-income-tax recording | Tax-timing rules can revise fiscal series. |
| Ireland | Updated source information and accrual adjustments | New information can revise previously published balances. |
| Greece | Updated information from an extrabudgetary government unit | Changes in source coverage can alter consolidated results. |
| Italy | Updated data and methodological changes in Sep 2026 | Must be assessed through the same statistical governance framework. |
Political-pressure proposition: evidence matrix
| Proposition | Evidence required | Verified record | Current status |
|---|---|---|---|
| ISTAT was induced to worsen Italy’s fiscal result | Instruction affecting methodology, timing, sources or publication | No such official record identified in the examined sources | Not established |
| Eurostat selectively altered Italian figures | Formal Italy-specific amendment | No amendments in April 2026 EDP notification | Not supported |
| Eurostat formally doubted Italian data | Reservation concerning Italy | No Member State reservation in April notification | Not supported |
| Italy was singled out for EDP entry | Equivalent qualifying states exempted without explanation | Multiple states entered procedures in 2024–2026 | Not established |
| Italy received a politically punitive deadline | Equivalent fiscal path treated more favourably without justification | Deadlines are formally country-specific | Requires deeper matching |
| Italy was escalated despite compliance | Negative effective-action decision despite compliance | Italy was held in abeyance in June 2026 | Contradicted by current record |
| Italy was denied flexibility selectively | Rejected request under conditions accepted elsewhere | No such rejection identified | Not established |
Closure standard: Malta and Italy at different procedural stages
| Closure element | Malta | Italy as of 23 Sep 2026 | Institutional consequence |
|---|---|---|---|
| Actual deficit below 3% | Satisfied | 2025 result remained 3.1% | Conditions not yet identical |
| Durability | Council concluded yes | Not yet established for closure | Forward assessment still material |
| Formal Council action | Procedure closed | No closure decision | Italy remains legally under EDP |
| Effective action | Consistent with closure | Recognised; EDP held in abeyance | Different procedural stages |
Where genuine asymmetry could still be identified
Evidence capable of changing the current judgment
| Potential evidence | Why it would matter |
|---|---|
| Political instruction to ISTAT or Eurostat concerning Italy’s fiscal result | Direct evidence of interference with statistical independence. |
| Italy-specific ESA classification inconsistent with equivalent treatment elsewhere | Potential evidence of methodological asymmetry. |
| Rejected Italian fiscal-flexibility request accepted for a materially equivalent state | Potential evidence of unequal institutional application. |
| Commission or Council communication explicitly linking Italy’s treatment to political considerations | Direct evidence concerning motive. |
| Formal Eurostat reservation or amendment using an Italy-specific standard | Documented statistical dispute requiring explanation. |
| Repeated and unexplained systematic forecast bias against Italy | Potential evidence of asymmetric analytical treatment. |
Immediate watchpoints
Institutional reading
Chapter 5 — Italy 2026–2030: Sustainability, Scenarios and Final Institutional Assessment
Principal judgment
Italy enters the 2026–2030 period with a fiscal configuration in which the central risk is no longer simply whether the annual deficit crosses the 3% of GDP reference value, but whether a sequence of primary surpluses, nominal economic growth and declining stock-flow adjustments becomes sufficiently strong to offset an interest bill that is increasing as older debt is progressively refinanced, while the temporary investment impulse supplied by the Recovery and Resilience Facility fades and expenditure pressures from pensions, healthcare, defence and population ageing become progressively more visible.
The latest fully comparable near-term institutional baselines do not yet produce a single unified 2026–2030 forecast. The Italian Government’s DFP 2026 currently projects a 2026 deficit of €68 billion, equal to 2.9% of GDP, public debt of 138.6% of GDP and real GDP growth of 0.6%, while the European Commission’s 21 May 2026 forecast projects real growth of 0.5% in 2026 and 0.6% in 2027, deficits of 2.9% in both years, and debt increasing from 137.1% of GDP in 2025 to 138.5% in 2026 and 139.2% in 2027.
The difference between those very similar 2026 debt estimates is not analytically important; what matters is that both official vintages show debt increasing even while the deficit moves below 3%, demonstrating that deficit correction and debt reduction are separate stages of Italy’s fiscal adjustment. The Commission attributes the increase to a debt-increasing interest-growth differential and large stock-flow adjustments linked especially to housing-renovation tax credits whose deficit effect was recorded in earlier years but whose cash impact continues to affect government debt.
The medium-term policy benchmark adopted before these newer developments remains the 2024 Italian Medium-Term Fiscal-Structural Plan, which envisaged debt falling to 136.4% in 2028, 134.9% in 2029 and 133.9% in 2030, accompanied by progressively stronger structural primary balances. Those numbers must now be treated as an earlier policy benchmark rather than as the current forecast, because the 2026 Commission baseline already places 2027 debt 1.7 percentage points above the 137.5% assumed in that plan.
The resulting 2026–2030 fiscal problem is therefore measurable: Italy must convert the currently projected peak in the debt ratio into a durable downward trajectory while absorbing the end of the exceptional RRF investment cycle, maintaining public investment, financing additional defence requirements, managing a debt stock whose residual maturity is approximately 7.9 years, and containing ageing-related spending pressures that are already projected to intensify during the 2030s.
The current official baseline does not show debt reduction beginning in 2026
The Italian Government’s DFP 2026 and the Commission’s Spring 2026 forecast agree on the key direction of travel for the immediate horizon even though their individual assumptions differ slightly: real growth remains weak, the headline deficit moves below 3%, and the debt ratio continues upward.
Latest verified near-term baseline
| Indicator | 2025 actual/latest statistical basis | 2026 official government baseline | 2026 Commission forecast | 2027 Commission forecast | Official source |
|---|---|---|---|---|---|
| Real GDP growth | Revised subsequently by ISTAT to 0.6% | 0.6% | 0.5% | 0.6% | DFP 2026 headline indicators and Commission Spring Forecast. |
| Inflation | — | — | 3.2% | 1.8% | European Commission. |
| Unemployment | — | — | 5.7% | 5.7% | European Commission. |
| General-government balance | −3.1% GDP | −2.9% | −2.9% | −2.9% | OpenBDAP / Commission. |
| 2026 nominal deficit | — | €68 bn | — | — | Ragioneria Generale dello Stato, DFP 2026 macro indicators. |
| Gross debt | 137.1% GDP under Commission/Eurostat vintage | 138.6% | 138.5% | 139.2% | OpenBDAP / Commission. |
| Current-account balance | 1.2% GDP | — | 0.5% | 0.6% | European Commission. |
The important feature is not the 0.1-percentage-point difference between the Government and Commission debt estimates for 2026 but their common conclusion that the ratio is still rising. A government can therefore satisfy the immediate EDP objective of bringing the deficit below 3% while still failing to reduce the debt ratio in the same year, because the debt stock responds to interest costs, nominal GDP growth, primary balances and stock-flow adjustments rather than solely to the headline deficit.
The debt equation: four variables determine whether the ratio falls
For government-level analysis, the medium-term debt trajectory can be reduced to four economic mechanisms: the inherited debt stock; the effective interest cost on that stock; nominal GDP growth; the primary fiscal balance; and, in accounting terms, the additional stock-flow adjustments that reconcile the deficit with the change in gross debt.
The Commission’s 2026 assessment identifies exactly this combination: primary surpluses reduce the debt ratio, but the effect is currently outweighed by an unfavourable interest-growth differential and large stock-flow adjustments associated particularly with housing-renovation tax credits.
Debt-ratio transmission mechanism
| Variable | Debt effect if it increases | Italy 2026–2030 relevance | Official evidence |
|---|---|---|---|
| Nominal GDP growth | Normally reduces debt/GDP by enlarging denominator | Critical because real growth remains around 0.5–0.6% in current near-term forecasts | Commission projects only 0.5% real growth in 2026 and 0.6% in 2027. |
| Effective interest burden | Raises deficit and debt accumulation | Increasing as debt reprices and inflation-linked securities respond to inflation | Commission expects interest expenditure to rise by 0.3 pp of GDP in 2026, citing higher yields, particularly inflation-linked bonds. |
| Primary surplus | Reduces borrowing needs and debt | Must strengthen sufficiently to dominate interest-growth and SFA effects | Earlier MEF medium-term plan envisaged progressively increasing primary surpluses. |
| Stock-flow adjustment | Can raise debt independently of current deficit | Major near-term Italian factor because tax-credit cash effects continue after deficit recognition | Commission explicitly identifies housing-tax-credit SFAs as a major debt-increasing factor. |
| Treasury liquidity and financial transactions | Can increase or reduce gross debt without identical deficit movement | Material for yearly debt reconciliation | Banca d’Italia identified Treasury-liquidity accumulation and valuation factors as significant components of the 2025 debt increase. |
This decomposition is also the reason the fiscal discussion becomes substantially more demanding after EDP correction: once the annual deficit falls below 3%, the decisive question becomes whether the combination of primary balance and nominal growth is sufficiently strong to overcome financing costs and residual stock-flow effects.
Interest expenditure becomes a more important constraint after 2026
The Commission forecasts that Italian interest expenditure will increase by approximately 0.3 percentage points of GDP in 2026, with higher yields and inflation-linked bonds specifically identified as contributors.
The pass-through of higher market yields is gradual rather than instantaneous because Italy does not refinance its €3 trillion-plus debt stock in one year. Banca d’Italia calculated an average residual maturity of 7.9 years at end-2025, essentially unchanged from the previous year, meaning that changes in market funding costs propagate through the effective interest burden over several fiscal years as existing securities mature and are replaced.
This maturity structure provides protection against abrupt repricing but does not eliminate the cumulative effect. If securities issued during the low-rate period mature and are refinanced at higher coupons, the interest bill rises progressively even if market rates no longer increase.
Refinancing transmission
| Channel | Current verified condition | Medium-term implication | Source |
|---|---|---|---|
| Average residual debt maturity | 7.9 years at end-2025 | Interest-rate shocks transmit gradually rather than immediately | Banca d’Italia. |
| Banca d’Italia share of public debt | Fell to 18.5% at end-2025, from 21.6% | A larger share of financing must be absorbed outside Banca d’Italia as Eurosystem portfolios decline | Banca d’Italia. |
| Interest expenditure | Commission expects +0.3 pp GDP in 2026 | Makes primary-surplus improvement less visible in the headline balance | European Commission. |
| Inflation-linked securities | Identified as a source of higher 2026 interest spending | Higher inflation directly affects part of debt service | European Commission. |
| Treasury liquidity | €52.4 bn at end-2025 following a €14.7 bn increase | Provides financing buffer but contributed to gross debt accumulation | Banca d’Italia. |
The fiscal risk is therefore not best described as an imminent refinancing cliff; it is a progressive repricing problem, in which the effective cost of the debt stock can continue rising after market rates peak because the sovereign portfolio adjusts with a lag.
The earlier official medium-term plan assumed a substantial strengthening of the primary balance
Italy’s 2024 Medium-Term Fiscal-Structural Plan provides the clearest published official medium-term policy architecture extending through 2030, even though its numerical baseline predates the subsequent 2025 outturn and 2026 forecast revisions.
That plan envisaged the primary balance moving from roughly balance in 2024 to a progressively larger surplus, while the headline deficit declined and the debt ratio eventually turned downward.
Earlier MEF policy benchmark
| Indicator | 2025 | 2026 | 2027 | 2028 | 2029 | 2030 | Status/source |
|---|---|---|---|---|---|---|---|
| General-government balance | −3.3% | −2.8% | −2.6% | −2.3% | −1.8% | −1.7% | Medium-Term Fiscal-Structural Plan; older policy vintage. |
| Structural primary balance | 0.0% | 0.6% | 1.1% | 1.6% | 2.2% | 2.7% | MEF medium-term plan. |
| Gross debt | 136.9% | 137.8% | 137.5% | 136.4% | 134.9% | 133.9% | MEF medium-term plan. |
These figures must not be presented as the September 2026 forecast. The significance of the table is analytical: it shows what fiscal architecture was originally judged necessary to place debt on a downward trajectory.
The plan required the structural primary balance to improve from roughly zero in 2025 to 2.7% of potential GDP by 2030.
The trajectory therefore depended on sustained fiscal discipline continuing well after the EDP threshold had been crossed.
The current near-term baseline is weaker than the original debt path
The Commission’s May 2026 forecast places public debt at 139.2% of GDP in 2027, whereas the 2024 Italian plan had projected 137.5% for the same year.
The gap is approximately 1.7 percentage points of GDP.
That difference should not be interpreted automatically as failure of the entire medium-term strategy because the statistical base, nominal GDP, tax-credit costs, interest rates and macroeconomic environment have all changed since the original plan. It does mean, however, that the original 2028–2030 debt numbers cannot now be used as though they were unchanged current forecasts.
Current-vintage versus original policy path
| Year | Original MEF debt benchmark | Latest Commission baseline where available | Difference | Interpretation |
|---|---|---|---|---|
| 2026 | 137.8% | 138.5% | +0.7 pp | Debt path currently above original benchmark. |
| 2027 | 137.5% | 139.2% | +1.7 pp | Near-term debt peak shifted upward. |
| 2028 | 136.4% | No current Commission figure in May 2026 forecast | — | Original figure remains a policy benchmark, not current forecast. |
| 2029 | 134.9% | No current Commission figure in May 2026 forecast | — | Same limitation. |
| 2030 | 133.9% | No current Commission figure in May 2026 forecast | — | Same limitation. |
This creates a clear policy test for the next fiscal-planning round: the Government must either recover the lost debt-ratio ground through stronger primary balances, stronger nominal growth, smaller stock-flow adjustments or lower financing costs, or publish a revised medium-term debt path.
A mechanical re-basing exercise shows why the 2027 slippage matters
A useful deterministic sensitivity can be constructed without inventing a forecast.
The earlier MEF path implied debt-ratio declines of approximately 1.1 percentage points between 2027 and 2028, 1.5 points between 2028 and 2029 and 1.0 point between 2029 and 2030.
If those exact subsequent annual improvements were achieved but started from the Commission’s newer 139.2% 2027 level instead of the original 137.5%, the mechanical path would be approximately 138.1% in 2028, 136.6% in 2029 and 135.6% in 2030.
Re-based debt arithmetic — not an official forecast
| Year | Original MEF benchmark | Mechanical re-base from 139.2% in 2027 | Difference | Method |
|---|---|---|---|---|
| 2027 | 137.5% | 139.2% | +1.7 pp | Current Commission forecast used as new starting level. |
| 2028 | 136.4% | 138.1% | +1.7 pp | Apply original −1.1 pp annual change |
| 2029 | 134.9% | 136.6% | +1.7 pp | Apply original −1.5 pp annual change |
| 2030 | 133.9% | 135.6% | +1.7 pp | Apply original −1.0 pp annual change |
This calculation is not a forecast and makes no assumption that the original annual improvements will actually occur. Its purpose is to demonstrate a simple fiscal property: if the level of debt begins the declining phase materially above the original policy baseline, achieving the same subsequent rate of debt reduction does not by itself restore the original end-point.
Nominal growth is as important as fiscal adjustment
Italy’s debt ratio is particularly sensitive to the denominator because gross debt is already close to 140% of annual GDP.
The mechanical effect can be shown without imposing a macroeconomic forecast.
If a country has debt equal to 139.2% of GDP and the nominal debt stock is unchanged, a nominal GDP denominator that is 1% smaller than otherwise assumed mechanically increases the ratio to approximately 140.6%; a denominator 2% smaller raises it to approximately 142.0%.
Pure denominator sensitivity at a 139.2% starting debt ratio
| Nominal-GDP deviation from assumed level | Debt stock assumption | Mechanical debt/GDP ratio | Change |
|---|---|---|---|
| Baseline | Debt unchanged | 139.2% | — |
| GDP 1% lower | Debt unchanged | ≈140.6% | ≈+1.4 pp |
| GDP 2% lower | Debt unchanged | ≈142.0% | ≈+2.8 pp |
| GDP 1% higher | Debt unchanged | ≈137.8% | ≈−1.4 pp |
These are simple arithmetic sensitivities, not predictions. They illustrate why productivity, labour-force participation and investment performance have direct fiscal importance even when no tax or spending rule changes.
The RRF creates both a 2026 investment peak and a post-2026 transition risk
Italy’s amended Recovery and Resilience Plan has estimated total costs of approximately €194.416 billion, comprising about €71.780 billion of non-repayable EU financial support and €122.602 billion in loan support.
The scale of the programme is therefore macroeconomically material.
The Commission’s latest forecast states that investment supported by the Recovery and Resilience Plan remains an important driver of 2026 economic activity, with public investment expenditure reaching 3.8% of GDP in the recent baseline, while the phase-out of RRF-related projects in 2027 is expected to lower capital expenditure.
The policy issue after 2026 is consequently not only whether Italy completes projects on time, but whether domestic and other EU investment programmes prevent a sharp decline in capital formation when the exceptional RRF cycle ends.
RRF transition
| Variable | Verified position | 2026–2030 significance | Official source |
|---|---|---|---|
| Amended Italian RRP estimated cost | €194.416 bn | Exceptionally large temporary investment/reform programme | European Commission. |
| Non-repayable support | €71.780 bn | Does not create the same repayment profile as RRF loans | European Commission. |
| Loan support | €122.602 bn | Adds a long-term financing component to the programme | European Commission. |
| Implementation horizon | Commitments concentrated through 2026 | Execution delays can reduce realised investment impulse | European Commission has repeatedly stressed completion within the RRF implementation window. |
| 2026 macro effect | Investment still materially supported by RRF | Supports real activity during weak external environment | Commission Spring Forecast. |
| 2027 transition | RRF-related capital expenditure falls | Risk of an investment cliff if national/EU replacement spending is insufficient | Commission Spring Forecast. |
The public-finance implication is significant because replacing RRF-financed investment with nationally financed expenditure would require additional fiscal space, while allowing investment to fall sharply could weaken potential growth and thereby worsen the debt denominator over time.
Post-PNRR investment becomes a debt-sustainability variable
The post-2026 problem is therefore not simply expenditure replacement.
Productive public investment affects debt sustainability through at least three channels: it increases near-term spending; it can raise medium-term potential output; and, if financed domestically rather than through EU grants, it can increase borrowing needs before any growth effect materialises.
This produces a timing problem. Cutting investment can improve short-term deficit arithmetic but potentially weaken medium-term nominal GDP; preserving investment can create immediate financing pressure while supporting the denominator later.
The new EU fiscal framework partly acknowledges this trade-off by excluding nationally financed co-financing of EU programmes from the net-expenditure indicator and by allowing longer adjustment paths for countries committing to qualifying reforms and investment. The Italian seven-year path was approved within precisely that framework.
Defence is emerging as a second major medium-term expenditure pressure
Italy’s 2026 ordinary Defence budget amounts to approximately €32.416 billion, an increase of about €1.117 billion from 2025, according to the Ministry of Defence’s 2026 outlook.
Within the formal State budget, Mission 5 — Defence and territorial security carries approximately €30.515 billion in 2026 appropriations, distributed across the Carabinieri, land forces, naval forces, air forces, joint commands, planning and procurement programmes.
These budget concepts are not identical to the NATO definition of defence expenditure and must not be treated as interchangeable.
At the 2025 Hague Summit, NATO Allies adopted a longer-term commitment to invest 5% of GDP annually by 2035, composed of at least 3.5% for core defence requirements and up to 1.5% for broader defence- and security-related investment.
Defence-related fiscal architecture
| Variable | Verified figure/status | Fiscal interpretation | Source |
|---|---|---|---|
| Italian ordinary Defence budget 2026 | €32.416 bn | Ministry budget concept | Italian Ministry of Defence. |
| Mission 5 appropriations 2026 | €30.515 bn | State-budget mission concept | Ministry of Defence budget tables. |
| NATO 2035 commitment | 5% GDP | Alliance-wide long-term commitment, not Italy’s 2026 budget figure | NATO. |
| Core defence component | ≥3.5% GDP by 2035 | Military requirements and NATO capability targets | NATO. |
| Broader security component | up to 1.5% GDP | Security-related infrastructure/resilience investment under NATO commitment | NATO. |
The fiscal implication through 2030 is real but cannot yet be converted into a single additional annual Italian spending amount without an official national path specifying how Italy intends to move toward the 2035 commitment.
Any estimate that simply multiplies 5% by current Italian GDP would therefore be analytically misleading because the NATO commitment is phased, encompasses multiple categories and extends to 2035.
Demographic pressure is already visible before 2030
ISTAT’s August 2026 population projections provide an updated demographic baseline that is materially relevant to fiscal sustainability.
Under the median scenario, Italy’s resident population declines from 58.9 million at the beginning of 2025 to 58.7 million in 2030, with the decline accelerating thereafter to 55.0 million in 2050 and 45.8 million in 2080. The population aged 85 and over rises from 4.1% in 2025 to 4.4% in 2030, while the working-age population is projected to contract.
Net foreign migration remains positive but falls from approximately 296,000 in 2025 to 247,000 in 2030 under the median scenario, while the natural balance remains deeply negative, moving from roughly −296,000 in 2025 to −353,000 in 2030.
Demographic indicators relevant to the 2030 fiscal horizon
| Indicator | 2025 | 2030 | Fiscal mechanism | Official source |
|---|---|---|---|---|
| Resident population | 58.9m | 58.7m | Smaller denominator for labour supply and tax base | ISTAT 2026 demographic projection. |
| Natural population balance | approx. −296k | approx. −353k | Persistent excess of deaths over births | ISTAT. |
| Immigration from abroad | approx. 432k | approx. 423k | Supports labour-force and population levels | ISTAT. |
| Emigration abroad | approx. 144k | approx. 176k | Reduces net labour/population contribution | ISTAT. |
| Net foreign migration | approx. +296k | approx. +247k | Partially offsets natural decline | ISTAT. |
| Population aged 85+ | 4.1% | 4.4% | Raises health and long-term-care requirements | ISTAT. |
The fiscal significance lies less in the small decline in total population by 2030 than in the age composition: fewer working-age residents relative to older cohorts make the financing of pensions, healthcare and long-term care progressively more dependent on participation rates, productivity and immigration.
Pensions become more expensive before the longer-term reforms reduce pressure
The European Commission’s 2024 Ageing Report, whose Italian pension projections were prepared with the Italian Ministry of Economy and Finance and peer-reviewed within the EU Ageing Working Group, projects gross public pension expenditure rising from 15.6% of GDP in 2022 to 16.6% in 2030, before reaching 17.1% in 2040 and peaking at approximately 17.3% in 2036.
The report attributes the initial increase principally to the retirement of the baby-boom cohorts, while later reductions reflect the progressively larger role of the notional defined-contribution system, changes in eligibility conditions and participation effects.
Pension-system pressure
| Indicator | 2022 | 2030 | Peak / later position | Source |
|---|---|---|---|---|
| Gross public pension expenditure | 15.6% GDP | 16.6% | 17.3% peak in 2036 | Commission/EPC Ageing Report Italy fiche. |
| Net public pension expenditure | 12.6% GDP | 13.5% | 14.0% peak in 2036 | Commission/EPC. |
| Public pension contributions | 10.9% GDP | 11.2% | around 11% thereafter | Commission/EPC. |
| Pension-system balance | −4.7% GDP | −5.5% | Most negative around −6.0% in 2036 | Commission/EPC. |
These projections are not a 2026 forecast and use a long-term unchanged-policy framework finalised earlier, but they identify the structural direction of demographic expenditure pressure relevant to the 2030 horizon.
The fiscal challenge is therefore front-loaded: the reforms embedded in the pension system improve sustainability later, but the retirement of large cohorts increases expenditure before those long-run stabilising mechanisms dominate.
The working-age population is the other side of the pension equation
Pension sustainability cannot be evaluated solely from benefit expenditure because contribution revenue depends on employment, participation, wage growth and productivity.
ISTAT’s 2026 projections explicitly identify the expected contraction of the 15–64 population as one of the most consequential demographic developments for economic growth, pension sustainability, labour supply and the capacity to fund increasing care demand.
The Ageing Report similarly projects rising participation rates among older workers, partly reflecting retirement-age and eligibility rules, which partially offset adverse demographic dependency.
The medium-term fiscal implication is therefore that employment-policy effectiveness becomes debt policy: stronger labour participation and productivity increase tax and social-contribution revenue and raise the GDP denominator without requiring higher statutory tax rates.
Stock-flow adjustments remain the most important accounting risk to a clean debt decline
The Commission identifies stock-flow adjustments associated with past housing-renovation tax credits as one of the principal reasons debt continues rising through 2027 despite primary surpluses.
The earlier Italian medium-term plan had already anticipated unusually large stock-flow contributions in the first years of the adjustment, reflecting the cash effects of tax credits and other financial transactions.
Why stock-flow adjustment matters
| Fiscal event | Effect on current deficit | Effect on current debt | Medium-term consequence |
|---|---|---|---|
| Expenditure recognised earlier under accrual accounting | Already affected historical deficit | Cash settlement can occur later | Debt can rise even after headline deficit improves |
| Tax credits accumulated in previous years | Fiscal cost partly recognised previously | Future cash utilisation reduces revenue / increases financing need | Delays debt-ratio decline |
| Increase in Treasury cash buffers | No equivalent deficit increase required | Gross debt rises | Creates liquidity protection but increases gross debt |
| Privatisation / asset disposal | Can reduce financing needs without improving structural primary balance | Can lower debt stock | One-off debt relief, not recurring fiscal adjustment |
| Valuation / indexation effects | Limited or different deficit timing | Can directly change nominal debt | Important for inflation-linked securities |
This is the main reason an assessment based solely on the annual deficit would systematically understate the near-term difficulty of reducing Italy’s debt ratio.
Transparent 2026–2030 scenarios
The scenarios below are not probability forecasts and do not assign subjective likelihoods. They are deterministic fiscal paths constructed from official benchmarks to identify the conditions under which the debt trajectory changes.
Scenario A — original policy benchmark
The first scenario reproduces the official debt path in the 2024 Medium-Term Fiscal-Structural Plan, with no modification.
| Year | Debt/GDP | Fiscal balance | Structural primary balance | Source |
|---|---|---|---|---|
| 2026 | 137.8% | −2.8% | +0.6% | MEF medium-term plan. |
| 2027 | 137.5% | −2.6% | +1.1% | MEF. |
| 2028 | 136.4% | −2.3% | +1.6% | MEF. |
| 2029 | 134.9% | −1.8% | +2.2% | MEF. |
| 2030 | 133.9% | −1.7% | +2.7% | MEF. |
Interpretation: this is no longer the latest short-term forecast because the current 2026–27 debt baseline is higher, but it remains the clearest official representation of the fiscal adjustment originally considered sufficient to restore a declining debt path.
Scenario B — mechanically re-based adjustment
The second scenario accepts the Commission’s newer 139.2% 2027 debt ratio and assumes, purely for sensitivity purposes, that Italy subsequently achieves exactly the same annual debt-ratio improvements planned in the old MEF path.
| Year | Debt/GDP | Calculation |
|---|---|---|
| 2027 | 139.2% | Commission current near-term baseline. |
| 2028 | 138.1% | 139.2 − original planned 1.1 pp decline |
| 2029 | 136.6% | 138.1 − original planned 1.5 pp decline |
| 2030 | 135.6% | 136.6 − original planned 1.0 pp decline |
Interpretation: even if the originally planned annual rate of debt reduction is fully achieved after 2027, the end-2030 ratio remains approximately 1.7 percentage points above the old policy benchmark because the starting level is higher.
Scenario C — primary-balance underperformance sensitivity
A deterioration in the primary balance has a near-direct first-year debt effect. Holding all other variables constant, a primary balance 1 percentage point of GDP weaker than planned adds approximately one percentage point to debt/GDP in the first year before interest and growth feedbacks; if repeated, the effect compounds.
| Primary-balance deviation | First-year approximate debt effect | Three-year cumulative arithmetic before feedback |
|---|---|---|
| 0.0 pp | 0 | 0 |
| −0.5 pp GDP | +0.5 pp | approximately +1.5 pp if repeated annually |
| −1.0 pp GDP | +1.0 pp | approximately +3.0 pp if repeated annually |
| +0.5 pp GDP | −0.5 pp | approximately −1.5 pp if sustained |
This is accounting sensitivity rather than a macroeconomic forecast; actual outcomes would differ because the fiscal stance also affects growth, interest costs and tax revenue.
Scenario D — nominal-GDP underperformance
At a starting debt ratio near 139%, even relatively small denominator changes produce material movements.
| Nominal GDP relative to baseline | Mechanical effect on a 139.2% debt ratio |
|---|---|
| +2% | approximately 136.5% |
| +1% | approximately 137.8% |
| Baseline | 139.2% |
| −1% | approximately 140.6% |
| −2% | approximately 142.0% |
This explains why a medium-term strategy relying only on expenditure restraint without raising productivity, labour supply and investment performance would be incomplete.
The decisive 2030 fiscal thresholds are observable
The path to 2030 does not require speculative probabilities because the conditions separating a stabilising from a non-stabilising debt trajectory can be monitored directly.
Fiscal signposts
| Indicator | Stabilising signal | Adverse signal | Why it matters |
|---|---|---|---|
| General-government deficit | Remains sustainably below 3% GDP | Returns above 3% outside permitted flexibility | Determines durability of EDP correction |
| Primary balance | Moves progressively toward the medium-term surplus path | Stagnates near zero or falls back into deficit | Determines capacity to offset interest expenditure |
| Debt/GDP | Peaks and begins multi-year decline | Continues rising after 2027 | Core sustainability outcome |
| Interest expenditure/GDP | Stabilises | Continues increasing materially | Absorbs primary surplus |
| Nominal GDP | Grows sufficiently to offset interest dynamics | Weak real growth plus low deflator | Reduces denominator contribution |
| Stock-flow adjustment | Falls sharply after tax-credit effects fade | Remains persistently debt-increasing | Can neutralise primary surpluses |
| Public investment | Remains elevated after RRF expiry | Falls sharply after 2026 | Affects potential growth |
| Defence expenditure | Integrated into fiscal path with identified financing | Added without corresponding fiscal adjustment | Raises medium-term spending burden |
| Working-age participation | Continues improving | Labour supply contracts faster than productivity rises | Determines revenue base |
| Pension expenditure | Remains within long-term reform profile | New permanent measures materially raise pre-2036 expenditure | Alters structural primary balance |
The post-2026 investment question is central to sustainability
Italy’s fiscal sustainability cannot be achieved through accounting consolidation alone because the country requires sufficient medium-term nominal GDP growth to bring down a debt stock close to 140% of GDP.
The Commission’s forecast already signals the transition: RRF investment supports activity in 2026, while its phase-out depresses capital expenditure from 2027.
The correct policy question is therefore not whether investment should simply remain at its RRF peak, which would be fiscally unrealistic, but whether the composition of national and EU expenditure after 2026 preserves projects with sufficient productivity, infrastructure, digitalisation and human-capital effects to support potential growth.
Defence and ageing compete for the same structural fiscal space
The 2026–2030 horizon introduces a fiscal interaction that was considerably less important when the original Italian medium-term plan was written.
On one side, defence requirements are structurally increasing under the NATO 2035 framework and through national capability programmes.
On the other, pension expenditure is projected to increase toward 16.6% of GDP in 2030 and to continue rising into the following decade as the baby-boom generation retires.
The two expenditure categories therefore create simultaneous claims on fiscal resources while Italy is also required to preserve primary surpluses and productive investment.
This makes the composition of fiscal adjustment strategically more important than the aggregate headline deficit.
A higher tax burden cannot indefinitely substitute for growth
The previous fiscal chapters established the significant role played by stronger revenues in recent deficit improvement. The forward sustainability problem is different.
If additional consolidation is achieved predominantly through higher revenue extraction while productivity and labour participation remain weak, the fiscal system can improve the primary balance in the short run but weaken the denominator and private investment channels on which debt reduction also depends.
Conversely, unfunded tax reductions can improve disposable income but worsen the primary balance.
The relevant 2026–2030 policy test is therefore not whether taxes are categorically raised or lowered, but whether permanent revenue measures are consistent with the expenditure path and with growth sufficient to stabilise debt.
Final institutional assessment
The verified record supports a more precise conclusion than either fiscal alarmism or claims that the 3% deficit correction has resolved Italy’s public-finance problem.
Italy is approaching a procedural turning point rather than the end of fiscal adjustment.
The Government’s current 2026 baseline places the deficit at 2.9% of GDP, while the Commission forecasts the same value for both 2026 and 2027.
If realised and judged durable, that trajectory addresses the immediate excessive-deficit problem.
It does not by itself resolve debt sustainability.
The Commission’s current forecast places the debt ratio at 139.2% in 2027, above both its 2025 level and the trajectory embedded in the original Italian medium-term plan.
The debt therefore becomes the dominant fiscal variable after the deficit correction.
The original medium-term plan demonstrates the scale of the adjustment implied by that objective: the structural primary balance was expected to rise to 2.7% of potential GDP by 2030, while debt was intended to decline toward 133.9% of GDP.
Current near-term data have made that endpoint more demanding.
At the same time, Italy enters this adjustment period with several supportive structural features: a long average residual debt maturity limits immediate repricing, the primary balance has returned to surplus, employment conditions have been relatively resilient, and the RRF has generated a large investment pipeline.
The countervailing forces are equally concrete: interest expenditure is increasing, the debt ratio is not yet declining, the RRF investment impulse is approaching its termination phase, pension expenditure rises toward 2030, the working-age population is contracting, and defence expenditure requirements are increasing.
The resulting fiscal assessment is therefore conditional rather than ideological: Italy’s debt is sustainable over the medium term only if the post-EDP adjustment produces persistent primary surpluses, nominal GDP grows sufficiently, the temporary stock-flow effects associated with past tax credits diminish as expected, interest-cost increases remain manageable, and the end of the RRF does not generate a lasting collapse in productive public investment.
Failure in one variable is not necessarily decisive because another can offset it; simultaneous underperformance in growth, primary balance and financing cost would be materially more serious because all three operate directly on the debt equation.
Decision-useful 2026–2030 monitoring matrix
| Domain | 2026 verified/official starting point | 2030 requirement or pressure | Assessment criterion | Source |
|---|---|---|---|---|
| Headline deficit | 2.9% GDP government forecast | Must remain durably controlled | No renewed excessive-deficit condition | |
| Debt | 138.6% government forecast / 138.5% Commission | Original plan benchmark 133.9%, now more difficult | Clear multi-year decline after peak | |
| Real growth | 0.5–0.6% institutional forecasts | Needs stronger medium-term productivity contribution | Avoid denominator stagnation | |
| Interest expenditure | Rising by ~0.3 pp GDP in 2026 in Commission forecast | Must stabilise relative to GDP | Prevent interest from absorbing larger primary surplus | |
| Debt maturity | 7.9 years end-2025 | Gradual refinancing through horizon | Manage repricing and redemption concentration | |
| RRF | €194.4 bn amended plan | Temporary instrument ends as investment driver | Replace high-quality investment rather than entire gross envelope | |
| Defence | €32.4 bn ordinary 2026 Defence budget | NATO 2035 spending commitment increases medium-term pressure | Financing path must be integrated with fiscal plan | |
| Population | 58.9m in 2025 | 58.7m projected 2030 | Labour participation/productivity must offset demographic contraction | |
| Pension spending | 15.6% GDP in 2022 Ageing baseline | 16.6% projected 2030 | Prevent permanent policy changes from worsening ageing trajectory | |
| Stock-flow adjustments | Large debt-increasing near-term effects | Expected to recede | Debt change should progressively converge toward fiscal balance dynamics |
What would materially improve the 2030 outlook
A sustained increase in productivity and labour participation would simultaneously improve tax revenue, pension contributions and nominal GDP without requiring an equivalent increase in statutory tax rates.
A faster disappearance of housing-tax-credit stock-flow effects would allow primary surpluses to translate more directly into debt reduction.
A sustained reduction in sovereign refinancing yields would gradually lower the effective interest rate as debt matures, although the long maturity structure means the benefit would also be delayed.
Successful completion of RRF reforms and investment, followed by effective use of cohesion-policy and national capital expenditure, would reduce the probability that the end of the RRF becomes a permanent investment shock.
A defence-spending path financed through reprioritisation, common European instruments or measures compatible with the fiscal framework would reduce pressure on the structural primary balance relative to an entirely additional nationally financed expenditure path.
What would materially weaken the 2030 outlook
A persistent real-growth rate around or below the current 0.5–0.6% near-term forecast, combined with falling inflation and continued interest expenditure growth, would worsen the interest-growth differential identified by the Commission.
A primary surplus materially below the path required by the medium-term framework would prevent debt from entering the planned declining trajectory even after stock-flow adjustments fade.
Permanent expenditure commitments introduced without permanent financing would become progressively more difficult to absorb because pension and defence expenditure are already moving upward.
A failure to replace the productive component of the RRF investment cycle after 2026 would weaken both near-term demand and medium-term potential output.
A larger-than-projected fall in the working-age population or weaker labour-force participation would reduce the contribution base while ageing-related expenditure continues to rise.
Final net assessment
The most defensible institutional assessment through the 2030 horizon is that Italy’s fiscal position is entering a more demanding phase rather than a less demanding one.
The first phase of adjustment was dominated by bringing an exceptionally large post-pandemic deficit back toward the Treaty reference value.
The second phase requires something structurally harder: reducing one of Europe’s largest sovereign-debt stocks while simultaneously financing an ageing welfare state, higher defence requirements and sufficient public investment to raise potential growth.
The official baselines show that deficit correction can occur before debt reduction, and current forecasts indicate precisely that sequence for 2026–2027.
The fiscal outcome by 2030 will therefore be determined less by the symbolic decimal around the 3% threshold than by whether Italy can maintain a primary surplus large enough to offset the effective interest burden while preserving nominal growth.
The earlier MEF benchmark of 133.9% debt/GDP in 2030 remains analytically useful as a policy reference but should no longer be represented as the latest forecast; the current 2027 starting point is already materially higher than the path from which that number was generated.
A mechanically re-based continuation of the original pace of debt reduction would instead leave debt at approximately 135.6% in 2030, illustrating how difficult it is to recover a higher starting level even when subsequent annual adjustment remains unchanged.
The demographic record adds a structural constraint that fiscal accounting alone cannot remove: population ageing will increase pension expenditure toward the mid-2030s while the working-age population contracts, making productivity, employment and participation central components of sovereign-debt sustainability rather than merely labour-market objectives.
The investment transition is equally consequential. Italy has benefited from an exceptional RRF programme approaching €194.4 billion, but that programme is temporary; fiscal sustainability after 2026 therefore depends not on permanently reproducing its spending volume but on converting completed infrastructure, digitalisation, administrative reforms and private investment into higher potential output.
Finally, the defence environment adds an expenditure obligation that was not incorporated at its present scale when much of the earlier medium-term fiscal architecture was designed. NATO’s 2035 commitment and Italy’s growing defence appropriations will have to be reconciled explicitly with the primary-balance path rather than treated as an accounting issue outside fiscal sustainability.
The 2026–2030 institutional test is consequently clear and measurable: a credible Italian fiscal path requires the deficit to remain durably below the excessive-deficit threshold, the primary surplus to strengthen, debt to peak and then decline, stock-flow adjustments to normalise, interest expenditure to stabilise relative to GDP, public investment to survive the end of the RRF cycle, and demographic and defence commitments to be incorporated transparently into the medium-term budget rather than deferred outside it.
Open official record
The most consequential missing record is the next fully updated Italian medium-term fiscal trajectory incorporating the September 2026 national-account revision, because the original 2024 plan and the current 2026–2027 Commission forecast now operate from different debt and GDP baselines.
The October 2026 Eurostat EDP notification will provide the next harmonised European fiscal vintage and can alter the denominator and debt ratios used for forward analysis.
The next Italian budgetary document must clarify whether the Government still targets a debt trajectory broadly converging toward the original 2030 benchmark or whether the higher 2026–2027 baseline requires a revised debt path.
The updated national implementation path for the NATO 2035 commitment is required before the defence burden can be converted into a defensible 2027–2030 annual fiscal series.
The final RRF implementation record is required to determine the actual investment carried into the post-2026 economy and to distinguish completed productive capital from delayed or cancelled expenditure.
Updated pension, health and long-term-care projections incorporating the latest ISTAT demographic baseline will be necessary to replace the older Ageing Report assumptions when the next official ageing exercise becomes available.
The decisive government-level question for 2030 is therefore no longer whether Italy can temporarily cross below a numerical deficit threshold; it is whether the country can turn fiscal correction into sustained debt reduction without undermining the productive capacity required to finance the adjustment itself.
From Deficit Correction to Debt Reduction
The key 2026–2030 question is no longer only whether Italy remains below the 3% deficit reference value. The decisive issue is whether primary surpluses, nominal growth and declining stock-flow adjustments become strong enough to offset rising interest expenditure, post-RRF investment pressures, defence commitments and demographic costs.
Near-term official baseline
The debt equation
Refinancing and interest-rate transmission
Original medium-term policy benchmark
| Year | General-government balance | Structural primary balance | Gross debt / GDP |
|---|---|---|---|
| 2025 | −3.3% | 0.0% | 136.9% |
| 2026 | −2.8% | +0.6% | 137.8% |
| 2027 | −2.6% | +1.1% | 137.5% |
| 2028 | −2.3% | +1.6% | 136.4% |
| 2029 | −1.8% | +2.2% | 134.9% |
| 2030 | −1.7% | +2.7% | 133.9% |
Current baseline versus original debt path
| Year | Original MEF benchmark | Latest Commission figure | Gap | Interpretation |
|---|---|---|---|---|
| 2026 | 137.8% | 138.5% | +0.7 pp | Current debt path already above original benchmark. |
| 2027 | 137.5% | 139.2% | +1.7 pp | Debt peak shifted materially upward. |
| 2028 | 136.4% | Not yet available in current Commission vintage | — | Original figure remains a policy reference. |
| 2029 | 134.9% | Not yet available | — | Requires updated medium-term trajectory. |
| 2030 | 133.9% | Not yet available | — | Cannot be treated as current forecast. |
Mechanical debt re-basing
Nominal GDP sensitivity
| Nominal GDP deviation | Debt-stock assumption | Mechanical debt / GDP ratio | Change from baseline |
|---|---|---|---|
| +2% | Debt unchanged | ≈136.5% | ≈−2.7 pp |
| +1% | Debt unchanged | ≈137.8% | ≈−1.4 pp |
| Baseline | Debt unchanged | 139.2% | — |
| −1% | Debt unchanged | ≈140.6% | ≈+1.4 pp |
| −2% | Debt unchanged | ≈142.0% | ≈+2.8 pp |
RRF and post-2026 investment transition
Defence-related fiscal pressure
Demographic pressure toward 2030
| Indicator | 2025 | 2030 | Fiscal mechanism |
|---|---|---|---|
| Resident population | 58.9m | 58.7m | Smaller long-run tax and labour-force base. |
| Natural balance | ≈−296k | ≈−353k | Deaths exceed births by a widening margin. |
| Net foreign migration | ≈+296k | ≈+247k | Partially offsets demographic decline. |
| Population aged 85+ | 4.1% | 4.4% | Raises healthcare and long-term-care pressure. |
Pension-system pressure
Scenario set
| Scenario | Core assumption | 2030 debt implication | Status |
|---|---|---|---|
| Original policy benchmark | Earlier MEF primary-balance and debt path | 133.9% | Official older policy benchmark |
| Mechanically re-based adjustment | Start from 139.2% in 2027, preserve original annual debt reductions | ≈135.6% | Deterministic sensitivity, not forecast |
| Primary-balance underperformance | Primary balance 1 pp GDP weaker each year | ≈+3 pp after three years before feedbacks | Accounting sensitivity |
| Nominal-GDP underperformance | GDP denominator 2% below baseline | ≈142.0% from 139.2 starting ratio | Mechanical denominator sensitivity |
2030 monitoring matrix
| Indicator | Stabilising signal | Adverse signal | Why it matters |
|---|---|---|---|
| Headline deficit | Durably below 3% | Returns above threshold outside permitted flexibility | EDP durability |
| Primary balance | Moves toward sustained surplus | Stagnates near zero or returns negative | Capacity to absorb interest burden |
| Debt / GDP | Peaks then declines | Keeps rising beyond 2027 | Core sustainability test |
| Interest expenditure | Stabilises relative to GDP | Continues rising materially | Can absorb primary adjustment |
| Nominal GDP | Growth supports denominator | Weak real growth plus low inflation | Direct debt-ratio effect |
| Stock-flow adjustments | Fade after tax-credit cash effects | Remain persistently debt-increasing | Can neutralise headline deficit improvement |
| Public investment | Remains productive after RRF | Falls sharply after 2026 | Potential-growth effect |
| Defence expenditure | Integrated into fiscal plan | Added without financing path | Medium-term expenditure pressure |
| Working-age participation | Rises | Labour supply contracts faster than productivity rises | Tax and contribution base |
| Pension spending | Tracks official reform profile | Permanent measures worsen pre-2036 path | Structural primary balance |


